
 Global Clinical Workflow Solutions Market | 2026-2036
Global Clinical Workflow Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Workflow Solutions Market Foresight
India's health-tech corridor is reconfiguring how clinical workflow platforms serve emerging-market hospitals with constrained IT infrastructure. Epic Systems Corporation leverages deep integration with academic medical centers to sustain long-term client retention across North America. Koninklijke Philips N.V. anchors its position through hardware-software convergence in critical care environments. Oracle competes aggressively via cloud-native architectures that reduce on-premises maintenance burdens for large hospital networks.
Clinical workflow solutions encompass software systems that orchestrate patient information, staff assignments, and care protocols across healthcare delivery settings, typically operating through HL7 FHIR interfaces and real-time notification engines to minimize administrative latency. Their primary commercial purpose centers on reducing clinical errors, optimizing resource utilization, and ensuring compliance with care quality mandates. Cloud-based deployment now captures the fastest expansion trajectory as hospitals prioritize remote accessibility and scalable infrastructure over capital-intensive on-premises installations. Patient scheduling software occupies the most mature margin pool, though task automation represents the segment where vendors increasingly differentiate through AI-assisted prioritization algorithms.
The FDA's interoperability rules, the EU's Medical Device Regulation through notified bodies, and India's CDSCO digital health guidelines collectively shape product certification timelines and data governance architectures for workflow vendors. Health systems in Germany face additional layering from BfArM's DiGA fast-track requirements, which embed workflow tools within reimbursable digital care pathways. Stakeholders must monitor how jurisdictional fragmentation in data localization rules affects multi-country deployment architectures and vendor partnership strategies.
Market Dynamics
Health system consolidation across the United States is forcing vendors to architect enterprise-grade platforms capable of unifying disparate EHR environments under single operational umbrellas.
Growth Catalysts
- Interoperability mandates:The FDA's 21st Century Cures Act enforcement compels vendors to deploy HL7 FHIR interfaces, accelerating replacement of legacy siloed systems in hospital networks.
- Cloud infrastructure maturation:Health systems in Germany are migrating scheduling and documentation workloads to scalable architectures that reduce on-premises maintenance overhead.
- India's CDSCO digital health guidelines:These frameworks legitimize workflow software as reimbursable infrastructure, opening procurement channels for mid-tier hospitals previously excluded from enterprise licensing.
Market Restraints
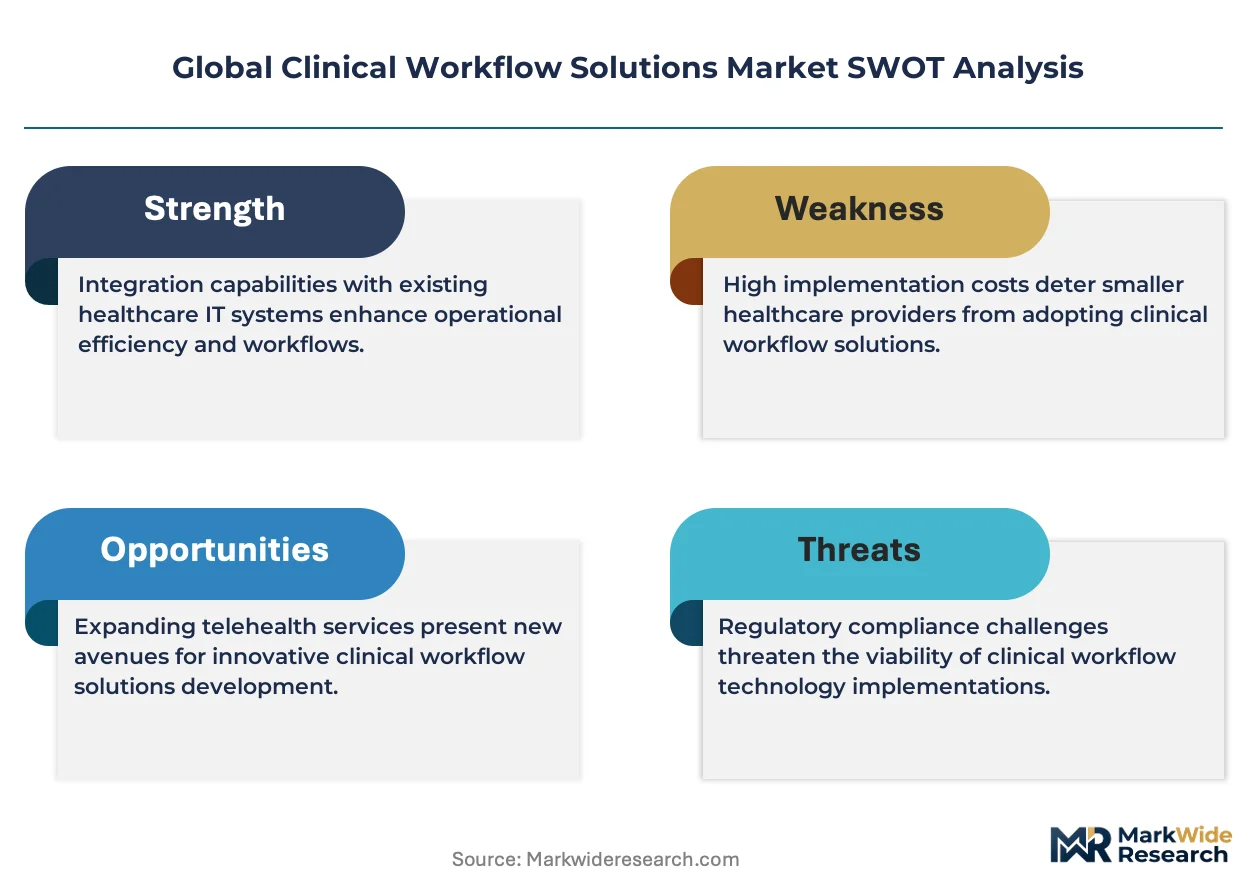
- Data localization fragmentation:Divergent sovereignty requirements across Brazil, China, and EU member states force vendors to maintain region-specific server farms, elevating compliance architecture costs.
- Legacy system entrenchment:Academic medical centers with decades-old custom EHR builds face prohibitive switching costs that delay platform modernization cycles.
- Specialized talent scarcity:Health informatics architects with dual clinical-technical training command premium compensation, constraining vendor scaling velocity.
Strategic Opportunities
- Rural hospital networks:Federally qualified health centers in the United States present underserved demand for lightweight, subscription-based workflow modules.
- AI-assisted prioritization:Machine learning integration with task automation engines creates differentiation in critical care environments where nursing allocation precision affects outcomes.
- DiGA fast-track embedding:Germany's BfArM pathway enables workflow tools to secure reimbursement status when bundled with approved digital therapeutic applications.
Industry Challenges
- Multi-EHR integration complexity:Health systems operating hybrid Cerner-Epic environments require bespoke middleware development, extending implementation timelines.
- ISO 13485 certification timelines:Workflow platforms with clinical decision support modules face 18-24 month quality management audits, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Workflow Solutions Market |
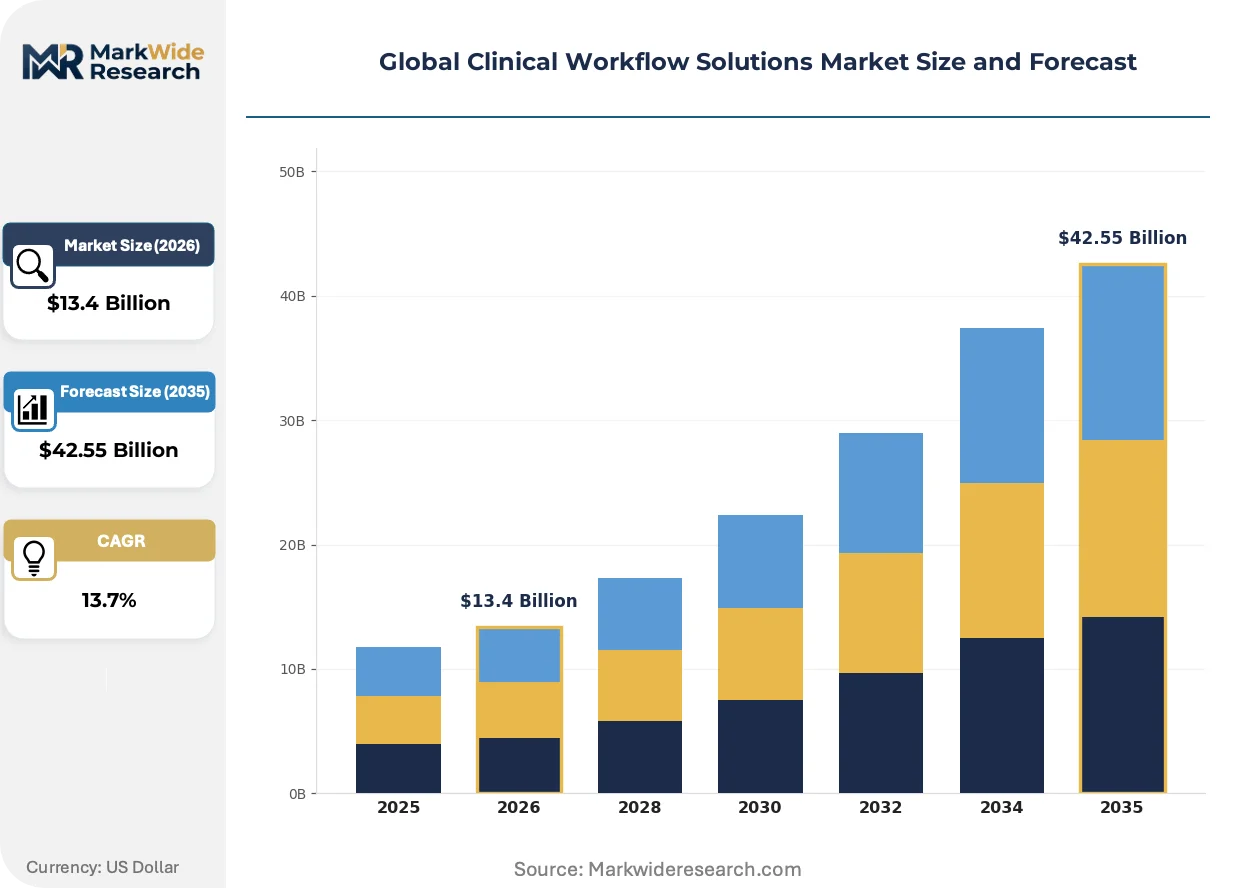
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $42.55 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Patient Scheduling Software, Clinical Documentation, Order Management, Results Reporting, Task Automation, Communication Platforms Deployment Mode: Cloud-Based, On-Premises, Hybrid, Virtualized, Hosted Application: Pre-Admission Processing, Inpatient Care Coordination, Outpatient Management, Discharge Planning, Case Management, Quality Assurance End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Primary Care Facilities, Rehabilitation Centers, Long-Term Care Institutions |
| Companies Covered | Oracle, McKesson Corporation, Koninklijke Philips N.V., Epic Systems Corporation, NXGN Management, LLC, Ascom, Stryker, GE Healthcare, Veradigm Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Workflow Solutions Market Shifts & Advancements
Vendor differentiation is compressing around three vectors: ambient clinical intelligence, regulatory interoperability enforcement, and procurement model restructuring away from perpetual licenses.
Generative AI documentation assistants are collapsing the administrative burden of clinical note completion. Emergency departments in the United States are deploying ambient listening tools that auto-populate structured EHR fields during patient encounters. This compression of documentation latency is reallocating nursing hours from keyboard time to bedside care.
REACH data-sharing amendments and the EU AI Act's high-risk system classification are reshaping how workflow vendors architect cross-border patient data flows. Platforms must now embed explainability logging for algorithmic prioritization decisions. German hospital procurement committees are prioritizing vendors with pre-certified conformity assessment documentation.
Subscription-based SaaS contracts are displacing perpetual license agreements as the dominant commercial structure. Large hospital networks in the United States now demand consumption-based pricing tied to active user seats rather than institutional site licenses. This shift transfers capital expenditure risk to vendors while accelerating platform refresh cycles.
Global Clinical Workflow Solutions Market Segmentation
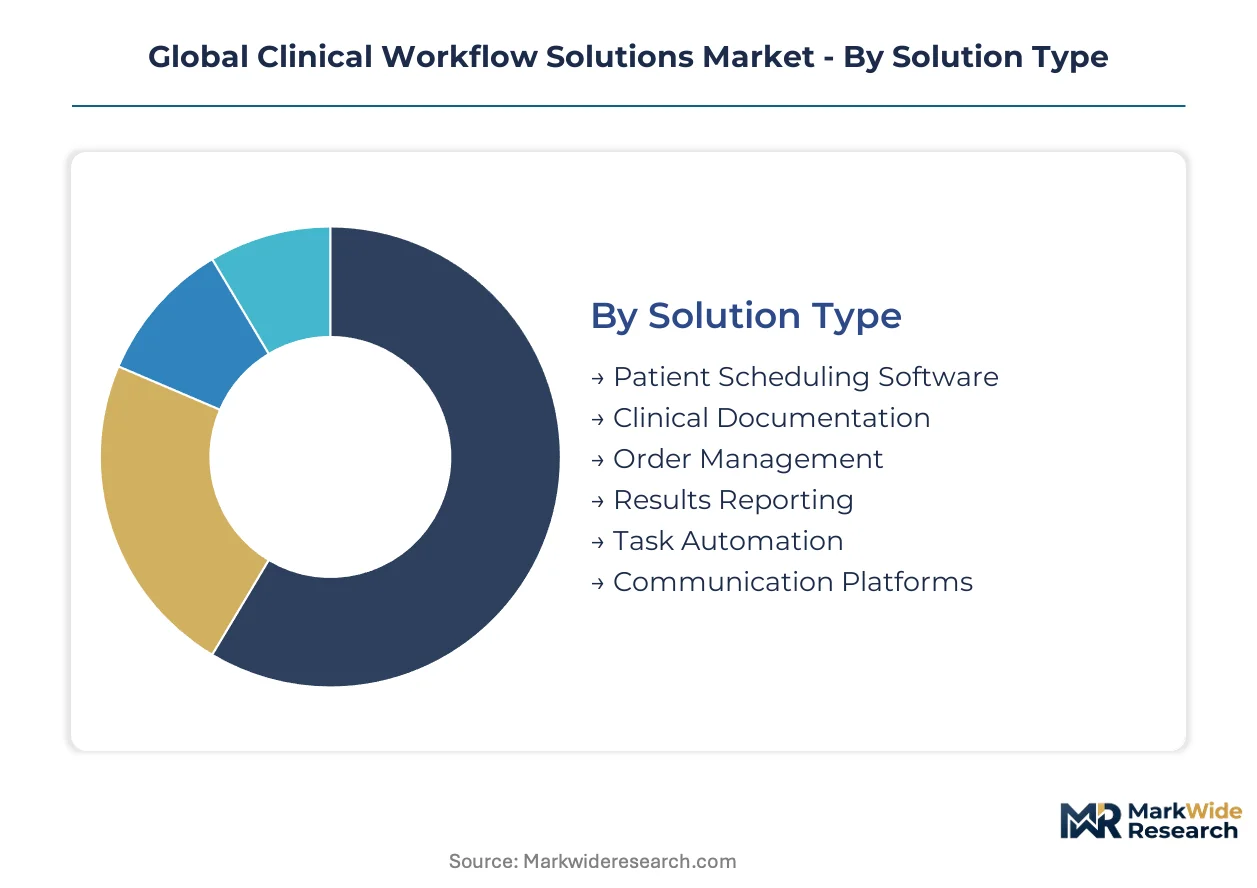
Workflow vendors architect product portfolios around distinct operational pain points across care delivery settings. Segment boundaries determine pricing architecture, implementation complexity, and regulatory certification pathways for platform providers.
Solution Type:
Application sophistication separates mature margin pools from emerging differentiation vectors in clinical workflow software.
- Patient Scheduling Software:Calendar optimization engines with HL7 FHIR integration manage appointment sequencing across multi-specialty departments. United States hospital networks concentrate procurement here as consolidation creates enterprise-scale scheduling complexity.
- Clinical Documentation:Structured data capture modules with voice recognition and template libraries reduce physician keyboard time. Ambient intelligence integration is accelerating replacement cycles in academic medical centers with legacy transcription contracts.
- Order Management:CPOE interfaces with pharmacy and laboratory system connectivity.
- Results Reporting:Critical value alerting and abnormal flag distribution to care teams.
- Task Automation:AI-assisted nursing prioritization engines with acuity-based workload balancing.
- Communication Platforms:Secure messaging with role-based escalation and on-call directory integration.
Patient Scheduling Software holds installed capacity. Task Automation is rotating up the share rankings.
Deployment Mode:
Infrastructure economics and data sovereignty requirements partition customer preferences across hosting architectures.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling compute and storage eliminate capital expenditure for hardware refresh cycles. German hospital networks are migrating here fastest as BfArM DiGA pathways legitimize reimbursable cloud infrastructure.
- On-Premises:Dedicated server installations with full physical control over patient data residency. China's NMPA data localization mandates preserve demand despite higher total cost of ownership.
- Hybrid:Sensitive workloads on local servers with analytics and backup to public cloud.
- Virtualized:Containerized application delivery with centralized IT management.
- Hosted:Single-tenant private cloud with vendor-managed infrastructure operations.
On-Premises retains legacy footprint. Cloud-Based is expanding most quickly among new procurement decisions.
Application:
Care episode phases define functional requirements and user workflow integration depth for platform modules.
- Pre-Admission Processing:Insurance verification, prior authorization, and surgical readiness assessment workflows. United States revenue cycle pressures concentrate vendor investment here as denial rates drive automation priority.
- Inpatient Care Coordination:Multi-disciplinary rounding tools with handoff documentation and nursing assignment optimization. Critical care environments in India demand these modules as CDSCO guidelines expand reimbursable digital infrastructure.
- Outpatient Management:Chronic disease monitoring and referral coordination across community settings.
- Discharge Planning:Post-acute placement and medication reconciliation workflows.
- Case Management:Complex patient stratification and care pathway adherence tracking.
- Quality Assurance:Incident reporting, peer review, and compliance documentation systems.
Inpatient Care Coordination anchors enterprise deployments. Pre-Admission Processing is climbing the fastest on reimbursement pressure.
End User:
Facility scale and care intensity determine platform complexity requirements and procurement authority structures.
- Hospitals:Enterprise-grade platforms with multi-department integration and 24/7 uptime requirements. United States health system consolidation is concentrating purchasing power here as IDNs demand unified scheduling across dozens of facilities.
- Ambulatory Surgical Centers:Lightweight perioperative workflow modules with rapid implementation timelines. Outpatient migration in Germany is expanding addressable market as BfArM fast-tracks same-day procedure digital pathways.
- Diagnostic Laboratories:Specimen tracking and result distribution with EMR connectivity.
- Primary Care Facilities:Chronic care management and preventive screening reminder systems.
- Rehabilitation Centers:Therapy scheduling and functional outcome documentation tools.
- Long-Term Care Institutions:Medication administration records and resident care planning modules.
Hospitals command platform development resources. Ambulatory Surgical Centers is gaining share fastest on site-of-care shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States health information exchange infrastructure, anchored by the Sequoia Project's interoperability framework, underwrites North American dominance in clinical workflow platform deployment. Germany's trans-European fiber corridors enable real-time hospital data synchronization across its federal hospital network.
United States
Health system consolidation and 21st Century Cures Act enforcement drive enterprise scheduling platform procurement. The FDA mandates HL7 FHIR interfaces for all certified health IT modules. The Texas Medical Center in Houston operates the world's largest concentration of integrated EHR environments, hosting live workflow analytics across 60+ institutions.
Germany
BfArM's DiGA fast-track pathway embeds workflow tools within reimbursable digital care pathways, accelerating hospital procurement. The EU AI Act's high-risk system classification requires explainability logging for algorithmic clinical decisions. The Rhine-Ruhr metropolitan cluster hosts Europe's densest concentration of university hospital networks migrating to cloud-native scheduling architectures.
India
CDSCO digital health guidelines legitimize workflow software as reimbursable infrastructure for mid-tier hospitals. The country's national pharmaceutical regulator mandates data localization for patient records processed by foreign-hosted platforms. Bangalore's health-tech corridor concentrates vendor development centers serving emerging-market hospitals with constrained IT infrastructure.
China
NMPA data localization mandates preserve demand for on-premises installations despite higher total cost of ownership. The Ministry of Industry and Information Technology certifies hospital information systems under GB standards for interoperability. The Yangtze River Delta region, centered on Shanghai, hosts the largest hospital network consolidation outside the United States, driving demand for unified scheduling platforms.
United Kingdom
NHS England's federated data platform procurement concentrates purchasing power for enterprise workflow deployments. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking for clinical software with decision support modules. London's academic medical center cluster leads European adoption of ambient clinical intelligence for emergency department documentation.
Global Clinical Workflow Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the clinical workflow solutions market, supplying modular scheduling engines and documentation interfaces to larger enterprise suites. The vendor base organizes around three strategic archetypes: EHR-native platforms with deep academic medical center integration, hardware-software convergence specialists in critical care environments, and cloud-native architects reducing on-premises maintenance burdens. Dominant competitive moves include strategic partnerships with health system consolidators and portfolio diversification into AI-assisted task automation modules.
Within the platform integrator tier, Oracle Corporation and Epic Systems Corporation exemplify divergent infrastructure philosophies. Oracle's cloud-native architectures transfer capital expenditure risk to vendor balance sheets through consumption-based SaaS contracts. Epic Systems Corporation anchors the EHR-native archetype through deep integration with academic medical centers. Koninklijke Philips N.V. occupies a position in the hardware-software convergence segment, embedding workflow modules within critical care monitoring ecosystems. These three entities represent the primary competitive vectors reshaping procurement committee evaluations across United States hospital networks.
| Leading Market Players |
|---|
| Oracle |
| McKesson Corporation |
| Koninklijke Philips N.V. |
| Epic Systems Corporation |
| NXGN Management, LLC |
| Ascom |
| Stryker |
| GE Healthcare |
| Veradigm Inc. |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container cost dynamics compress margins for hardware-dependent workflow vendors while amplifying price differentiation between cloud-native and on-premises deployment tiers. Supply concentration in semiconductor fabrication and server component manufacturing concentrates pricing power upstream, forcing downstream vendors to absorb logistics volatility or pass through tiered service fees.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement negotiations, with health system consolidators extracting steeper concessions at scale than standalone hospitals. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-cleared decision support modules commanding substantial premiums over documentation-only tiers. Pricing pressure stems from SaaS consumption models transferring capital expenditure risk to vendor balance sheets. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize integration depth over unit cost.
Supply Chain Analysis
Upstream feedstock dependencies center on Taiwan and South Korea for advanced server processors, with China dominating rare earth elements for magnetic storage components. Software vendors draw from Indian development centers for health informatics engineering talent and Irish data center infrastructure for EU patient data residency compliance. Single-source vulnerability in GPU acceleration chips for AI-assisted prioritization modules threatens delivery timelines. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical workflow solutions function as a service-attach opportunity where recurring revenue from interoperability maintenance and AI module subscriptions expands faster than perpetual license recognition. Implementation services and ongoing FHIR interface certification support represent the fastest-growing revenue layer.
For Market Incumbents: Entrench platform stickiness through deep EHR integration investments that elevate switching costs for health system consolidators. Prioritize ISO 13485 certification for clinical decision support modules to defend against cloud-native challengers. Expand captive professional services capacity to capture implementation revenue streams. For New Entrants and Emerging Players: Establish a beachhead in rural hospital networks underserved by enterprise vendors, where lightweight SaaS modules address constrained IT infrastructure. Target ambulatory surgical centers in Germany's DiGA fast-track pathway as the most penetrable segment. Lead with AI-assisted nursing prioritization to differentiate against legacy scheduling incumbents. For Investors and Strategic Acquirers: FDA's 21st Century Cures Act enforcement reshapes the acquisition landscape by privileging vendors with pre-certified interoperability architectures. Long-term viability hinges on recurring revenue density rather than license velocity. Target mid-cap specialists with vertical integration into health informatics talent pipelines. Watch for inflection when hospital procurement committees mandate explainability logging for algorithmic decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR connectivity with Epic and Oracle environments secures hospital network procurement. |
| AI Module Development | FDA-cleared clinical decision support expands reimbursable service attach rates. |
| Hospital System Partnership | IDN consolidation in Texas and California creates multi-facility deployment leverage. |
| Geographic Expansion | BfArM DiGA fast-track embedding opens reimbursable procurement channels in Germany. |
| Regulatory Certification Investment | ISO 13485 quality management audits accelerate revenue recognition for decision support modules. |
Research Methodology
A spread of perspectives from hospital CIOs, health informatics architects, GPO contracts managers, and FDA regulatory consultants converged on the working assumptions driving this analysis. Primary interviews with clinical workflow vendors and health system procurement committees combined with secondary validation against CMS Medicare reimbursement databases, hospital procurement records, and SEC filings from publicly traded platform providers. Bottom-up deployment estimates across cloud and on-premises segments triangulated with top-down health IT spending projections.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling adoption curves against certified vendor capacity and health informatics talent availability. Segmentation dimensions included deployment mode, solution type, end-user facility scale, and regional regulatory cluster complexity. CAGRs derived from logistic diffusion curves fitted to historical EHR replacement cycles and interoperability mandate enforcement timelines. Forecast inputs incorporated BfArM DiGA approval velocity and CDSCO digital health guideline implementation pace.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and cloud infrastructure pricing would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and health system consolidation velocity. Cross-checking against CMS health IT incentive payment disbursement trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Global Health Kiosk Market