
 Glass Cleaner Market | 2026-2036
Glass Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Cleaner Market Analysis
REACH compliance is shifting the cost-of-entry calculus for glass cleaner manufacturers seeking European market access. S.C. Johnson & Son leverages its Greenlist ingredient screening protocol to preempt regulatory thresholds across multiple jurisdictions. PPG Industries anchors its position through captive supply of specialty solvents from its chemicals division. 3M competes by extending its Scotchgard brand equity into streak-resistant coating technologies that reduce re-cleaning frequency.
Glass cleaner comprises aqueous or solvent-based formulations designed to remove soils, fingerprints, and films from silica-based surfaces without residue, typically containing surfactants, chelating agents, and volatile carriers that evaporate below 100 degrees Celsius to leave optical clarity. The liquid product type dominates volume due to compatibility with trigger sprayers and bulk refill systems in commercial contracts. The non-toxic formulation segment leads value growth as institutional buyers in healthcare and education specify products exempt from California Proposition 65 warnings. The automotive application commands premium positioning through concentrated formulas that dissolve road film and silicone sealant overspray without damaging adjacent trim materials.
The EPA Safer Choice program and the EU REACH framework govern permissible surfactant chemistries, while California Air Resources Board rules limit volatile organic compound content in consumer products. These standards compel manufacturers to reformulate with bio-derived solvents and lower-VOC carriers, raising R&D costs for new entrants but creating margin pools for established players with compliance infrastructure. Stakeholders must monitor pending amendments to state-level VOC regulations and the expansion of refill-station retail formats that threaten conventional packaging economics.
Market Dynamics
Reformulation pressure from the EPA Safer Choice program and REACH compliance is compressing margins for commodity producers while rewarding manufacturers with captive bio-surfactant supply chains and in-house toxicology screening infrastructure.
Growth Catalysts
- Automotive detailing expansion:Fleet maintenance operators in Germany are specifying concentrated dilutable formulations to reduce packaging waste and transport costs across multi-site contracts.
- REACH framework acceleration:The EU's phased restrictions on nonylphenol ethoxylates are pulling demand toward biodegradable surfactant chemistries that biodegrade within 28 days.
- Healthcare institutional procurement:Hospital systems in California are mandating Proposition 65-exempt glass cleaners for patient room sanitation protocols.
Market Restraints
- Isopropanol cost volatility:Solvent price swings tied to propylene feedstock fluctuations constrain margin predictability for aqueous-alcohol formulations.
- Specialty surfactant supply concentration:German and Dutch chemical producers control 70% of alkyl polyglucoside supply for North American formulators.
- VOC ceiling compression:California Air Resources Board limits on volatile organic compound content force reformulation cycles every 24-36 months.
Strategic Opportunities
- Refill-station retail formats:Bulk dispensing systems in French and German grocery chains threaten conventional 32-ounce trigger-spray packaging economics.
- Streak-resistant coating convergence:Integration of hydrophobic polymers with cleaning chemistries reduces re-cleaning frequency for automotive and solar panel applications.
- Indian commercial cleaning sector:Underpenetrated demand from facility management companies in Mumbai and Bangalore offers first-mover positioning for concentrated professional grades.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with REACH dossier preparation and biodegradability testing expertise command 40% salary premiums.
- Multi-jurisdiction compliance timelines:Simultaneous EPA Safer Choice, EU Ecolabel, and Blue Angel certification processes extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Cleaner Market |
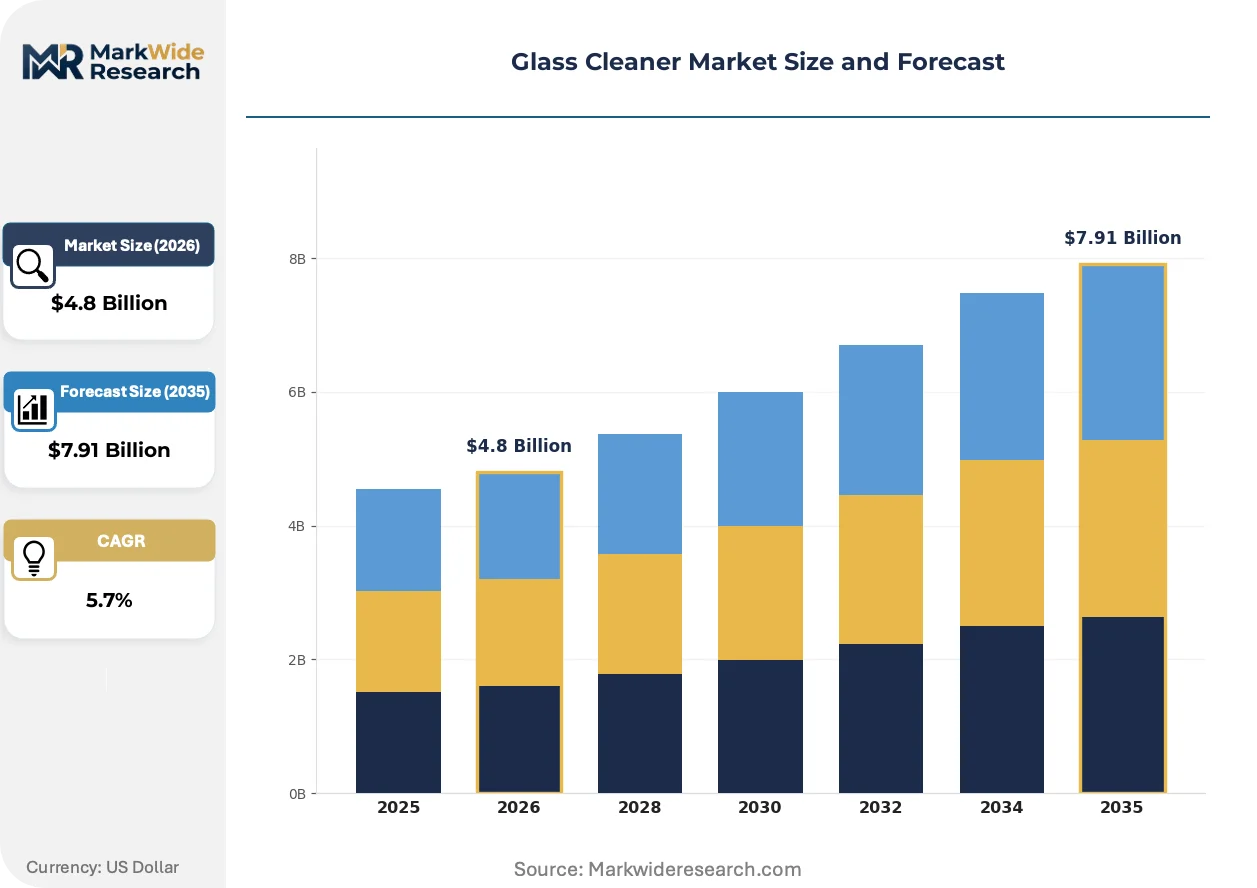
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Foam, Wipes, Spray Application: Household, Automotive, Commercial, Industrial Formulation: Alcohol-Based, Vinegar-Based, Ammonia-Based, Non-Toxic Distribution Channel: Retail Stores, Online, Wholesale, Distributors |
| Companies Covered | S.C. Johnson & Son, PPG Industries, 3M, CRC Industries, ITW Global Brands, The Clorox Company, Zep Inc., Armor All Company, Reckitt Benckiser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Cleaner Market Emerging Trajectories
Active ingredient sourcing and delivery mechanisms are undergoing simultaneous transformation as bio-derived surfactants scale and concentrated refill formats displace single-use packaging.
Alkyl polyglucoside surfactants synthesized from coconut oil and corn starch are overtaking petroleum-derived alternatives in premium formulations. Automotive OEMs and solar panel installers are adopting these chemistries for residue-sensitive optical surfaces. The shift is compressing demand for synthetic ethoxylates and rewarding suppliers with backward integration into tropical oleochemical supply chains.
The EU F-Gas Regulation and its phasedown of hydrofluorocarbon propellants are forcing aerosol glass cleaner manufacturers toward compressed air and pump-spray alternatives. Aerosol-dependent product lines face reformulation investments exceeding $2 million per SKU for valve and actuator redesign. German retailers are delisting non-compliant SKUs ahead of 2027 enforcement deadlines, accelerating category consolidation.
Facility management companies are consolidating supplier relationships around full-line cleaning chemical contracts that bundle glass cleaner with floor care and disinfectant procurement. Distributor sales representatives in the United Kingdom are losing commission autonomy as national purchasing agreements centralize specification authority. This concentration is most visible in London and Manchester, where ISS and Sodexo have reduced active chemical suppliers from twelve to four since 2022.
Glass Cleaner Market Segmentation
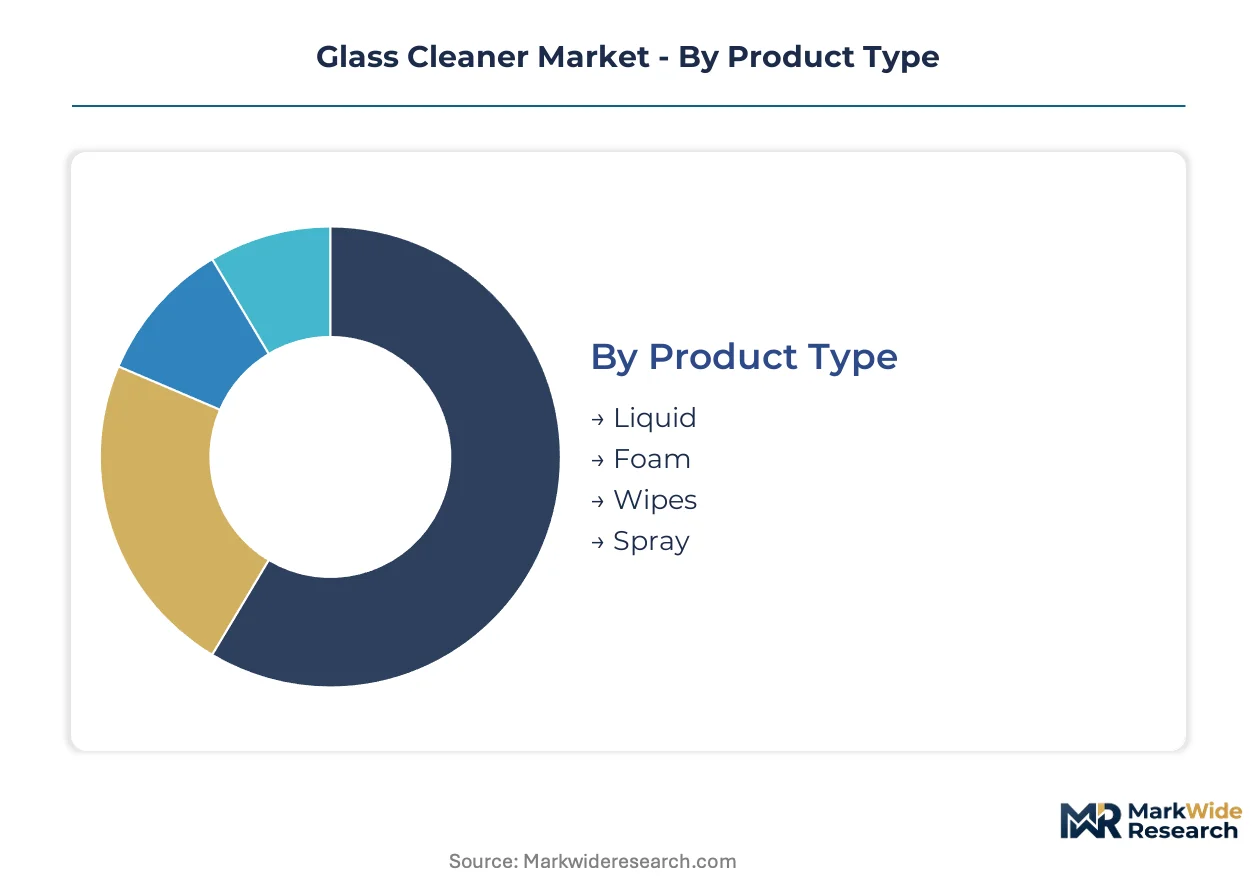
Glass cleaner procurement patterns diverge sharply between institutional buyers seeking concentrated bulk formats and consumers prioritizing convenience packaging. Understanding these segment boundaries reveals where formulation investments concentrate and which distribution channels capture margin.
Product Type:
Buyers in this category separate by cleaning frequency and surface area requirements, with commercial contractors favoring refill-compatible formats while residential users prioritize single-use convenience.
- Liquid:Aqueous or solvent-based solutions formulated for trigger sprayers and bulk dispensing systems dominate commercial contracts. Fleet maintenance operators in Germany specify concentrated dilutable liquids to reduce packaging waste across multi-site service agreements.
- Spray:Pressurized or pump-actuated delivery systems integrate compressed air alternatives as EU F-Gas Regulation phases down hydrofluorocarbon propellants. Aerosol-dependent SKUs face reformulation investments exceeding two million dollars per product line for valve redesign.
- Foam:Viscous formulations that cling to vertical surfaces for extended contact time on shower enclosures and architectural glass.
- Wipes:Pre-saturated substrates targeting quick-clean scenarios in automotive interiors and healthcare patient rooms.
Volume sits with Liquid; growth tilts toward Spray as regulatory pressure accelerates propellant transition.
Application:
End-use differentiation in this category tracks surface sensitivity and soil composition, with optical-grade requirements commanding premium positioning against general-purpose maintenance.
- Automotive:Concentrated formulas dissolve road film and silicone sealant overspray without damaging adjacent trim materials. Automotive OEMs and solar panel installers specify residue-sensitive chemistries for optical clarity on coated surfaces.
- Commercial:Facility management companies consolidate procurement around full-line contracts bundling glass cleaner with floor care and disinfectant. ISS and Sodexo have reduced active chemical suppliers from twelve to four since 2022 in London and Manchester.
- Household:Consumer-grade formulations distributed through retail trigger-spray formats face margin compression from refill-station retail expansion in French and German grocery chains.
- Industrial:Heavy-duty degreasing chemistries for manufacturing environments and warehouse glazing maintenance.
Commercial commands volume share; Automotive climbs fastest on coating convergence and detailing studio expansion.
Formulation:
Chemical composition in this category determines regulatory compliance burden and end-user safety classification, with institutional buyers mandating exemption from hazard warnings.
- Non-Toxic:Proposition 65-exempt formulations specified by California hospital systems for patient room sanitation protocols. EPA Safer Choice certification and EU Ecolabel alignment extend product launch cycles by 14-18 months but capture institutional premium.
- Alcohol-Based:Isopropanol or ethanol carriers that evaporate below 100 degrees Celsius for streak-free drying. Feedstock volatility tied to propylene fluctuations constrains margin predictability for aqueous-alcohol blends.
- Vinegar-Based:Acetic acid solutions targeting eco-conscious residential segments and natural-food retail channels.
- Ammonia-Based:Traditional formulations with superior grease-cutting performance declining in healthcare and education procurement.
Alcohol-Based retains volume leadership; Non-Toxic expands most quickly on healthcare institutional procurement mandates.
Distribution Channel:
Channel selection in this category reflects buyer scale and specification authority, with national purchasing agreements displacing distributor autonomy.
- Wholesale:Bulk concentrate supply to commercial cleaning contractors and fleet maintenance operators. German retailers specify dilutable products to reduce transport costs.
- Distributors:Full-line chemical portfolios sold through sales representatives losing commission autonomy as centralized procurement consolidates supplier relationships.
- Retail Stores:32-ounce trigger-spray formats threatened by refill-station economics in European grocery chains.
- Online:Direct-to-consumer and subscription refill models gaining traction in residential segments.
Wholesale anchors current volume; Online gains fastest on subscription refill adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Baden-Württemberg concentrate glass cleaner formulation capacity through tax incentives for green chemistry R&D facilities. German commercial cleaning contractors drive concentrated product specifications across European procurement networks.
Germany
Fleet maintenance operators in Munich and Stuttgart specify concentrated dilutable formulations to reduce packaging waste across multi-site service agreements. The EU REACH framework enforces phased restrictions on nonylphenol ethoxylates, accelerating demand for biodegradable surfactants. Chemical producers in North Rhine-Westphalia control the majority of alkyl polyglucoside supply for North American formulators.
United States
California hospital systems mandate Proposition 65-exempt glass cleaners for patient room sanitation protocols, pulling institutional procurement toward non-toxic formulations. The EPA Safer Choice program governs permissible surfactant chemistries for federal procurement eligibility. Automotive detailing studios in Los Angeles and Phoenix expand procurement of professional-grade concentrated formulas for coating-sensitive surfaces.
France
Facility management companies in Paris consolidate supplier relationships around full-line cleaning chemical contracts bundling glass cleaner with disinfectant procurement. The EU F-Gas Regulation phases down hydrofluorocarbon propellants, forcing aerosol manufacturers toward compressed air alternatives. Retail chains in Lyon and Marseille pioneer bulk dispensing systems that threaten conventional trigger-spray packaging economics.
United Kingdom
ISS and Sodexo have reduced active chemical suppliers from twelve to four since 2022 in London and Manchester, centralizing specification authority through national purchasing agreements. The UK Environment Agency enforces biodegradability standards aligned with EU Ecolabel criteria post-Brexit. Distributor sales representatives in Birmingham lose commission autonomy as procurement concentrates.
India
Facility management companies in Mumbai and Bangalore generate underpenetrated demand for concentrated professional-grade formulations from first-mover suppliers. The Bureau of Indian Standards mandates labeling disclosure for volatile organic compound content in consumer products. Commercial cleaning contractors in Delhi-NCR specify dilutable concentrates to reduce transport costs across dispersed service territories.
Glass Cleaner Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base separates into three strategic archetypes: diversified chemical conglomerates with captive solvent supply, consumer goods multinationals with retail distribution scale, and regional formulators serving institutional procurement contracts. Competitive positioning hinges on regulatory compliance infrastructure and backward integration into bio-surfactant feedstocks. M&A activity targets specialty surfactant producers in Germany and the Netherlands, while capacity expansion concentrates in Bavaria and Baden-Württemberg.
Among diversified chemical conglomerates, PPG Industries anchors the premium industrial tier through captive supply of specialty solvents from its chemicals division. S.C. Johnson & Son exemplifies the consumer goods multinational archetype with retail-scale distribution and green chemistry screening protocols. 3M occupies a position at the technology convergence intersection, extending brand equity into streak-resistant coating technologies.
| Leading Market Players |
|---|
| S.C. Johnson & Son |
| PPG Industries |
| 3M |
| CRC Industries |
| ITW Global Brands |
| The Clorox Company |
| Zep Inc. |
| Armor All Company |
| Reckitt Benckiser Group |
| Others |
Supply Flow & Price Mechanics
Propylene feedstock price volatility cascades through glass cleaner supply chains into three distinct pricing tiers, with premium formulations commanding stability through long-term surfactant offtake agreements while commodity producers absorb spot-market cost swings.
Pricing Analysis
Short lead-time premiums separate emergency procurement contracts from scheduled bulk orders in institutional channels. Three-tier pricing structure across professional concentrate, standard ready-to-use, and economy private-label tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from isopropanol cost swings tied to propylene feedstock fluctuations, compressing margins for aqueous-alcohol formulations. Fleet maintenance operators in Germany demonstrate lowest price sensitivity due to total-cost-of-ownership optimization, while household retail buyers face margin compression from refill-station economics.
Supply Chain Analysis
EPA Safer Choice and EU Ecolabel certification requirements gate supplier qualification for institutional procurement channels. Supply concentrates in Germany, the Netherlands, and North Rhine-Westphalia for alkyl polyglucoside surfactants. Raw material dependencies center on coconut oil and corn starch feedstocks for bio-derived alternatives, plus isopropanol and specialty solvents for conventional formulations. Single-source vulnerability runs through German and Dutch chemical producers controlling seventy percent of North American alkyl polyglucoside supply. Distribution runs through consolidated national purchasing agreements that displace independent distributor autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressed air propellant technology is displacing hydrofluorocarbon aerosol systems, creating a multi-year transition window where regulatory compliance infrastructure separates viable competitors from stranded product lines.
For Market Incumbents: Anchor market position through captive supply of bio-surfactant feedstocks and in-house REACH dossier preparation capabilities. Consolidate supplier relationships ahead of EU F-Gas Regulation enforcement deadlines. Defend against refill-station retail formats by locking multi-year commercial contracts with fleet maintenance operators.
For New Entrants and Emerging Players: Begin with concentrated professional-grade formulations for underpenetrated facility management companies in Mumbai and Bangalore. Target automotive detailing studios seeking residue-sensitive chemistries for coated surfaces. Pursue direct-to-subscription models bypassing consolidated retail channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty surfactant producers in Germany and the Netherlands facing reformulation investment burdens. Long-term viability over a five-to-ten year window rests on backward integration into tropical oleochemical supply chains. Monitor EU F-Gas Regulation compliance timelines as inflection indicator for aerosol-dependent product line viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Surfactant Feedstocks | Captive supply of alkyl polyglucoside from coconut oil and corn starch secures margin against propylene volatility. |
| REACH Dossier Preparation Infrastructure | In-house toxicology screening compresses product launch cycles by fourteen to eighteen months versus outsourced compliance. |
| Compressed Air Propellant Transition | Valve and actuator redesign ahead of EU F-Gas Regulation deadlines avoids German retailer delisting. |
| Refill-Station Retail Partnership | Bulk dispensing systems in French and German grocery chains capture margin from displaced trigger-spray economics. |
| Full-Line Chemical Contract Consolidation | Bundling glass cleaner with floor care and disinfectant procurement locks national purchasing agreements with ISS and Sodexo. |
Methodological Framework
Trade databases, customs records, and SEC filings formed the secondary backbone for supply chain mapping and competitor financial analysis. Primary interviews with formulation chemists, procurement leads at commercial cleaning contractors, fleet maintenance operators, and retail category buyers validated demand assumptions. Bottom-up and top-down triangulation reconciled segment-level volume estimates against aggregate market sizing.
Bottom-up modeling built segment forecasts from individual application demand drivers, while top-down approaches anchored projections to macroeconomic indicators across the analysis window. Segmentation dimensions included product type, application, formulation chemistry, and distribution channel. CAGRs derived from regression analysis of historical volume trends against regulatory phase-in schedules and feedstock price cycles. Automotive OEM coating specifications and hospital procurement mandates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; institutional and automotive applications carry tighter precision than fragmented household retail. Forecasts reflect assumptions about REACH amendment timelines and state-level VOC regulation expansion. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement deadlines or alkyl polyglucoside supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market