
 Proxy Services and Software Market | 2026-2036
Proxy Services and Software Market Size, Share, and Industry Trends Forecast 2026-2036
Proxy Services and Software Market Insights
The EU AI Act is pivoting enterprise data collection practices toward auditable proxy infrastructure with built-in consent management and origin masking. Bright Data leverages its residential proxy network to serve compliance-heavy financial services clients across Frankfurt and Amsterdam. Oxylabs anchors its competitive position through specialized scraping APIs that sustain data pipeline reliability for e-commerce intelligence platforms. Smartproxy differentiates by competing aggressively on self-service onboarding tools that reduce deployment friction for mid-market agencies.
Proxy services and software encompass intermediary server systems that route client requests through distributed IP addresses, operating via protocols including HTTP, HTTPS, and SOCKS5 with session persistence controls and geographic targeting precision. These systems enable anonymous data extraction, geo-restricted content access, and competitive intelligence gathering while masking origin identities from destination servers. Residential proxies command premium positioning due to their lower block rates on sophisticated target platforms, whereas datacenter proxies occupy volume-driven segments where cost efficiency outweighs stealth requirements. Cloud-based deployment models are capturing fastest-growing demand as API-first architectures eliminate hardware provisioning delays. Enterprise customer types concentrate margin pools through multi-year contracts with dedicated account engineering.
The EU AI Act and GDPR jointly constrain how European enterprises deploy automated data collection, forcing proxy vendors to implement granular consent logging and data retention limits. The Federal Trade Commission in the United States monitors proxy-enabled scraping for unfair competition violations, while China's MIIT requires domestic data routing through registered infrastructure providers. Stakeholders must monitor evolving cross-border data localization rules that could fragment proxy network architectures into jurisdiction-specific operational zones.
Market Dynamics
Zero-trust security architectures are forcing enterprises to rearchitect data flows through compliant intermediary layers, redirecting procurement budgets toward auditable proxy infrastructure with embedded consent management and geographic routing controls.
Growth Catalysts
- EU AI Act data governance mandates:Automated decision-making systems in European enterprises now require traceable data provenance, pushing demand for proxy networks with built-in audit trails and origin masking capabilities.
- Financial services compliance automation:Frankfurt-based banks and Amsterdam trading platforms deploy residential proxy infrastructure to satisfy cross-border data sovereignty requirements while maintaining real-time market intelligence pipelines.
- Cloud-native API architectures:Containerized deployment models eliminate hardware provisioning delays, enabling mid-market agencies to spin up geo-targeted proxy pools through self-service onboarding portals.
Market Restraints
- Residential IP supply concentration:Ethically sourced residential proxy pools depend on limited ISP partnership networks in Germany and the Netherlands, creating procurement bottlenecks during demand spikes.
- Datacenter proxy commoditization:Volume-driven segments face margin compression as cloud hyperscalers bundle basic proxy functionality into existing infrastructure services at near-zero marginal cost.
- GDPR retention limit friction:The regulation's 72-hour breach notification and purpose limitation requirements force vendors to maintain complex data lifecycle management systems that inflate operational overhead.
Strategic Opportunities
- Industrial IoT data sovereignty:German manufacturing clusters in Bavaria and Baden-Württemberg mandate localized data routing for predictive maintenance systems, creating demand for jurisdiction-specific proxy nodes.
- Consent management platform convergence:Integration of proxy infrastructure with GDPR-compliant consent orchestration tools opens white space in enterprise martech stacks undergoing privacy-first redesigns.
- SOCKS5 session persistence innovation:Real-time bidding platforms and price intelligence engines require extended session continuity, rewarding vendors that optimize protocol-level connection stability beyond HTTP/HTTPS alternatives.
Industry Challenges
- Distributed systems engineering scarcity:Vendors struggle to hire engineers with combined expertise in low-latency networking, cryptographic tunneling, and multi-jurisdictional compliance automation.
- Legacy SIEM integration complexity:Enterprise security teams demand seamless ingestion of proxy logs into existing Splunk and IBM QRadar deployments, requiring custom connector development that extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proxy Services and Software Market |
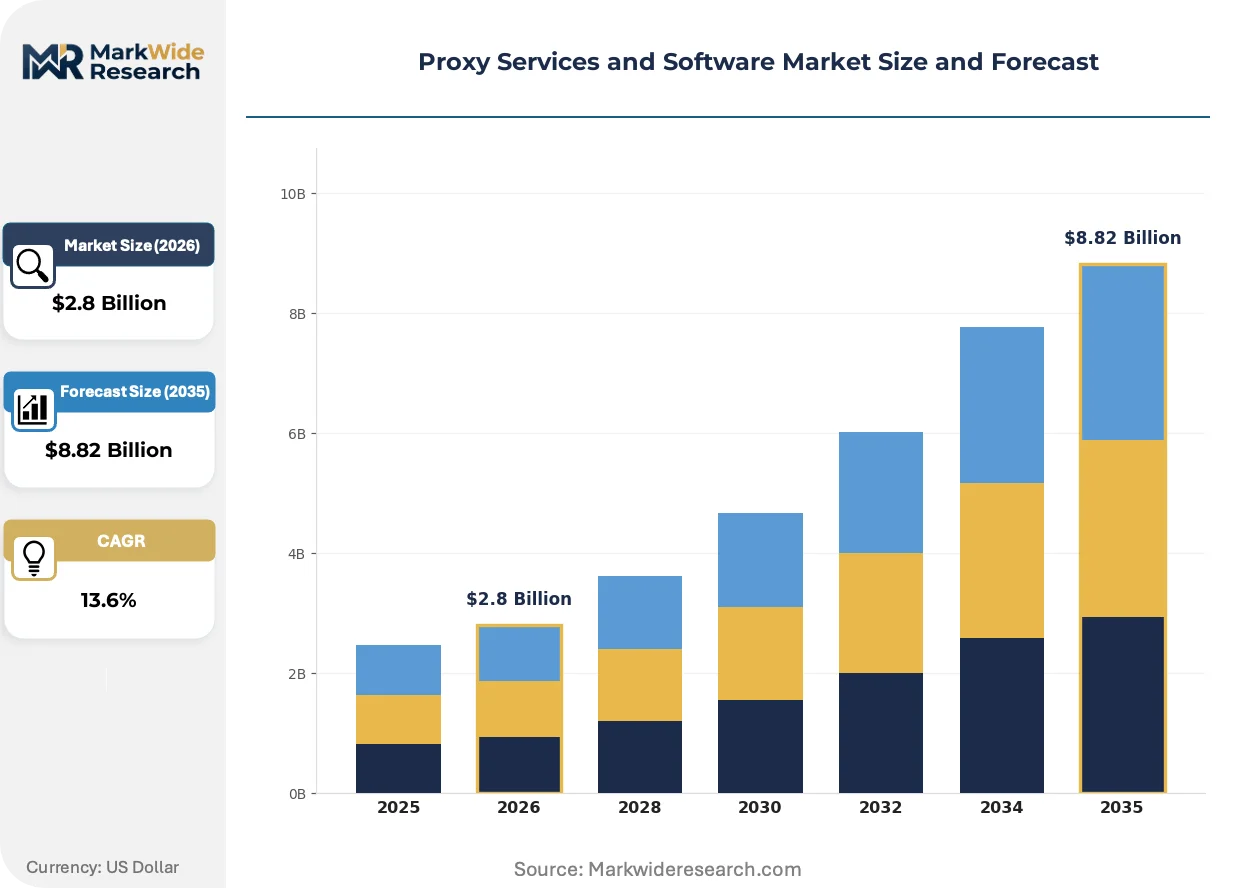
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Proxies, Shared Proxies, Residential Proxies, Datacenter Proxies Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Customer Type: Individual Users, Small Businesses, Enterprises, Agencies Application: Web Scraping, Content Access, Data Mining, Anonymity |
| Companies Covered | Bright Data, Oxylabs, Smartproxy, SOAX, NetNut, IPRoyal, Zyte, Apify, Infatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proxy Services and Software Market Trends and Innovations
Artificial intelligence training data pipelines are reshaping infrastructure requirements, with foundation model developers demanding petabyte-scale web scraping operations that stress-test traditional proxy architectures and force innovation in IP rotation algorithms.
Residential proxy infrastructure is absorbing the compliance burden previously managed through separate data governance layers. Financial services procurement teams in Frankfurt now specify origin-masking capabilities as core infrastructure requirements rather than aftermarket add-ons. This convergence is compressing vendor margins on standalone compliance tools while elevating premium positioning for integrated proxy-consent platforms.
The EU AI Act's training data documentation requirements are mandating granular provenance tracking for automated collection systems. Industrial AI deployments in German automotive and pharmaceutical clusters must now demonstrate lawful basis for every data point entering model training pipelines. Vendors responding with embedded consent logging and automated data retention enforcement are capturing multi-year enterprise contracts.
Mid-market agencies are abandoning annual proxy subscriptions in favor of consumption-based billing tied to successful data extraction events. E-commerce intelligence platforms in Amsterdam and Rotterdam now negotiate outcome-based pricing that shifts risk to infrastructure providers. This behavioral shift is most visible in the Benelux region, where procurement teams prioritize transparent success-rate metrics over raw IP volume commitments.
Proxy Services and Software Market Segmentation
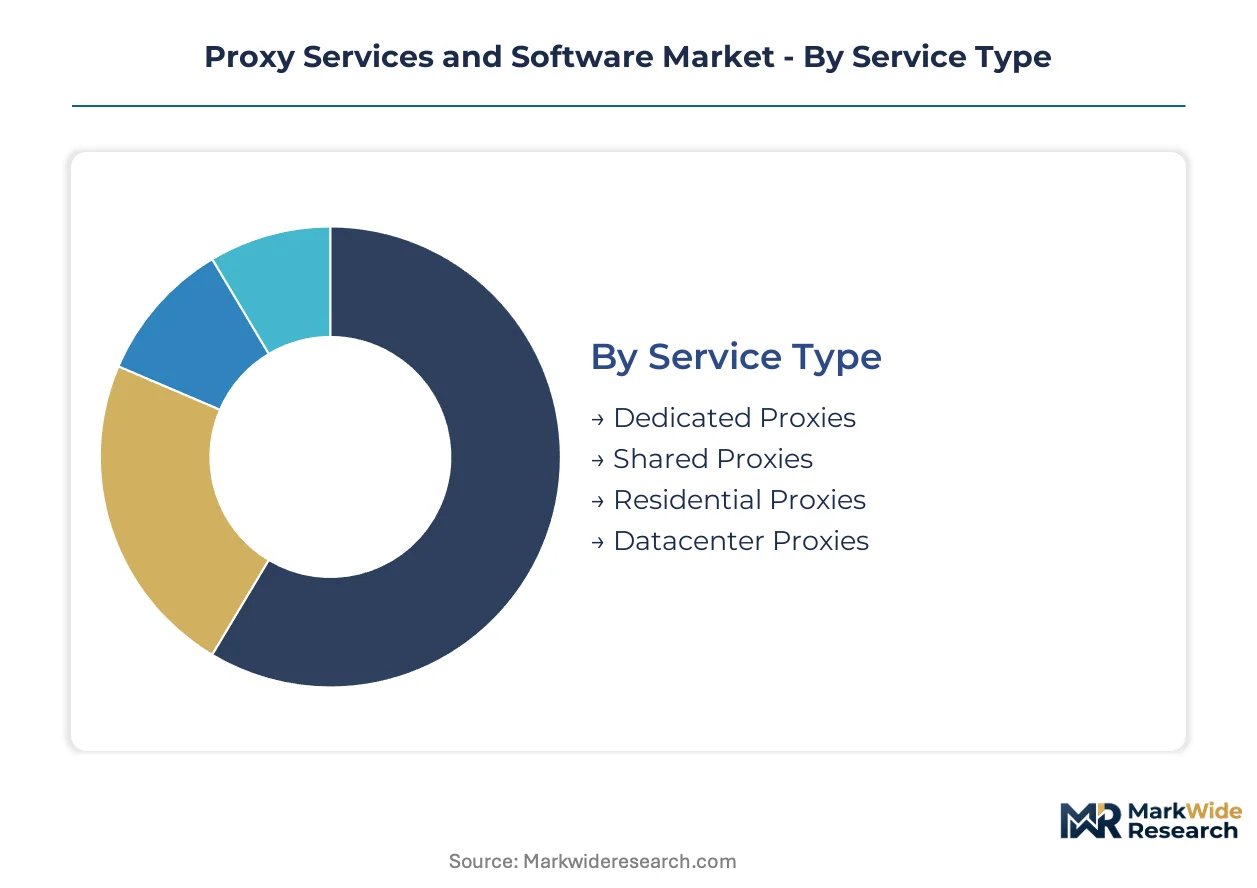
Proxy infrastructure purchasing decisions hinge on balancing anonymity requirements against operational complexity and compliance overhead. Segmentation reveals how enterprise procurement teams prioritize residential IP authenticity while mid-market buyers optimize for deployment velocity.
Service Type:
Buyers select proxy categories based on target platform sophistication and block-rate tolerance rather than price alone.
- Residential Proxies:These routes traffic through ISP-assigned IP addresses of actual consumers, achieving sub-5% block rates on detection-heavy platforms. Financial services compliance teams in Frankfurt and Amsterdam specify residential infrastructure for cross-border market intelligence pipelines subject to EU AI Act provenance requirements.
- Datacenter Proxies:Hosted on cloud server infrastructure, these deliver sub-50ms latency at volume price points. E-commerce intelligence platforms accepting higher block rates in exchange for petabyte-scale extraction dominate procurement here.
- Dedicated Proxies:Single-tenant IP pools eliminate neighbor reputation risks. German automotive clusters deploying predictive maintenance systems mandate dedicated routing for industrial IoT data sovereignty compliance.
- Shared Proxies:Multi-tenant IP pools distribute infrastructure costs across user bases. Mid-market agencies in Rotterdam and Brussels leverage shared pools for non-critical content access workflows.
Datacenter proxies lead on scale; residential proxies lead on momentum.
Deployment Model:
Infrastructure provisioning timelines now determine competitive positioning in time-sensitive data pipelines.
- Cloud-Based:API-first architectures enable geo-targeted proxy pool activation within minutes. Containerized deployment eliminates hardware procurement delays that previously extended enterprise sales cycles by 8-12 weeks.
- Managed:Vendors assume full operational responsibility including IP rotation logic and compliance logging. Frankfurt-based banks facing GDPR retention limits outsource lifecycle management to reduce internal engineering overhead.
- Hybrid:Combines on-premises gateway nodes with cloud burst capacity for demand spikes. Bavarian manufacturing clusters use hybrid models to keep sensitive predictive maintenance data within jurisdiction while accessing global IP pools.
- On-Premises:Self-hosted infrastructure satisfies strictest data localization mandates. Pharmaceutical R&D facilities in Baden-Württemberg deploy on-premises proxies to maintain custody of training data subject to EU AI Act documentation rules.
Cloud-based deployments are expanding most quickly; managed services capture premium margin concentration.
Customer Type:
Contract structures diverge sharply between consumption-based billing for mid-market buyers and multi-year enterprise agreements.
- Enterprises:Multi-year contracts with dedicated account engineering and SLA guarantees. These buyers specify embedded consent management and audit trail capabilities as core infrastructure requirements.
- Agencies:Outcome-based pricing tied to successful extraction events is displacing annual subscriptions. Benelux procurement teams prioritize transparent success-rate metrics over raw IP volume commitments.
- Small Businesses:Self-service onboarding portals reduce deployment friction. Cloud API access enables rapid geo-targeted proxy activation without vendor negotiation.
- Individual Users:Browser extension and mobile app interfaces dominate. Basic anonymity and content access use cases drive minimal feature requirements.
Enterprises lead on revenue per account; agencies are gaining share fastest.
Application:
Functional requirements shape protocol selection and session persistence specifications.
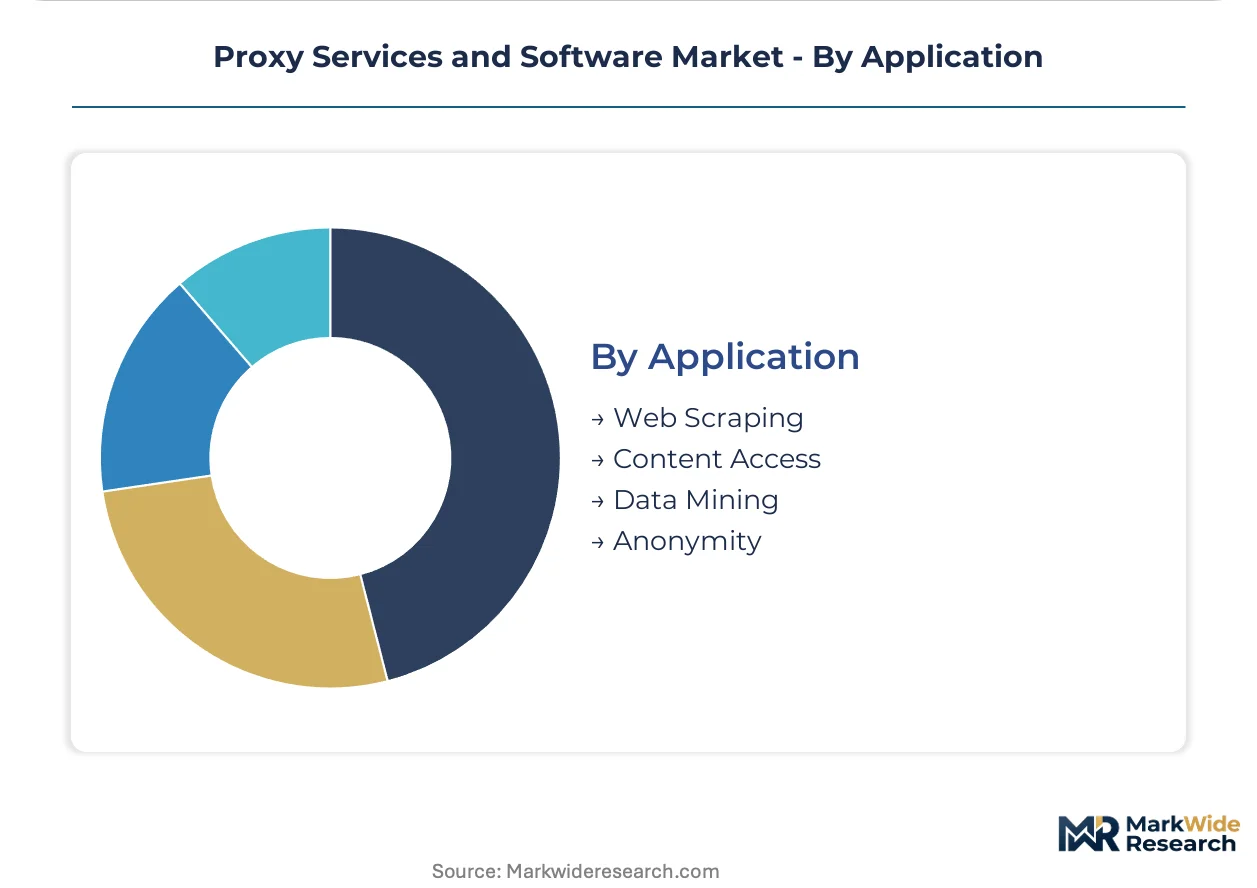
- Web Scraping:Automated data extraction at scale demands intelligent IP rotation and request throttling. Foundation model developers stress-test proxy architectures with petabyte-scale collection operations.
- Anonymity:Origin masking for security-conscious users requires SOCKS5 protocol support with cryptographic tunneling. Journalists and researchers in jurisdictions with restricted internet access constitute core demand.
- Data Mining:Structured extraction from multiple sources for business intelligence. Real-time bidding platforms require extended session continuity beyond standard HTTP/HTTPS rotation.
- Content Access:Geo-restricted streaming and research database access. Academic institutions and media monitoring services constitute stable demand pools.
Web scraping leads on infrastructure intensity; anonymity applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proxy infrastructure originated in North American data centers during the early commercial internet era, then migrated toward European compliance hubs as GDPR and subsequent AI governance frameworks reshaped architectural requirements.
United States
Enterprise security teams in New York and San Francisco drive consumption of cloud-native proxy pools for zero-trust network segmentation. The FTC monitors scraping-enabled competitive intelligence for unfair practice violations. Financial services clusters in Chicago and Charlotte deploy residential infrastructure for real-time market data collection.
Germany
Industrial data sovereignty mandates in Bavaria and Baden-Württemberg force automotive and pharmaceutical manufacturers toward jurisdiction-locked proxy nodes. The EU AI Act's training data documentation rules require granular provenance tracking. Frankfurt-based banks specify origin-masking capabilities as core procurement requirements for cross-border intelligence pipelines.
Netherlands
Amsterdam trading platforms and Rotterdam e-commerce intelligence providers demand outcome-based pricing tied to successful extraction events. GDPR retention limits force vendors to maintain complex data lifecycle management systems. Benelux procurement teams prioritize transparent success-rate metrics over raw IP volume commitments.
United Kingdom
London-based hedge funds and regulatory technology vendors absorb residential proxy capacity for compliance-heavy data collection workflows. The Information Commissioner's Office enforces purpose limitation requirements on automated collection systems. Fintech clusters in Manchester and Edinburgh specify embedded consent logging for AI training data pipelines.
China
Domestic data routing requirements from MIIT constrain foreign proxy infrastructure while enabling registered local providers to capture enterprise demand. Manufacturing intelligence platforms in Shenzhen and Hangzhou stress-test IP rotation algorithms with petabyte-scale collection operations. Shanghai-based foundation model developers drive innovation in session persistence protocols.
Proxy Services and Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance integration depth, with residential IP authenticity and embedded audit capabilities commanding 3-4x pricing multiples over basic datacenter rotation services. The vendor base stratifies into three functional tiers: full-stack platforms with consent management convergence, specialized scraping API providers, and self-service portals optimized for mid-market deployment velocity. Consolidation pressure concentrates among cloud hyperscalers bundling basic proxy functionality at near-zero marginal cost. Strategic moves center on API-first architectural shifts and jurisdiction-specific node deployment for data sovereignty compliance.
Within the full-stack platform tier, Bright Data and Oxylabs exemplify divergent positioning strategies. Bright Data anchors the premium residential proxy segment through ISP partnership networks concentrated in European compliance hubs. Oxylabs occupies the specialized infrastructure position with scraping API architectures designed for pipeline reliability at scale. Smartproxy represents the self-service velocity archetype, competing through reduced deployment friction for mid-market agency procurement teams.
| Leading Market Players |
|---|
| Bright Data |
| Oxylabs |
| Smartproxy |
| SOAX |
| NetNut |
| IPRoyal |
| Zyte |
| Apify |
| Infatica |
| Others |
Pricing and Supply Chain Analysis
Residential-authenticity premiums versus datacenter-volume economics bifurcate the market, with Frankfurt-based financial services procurement teams paying substantial markups for ISP-partnered IP pools while Rotterdam e-commerce platforms optimize for petabyte-scale extraction at minimal unit cost. This divergence concentrates margin capture among vendors controlling German and Dutch residential infrastructure, while compressing returns for cloud-hyperscaler bundles that commoditize basic rotation services.
Pricing Analysis
Consumption-based billing tied to successful extraction events is displacing annual subscriptions across Benelux procurement teams, with outcome-based contracts shifting operational risk to infrastructure providers. Price differentiation rests on consent-management integration depth and audit-trail granularity, with embedded compliance capabilities commanding substantial premiums over standalone proxy rotation. Cost compression in datacenter tiers intensifies as cloud hyperscalers bundle basic functionality at near-zero marginal cost. Mid-market agencies exhibit highest price sensitivity, while Frankfurt banks prioritize provenance documentation over unit economics.
Supply Chain Analysis
Engineering talent scarcity in low-latency networking and cryptographic tunneling concentrates vendor operations in Germany, the Netherlands, and Estonia, where specialized workforce pools support distributed systems development. Infrastructure draws from ISP partnership networks, cloud server capacity, and proprietary node hardware, with residential IP sourcing anchored in consumer broadband agreements. Single-source vulnerability in German ISP partnerships creates procurement bottlenecks during demand spikes. Distribution runs through API-first platforms and managed service engagements with dedicated account engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
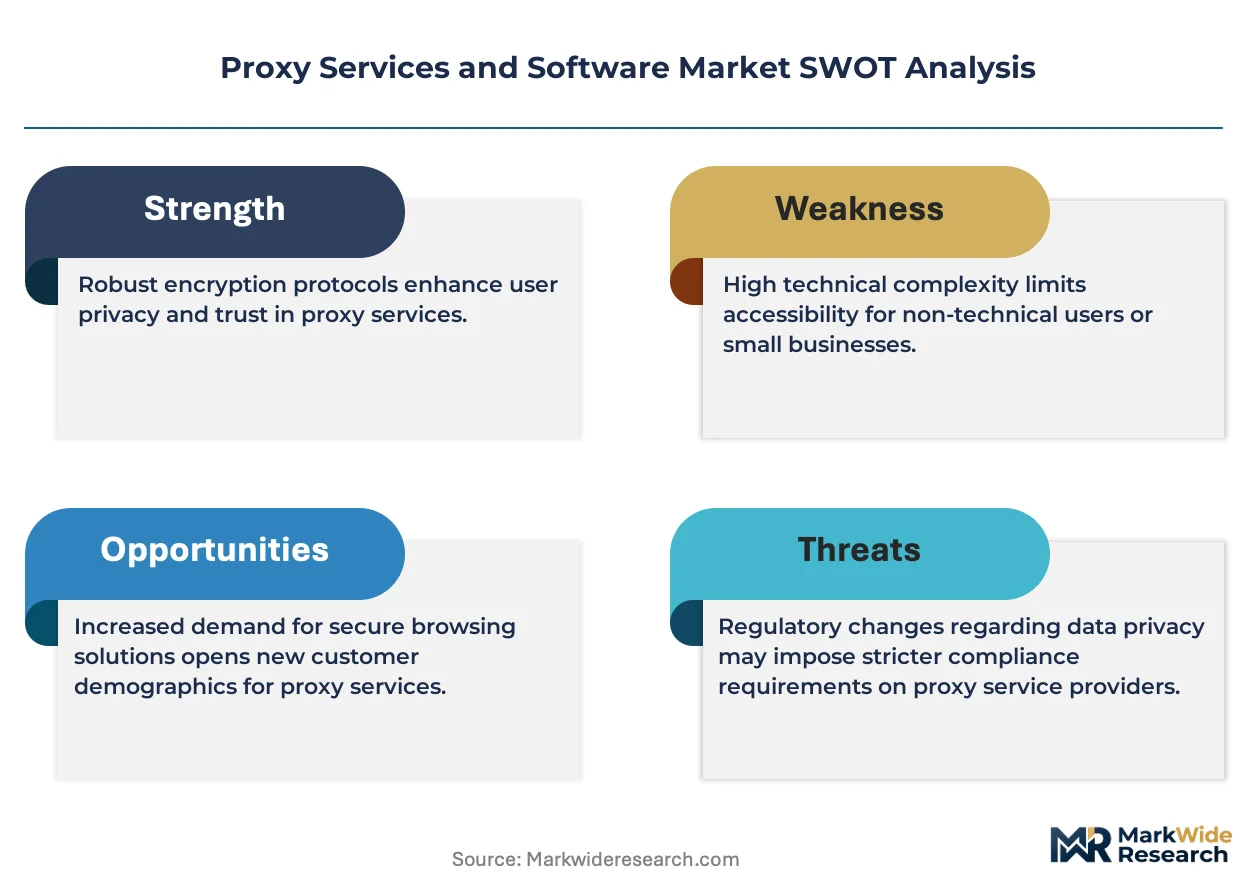
The proxy services market represents a late-cycle quality story where enterprise procurement teams are redirecting budgets toward auditable infrastructure with embedded consent management, elevating vendors with integrated compliance capabilities over commodity rotation providers.
For Market Incumbents: Acquire specialized scraping API architectures to fortify pipeline reliability positioning against emerging cloud-hyperscaler bundles. Secure exclusive ISP partnerships in Bavaria and Baden-Württemberg to defend residential IP supply advantages as industrial data sovereignty mandates tighten. Invest in SOCKS5 session persistence engineering to capture real-time bidding platform demand. For New Entrants and Emerging Players: Capture white space in consent management platform convergence for GDPR-compliant martech stacks undergoing privacy-first redesigns. Target mid-market agency segments in Rotterdam and Brussels with transparent success-rate pricing that displaces volume-based competitors. Lead with self-service onboarding velocity to reduce deployment friction against established managed service incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated platforms combining residential IP authenticity, embedded audit capabilities, and jurisdiction-specific node deployment. Long-term viability favors vendors with demonstrated EU AI Act compliance automation and multi-year enterprise contract structures. Monitor German automotive cluster procurement specifications for predictive maintenance data sovereignty requirements as an inflection indicator for industrial IoT proxy demand.| Strategic Initiative | Industry Significance |
|---|---|
| Residential IP Partnership Expansion | Exclusive ISP agreements in Frankfurt and Amsterdam lock in sub-5% block rate advantages for financial services compliance pipelines. |
| Consent Management Platform Integration | Embedded GDPR logging capabilities capture enterprise martech budget shifts toward privacy-first infrastructure convergence. |
| SOCKS5 Session Persistence Engineering | Extended connection continuity protocols differentiate vendors for real-time bidding and price intelligence engine requirements. |
| Jurisdiction-Specific Node Deployment | Localized routing infrastructure satisfies Bavarian manufacturing cluster mandates for predictive maintenance data sovereignty. |
| Outcome-Based Pricing Model Adoption | Success-rate metrics align vendor incentives with Benelux agency procurement priorities over raw IP volume commitments. |
Research Methodology
Coverage spans Germany, the Netherlands, the United States, and the United Kingdom, with primary inputs from each market triangulated against secondary validation. Interviews with enterprise cybersecurity directors, proxy infrastructure procurement leads at Frankfurt banks, compliance officers at Amsterdam trading platforms, and distributed systems engineers informed demand-side dynamics. Secondary sources include GDPR enforcement actions by European data protection authorities, SEC filings from cloud infrastructure providers, EU AI Act implementation guidance, and customs data on cross-border data routing equipment. Bottom-up proxy adoption modeling and top-down enterprise IT spending analysis were cross-referenced for triangulation.
Granularity-level modeling disaggregated revenue across service type, deployment model, customer type, and application dimensions throughout the projection horizon. CAGRs were derived from segment-specific adoption curves weighted by compliance mandate implementation timelines. Forecast inputs incorporated EU AI Act training data documentation requirements, zero-trust architecture penetration rates at financial services institutions, and industrial IoT deployment schedules at German automotive clusters. Volume projections for residential versus datacenter proxy consumption were validated against ISP capacity expansion announcements.
Regulatory enforcement intensity, residential IP supply constraints, and cloud-hyperscaler bundling acceleration are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about compliance automation adoption curves and enterprise procurement cycle timing. Practitioners should monitor German industrial data sovereignty mandate expansion and FTC scraping enforcement patterns for early signals of demand or supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Board Portal Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Procure to Pay Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Online Whiteboard Software Market
Software & Services
Global API Management Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Kennel Management Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Global Survey Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Mobile Enterprise Application Development Platform Market