
 UK Applicant Tracking System Market | 2026-2036
UK Applicant Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
UK Applicant Tracking System Market Analytics
The UK Equality Act 2010 and emerging Equality and Human Rights Commission guidance on algorithmic fairness in hiring is pivoting enterprise procurement toward audit-ready platforms. Oracle Corporation leverages its cloud infrastructure dominance to anchor large government contracts requiring sovereign data residency. Workday, Inc. sustains R&D intensity in native AI screening tools that compete on compliance documentation. Greenhouse Software specializes in mid-market SaaS configurations that navigate the UK's complex right-to-work verification workflows.
An applicant tracking system constitutes recruitment software that automates job posting distribution, candidate relationship management, and hiring workflow orchestration through configurable rule engines and API-based integrations with identity verification services. Cloud-Based deployment leads structural adoption as UK employers abandon on-premise maintenance overhead for scalable subscription models; SaaS configurations capture the fastest expansion among recruitment agencies seeking per-seat elasticity without capital commitment. Medium Enterprises represent the most contested end-user segment, where functionality demands for resume parsing and interview scheduling outpace vendor standardization, compressing margin pools and forcing differentiation through HRIS integration depth.
The Information Commissioner's Office enforces UK GDPR limits on automated decision-making in candidate evaluation, compelling vendors to embed explainability features and consent audit trails. The Equality and Human Rights Commission's emerging guidance on AI-assisted hiring intersects with the Cabinet Office's Procurement Policy Note on social value, reshaping product standards and public sector market access. Stakeholders must monitor how the UK's anticipated AI regulation framework recalibrates liability allocation between platform providers and employer users.
Market Dynamics
UK GDPR enforcement by the Information Commissioner's Office is forcing enterprise employers to replace legacy screening platforms with explainable AI architectures that document consent trails and decision logic. This regulatory pressure concentrates procurement cycles among NHS trusts and local authorities where workforce compliance mandates intersect with high-volume hiring.
Growth Catalysts
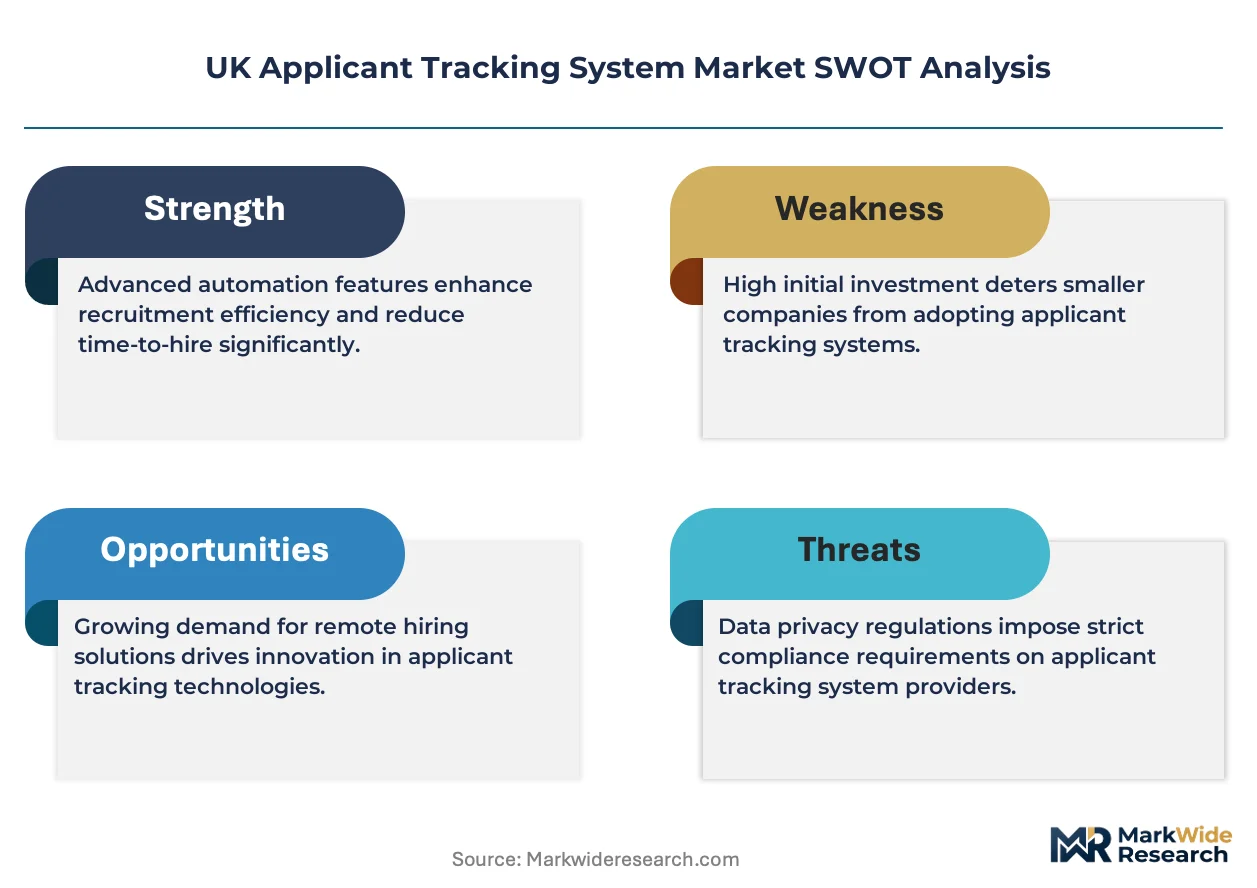
- Equality Act 2010 compliance mandates:Public sector employers must demonstrate bias-free candidate screening, accelerating platform replacement cycles in government and healthcare hiring.
- Right-to-work verification automation:Immigration compliance requirements are pulling mid-market recruitment agencies toward API-integrated ATS configurations that streamline document validation.
- London technology corridor expansion:Financial services and fintech hiring volumes in the capital are generating concentrated demand for scalable cloud-native recruitment infrastructure.
Market Restraints
- Sovereign data residency requirements:UK employers face elevated cloud infrastructure costs when mandating domestic data storage for GDPR compliance.
- Legacy system integration friction:On-premise HRIS architectures in established enterprises resist API-based connectivity, prolonging deployment timelines.
- Skills scarcity in algorithmic auditing:Shortage of compliance professionals capable of validating AI screening models limits vendor implementation capacity.
Strategic Opportunities
- Mid-market SaaS penetration:Recruitment agencies outside London remain underpenetrated by configurable per-seat platforms that eliminate capital commitment.
- Cabinet Office social value procurement:Public sector tender requirements create competitive openings for vendors embedding diversity reporting and local employment metrics.
- Explainable AI convergence with consent management:Platforms integrating automated decision documentation with candidate preference portals can capture premium positioning.
Industry Challenges
- Multi-jurisdictional compliance complexity:Vendors serving UK employers with EU operations must reconcile UK GDPR with emerging EU AI Act requirements on automated hiring decisions.
- Technical debt in public sector procurement:NHS trusts and local authorities operate fragmented legacy systems that resist standardized API integration, forcing costly custom implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Applicant Tracking System Market |
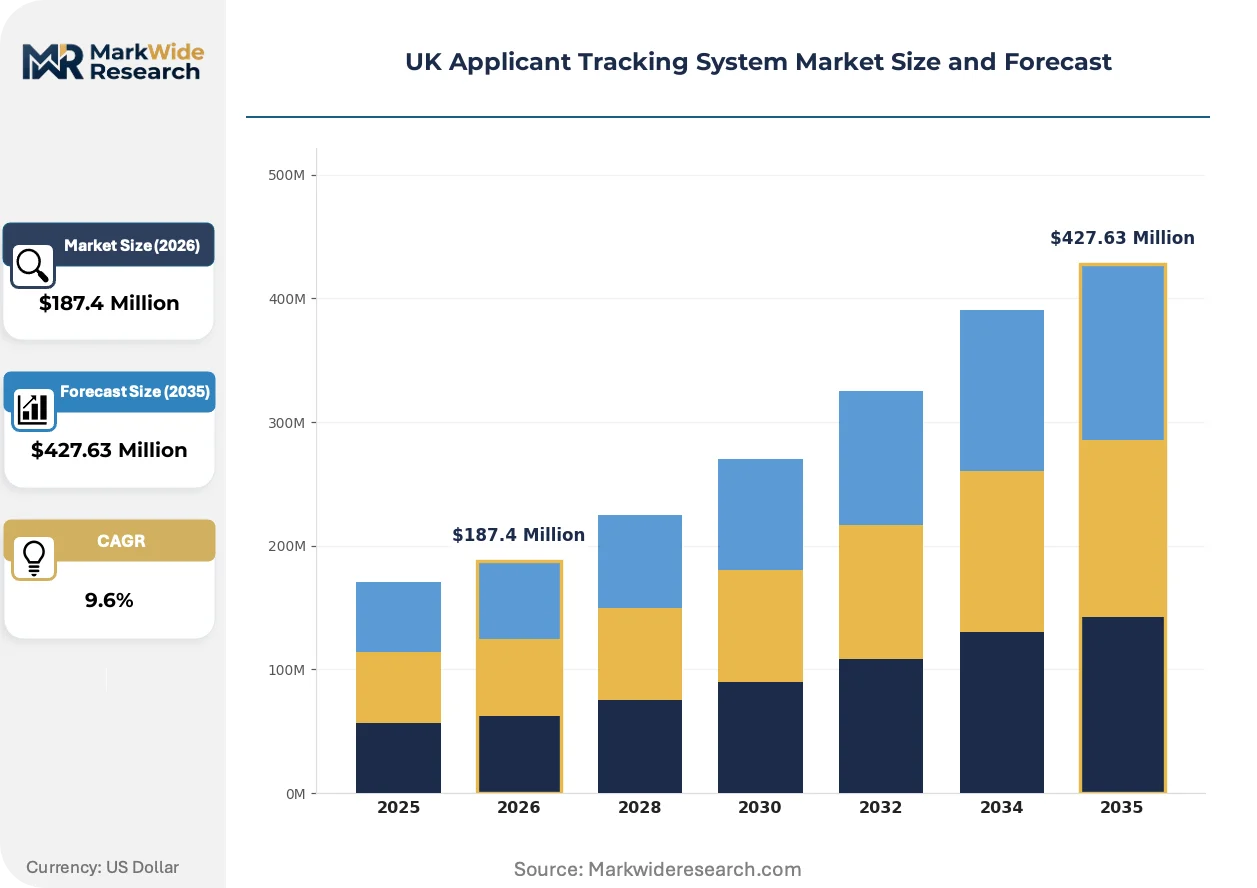
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Recruitment Agencies Functionality: Talent Acquisition, Resume Parsing, Interview Scheduling, Analytics Integration: HRIS, Payroll Systems, Job Boards, Others |
| Companies Covered | Oracle Corporation, SAP SE, Workday, Inc., iCIMS, Bullhorn, Inc., SmartRecruiters, Inc., Greenhouse Software, Workable, Pinpoint, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Applicant Tracking System Market Evolving Landscape
Explainable AI architectures are absorbing compliance documentation burdens while compressing vendor differentiation around audit-ready feature sets. Three convergent developments are restructuring competitive positioning.
Natural language processing for resume parsing is absorbing regulatory scrutiny around automated decision transparency. Mid-market recruitment agencies in Birmingham and Manchester are adopting these tools fastest, driven by volume hiring pressures. The technology is absorbing documentation requirements that previously demanded manual compliance workflows, compressing implementation timelines.
UK GDPR Article 22 restrictions on solely automated decisions are reshaping product architecture requirements. The Information Commissioner's Office enforcement posture compels vendors to embed human-in-the-loop checkpoints and consent audit trails. Public sector employers in Scotland and Wales are responding with procurement specifications that mandate explainability dashboards.
Subscription elasticity is displacing perpetual licensing in recruitment agency procurement. Per-seat SaaS configurations are replacing capital-intensive on-premise deployments among regional staffing firms. This pattern concentrates in the West Midlands and Greater Manchester, where agency margins resist fixed-cost infrastructure commitments.
UK Applicant Tracking System Market Segmentation
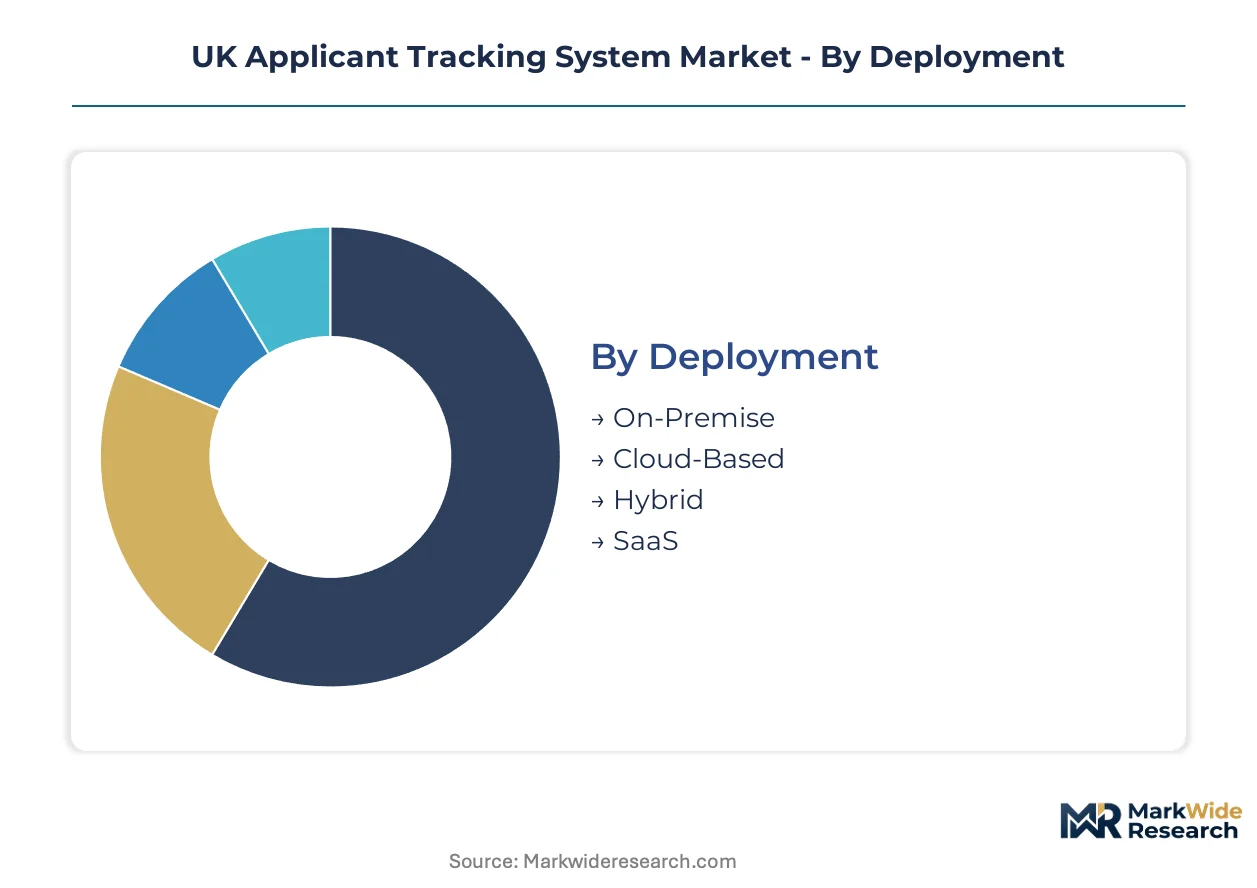
Segmentation in the UK ATS market reveals how procurement priorities diverge across employer size, technical architecture preference, and compliance workflow complexity. Understanding these fault lines exposes where vendor differentiation commands premium pricing versus where standardization erodes margins.
Deployment:
The volume-premium split in deployment modes reflects a stark trade-off between capital efficiency and data sovereignty control.
- Cloud-Based:Multi-tenant architectures with elastic compute allocation dominate procurement among London financial services and technology employers. NHS trusts in England are accelerating migration to these configurations to satisfy Cabinet Office cloud-first mandates while avoiding on-premise maintenance overhead.
- SaaS:Per-seat subscription models with API-native integration layers are capturing recruitment agencies across Birmingham and Manchester. West Midlands staffing firms favor this deployment for its elimination of capital commitment and rapid onboarding timelines.
- On-Premise:Single-tenant installations with dedicated hardware stacks persist in defense contractors and security-cleared government functions requiring air-gapped candidate data.
- Hybrid:Split architectures maintaining sensitive screening data on-premise while leveraging cloud compute for analytics are emerging among mid-market professional services firms navigating GDPR Article 22 complexity.
Today's leader: Cloud-Based. Tomorrow's challenger: SaaS.
End User:
Customer type dictates functionality depth, with mid-market employers demanding the most contested feature bundles.
- Medium Enterprises:Organizations with 250-999 employees require configurable workflow engines that balance sophistication against implementation speed. These employers in Greater Manchester and Leeds generate concentrated demand for resume parsing and interview scheduling modules that outpace vendor standardization.
- Recruitment Agencies:High-volume staffing operations need per-seat elasticity and rapid candidate pipeline turnover. Regional agencies outside London's technology corridor are adopting cloud-native platforms fastest to streamline right-to-work verification workflows.
- Large Corporations:Enterprise employers with complex HRIS ecosystems prioritize API integration depth and audit-ready compliance documentation over out-of-box functionality.
- Small Enterprises:Micro-employers with limited hiring volume favor stripped-down configurations emphasizing job board distribution and basic candidate tracking over advanced analytics.
Medium Enterprises absorb the most vendor R&D investment, while Recruitment Agencies are gaining share fastest.
Functionality:
Application focus determines where AI investment concentrates and where regulatory scrutiny bites hardest.
- Talent Acquisition:End-to-end sourcing and engagement platforms with CRM-style candidate nurturing are expanding most quickly among fintech employers in London competing for scarce technical talent.
- Resume Parsing:Natural language processing engines for automated CV extraction face intensifying Equality and Human Rights Commission scrutiny around algorithmic bias. These tools are absorbing compliance documentation requirements that previously demanded manual workflows.
- Interview Scheduling:Calendar integration and automated coordination modules reduce administrative overhead for high-volume hiring managers in NHS trusts and local authorities.
- Analytics:Dashboard and reporting functions embedding diversity metrics and time-to-hire analytics respond to Cabinet Office social value procurement requirements.
Talent Acquisition commands current R&D spend, but Resume Parsing is climbing the fastest as explainable AI mandates reshape product architecture.
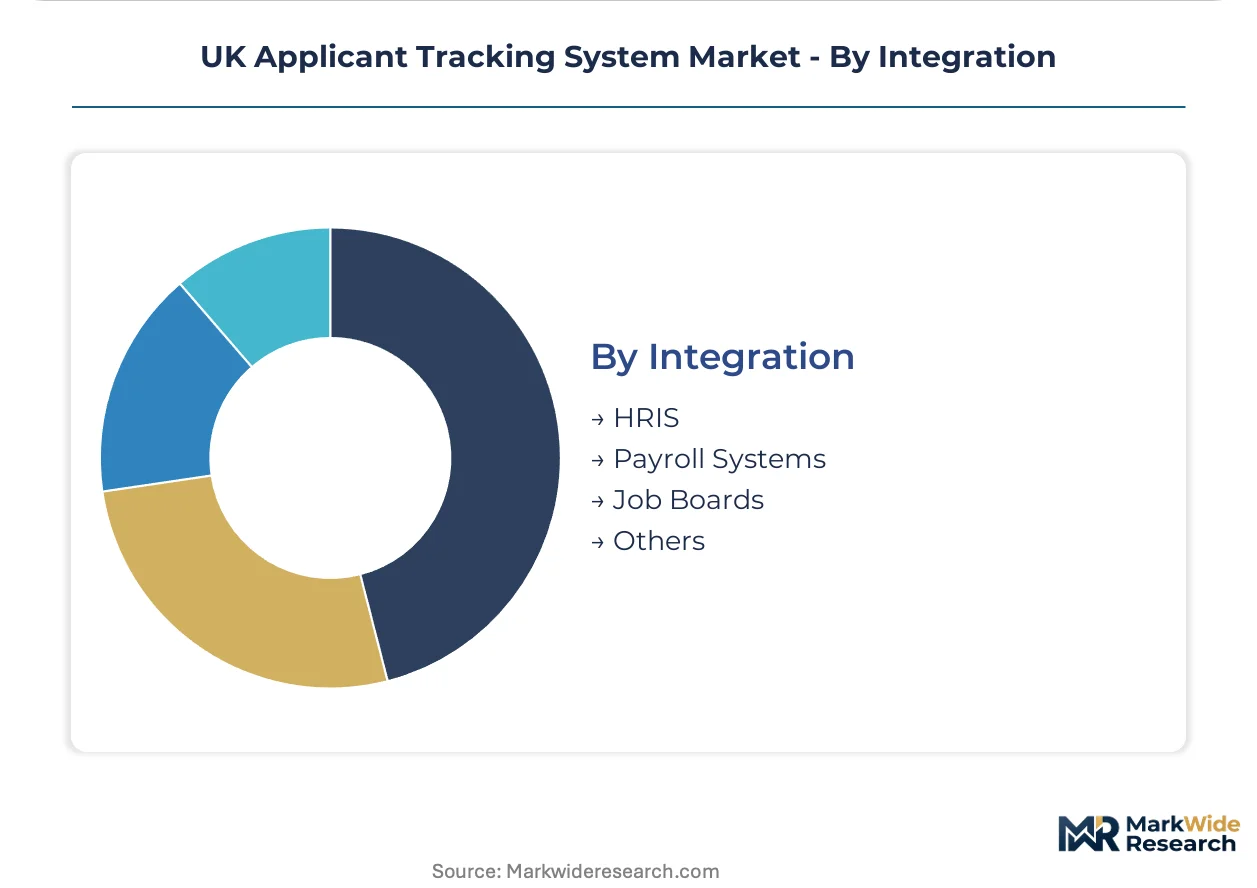
Integration:
Connectivity requirements expose where legacy system friction prolongs deployment and elevates implementation costs.
- HRIS:Bidirectional data synchronization with incumbent human capital management platforms represents the most technically demanding integration category. Established enterprises with on-premise Workday or Oracle deployments face extended API mapping exercises.
- Payroll Systems:Compensation data feeds and new-hire record automation are standardizing fastest, with pre-built connectors to major UK payroll providers reducing custom development.
- Job Boards:Multi-posting distribution APIs to Indeed, LinkedIn, and sector-specific platforms are table stakes, with differentiation shifting toward performance analytics rather than connectivity breadth.
- Others:Identity verification services, background check providers, and assessment platform integrations are expanding as right-to-work compliance automation becomes procurement-critical.
HRIS integration depth separates premium vendors from commodity players, while identity verification connectivity is emerging as the next competitive battleground.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Applicant tracking system deployment in the UK originated within London's financial services sector during the early 2000s digitization wave, then diffused through public sector procurement mandates and regional staffing industry consolidation.
London and the Southeast
Financial services and fintech employers drive concentrated demand for cloud-native recruitment infrastructure capable of handling high-volume technical hiring. The Financial Conduct Authority's operational resilience requirements intersect with UK GDPR mandates, pushing institutions toward audit-ready platforms with sovereign data residency guarantees. The City of London and Canary Wharf clusters host the densest concentration of enterprise ATS deployments, where regulatory scrutiny and talent competition converge most intensely.
Midlands
Manufacturing and logistics employers in Birmingham and the West Midlands generate sustained demand for right-to-work verification automation and shift-based workforce scheduling. The region's recruitment agencies favor per-seat SaaS configurations that eliminate capital commitment while streamlining compliance documentation. Leicester and Coventry industrial corridors are adopting API-integrated platforms fastest among mid-market staffing operations serving automotive and warehousing sectors.
North England
Leeds and Manchester technology corridors are emerging as secondary demand centers where scale-up employers compete for software engineering talent. The Department for Business and Trade's Northern Powerhouse investment programs are accelerating digital hiring infrastructure adoption among regional professional services firms. Greater Manchester's recruitment agency density is driving fastest SaaS penetration outside London, particularly for configurable workflow engines serving volume temporary staffing.
Scotland
Edinburgh and Glasgow financial services hubs maintain distinct procurement patterns shaped by Scottish Government public sector employment mandates and devolved regulatory frameworks. NHS Scotland trusts are migrating toward cloud-first ATS configurations under Cabinet Office-aligned procurement policies, with explainable AI requirements embedded in tender specifications. The Scottish technology corridor around Edinburgh's financial district is generating concentrated demand for candidate relationship management platforms serving asset management and fintech hiring.
Wales
Cardiff and Swansea public sector employers represent an underpenetrated segment where local government workforce compliance mandates are accelerating platform replacement cycles. The Welsh Government's digital transformation programs for public services are pulling procurement toward mid-market SaaS configurations with embedded diversity reporting. South Wales recruitment agencies serving manufacturing and healthcare sectors are adopting cloud-native platforms to streamline right-to-work verification workflows.
UK Applicant Tracking System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance documentation depth and HRIS integration sophistication. The UK ATS market structures around three distinct tiers: enterprise cloud platforms anchoring government and financial services contracts, mid-market SaaS specialists capturing recruitment agency procurement, and point-solution vendors competing on price for small employer segments. Strategic archetypes include infrastructure-leveraged incumbents with sovereign data residency capabilities, API-native challengers with rapid implementation timelines, and compliance-focused specialists embedding audit-ready feature sets. Dominant competitive moves center on M&A activity consolidating mid-market SaaS capabilities and strategic partnerships with identity verification providers automating right-to-work workflows.
Within the infrastructure-leveraged tier, Oracle Corporation and SAP SE exemplify platform providers anchoring large-scale public sector deployments through cloud sovereignty guarantees. Workday, Inc. occupies a position among native AI specialists competing on compliance documentation automation. These three enterprises represent contrasting archetypes: Oracle leverages existing government cloud relationships, SAP emphasizes ERP-integrated workflow orchestration, and Workday sustains R&D intensity in explainable screening architectures. Their collective positioning illustrates how regulatory complexity fragments competitive advantage across data residency, integration depth, and algorithmic transparency vectors.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Workday, Inc. |
| iCIMS |
| Bullhorn, Inc. |
| SmartRecruiters, Inc. |
| Greenhouse Software |
| Workable |
| Pinpoint |
| Others |
Value Network & Pricing Analysis
Cloud-native architecture migration is simultaneously compressing infrastructure costs for UK employers and concentrating vendor bargaining power among hyperscale platform providers. This dual effect reshapes how procurement teams negotiate subscription elasticity against data sovereignty requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates UK ATS procurement, with differentiation anchored in GDPR audit-readiness and HRIS integration depth. Price differentiation stems from compliance documentation sophistication and sovereign data residency guarantees. Cost compression in the standard tier is intensifying because mid-market recruitment agencies demand per-seat elasticity without capital commitment. Small enterprises exhibit highest price sensitivity, while NHS trusts and financial services institutions prioritize audit-ready feature sets over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Ireland and Netherlands as primary EU cloud infrastructure nodes serving UK data residency requirements. Software development draws from India, Poland, and Portugal for engineering talent pools. API dependency on identity verification services creates tariff exposure risk as immigration compliance automation becomes procurement-critical. Distribution runs through direct enterprise sales for large employers and channel partnerships for regional recruitment agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK ATS market functions as a stable compounder, with regulatory compliance mandates driving predictable replacement cycles across public sector and financial services hiring corridors.
For Market Incumbents: To counter mid-market SaaS challengers, Oracle Corporation and SAP SE should deepen API integration depth with legacy HRIS architectures while embedding explainable AI documentation as standard features. Sovereign data residency investments in UK-based cloud regions will anchor NHS and Cabinet Office contract renewals. For New Entrants and Emerging Players: Regional recruitment agencies outside London's technology corridor represent the most penetrable buyer archetype. West Midlands and Greater Manchester staffing operations favor configurable per-seat platforms that streamline right-to-work verification workflows. A vertical go-to-market targeting automotive and logistics hiring with shift-based scheduling modules captures fastest adoption. For Investors and Strategic Acquirers: Valuations sit cheapest among compliance-focused specialists with audit-ready feature sets but limited geographic footprint. Long-term viability hinges on algorithmic transparency capabilities as Equality and Human Rights Commission guidance hardens into enforceable standards. Monitor Cabinet Office Procurement Policy Note revisions as the signal for public sector tender specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native connectivity with Workday and Oracle HRIS anchors enterprise retention. |
| Strategic Partnership | Identity verification provider alliances automate UK right-to-work compliance workflows. |
| Acquisition of Specialist Firm | Explainable AI boutiques add algorithmic auditing capabilities for GDPR Article 22 mandates. |
| Geographic Expansion | Scottish and Welsh public sector presence captures devolved procurement authority flows. |
| Product Launch | Consent management portals with candidate preference documentation satisfy ICO enforcement posture. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HR technology procurement officers, NHS workforce planning directors, recruitment agency operations managers, and compliance audit specialists with secondary validation against Information Commissioner's Office enforcement notices, Cabinet Office procurement policy documentation, and Equality and Human Rights Commission draft guidance. Bottom-up deployment estimates across cloud, SaaS, on-premise, and hybrid configurations were triangulated against top-down vendor revenue segmentation.
Segment-weighting approaches applied differential growth assumptions across deployment modes, end-user categories, and functionality modules. The analytical framework modeled organization size tiers, vertical industry concentration, and regional adoption patterns throughout the forecast period. CAGRs were derived from historical procurement cycle analysis and projected regulatory compliance-driven replacement timelines, with sensitivity testing around AI regulation framework implementation pacing and public sector budget allocation shifts.
Underlying measurement precision varies by segment; cloud-based and SaaS deployment estimates carry tighter precision than hybrid configurations where definitional boundaries blur. Forecasts reflect assumptions about ICO enforcement continuity and Cabinet Office cloud-first mandate persistence, with revision risk from delayed UK AI legislation or devolved administration procurement policy divergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Address Verification Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Business Productivity Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Global Membership Management Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Global Programming Software Market
Software & Services
Global Chromatography Software Market
Software & Services
Global Content Management Software Market
Software & Services
Global OEE Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Global Permit Management Software Market