
 Chromatography Data System (CDS) Software Market | 2026-2036
Chromatography Data System (CDS) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Data System (CDS) Software Market Insights
The shortage of chromatography-trained laboratory informatics specialists is collapsing implementation timelines for enterprise CDS rollouts. Agilent Technologies leverages its OpenLab platform to sustain dominance in regulated pharmaceutical environments. Waters Corporation anchors its competitive position through tight integration with its chromatography hardware ecosystem. Thermo Fisher Scientific competes by extending chromatography data management into broader laboratory information management architectures.
Chromatography Data System software comprises applications that acquire, process, store, and report analytical data from gas and liquid chromatography instruments, typically supporting 21 CFR Part 11-compliant electronic records and signatures with audit trail functionality. The software serves pharmaceutical quality control, environmental testing, and food safety laboratories by ensuring data integrity, traceability, and regulatory compliance across analytical workflows. Cloud-based deployment models represent the fastest-expanding segment as laboratories seek reduced IT infrastructure burdens and remote accessibility, while single-vendor solutions still command the largest installed base due to hardware-software bundling incentives from instrument manufacturers. Compliance monitoring functionality carries the highest margin pools because pharmaceutical buyers prioritize validated audit trail and electronic signature capabilities over basic data acquisition features.
FDA 21 CFR Part 11, EU Annex 11, and ISO 17025 standards collectively shape CDS demand by mandating electronic data integrity controls that legacy systems cannot satisfy without costly replacement. The EPA and EMA both enforce data authenticity requirements that drive recurring validation service revenue for CDS vendors. Stakeholders must monitor evolving AI-enabled peak detection algorithms and their acceptance by regulators before embedding machine learning into validated chromatography workflows.
Market Dynamics
Pharmaceutical manufacturers are retiring paper-based chromatography workflows en masse as FDA 21 CFR Part 11 and EU Annex 11 deadlines harden. This compliance-driven replacement cycle is compressing sales cycles for validated CDS platforms while expanding validation service revenue pools.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature mandates force quality control laboratories to replace legacy data systems with compliant CDS infrastructure.
- Environmental testing laboratories:EPA enforcement of data authenticity requirements drives recurring validation investments in chromatography informatics.
- Cloud deployment models:Reduced IT infrastructure burdens accelerate adoption among mid-sized pharmaceutical contract manufacturers seeking remote accessibility.
Market Restraints
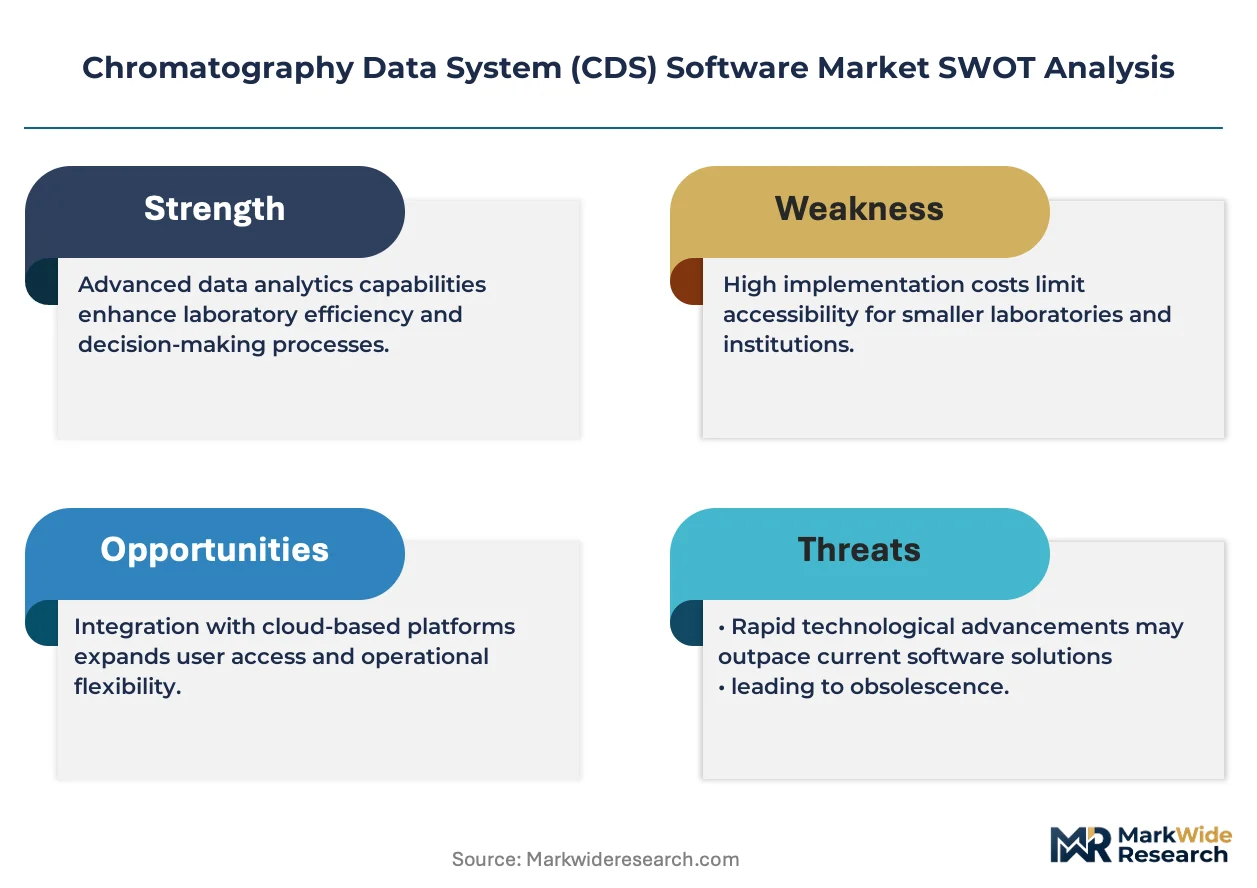
- Specialized talent scarcity:The shortage of chromatography-trained laboratory informatics specialists extends enterprise implementation timelines by 40-60%.
- Validation cost structure:Initial software licensing represents only 30-35% of total cost of ownership; ongoing validation services dominate lifetime expenditure.
- Hardware-software bundling:Instrument manufacturers leverage captive chromatography hardware bases to lock in CDS customers, raising switching costs for multi-vendor environments.
Strategic Opportunities
- AI-enabled peak detection:Machine learning algorithms for automated integration and anomaly detection await regulatory acceptance before embedding in validated workflows.
- China NMPA compliance:Domestic pharmaceutical manufacturing expansion creates demand for CDS platforms meeting China's evolving data integrity standards.
- Subscription pricing models:SaaS-based CDS offerings reduce upfront capital barriers for emerging biotech startups and contract research organizations.
Industry Challenges
- Chromatography informatics expertise gap:Laboratories struggle to staff hybrid roles combining analytical chemistry knowledge with software validation competency.
- Legacy system integration complexity:Multi-instrument environments require costly middleware development to unify data from heterogeneous chromatography hardware generations.
- Regulatory audit trail standardization:Divergent FDA, EMA, and NMPA requirements force vendors to maintain parallel validation documentation sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Data System (CDS) Software Market |
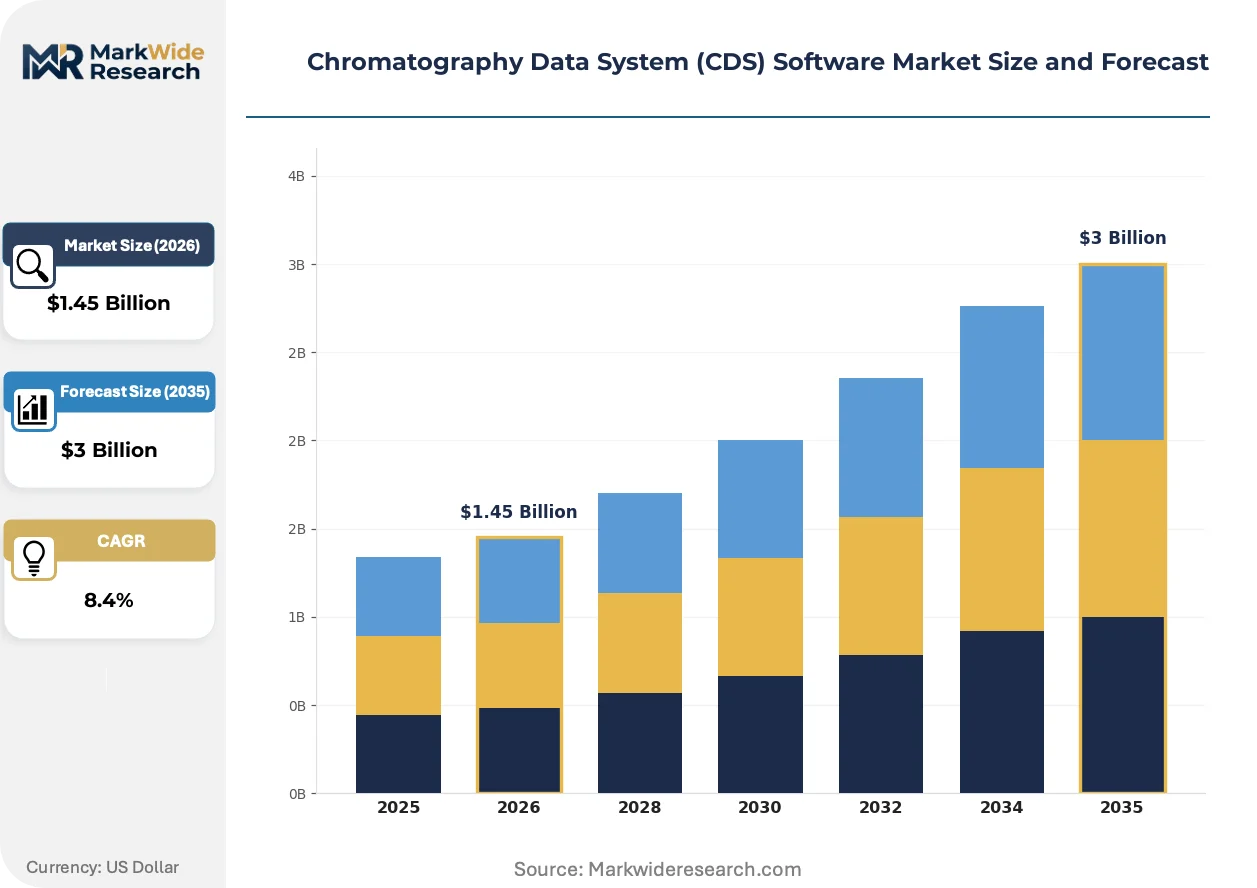
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Single-vendor, Multi-vendor, Open-source, Cloud-based Deployment Model: On-premises, SaaS, Hybrid, Virtual End User: Pharmaceuticals, Biotechnology, Food & Beverage, Environmental Functionality: Data Management, Compliance Monitoring, Reporting, Integration |
| Companies Covered | Shimadzu Corporation, Bruker Corporation, Agilent Technologies, DataApex, Gilson, Waters Corporation, PerkinElmer, KNAUER, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Data System (CDS) Software Market Trends and Innovations
Chromatography data management is converging with broader laboratory informatics architectures as vendors seek to escape hardware-software bundling traps. Three forces are actively restructuring competitive positioning and customer value propositions.
Cloud-native CDS architectures are displacing on-premise installations in quality control environments. Pharmaceutical manufacturers in Germany and Switzerland are migrating validated systems to private cloud instances to reduce data center overhead. This shift is compressing traditional perpetual-license revenue models while expanding recurring service contracts.
EU Annex 11 guidance on computerized systems is tightening electronic data integrity expectations for chromatography workflows. The EMA's heightened scrutiny of audit trail completeness is forcing retrospective validation of legacy CDS installations. Small-molecule API manufacturers in Ireland and the Netherlands are prioritizing platforms with pre-validated electronic signature modules.
Consolidated vendor relationships are reshaping procurement patterns among large pharmaceutical buyers. Quality control directors are reducing approved vendor lists from 4-5 CDS suppliers to 1-2 strategic partners. This concentration is most pronounced at US-based biologics manufacturers, where standardization across multiple manufacturing sites outweighs best-of-breed feature differentiation.
Chromatography Data System (CDS) Software Market Segmentation
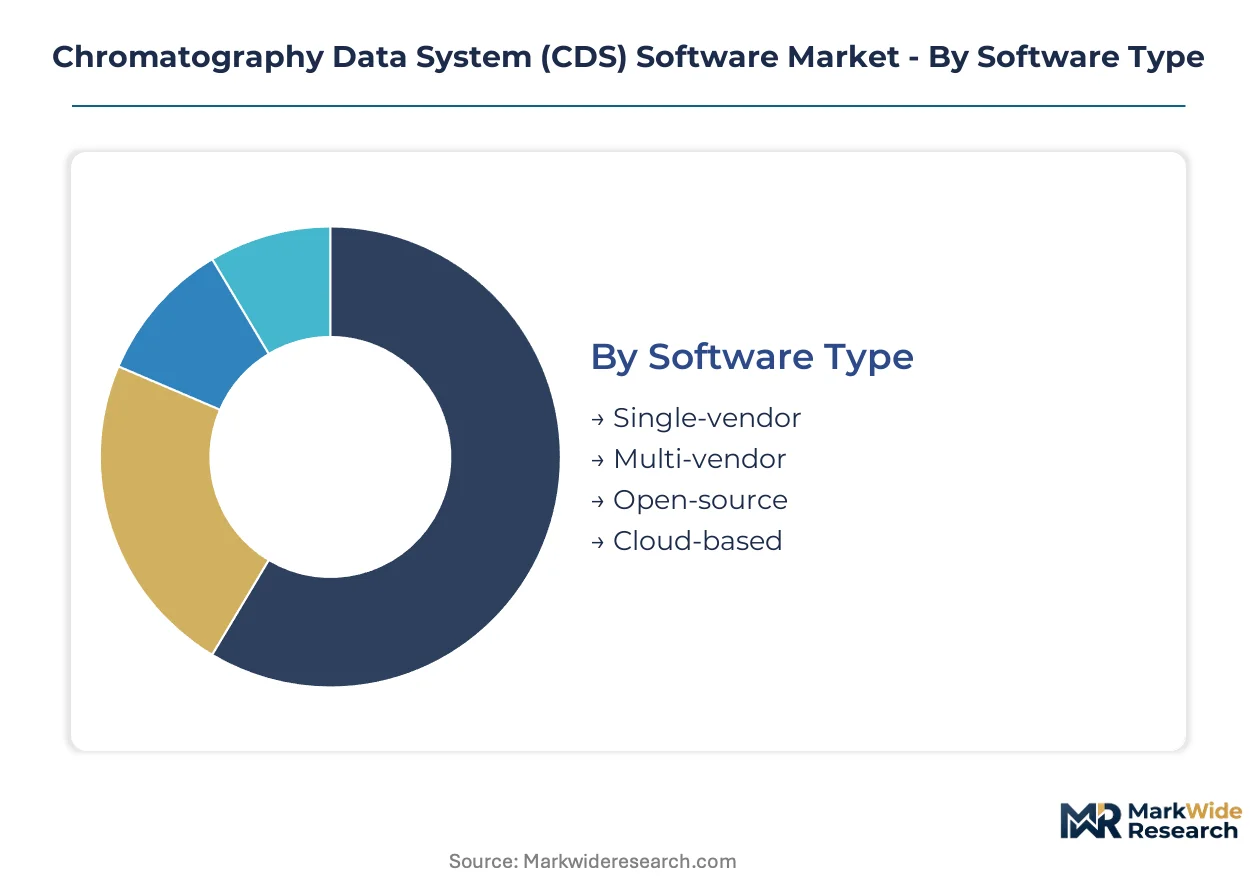
CDS software segmentation reveals how procurement channels, regulatory requirements, and technical architectures fragment demand across laboratory environments. Pharmaceutical buyers prioritize validated compliance modules while contract manufacturers gravitate toward cloud deployment to minimize capital expenditure.
Software Type:
Channel distribution varies sharply by software origin: instrument manufacturers push single-vendor solutions through hardware bundling, while independent vendors and system integrators dominate multi-vendor and open-source channels.
- Single-vendor:Tightly coupled with proprietary chromatography hardware from manufacturers like Agilent, Waters, and Thermo Fisher. Pharmaceutical quality control laboratories in the United States and Germany accept premium pricing to ensure seamless instrument-software compatibility and unified validation documentation.
- Cloud-based:Architected for remote accessibility and reduced IT infrastructure overhead. Mid-sized contract manufacturers in Switzerland and emerging biotech startups favor subscription models that convert capital expenditure to operational spending while maintaining 21 CFR Part 11 compliance.
- Multi-vendor:Middleware solutions unifying data from heterogeneous chromatography hardware generations. Environmental testing laboratories with mixed instrument fleets require these platforms to consolidate legacy and modern equipment.
- Open-source:Community-developed alternatives with limited regulatory validation support. Academic research institutions and early-stage discovery operations tolerate higher internal validation burdens to avoid licensing costs.
By volume, single-vendor solutions lead. By growth pace, cloud-based deployment is expanding most quickly.
Deployment Model:
Cost tier stratification separates enterprise pharmaceutical manufacturers investing in perpetual on-premises licenses from resource-constrained laboratories seeking operational flexibility through subscription models.
- SaaS:Fully managed cloud delivery with vendor-controlled infrastructure and automatic updates. Contract research organizations in Ireland and the Netherlands adopt SaaS to accelerate deployment timelines and eliminate server maintenance overhead.
- On-premises:Local server installation with customer-managed security and validation. Large biologics manufacturers in the United States retain on-premises systems to satisfy internal IT governance and data sovereignty requirements.
- Hybrid:Split architectures keeping sensitive acquisition data local while pushing archival and reporting functions to cloud tiers. European manufacturers navigating GDPR and EU Annex 11 simultaneously favor this compromise.
- Virtual:Containerized or virtualized deployments abstracting hardware dependencies. Organizations with centralized IT standardization policies leverage virtual models to replicate validated environments across multiple sites.
By installed base, on-premises retains dominance. By new contract velocity, SaaS is gaining share fastest.
End User:
Application-specific requirements drive divergent functionality priorities: pharmaceutical buyers demand audit trail completeness while environmental laboratories prioritize multi-instrument integration.
- Pharmaceuticals:Quality control and release testing operations governed by FDA 21 CFR Part 11 and EMA Annex 11. Small-molecule API manufacturers in Ireland and the Netherlands invest heavily in pre-validated electronic signature modules.
- Environmental:EPA and EMA-enforced data authenticity requirements for air, water, and soil analysis. Testing laboratories in Germany and Switzerland require robust audit trails to defend results during regulatory inspections.
- Biotechnology:Cell line development and bioprocess analytics with emerging AI-enabled peak detection needs. US-based biologics manufacturers pilot machine learning integration while awaiting regulatory acceptance.
- Food & Beverage:FSSAI and EFSA compliance for contaminant detection and nutritional labeling. Quality assurance departments seek cost-effective solutions with simplified validation pathways.
By revenue contribution, pharmaceuticals leads. By expansion trajectory, biotechnology shows the steepest climb.
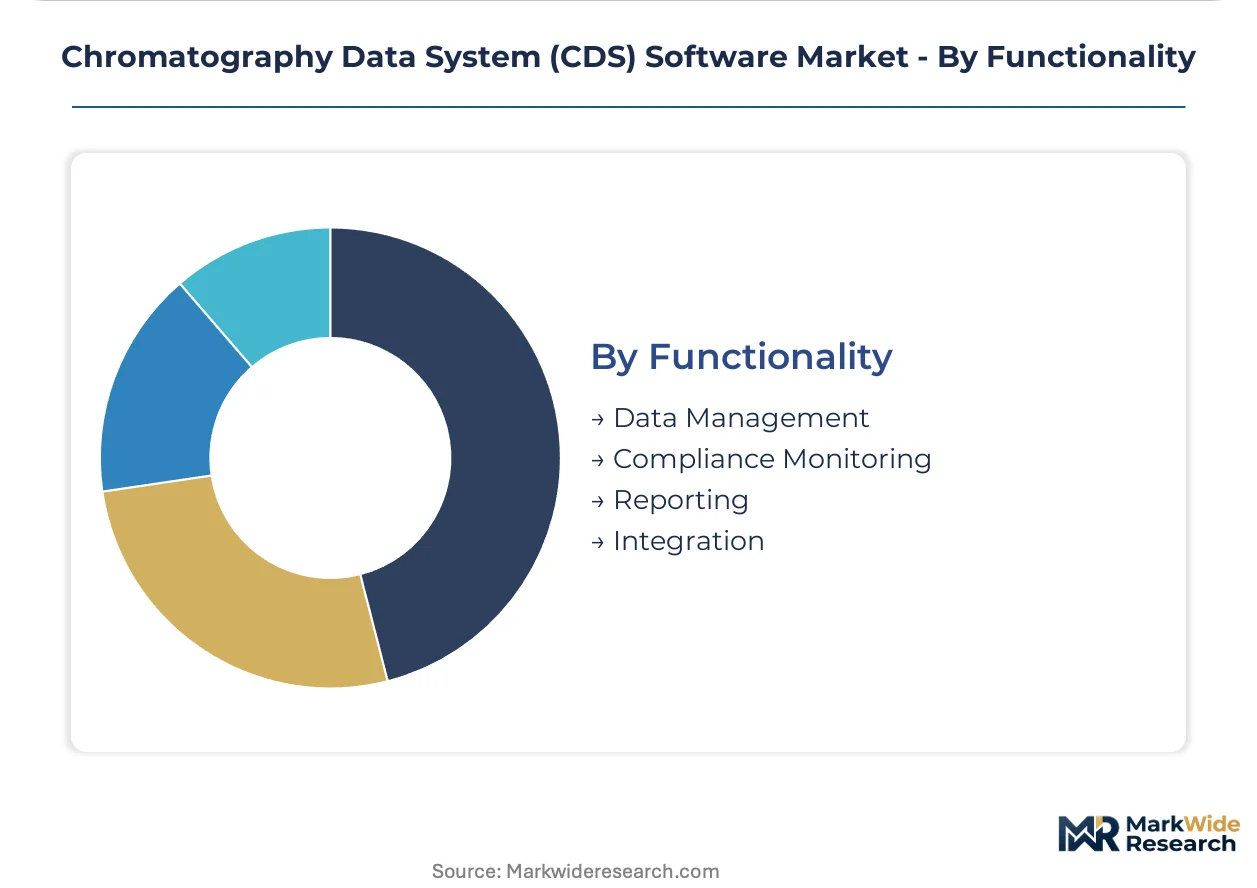
Functionality:
Margin concentration pools in high-value compliance modules rather than basic data acquisition, with pharmaceutical procurement committees prioritizing validated audit trail capabilities over feature breadth.
- Compliance Monitoring:Electronic records, signatures, and audit trail management satisfying FDA, EMA, and NMPA requirements. This functionality commands premium pricing due to validation documentation burdens and regulatory liability exposure.
- Data Management:Acquisition, processing, storage, and archival of chromatographic data. Core functionality bundled with most platforms but differentiated by search performance and long-term data integrity guarantees.
- Integration:Connectivity with LIMS, ELN, and ERP systems to unify laboratory informatics architectures. Large pharmaceutical buyers reducing approved vendor lists demand seamless bidirectional data exchange.
- Reporting:Automated generation of regulatory submission documents and internal quality reports. Customizable templates accelerate batch release decisions in high-throughput manufacturing environments.
By margin pool, compliance monitoring leads. By development investment, integration functionality is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 enforcement in the United States drives the largest installed base of validated CDS platforms. Pharmaceutical quality control laboratories across Germany, China, Switzerland, and the United Kingdom face parallel regulatory deadlines that are accelerating replacement cycles.
United States
Biologics manufacturers in Massachusetts and North Carolina are consolidating approved vendor lists from four suppliers to one or two strategic partners. FDA inspections of chromatography data integrity have intensified since 2023. The Boston-Cambridge cluster anchors demand for cloud-native CDS architectures that reduce data center overhead.
Germany
Small-molecule API manufacturers in Bavaria and North Rhine-Westphalia prioritize pre-validated electronic signature modules. EMA Annex 11 guidance on computerized systems has tightened audit trail expectations. The Frankfurt-Rhine-Main pharmaceutical corridor is migrating validated systems to private cloud instances.
China
Domestic pharmaceutical manufacturing expansion in Jiangsu and Zhejiang provinces creates demand for CDS platforms meeting NMPA data integrity standards. The country's national pharmaceutical regulator is aligning inspection protocols with FDA and EMA precedents. Shanghai-based contract manufacturers are piloting SaaS deployment models to minimize capital expenditure.
Switzerland
Swissmedic oversight of bioprocess analytics drives investment in compliance monitoring functionality. Basel's pharmaceutical cluster demands seamless LIMS integration to unify laboratory informatics architectures. Geneva-based quality control laboratories are adopting hybrid deployment models that keep acquisition data local while pushing archival functions to cloud tiers.
United Kingdom
Post-Brexit divergence from EU regulatory frameworks is forcing parallel validation documentation sets. MHRA inspections of chromatography workflows have increased at manufacturing sites in Cambridge and Oxford. The Southeast England biotech corridor favors subscription pricing models that convert capital expenditure to operational spending.
Chromatography Data System (CDS) Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the CDS market. The vendor base clusters around instrument manufacturers with captive hardware bases and independent software specialists serving multi-vendor environments. Three archetypes dominate: chromatography hardware bundlers, cloud-native platform specialists, and open-source middleware developers. Consolidation pressure is intensifying as large pharmaceutical buyers reduce approved vendor lists, while hardware-software bundling raises switching costs for laboratories seeking multi-vendor flexibility.
Within the instrument-integrated tier, Agilent Technologies, Waters Corporation, and Thermo Fisher Scientific exemplify the hardware-coupled archetype that commands premium pricing through unified validation documentation. These companies occupy positions where seamless instrument-software compatibility outweighs feature differentiation for pharmaceutical quality control laboratories. Independent platform specialists represent an alternative archetype focused on multi-vendor middleware and cloud deployment flexibility.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Bruker Corporation |
| Agilent Technologies |
| DataApex |
| Gilson |
| Waters Corporation |
| PerkinElmer |
| KNAUER |
| Thermo Fisher Scientific |
| Others |
Pricing and Supply Chain Analysis
Ninety-day validation service lead times for enterprise CDS rollouts concentrate pricing power with incumbent vendors possessing pre-validated documentation libraries, while hardware-software bundling from instrument manufacturers locks in premium tiers. Pharmaceutical quality control laboratories in the United States and Germany absorb these extended timelines because FDA 21 CFR Part 11 and EMA Annex 11 compliance mandates eliminate viable substitutes.
Pricing Analysis
Perpetual license premiums in Switzerland and Germany run substantially above subscription rates in China and India, reflecting validation documentation burdens and regulatory liability exposure. Three-tier pricing structure across validated compliance modules, standard data management, and basic acquisition tiers separates pharmaceutical manufacturers from contract research organizations and academic institutions. Pricing pressure stems from cloud-native entrants offering SaaS conversion of capital expenditure to operational spending. Contract research organizations in Ireland exhibit highest price sensitivity; large biologics manufacturers in Massachusetts demonstrate lowest sensitivity due to unified vendor standardization mandates.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for chromatography hardware components manufactured in Japan, Germany, and the United States. Software development centers in India and Ireland supply cloud architecture talent, while validation documentation production rests on specialized consultancies in Switzerland and the Netherlands. Single-source vulnerability concentrates in proprietary data format dependencies from dominant instrument manufacturers. Distribution runs through direct enterprise sales teams for large pharmaceutical accounts, with value-added resellers serving mid-sized contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as quality control directors reduce approved vendor lists from four suppliers to one or two strategic partners, compressing pricing flexibility for incumbent platforms.
For Market Incumbents: Compound hardware-software bundling advantages by deepening captive chromatography instrument bases before cloud-native platforms achieve regulatory acceptance. Invest in pre-validated AI-enabled peak detection modules to neutralize emerging machine learning entrants. Prioritize LIMS integration certification to defend against independent middleware specialists. For New Entrants and Emerging Players: Anchor in SaaS deployment models for emerging biotech startups and contract research organizations in China and India, where capital expenditure constraints outweigh brand loyalty. Target environmental testing laboratories with mixed instrument fleets requiring multi-vendor unification. Lead with rapid deployment timelines and subscription pricing to bypass incumbent validation service revenue pools. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA, EMA, and NMPA compliance documentation creates durable switching costs that transcend feature differentiation. Target acquisition candidates with validated audit trail modules and established pharmaceutical manufacturer relationships. Monitor EMA guidance on AI-enabled chromatography workflows as inflection signal for machine learning integration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Reduces data center overhead for pharmaceutical manufacturers in Germany and Switzerland. |
| AI-Enabled Peak Detection Development | Awaits FDA and EMA regulatory acceptance before validated workflow embedding. |
| Pre-Validated Compliance Module Expansion | Captures premium pricing from small-molecule API manufacturers in Ireland and Netherlands. |
| LIMS Integration Partnership | Unifies laboratory informatics architectures for Basel pharmaceutical cluster demands. |
| SaaS Pricing Model Introduction | Converts capital expenditure to operational spending for Shanghai contract manufacturers. |
Research Methodology
Desk research of FDA 483 observation databases, EMA inspection reports, and SEC 10-K software revenue disclosures preceded structured interviews with quality control directors, regulatory affairs leads, validation service consultants, and laboratory informatics architects. Primary fieldwork across pharmaceutical manufacturing clusters in Massachusetts, Bavaria, and Jiangsu province combined with secondary triangulation against ISO 17025 accreditation records and NMPA guidance documents. Bottom-up installation base estimates and top-down enterprise spending allocations were reconciled through iterative stakeholder validation.
Variance decomposition across deployment models, end-user verticals, and functionality tiers shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled dimensions included software type, deployment architecture, end-user industry, and regional regulatory cluster. Forecast inputs incorporated cloud adoption velocity in contract manufacturing, AI regulatory acceptance timelines, and pharmaceutical capital expenditure cycles.
Decision-makers should treat outputs as directional under assumptions of sustained FDA 21 CFR Part 11 enforcement and stable pharmaceutical manufacturing footprint expansion; material deviation in regulatory inspection intensity or biologics facility investment would warrant model refresh. Specific risk factors include NMPA data integrity standard evolution, AI validation pathway uncertainty, and talent scarcity impacts on implementation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Optical Design Software Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Software Defined Broadcasting Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Avionics Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Global ITSM Software Market
Software & Services
Global Award Management Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Period-Tracking Software Market
Software & Services
Calorie Metering Software Market
Software & Services
Global Back Testing Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Construction Equipment Fleet Management Software Market