
 Meditation Software Market | 2026-2036
Meditation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Meditation Software Market Insights
Generative AI integration into personalized meditation content is reconfiguring how platforms deliver adaptive mindfulness experiences at scale. Calm leverages its extensive audio library and celebrity partnerships to sustain brand dominance in the direct-to-consumer segment. Headspace anchors its position through corporate wellness channels, competing for large employer contracts against newer entrants. Insight Timer differentiates via its community-driven model, offering free content from thousands of teachers while monetizing through premium subscriptions.
Meditation software encompasses digital platforms that deliver structured mindfulness, breathing, and relaxation protocols through audio, video, and interactive interfaces, typically operating on cloud-native architectures with latency requirements under 200 milliseconds for real-time biometric feedback integration. These systems serve therapeutic, productivity, and preventive health objectives across consumer and institutional settings. Cloud-Based deployment leads the infrastructure landscape due to elastic scaling demands during peak usage windows, while the Corporate end-user segment captures expanding margin pools as enterprise procurement centralizes wellness spending under HR technology budgets. Freemium license structures dominate user acquisition funnels, though Enterprise licensing generates superior unit economics through annual contract values and reduced churn.
The US Food and Drug Administration maintains evolving oversight of software-based mental health interventions, creating compliance thresholds that influence product classification and clinical claim validation. The European Union's GDPR and the US HIPAA framework jointly shape data governance architectures, requiring vendors to implement region-specific consent management and encryption standards. Stakeholders must monitor regulatory divergence between jurisdictions as digital therapeutics classifications expand, determining whether to pursue formal medical device pathways or remain in the wellness category.
Market Dynamics
Generative AI is restructuring content production economics across meditation platforms, compressing the cost of personalized audio generation while raising the bar for differentiation through proprietary biometric integration and clinical validation pipelines.
Growth Catalysts
- Employer Wellness Mandates:Large enterprises in the United States are consolidating mental health spending under HR technology budgets, creating procurement centralization that favors platform vendors with enterprise-grade security and administrative dashboards.
- HIPAA Compliance Infrastructure:The US framework for health data protection is driving vendor investment in encryption and consent management systems that unlock institutional contracts previously closed to consumer-grade applications.
- Real-Time Biometric Feedback:Wearable device integration is enabling adaptive meditation protocols that adjust session parameters based on heart rate variability and skin conductance, improving engagement metrics and retention curves.
Market Restraints
- Clinical Validation Costs:Randomized controlled trials required for FDA digital therapeutics classification demand capital outlays that favor well-capitalized platforms and exclude smaller developers from medical-grade positioning.
- Cloud Infrastructure Concentration:Dependency on hyperscale providers in the United States for low-latency audio delivery creates geographic concentration risk and compliance complexity for data residency requirements in Europe and Asia-Pacific.
- Free Substitute Availability:YouTube and podcast platforms offer unlimited meditation content without subscription fees, establishing a price anchor that compresses willingness-to-pay for premium features among price-sensitive consumer segments.
Strategic Opportunities
- Underpenetrated German Market:Corporate wellness adoption in Germany lags the United States by several years, creating first-mover advantage for platforms that localize content and achieve BfArM digital health application classification.
- AI-Voice Synthesis Convergence:Neural text-to-speech systems combined with large language models enable dynamic script generation that responds to user emotional state, opening premium pricing tiers for hyper-personalized experiences.
- Insurance Reimbursement Channels:Germany's DiGA framework and similar programs in France and the Netherlands are creating prescription pathways where meditation apps qualify for statutory health insurance coverage, fundamentally altering customer acquisition economics.
Industry Challenges
- Clinical Evidence Generation:Building randomized trial portfolios for regulatory submissions requires specialized health economics expertise that commands premium salaries and extends product development timelines.
- Cross-Border Data Architecture:Reconciling GDPR data localization requirements with HIPAA portability rules demands engineering resources that strain mid-size vendors and complicate multi-region expansion strategies.
- Interoperability Standards:Absence of universal APIs for electronic health record integration forces bespoke development for each hospital system, fragmenting engineering roadmaps and delaying enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meditation Software Market |
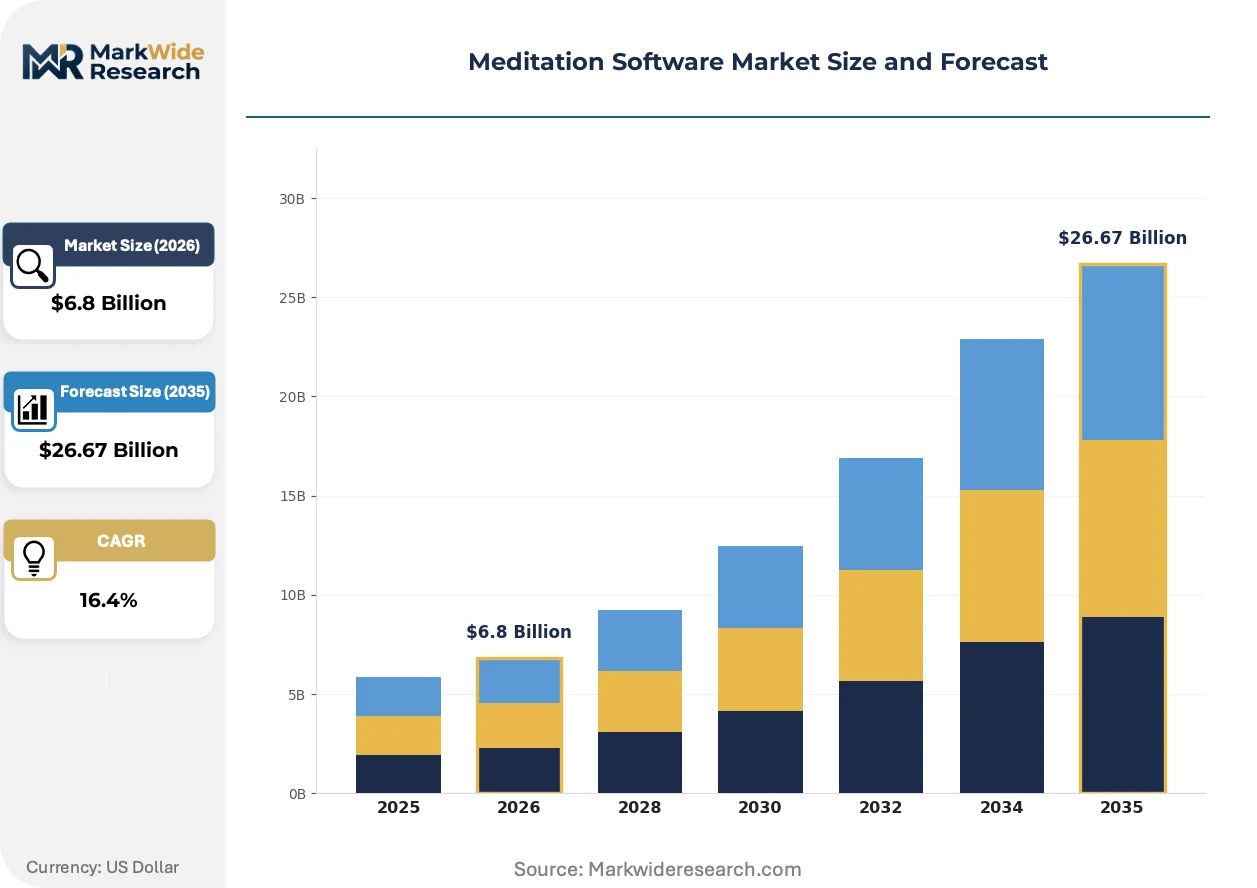
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Individual Users, Corporates, Educational Institutions, Wellness Centers Feature: Guided Sessions, Progress Tracking, Community Support, Analytics License Type: Subscription, One-Time Purchase, Freemium, Enterprise |
| Companies Covered | Calm, Headspace, Insight Timer, Aura Health, Simple Habit, Meditopia, Ten Percent Happier, Breethe, Smiling Mind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meditation Software Market Trends and Innovations
Adaptive content generation and clinical validation pathways are redefining competitive moats in meditation software, separating wellness applications from regulated digital therapeutics through diverging investment priorities and technical architectures.
Generative audio synthesis is virtualizing the production of personalized meditation sessions at scale. Enterprise wellness buyers in the United States are piloting platforms that generate custom content based on employee stress profiles and organizational objectives. This technology is virtualizing the traditional content library model, compressing the value of static audio catalogs while amplifying returns on proprietary user data and algorithmic personalization engines.
The FDA's evolving oversight of software-based mental health interventions is creating bifurcated product strategies. Developers must now decide between wellness positioning with limited clinical claims or pursuing 510(k) clearance with associated trial costs and timeline risks. European developers face parallel complexity from the MDR's expanding scope for mental health software, with Germany's BfArM emerging as the most active national regulator for digital therapeutic classification.
Buyer concentration within Fortune 500 HR departments is consolidating vendor selection authority. Procurement teams now evaluate meditation platforms alongside broader benefits technology stacks, replacing decentralized departmental purchasing with centralized multi-year contracts. This shift is most visible in the United States, where employer-sponsored wellness spending exceeds all other national markets and procurement professionals demand integration with existing HRIS and benefits administration systems.
Meditation Software Market Segmentation
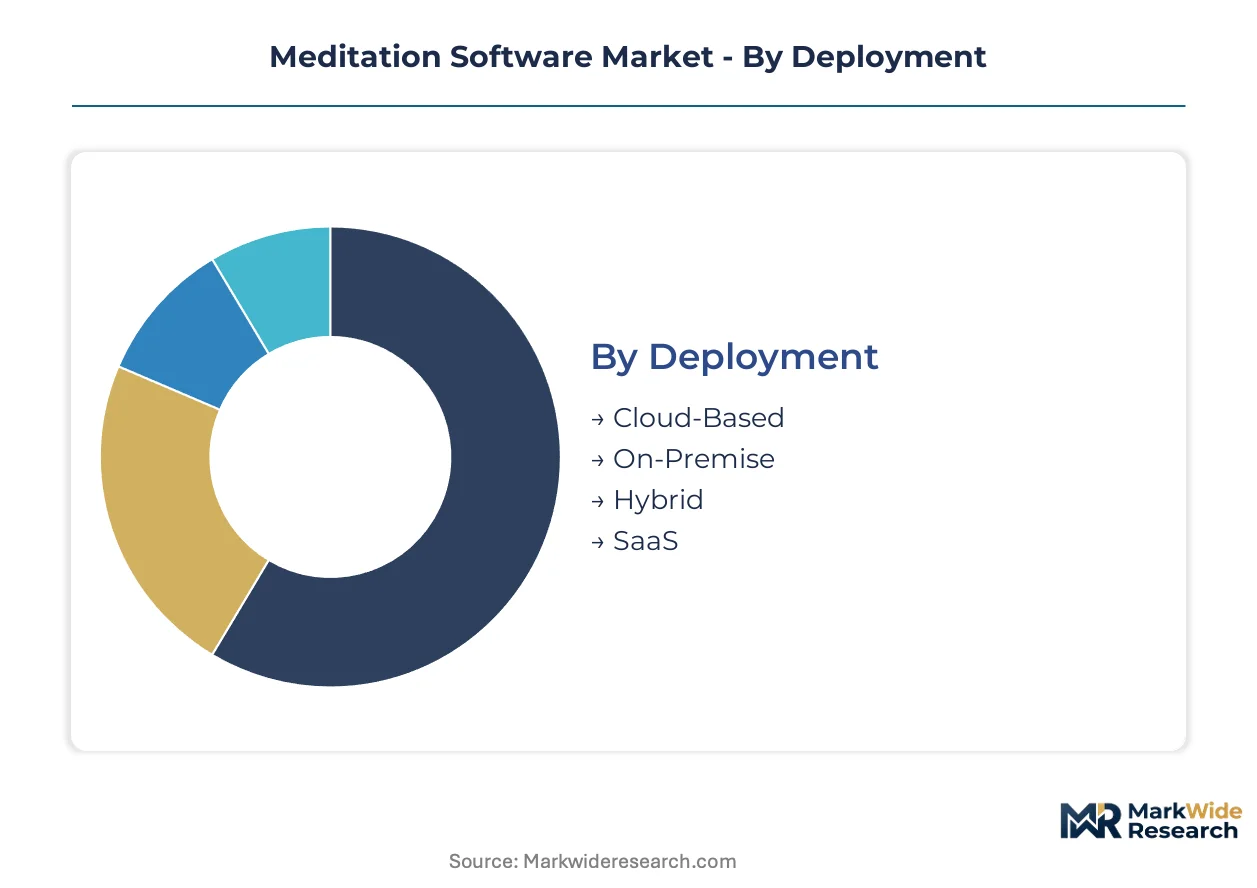
Segmentation in meditation software reveals how infrastructure choices, customer economics, and engagement mechanics split the addressable market into discrete purchasing contexts. Each dimension carries distinct margin profiles and competitive dynamics that shape vendor strategy.
Deployment:
Cost tier determines infrastructure commitment and operational flexibility for platform operators and their customers.
- Cloud-Based:Elastic compute resources scale automatically during morning and evening usage peaks without capital expenditure. Demand concentrates among mid-size wellness platforms serving United States employers that require sub-200ms latency for biometric feedback integration.
- SaaS:Pre-configured application stacks eliminate DevOps overhead while embedding compliance certifications into the service layer. Corporate procurement teams in Germany favor this model for rapid BfArM digital health application pathway compliance without自建 infrastructure investment.
- On-Premise:Dedicated servers within institutional firewalls serve hospital systems and defense contractors with data residency mandates.
- Hybrid:Split architectures process sensitive user data locally while pushing anonymized analytics to cloud endpoints.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
End User:
Customer type defines pricing power, contract duration, and integration complexity across the revenue base.
- Corporates:Annual contracts with centralized HR technology budgets generate superior unit economics through reduced churn and administrative dashboard requirements. United States Fortune 500 procurement teams now evaluate meditation platforms alongside benefits administration systems.
- Individual Users:Direct-to-consumer subscriptions face price compression from YouTube and podcast substitutes, though celebrity-voiced content sustains premium tiers in English-language markets.
- Educational Institutions:Campus-wide licenses for student mental health services operate on academic pricing schedules with extended pilot periods.
- Wellness Centers:Brick-and-mortar studios white-label platform content for member retention and at-home practice continuity.
Corporates command pricing power. Individual Users anchor volume scale.
Feature:
Application depth separates wellness utilities from clinical-grade therapeutic tools through functional architecture.
- Guided Sessions:Audio and video content libraries remain the core engagement mechanism, with generative AI now compressing production costs for personalized script generation.
- Progress Tracking:Streak counters and milestone systems drive retention curves through behavioral reinforcement loops.
- Community Support:Teacher-led groups and peer forums create network effects that differentiate platforms from static content repositories.
- Analytics:Aggregate stress metrics and usage dashboards serve corporate wellness administrators seeking ROI documentation for benefits spending.
Guided Sessions delivers baseline utility. Analytics is climbing the fastest as enterprise buyers demand measurable outcomes.
License Type:
Revenue model selection shapes customer acquisition economics and lifetime value trajectories.
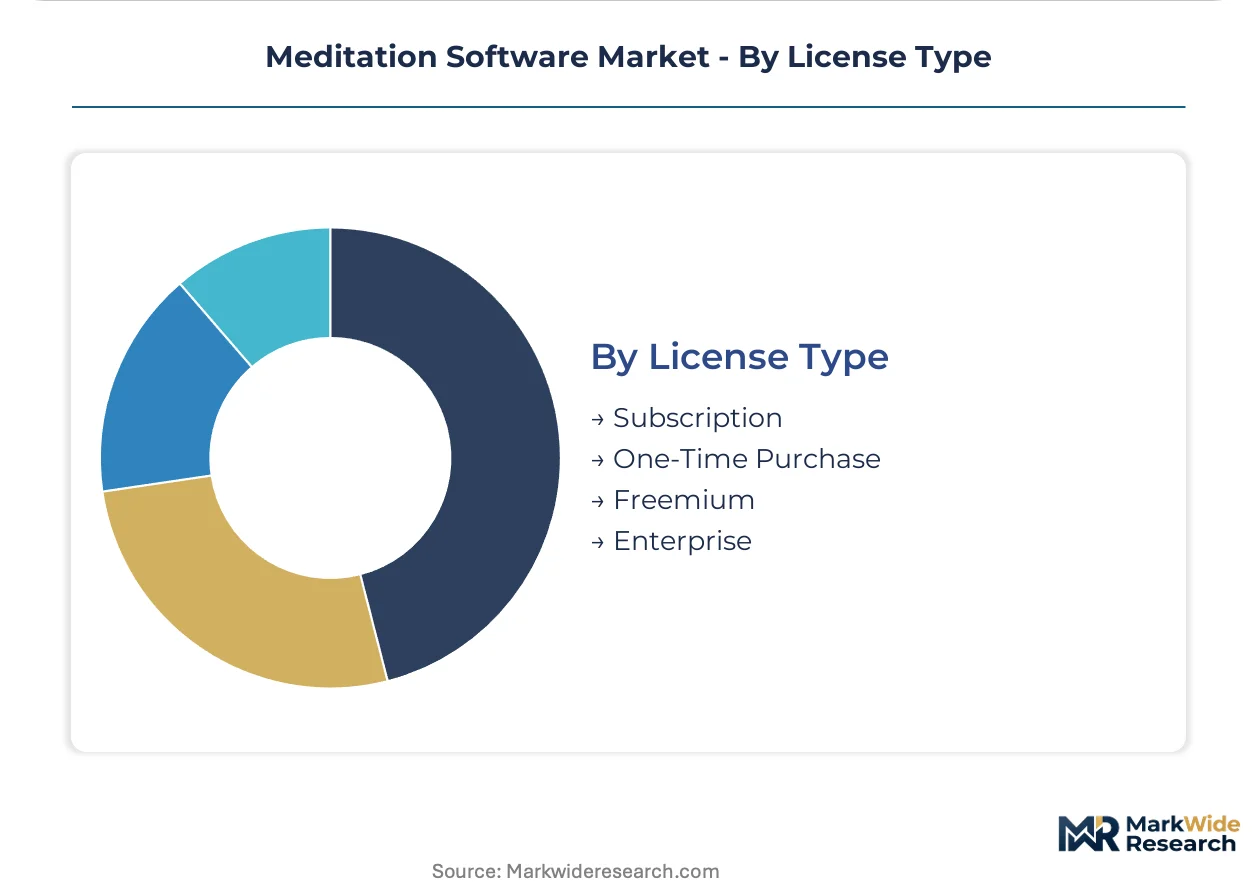
- Freemium:Unlimited basic content with premium feature gates dominates user acquisition funnels, converting 3-8% of active users to paid tiers according to industry benchmarks.
- Enterprise:Multi-year contracts with single sign-on integration and custom content generation capture expanding margin pools as HR technology budgets consolidate.
- Subscription:Monthly and annual recurring revenue models sustain direct-to-consumer platforms facing churn pressure from free substitutes.
- One-Time Purchase:Perpetual licenses for downloadable content persist in markets with limited payment infrastructure or privacy-conscious user segments.
Freemium anchors user acquisition. Enterprise is expanding most quickly as procurement centralization favors vendors with administrative tooling and compliance certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based meditation platforms export subscription services and enterprise licensing to corporate buyers across Canada, the United Kingdom, and Australia, establishing North America-to-Anglosphere corridors as the dominant trade flow in digital wellness delivery.
United States
Fortune 500 HR departments centralize wellness technology procurement under single-vendor contracts, while FDA digital therapeutics pathways create compliance thresholds for clinical-grade positioning. HIPAA encryption mandates drive vendor investment in health data infrastructure. San Francisco Bay Area clusters host engineering teams building biometric feedback integrations for wearable device compatibility.
Germany
Corporate wellness adoption lags US penetration by several years, creating whitespace for platform localization and BfArM digital health application classification. The DiGA framework enables statutory health insurance reimbursement for prescribed meditation apps. Berlin and Munich host emerging health technology clusters where vendors pursue regulatory pre-certification ahead of market entry.
United Kingdom
National Health Service pilot programs integrate mental health apps into primary care pathways, while employer-sponsored wellness spending grows among London-based financial services firms. GDPR consent management requirements shape data architecture decisions for US platforms entering the market. The Cambridge-Oxford corridor attracts health economics research teams supporting clinical validation studies.
Australia
Workplace mental health regulations mandate employer provision of psychological support tools, driving enterprise procurement of meditation platforms. The Therapeutic Goods Administration maintains evolving oversight of software-based mental health interventions. Sydney and Melbourne host Asia-Pacific headquarters for international vendors seeking regional distribution hubs.
Japan
Corporate stress management programs expand among manufacturing and technology employers, while aging demographics create demand for cognitive wellness applications. The Ministry of Economy, Trade and Industry promotes digital health adoption through regulatory sandbox programs. Tokyo clusters concentrate platform localization teams adapting content for cultural preferences in guided meditation delivery.
Meditation Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where celebrity-branded consumer applications and enterprise-focused wellness platforms occupy distinct competitive tiers. The market consolidates around vendors with HIPAA-compliant infrastructure and administrative dashboard capabilities for HR technology integration. Three archetypes dominate: direct-to-consumer subscription platforms, corporate wellness specialists, and community-driven freemium models. Competitive moves concentrate on generative AI content generation and biometric data integration partnerships with wearable device manufacturers.
Within the direct-to-consumer tier, Calm and Headspace exemplify scale-driven positioning through audio library depth and celebrity partnership strategies. Insight Timer occupies a distinct archetype as a community-driven platform monetizing through teacher networks rather than proprietary content production. These three anchors demonstrate how vendor strategy diverges between content ownership models and user-generated ecosystem approaches.
| Leading Market Players |
|---|
| Calm |
| Headspace |
| Insight Timer |
| Aura Health |
| Simple Habit |
| Meditopia |
| Ten Percent Happier |
| Breethe |
| Smiling Mind |
| Others |
Pricing and Supply Chain Analysis
Elastic cloud capacity utilization across United States hyperscale regions runs above baseline during morning and evening meditation peaks, compressing infrastructure margins for mid-size platforms while amplifying pricing power for vendors with reserved compute commitments and enterprise-grade SLAs.
Pricing Analysis
The generational pricing gap between static-content platforms and AI-native competitors is widening as personalized audio generation reduces per-session production costs by orders of magnitude. Three-tier pricing structure across premium, standard, and economy levels dominates direct-to-consumer segments, with premium tiers anchored by celebrity-voiced content and biometric integration. Price differentiation rests on clinical validation status and HIPAA certification tier, with FDA digital therapeutics pathway positioning commanding substantial premiums. Cost compression in the freemium tier is intensifying because YouTube and podcast substitutes establish zero-price anchors. Individual consumers show highest price sensitivity, while United States Fortune 500 HR departments demonstrate lowest sensitivity due to consolidated wellness technology budgets.
Supply Chain Analysis
Extended payment terms from enterprise wellness buyers in the United States are forcing platform vendors to rely on supply-chain finance facilities for cloud infrastructure pre-commitments. Geographic supply concentrates in the United States for hyperscale compute, Ireland and Germany for GDPR-compliant data residency, and India for engineering talent pools. Raw material dependencies include cloud compute credits, neural text-to-speech licensing, and wearable device API access. Single-source vulnerability runs through AWS and Azure concentration for low-latency audio delivery. Distribution runs through direct-to-consumer app stores, corporate benefits administration platforms, and health insurance reimbursement channels in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of health economics expertise capable of designing randomized controlled trials for FDA digital therapeutics submissions is constraining competitive entry and consolidating advantage among well-capitalized platforms.
For Market Incumbents: Pre-empt regulatory capture by accelerating BfArM pre-certification in Germany before competitors localize content, while deepening backward integration into proprietary biometric algorithm development to reduce wearable API dependency. Vertical integration into clinical validation pipelines defends margin position against AI-native entrants with lower content production costs. For New Entrants and Emerging Players: Establish a beachhead in the underpenetrated German corporate wellness segment by pursuing DiGA classification for statutory health insurance reimbursement, bypassing the saturated United States direct-to-consumer battlefield. White-label partnerships with wellness centers offer lowest customer acquisition friction for capital-constrained entrants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise wellness platforms with HIPAA-compliant infrastructure and administrative dashboard capabilities. Long-term viability across the analysis window favors vendors with clinical validation pipelines and multi-region data residency architecture. The signal to watch is BfArM approval velocity as an indicator of European market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Pipeline Investment | Randomized trial portfolios unlock FDA 510(k) clearance and DiGA reimbursement eligibility. |
| Biometric Integration Partnership | Wearable API access enables adaptive meditation protocols that improve retention metrics. |
| Enterprise SSO Deployment | Single sign-on integration captures centralized HR technology procurement contracts. |
| Generative AI Content Engine | Neural audio synthesis compresses per-session production costs while enabling mass personalization. |
| German Localization and BfArM Submission | DiGA classification opens statutory health insurance reimbursement channels. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with platform product executives, corporate benefits administrators, health economics researchers, and wearable device partnership leads; and secondary validation against SEC filings, App Annie engagement metrics, hyperscaler capex disclosures, and BfArM digital health application databases. Bottom-up triangulation across deployment models and end-user segments was cross-checked against top-down market sizing.
Forecast inputs considered cloud infrastructure scaling patterns, employer wellness budget consolidation trajectories, and regulatory approval velocity across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size, clinical claim intensity, and regional reimbursement framework. CAGRs were derived from elasticity-adjusted adoption curves and enterprise contract value expansion. AI content generation cost curves and biometric integration penetration served as technology-specific forecast inputs.
Sensitivities concentrate around FDA digital therapeutics classification timelines and German DiGA approval rates. Forecasts reflect assumptions about employer wellness mandate expansion and cloud infrastructure cost trajectories. Macroeconomic contraction affecting HR technology budgets, regulatory divergence between HIPAA and GDPR enforcement, or breakthrough wearable form factors would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
App Uninstall Software Market
Software & Services
App Development Software Market
Software & Services
Global Portal Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Stock Footage Software Market
Software & Services
Global Application Release Automation Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Global Mobile Application Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Global Remote Work Software Market
Software & Services
Video Converter Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Global Business Card Software Market