
 Microwave Safe Utensils Market | 2026-2036
Microwave Safe Utensils Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Safe Utensils Market Foresight
Aftermarket replacement cycles for branded containers is narrowing as consumers shift toward premium durable sets. Tupperware Brands Corporation leverages direct-selling networks to sustain recurring revenue from repeat buyers. Corelle Brands anchors its position through tempered-glass technology leadership in North American retail channels. Rubbermaid Incorporated competes aggressively in commercial foodservice with stackable designs optimized for institutional kitchens.
Microwave safe utensils are engineered food-contact articles designed to withstand electromagnetic heating at 2.45 GHz without thermal deformation, chemical migration, or structural failure, typically manufactured through injection molding of polypropylene, borosilicate glass forming, or platinum-cured silicone vulcanization to serve residential meal preparation and commercial foodservice reheating. Bowls and lids command the largest volume share due to leftovers storage frequency, while BPA-Free plastic dominates unit economics in mass retail. Silicone segments are expanding fastest among health-conscious households seeking collapsible, freezer-to-microwave convenience.
The US FDA regulates food-contact substance notifications under 21 CFR, while the EU enforces migration testing through Commission Regulation (EU) No 10/2011 and REACH substance restrictions, collectively elevating compliance costs for non-compliant exporters. China's SAMR implements GB standards for plastic food containers that domestic producers like Fujian Singyee Group navigate with localized testing infrastructure. Stakeholders must monitor evolving state-level chemical disclosure requirements and material substitution timelines to preserve market access.
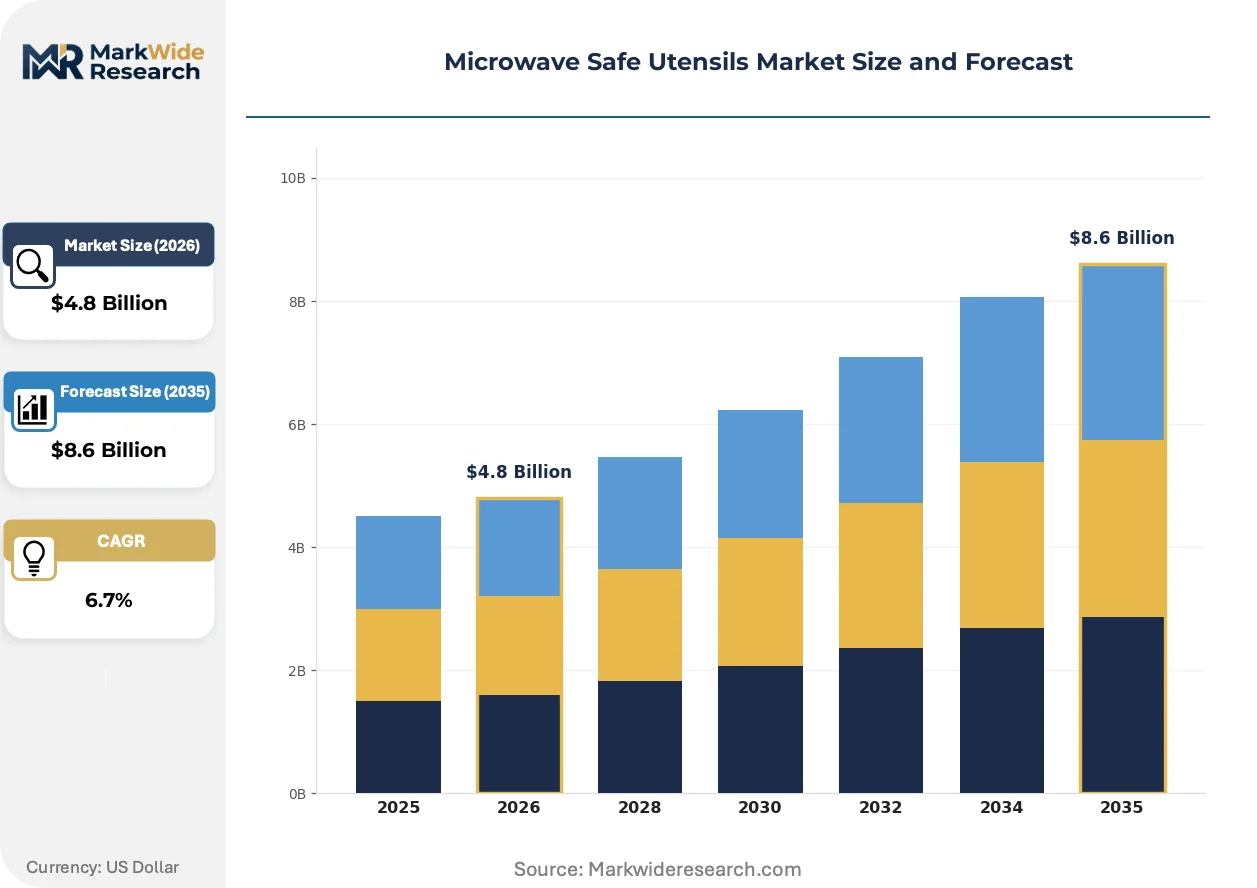
Market Dynamics
Migration testing requirements under FDA 21 CFR and EU Commission Regulation 10/2011 are compressing margins for commodity-grade polypropylene exporters while rewarding certified borosilicate glass and platinum-cured silicone specialists with shelf access in premium retail channels.
Growth Catalysts
- Cloud kitchen proliferation:Ghost kitchen operators in China and the United States are standardizing heat-resistant container procurement for delivery-optimized reheating workflows.
- REACH substance restrictions:EU ECHA's tightening migration limits for phthalates and bisphenols are accelerating substitution toward medical-grade silicone and tempered glass across European foodservice.
- Platinum-cured silicone vulcanization:Advanced curing chemistry enables freezer-to-microwave collapsible designs that capture health-conscious household demand in Japan and South Korea.
Market Restraints
- Propylene feedstock volatility:Crude-linked resin pricing squeezes injection molders in Southeast Asia who lack backward integration into petrochemical supply.
- Testing infrastructure concentration:GB standard compliance for China's SAMR requires localized laboratory certification that foreign exporters struggle to access without domestic partnerships.
- Technical performance ceiling:Polypropylene's thermal deformation threshold near 120°C limits high-temperature applications where ceramic or glass maintains structural integrity.
Strategic Opportunities
- Indian urban household penetration:FSSAI's emerging food-contact standards create first-mover advantage for compliant borosilicate glass entrants in tier-1 and tier-2 cities.
- Smart packaging convergence:Integration of RFID temperature logging with microwave-safe bases addresses food safety liability in institutional healthcare catering.
- Direct-to-consumer subscription:Replenishment models for modular container systems bypass traditional retail slotting fees and capture lifetime value from organized pantry households.
Industry Challenges
- Migration testing talent scarcity:Analytical chemists capable of simulant-based extraction studies under EU 10/2011 protocols command premium compensation that mid-tier manufacturers struggle to afford.
- Multi-jurisdiction certification timelines:Sequential FDA notification, EU testing, and GB compliance extend product launch cycles by eighteen to twenty-four months for novel polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Safe Utensils Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bowls, Plates, Cups, Lids Material: Plastic, Glass, Silicone, Ceramics Feature: Stackable, BPA-Free, Non-Toxic, Heat-Resistant End User: Households, Restaurants, Hotels, Catering Services |
| Companies Covered | Tupperware Brands Corporation, Corelle Brands, Rubbermaid Incorporated, LocknLock Co., Sistema Plastics Limited, Nordic Ware, Anchor Hocking Company, Pyrex, Fujian Singyee Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Safe Utensils Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are compressing the viable product lifecycle for legacy food-contact polymers while opening premium positioning for certified alternatives with embedded traceability features.
Platinum-cured silicone formulations with embedded mineral fillers are achieving thermal stability beyond 200°C while maintaining flexibility across freeze-thaw cycles. Quick-service restaurant chains in California and Texas are piloting collapsible bowl systems for delivery-optimized packaging reduction. This chemistry is rendering obsolete rigid polypropylene clamshells in prepared meal segments where space-efficient storage drives logistics economics.
EU EFSA is expanding migration testing protocols to cover nanoparticle additives and recycled content streams under revised Commission Regulation frameworks. Industrial consequence includes mandatory pre-market notification for any food-contact article containing greater than 0.1% engineered nanomaterial. German and French retailers are responding by demanding extended supplier documentation that traces additive provenance through polymer compounding stages.
Subscription-based container replenishment is displacing episodic retail purchasing among organized pantry households in Shanghai and Seoul. Direct-to-consumer platforms bundle modular bowl-lid systems with recipe-aligned portion sizing. This behavioral shift concentrates buyer power with curated brands capable of sustaining engagement through mobile application integration rather than shelf visibility alone.
Microwave Safe Utensils Market Segmentation
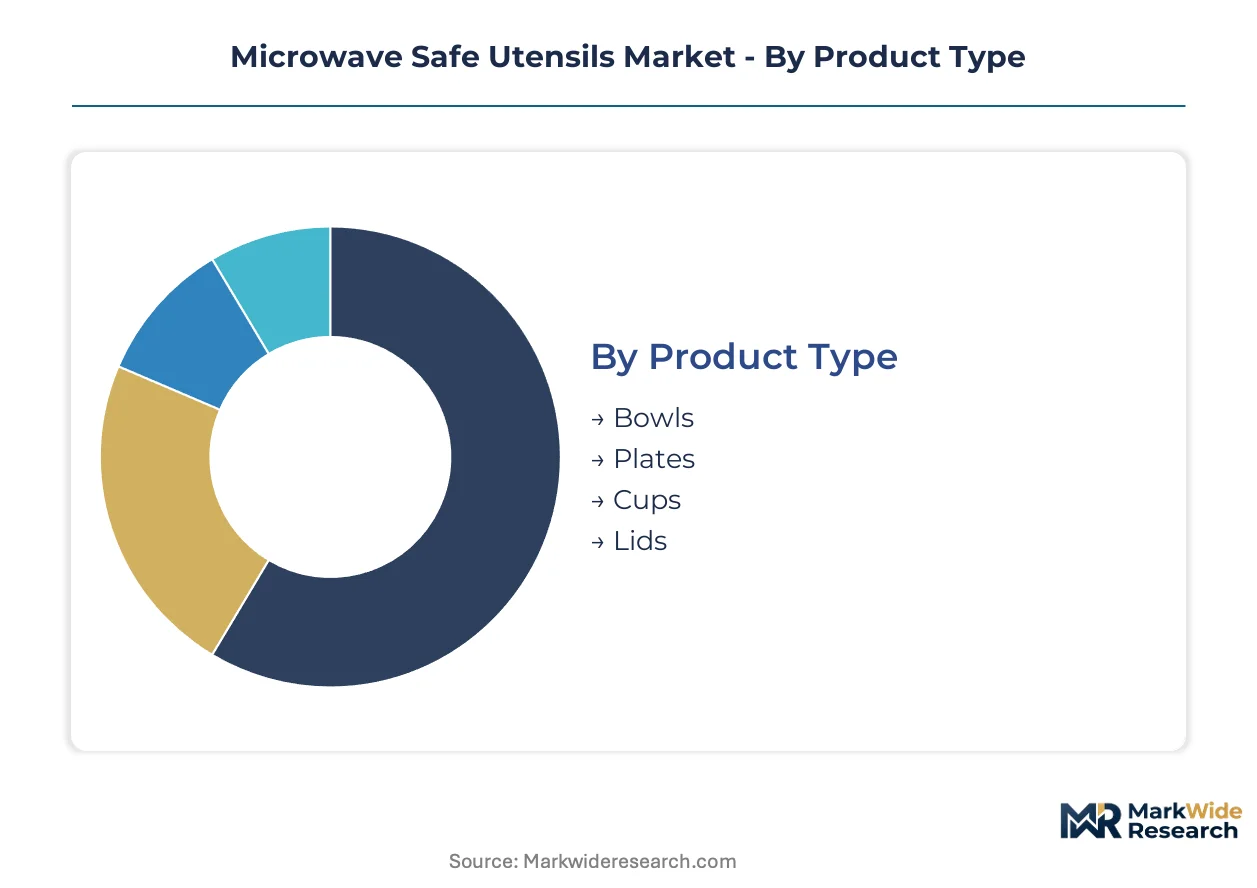
Segmentation in microwave safe utensils reveals divergent replacement cycles and margin structures across material grades and institutional channels. Manufacturers configure warranty terms and replenishment programs differently for each cluster, with direct-to-consumer models capturing lifetime value from organized pantry households while commercial contracts prioritize volume durability.
Product Type:
After-sales intensity varies sharply across container geometries, with lidded systems requiring more frequent seal replacement than open vessels and driving recurring revenue attachment rates.
- Bowls:Deep-walled vessels engineered from polypropylene or borosilicate glass for soup and grain reheating. Demand clusters in Chinese urban households where leftovers storage frequency exceeds Western norms, though thermal deformation thresholds near 120°C limit polypropylene adoption for high-temperature applications.
- Lids:Precision-molded sealing components with silicone gaskets or snap-fit polypropylene rims designed for vapor retention and splatter prevention. Cloud kitchen operators in California and Texas standardize procurement of vented lid systems for delivery-optimized workflows, with replacement cycles compressing as operators prioritize hygiene protocols.
- Plates:Flat-bottomed serving surfaces with raised edges, typically tempered glass or ceramic for table-ready presentation. Japanese households favor shallow-profile designs for microwave-to-table convenience.
- Cups:Cylindrical vessels with handle attachments, dominated by borosilicate glass for beverage reheating applications. South Korean consumers drive demand for insulated double-wall constructions.
Bowls and lids command the largest combined share; momentum sits with lidded systems as delivery logistics expand.
Material:
Cost tier stratification separates medical-grade certified suppliers from commodity resin molders, with compliance investments creating defendable margin positions at the premium end.
- Plastic:Injection-molded polypropylene homopolymer and copolymer formulations, BPA-free certified under FDA 21 CFR and EU 10/2011. Mass retail channels in the United States and Germany concentrate procurement here due to unit economics, though propylene feedstock volatility squeezes Southeast Asian molders lacking backward integration.
- Glass:Tempered soda-lime or borosilicate compositions formed through thermal strengthening processes. EU EFSA's tightening migration limits accelerate substitution toward glass in French and German foodservice, with Corelle Brands anchoring technology leadership in North American retail.
- Silicone:Platinum-cured vulcanized elastomers with mineral fillers achieving thermal stability beyond 200°C. Health-conscious households in Japan and South Korea drive steepest expansion trajectory for collapsible freezer-to-microwave designs that optimize pantry storage density.
- Ceramics:Glazed stoneware and porcelain with microwave-safe metallic oxide formulations. Limited to specialty retail due to weight and fragility constraints in logistics.
Plastic retains volume leadership; silicone gains share fastest on health positioning and space-efficient design.
Feature:
Application requirements dictate feature bundling, with institutional buyers prioritizing stackability for storage density while residential purchasers emphasize chemical safety certifications.
- BPA-Free:Formulations excluding bisphenol-A and related analogs, certified through third-party migration testing. Mass-market retail in the United States treats this as table stakes, with California state-level disclosure requirements extending to bisphenol-S and F alternatives.
- Stackable:Geometric nesting designs with interlocking rims or tapered walls for vertical storage efficiency. Rubbermaid Incorporated optimizes this feature for institutional kitchen clients in the United States where space constraints drive procurement decisions.
- Heat-Resistant:Thermal performance specifications exceeding standard polypropylene thresholds, typically borosilicate glass or advanced silicone compositions. Quick-service restaurant chains specify this for high-temperature reheating workflows.
- Non-Toxic:Broad-safety marketing claims encompassing heavy metal, phthalate, and volatile organic compound exclusions. Shanghai and Seoul direct-to-consumer platforms bundle this messaging with recipe-aligned subscription offerings.
BPA-Free dominates unit economics; heat-resistant specifications expand most quickly in commercial channels.
End User:
Customer type determines contract structure, with households engaging through episodic retail or subscription replenishment while institutional buyers negotiate multi-year supply agreements with technical performance clauses.
- Households:Residential meal preparation and leftovers storage, spanning single-person urban apartments to multi-generational homes. Tupperware Brands Corporation leverages direct-selling networks to sustain recurring revenue from repeat buyers in this segment across the United States and emerging Asian markets.
- Restaurants:Quick-service and casual dining operators requiring heat-resistant containers for back-of-house reheating and front-of-house service. Ghost kitchen proliferation in China and the United States standardizes procurement for delivery-optimized workflows, with procurement teams prioritizing stackable designs for storage density.
- Hotels:Full-service and limited-service hospitality properties with in-room dining and banquet operations. Brand standards in international chains mandate uniform container specifications across property portfolios.
- Catering Services:Institutional foodservice contractors for healthcare, education, and corporate facilities. RFID temperature logging integration addresses food safety liability in healthcare catering applications in Germany and the United States.
Households represent the largest addressable base; restaurants climb fastest on cloud kitchen expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese buyers prioritize unit economics in mass retail channels, while Japanese and South Korean households absorb premium pricing for certified silicone and borosilicate glass. European procurement teams enforce compliance premiums that compress margins for non-certified exporters.
China
Urban household penetration and cloud kitchen proliferation drive volume demand. SAMR's GB standards for plastic food containers mandate localized testing infrastructure that domestic producers like Fujian Singyee Group navigate with captive laboratory certification. Manufacturing scales concentrate in Fujian and Guangdong provinces where injection molding clusters serve both domestic consumption and export markets.
United States
Quick-service restaurant chains and ghost kitchen operators standardize heat-resistant container procurement for delivery-optimized workflows. FDA 21 CFR notifications for food-contact substances elevate compliance costs for novel polymer formulations. Procurement decisions cluster in California and Texas where state-level chemical disclosure requirements extend beyond federal baselines.
Germany
EU EFSA's tightening migration limits for phthalates and bisphenols accelerate substitution toward tempered glass and medical-grade silicone. ECHA's REACH substance restrictions mandate extended supplier documentation tracing additive provenance. Retailer concentration in North Rhine-Westphalia and Bavaria drives harmonized compliance standards across European supply chains.
Japan
Health-conscious households absorb premium pricing for platinum-cured silicone with collapsible freezer-to-microwave designs. METI's consumer safety standards align with international migration testing protocols while preserving domestic certification requirements. Demand concentrates in the Kanto region around Tokyo where pantry storage density optimization drives product selection.
South Korea
Double-wall borosilicate glass constructions for beverage reheating capture household preference. MFDS food-contact regulations enforce testing parity with EU and US standards. Subscription-based container replenishment models pioneered in Seoul concentrate buyer power with curated direct-to-consumer platforms.
Microwave Safe Utensils Market Competitive Landscape
Capability concentration sits with specialized silicone and glass manufacturers; scale advantage sits with diversified housewares conglomerates. The market structures around three tiers: premium certified specialists, mass-market resin molders, and direct-selling network operators. Strategic archetypes include compliance-forward material science leaders, logistics-optimized foodservice suppliers, and engagement-driven subscription platforms. Dominant competitive moves encompass vertical integration into platinum-cured silicone chemistry and partnerships with cloud kitchen operators for standardized procurement.
Within the direct-selling network tier, Tupperware Brands Corporation occupies a position exemplifying recurring revenue attachment through repeat buyer relationships. Among diversified housewares manufacturers, Corelle Brands and Rubbermaid Incorporated represent contrasting archetypes—one anchoring technology leadership in tempered-glass retail channels, the other optimizing stackable designs for institutional foodservice contracts. These three companies illustrate how divergent channel strategies—direct sales, premium retail, and commercial supply—coexist without direct price competition.
| Leading Market Players |
|---|
| Tupperware Brands Corporation |
| Corelle Brands |
| Rubbermaid Incorporated |
| LocknLock Co. |
| Sistema Plastics Limited |
| Nordic Ware |
| Anchor Hocking Company |
| Pyrex |
| Fujian Singyee Group |
| Others |
Supply & Pricing Matrix
Propylene feedstock volatility determines both pricing tier spreads and supply chain shape in microwave safe utensils, compressing margins for Southeast Asian injection molders lacking backward integration while rewarding certified borosilicate glass and platinum-cured silicone specialists with shelf access in premium retail channels.
Pricing Analysis
After-sales revenue from replacement lids and seal components drives lifetime value across the product portfolio. Pricing stratifies across premium certified tiers, standard BPA-free formulations, and economy polypropylene grades, with differentiation anchored in FDA 21 CFR and EU 10/2011 certification levels versus commodity resin sourcing. Cost compression in mass retail channels is intensifying because propylene price volatility squeezes non-integrated molders. Quick-service restaurant procurement teams exhibit lowest price sensitivity, prioritizing heat-resistant specifications and stackable designs for storage density over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Fujian Singyee Group and domestic producers in China's Fujian and Guangdong provinces, where injection molding clusters serve both domestic consumption and export markets. Raw material sourcing draws from Saudi Arabian and Chinese petrochemical feedstock, Korean specialty silicone suppliers, and German borosilicate glass technology licensors. Single-source vulnerability sits with platinum-cured silicone vulcanization equipment concentrated among Japanese and German machinery suppliers. Distribution runs through mass retail channel slotting fees in the United States and Germany, direct-selling networks in emerging Asian markets, and institutional foodservice contracts with technical performance clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment platforms are reconfiguring microwave safe utensils as a recurring-revenue ecosystem, with interoperability between modular container systems and recipe-aligned mobile applications displacing episodic retail purchasing among organized pantry households.
For Market Incumbents: Entrench certification leadership through captive laboratory investment for FDA 21 CFR and EU 10/2011 migration testing, shortening multi-jurisdiction launch cycles that currently extend eighteen to twenty-four months for novel polymer formulations. Anchor supply relationships with cloud kitchen operators in California and Texas through standardized procurement contracts for heat-resistant container systems, defending against emerging direct-to-consumer subscription platforms that bypass traditional retail slotting fees.
For New Entrants and Emerging Players: Pursue white-space positioning in Indian tier-1 and tier-2 cities where FSSAI's emerging food-contact standards create first-mover advantage for compliant borosilicate glass entrants ahead of established mass-market resin molders. Target healthcare catering services in Germany and the United States with RFID temperature logging integration, addressing food safety liability through smart packaging convergence rather than competing on commodity container economics.
For Investors and Strategic Acquirers: EU EFSA's expansion of migration testing protocols to cover nanoparticle additives and recycled content streams reshapes the acquisition landscape toward certified specialists with embedded traceability capabilities and extended supplier documentation systems. Long-term viability favors platinum-cured silicone chemistry leaders and tempered-glass technology holders over commodity polypropylene molders exposed to feedstock volatility. Monitor ECHA REACH substance restriction timelines for phthalates and bisphenols as inflection indicators accelerating substitution toward medical-grade certified alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Silicone Chemistry Investment | Captures health-conscious household demand in Japan and South Korea through freezer-to-microwave collapsible designs. |
| Cloud Kitchen Operator Partnership | Standardizes heat-resistant container procurement for delivery-optimized reheating workflows in California and Texas. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and captures lifetime value from organized pantry households in Shanghai and Seoul. |
| RFID Temperature Logging Integration | Addresses food safety liability in institutional healthcare catering applications across Germany and the United States. |
| Captive Migration Testing Laboratory | Accelerates multi-jurisdiction certification timelines for FDA 21 CFR and EU 10/2011 compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR food-contact substance notifications, EU EFSA migration testing protocols, and SAMR GB standards documentation. Primary interviews engaged product development directors at diversified housewares manufacturers, procurement leads at quick-service restaurant chains, regulatory affairs specialists at silicone chemistry suppliers, and category buyers at German and French retail concentration points. Secondary validation drew from customs and trade data, SEC 10-K filings of listed housewares conglomerates, and hospital procurement databases for institutional catering applications. Bottom-up demand modeling triangulated against top-down macroeconomic consumption indicators across the analysis window.
Forecast inputs span material-grade segmentation across polypropylene, borosilicate glass, platinum-cured silicone, and ceramic compositions; end-user channel splits between household, restaurant, hotel, and catering service procurement; and regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for substitution dynamics and compliance cost trajectories. Industry-specific inputs include propylene feedstock price volatility assumptions and cloud kitchen penetration rates in China and the United States.
Sensitivities concentrate around EU EFSA migration testing protocol revisions, propylene resin price volatility, and state-level chemical disclosure requirement expansions beyond federal baselines. Quarterly review of ECHA REACH substance restriction announcements, SAMR GB standard updates, and FSSAI food-contact regulation finalization timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Saudi Arabia Cookware Market
Household Items
Water Purifier Bottle Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Commercial Locker Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Non-Stick Cookware Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Commercial Lawnmower Market
Household Items
Germany Digital Showers Market
Household Items
Dryer Sheets Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Ironing Boards Market
Household Items
Home Scales Market
Household Items
United States Smart Shower Market
Household Items
Hydralight Lanterns Market