
 Europe Cookware Market | 2026-2036
Europe Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cookware Market Foresight
CE marking under the EU Food Contact Materials Regulation is redrawing competitive boundaries for cookware suppliers entering European distribution. Groupe SEB leverages its multi-brand architecture to dominate premium and mid-tier shelf space across French and German retailers. Zwilling J.A. Henckels AG anchors its position through specialized forged-aluminum and clad-stainless production lines engineered for induction efficiency. Fiskars Group competes by extending its design-led portfolio into ceramic-reinforced non-stick surfaces that meet tightened emissions protocols.
Europe cookware encompasses vessels and containers fabricated from metals, ceramics, or composite substrates, typically featuring base thicknesses of 3.0–5.5 mm for thermal uniformity and compatibility with induction cooktops generating oscillating magnetic fields at 20–25 kHz. These products serve residential food preparation and commercial kitchen operations requiring precise temperature control and repeated thermal cycling. Stainless steel cookware occupies the largest revenue pool due to durability and professional kitchen preference, while cast iron segments command premium pricing through enameled finishes and artisan positioning. Non-stick material categories face structural pressure as REACH restrictions on perfluorinated compounds force reformulation investments, redirecting margin pools toward ceramic and diamond-reinforced alternatives.
EMA food contact guidelines, REACH chemical registration requirements, and the EU Green Deal's circular economy action plan collectively dictate coating compositions, recyclability targets, and market access documentation for cookware placed on European markets. ECHA's evolving restrictions on PFAS substances are forcing manufacturers to validate alternative slip-resistant surfaces through migration testing protocols. Stakeholders must monitor regulatory consultation timelines and pre-emptively qualify substitute materials before substance bans disrupt existing supply arrangements.
Market Dynamics
REACH restrictions on perfluorinated compounds are forcing cookware manufacturers across France, Germany, and Italy to abandon legacy non-stick chemistries and rebuild coating supply chains from raw material qualification through finished goods testing.
Growth Catalysts
- EU Green Deal circular economy mandates:Recyclability targets for food contact materials are accelerating stainless steel and cast iron demand across Northern European hospitality supply chains.
- Induction cooktop penetration:Restaurant kitchens in Milan, Paris, and Berlin are replacing gas-fired equipment with magnetic-field systems requiring ferromagnetic base compatibility.
- Professional kitchen renovation cycles:Premium hospitality operators in Spain and the Netherlands are upgrading to clad-stainless and copper-core vessels for thermal precision.
Market Restraints
- Raw material cost volatility:Nickel and chromium price swings squeeze margin on 18/10 stainless steel production lines serving mid-tier retail channels.
- Coating supply concentration:Ceramic and sol-gel non-stick alternatives depend on specialized German and French chemical compounders with limited qualified capacity.
- Technical performance gaps:PFAS-free surfaces currently deliver shorter service life in high-cycle commercial environments versus legacy fluoropolymer coatings.
Strategic Opportunities
- Polish and Romanian retail expansion:Underpenetrated mass-market channels in Central European capitals present volume growth for induction-compatible aluminum lines.
- Smart cookware integration:Temperature-sensing handles and Bluetooth-enabled base sensors are converging with home automation systems in German and Nordic residential markets.
- Refurbishment and re-coating services:Circular economy business models targeting professional kitchen operators in Belgium and Austria extend asset life and capture recurring revenue.
Industry Challenges
- Migration testing backlog:ECHA substance evaluation queues delay new coating chemistry approvals by 18-24 months, freezing product pipeline decisions.
- Induction compatibility certification:EN 12983-1 testing protocol complexity requires specialized laboratory partnerships that smaller manufacturers struggle to secure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cookware Market |
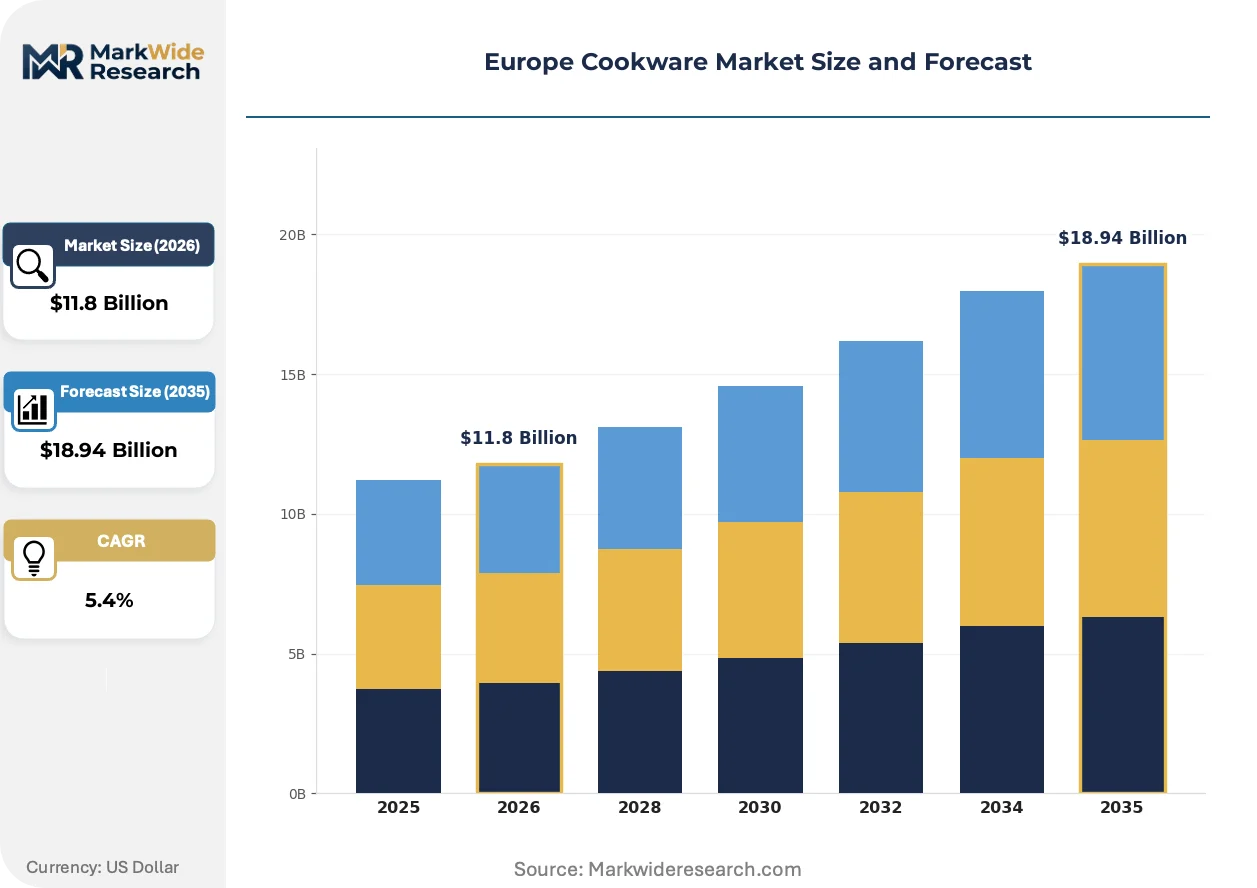
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frypans, Cookware Sets, Saucepans, Dutch Ovens Material: Stainless Steel, Cast Iron, Non-Stick, Copper End User: Households, Restaurants, Catering Services, Hotels Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale |
| Companies Covered | Le Creuset Group AG, Fiskars Group, Groupe SEB, De Buyer Industries, BergHOFF Worldwide, Meyer Group Ltd., Fissler GmbH, Scanpan A/S, Zwilling J.A. Henckels AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cookware Market Shifts & Advancements
Coating chemistry and base material engineering are diverging sharply as regulatory pressure and thermal performance demands pull product development in opposing directions across European manufacturing centers.
Clad-stainless construction with aluminum or copper cores is bifurcating the premium segment. Professional kitchens in Lyon and Hamburg are specifying 5-ply bases for heat distribution precision. Residential buyers in Scandinavia follow this specification pattern, compressing demand for single-material vessels and elevating forged-aluminum with stainless steel disc bases into the mid-tier.
ECHA's evolving PFAS restriction roadmap is eliminating fluoropolymer coatings from food contact applications by 2026. Manufacturers serving French and Italian markets are pivoting to ceramic-reinforced and diamond-particle surfaces. Commercial operators in Spain face accelerated replacement cycles as existing inventory loses regulatory grandfathering protection.
Direct-to-restaurant procurement platforms are disintermediating traditional hospitality supply distributors in Germany and the Netherlands. Purchasing managers at multi-location operators now specify exact base thickness and alloy composition through digital portals. This pattern concentrates in metropolitan clusters where procurement centralization and sustainability documentation requirements intersect.
Europe Cookware Market Segmentation
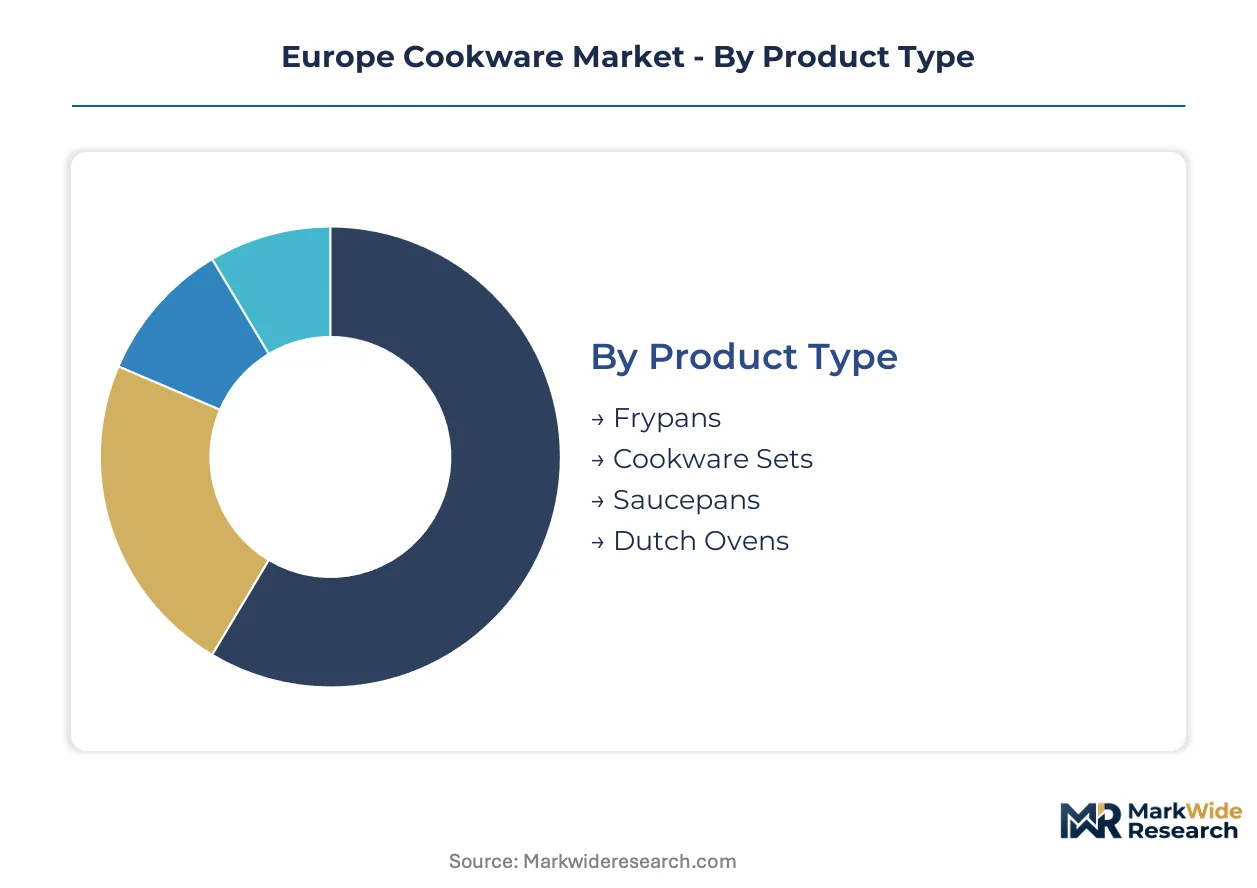
Europe's cookware segmentation reflects divergent channel economics and regulatory pressures across product categories. Material composition and end-use specifications determine margin pools, while distribution access dictates which segments reach scale in German retail corridors versus Italian hospitality supply chains.
Product Type:
Channel mix varies sharply by vessel function—specialty retailers dominate premium cookware sets while online platforms capture volume in single-piece frypan replacements across metropolitan France and Germany.
- Frypans:Single-piece aluminum and clad-stainless constructions with 3.0–4.5 mm base thickness dominate residential replacement cycles. German online retailers and French hypermarket chains capture the highest transaction velocity for induction-compatible disc-base models serving apartment kitchens in Berlin and Paris.
- Cookware Sets:Multi-piece configurations with coordinated lids and nesting profiles target gift purchasing and first-home establishment. Northern Italian specialty stores and Dutch department store concessions concentrate demand for 5-ply stainless sets with copper cores.
- Saucepans:Medium-capacity vessels with pour spouts and helper handles serve sauce reduction and liquid heating tasks. Restaurant supply distributors in Lyon and Hamburg specify these for back-of-house operations requiring precise temperature modulation.
- Dutch Ovens:Enameled cast iron vessels with self-basting lid designs occupy artisan positioning in premium channels. Belgian and Austrian cookware boutiques concentrate demand for heritage-brand pieces with lifetime warranty positioning.
By volume, frypans lead through frequent replacement and single-piece purchasing flexibility. By growth pace, cookware sets are climbing the fastest as induction cooktop adoption drives coordinated vessel upgrades.
Material:
Cost tier stratification separates professional-grade specifications from mass-market accessibility, with raw material volatility compressing margins differently across each substrate category.
- Stainless Steel:Austenitic 18/10 and 18/8 alloys with aluminum or copper cores deliver thermal uniformity and dishwasher durability. German restaurant kitchens and Scandinavian residential buyers specify these for regulatory compliance with EU Food Contact Materials standards and extended service life requirements.
- Cast Iron:Enameled and bare ferrous vessels with 4.5–6.0 mm wall thickness retain heat for slow-cooking applications. French and Belgian hospitality operators favor these for bistro-style service presentations and oven-to-table versatility.
- Non-Stick:Ceramic-reinforced and sol-gel surfaces replacing legacy fluoropolymer coatings under REACH PFAS restrictions. Spanish and Italian manufacturers are pivoting production lines to meet ECHA compliance deadlines.
- Copper:2.5–3.0 mm hammered or rolled substrates with stainless steel lining for reactive food compatibility. Premium restaurant kitchens in Paris and Milan specify these for sauce work requiring instantaneous thermal response.
By installed base, stainless steel dominates across commercial and residential segments. By value expansion, copper is gaining share fastest as professional kitchen renovation cycles elevate performance specifications.
End User:
Customer type determines purchasing cadence and specification complexity, with commercial operators demanding documentation trails that residential buyers rarely require.
- Households:Individual and family purchasers selecting vessels for daily meal preparation across gas, electric, and induction cooktops. German and Dutch online platforms and mass-market retailers serve this segment with mid-tier aluminum and entry stainless offerings.
- Restaurants:Independent and multi-location operators specifying NSF-certified or CE-marked equipment for health authority compliance. French and Italian full-service restaurants drive demand for clad-stainless and copper-core vessels with induction base compatibility.
- Catering Services:Mobile and event-focused operators requiring lightweight, high-volume vessels for transport and rapid turnaround. Central European catering hubs in Poland and the Czech Republic concentrate procurement for aluminum disc-base lines.
- Hotels:Property-level and chain-wide purchasing managers sourcing for breakfast service, room service, and banquet operations. Spanish and Portuguese resort properties specify enameled cast iron and stainless steel for buffet presentation durability.
By transaction volume, households lead through replacement frequency and single-piece purchasing. By contract value, hotels are expanding most quickly as chain-wide standardization programs consolidate vendor relationships.
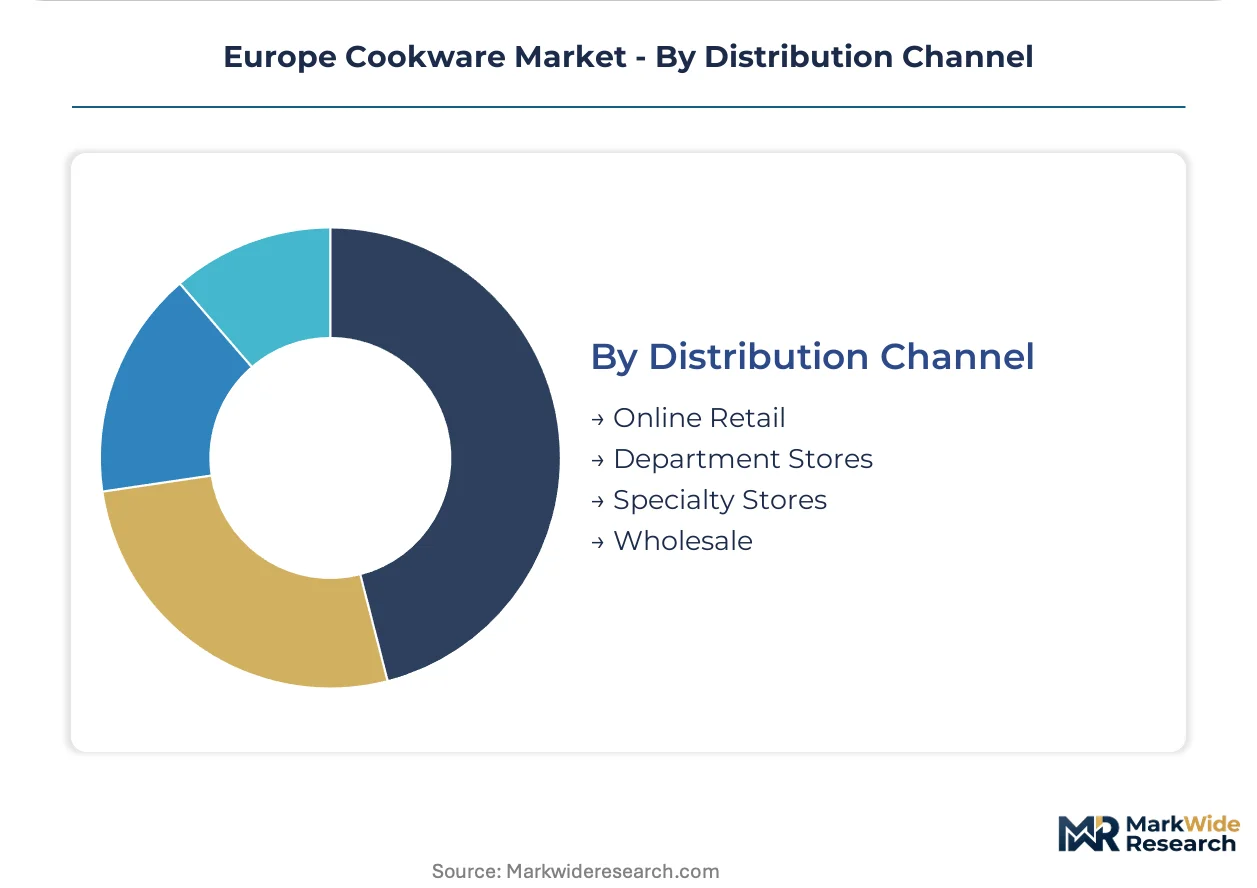
Distribution Channel:
Supply concentration in specialized logistics networks creates divergent access economics for manufacturers serving retail versus commercial end points.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with search-filtered specification comparison. German and Nordic consumers use these channels for induction compatibility verification and price transparency.
- Department Stores:Concession-based and owned-buyer operations with curated brand portfolios and gift-oriented merchandising. French and British department store cookware halls concentrate premium and bridge-price positioning.
- Specialty Stores:Independent cookware boutiques and regional chains with staff-assisted selling and product demonstration capabilities. Northern Italian and Belgian specialty retailers emphasize artisan brands and heritage manufacturing narratives.
- Wholesale:Hospitality supply distributors and cash-and-carry operators serving restaurant and hotel procurement managers. Dutch and German foodservice wholesalers dominate this channel with catalog-based specification selling and volume pricing tiers.
By revenue contribution, wholesale leads through commercial contract scale. By channel expansion, online retail is gaining share fastest as specification transparency and induction compatibility tools reduce purchase risk for residential buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's circular economy mandates and ECHA's PFAS restrictions are redrawing procurement patterns across national markets. Member states with concentrated hospitality sectors and advanced retail infrastructure capture disproportionate value migration toward induction-compatible and certified-sustainable cookware lines.
Germany
Metropolitan retail corridors in Berlin, Munich, and Hamburg drive premium cookware turnover through department store concessions and specialized kitchen boutiques. ECHA's chemical registration requirements under REACH force domestic distributors to validate coating compositions before shelf placement. The North Rhine-Westphalia industrial cluster anchors forged-aluminum and clad-stainless production serving both residential and commercial channels.
France
Lyon and Paris restaurant kitchens specify copper-core and enameled cast iron vessels for sauce precision and tableside presentation. ANSM food contact material guidelines complement EU-wide EMA standards, tightening documentation requirements for imported cookware. The Auvergne-Rhône-Alpes region concentrates heritage-brand manufacturing with artisan positioning and lifetime warranty programs.
Italy
Milan's hospitality supply chains and Northern Italian specialty retailers elevate 5-ply stainless and ceramic-reinforced non-stick specifications. EU Green Deal recyclability targets accelerate demand for bare cast iron and uncoated stainless across Lombardy and Piedmont commercial operators. Emilia-Romagna's metalworking tradition supports forged-aluminum disc-base production for induction conversion.
Spain
Barcelona and Madrid hotel chains consolidate vendor relationships for buffet presentation and banquet service equipment. Accelerated PFAS restriction timelines eliminate grandfathering protection for existing fluoropolymer-coated inventory, forcing replacement cycles. Andalusian resort properties specify enameled cast iron durability for high-turnover breakfast service operations.
Netherlands
Amsterdam and Rotterdam procurement centralization platforms disintermediate traditional hospitality distributors through direct-to-restaurant digital portals. CSRD sustainability disclosure requirements extend to supply chain documentation for cookware vendors serving Dutch foodservice operators. The Randstad logistics hub enables rapid fulfillment of specification-heavy commercial contracts.
Europe Cookware Market Competitive Landscape
Player mix skews toward diversified multi-brand conglomerates controlling premium and mid-tier shelf space across French and German retail. Consolidation pressure intensifies as REACH compliance costs and coating reformulation investments favor scaled manufacturers with captive laboratory partnerships. Two strategic archetypes dominate: heritage European fabricators with artisan positioning and Nordic design-led specialists with ceramic-reinforced portfolios. Competitive moves concentrate on portfolio diversification into smart cookware integration and geographic expansion into underpenetrated Central European mass-market channels.
Within the heritage European tier, Le Creuset Group AG and Zwilling J.A. Henckels AG exemplify forged-metal and clad-stainless archetypes with established induction-efficiency credentials. Groupe SEB occupies a position spanning multi-brand architecture across price tiers. Fiskars Group represents the design-led specialist archetype with ceramic-reinforced surface portfolios. These three anchors illustrate how regulatory pressure and thermal performance demands pull product development toward divergent material engineering strategies.
| Leading Market Players |
|---|
| Le Creuset Group AG |
| Fiskars Group |
| Groupe SEB |
| De Buyer Industries |
| BergHOFF Worldwide |
| Meyer Group Ltd. |
| Fissler GmbH |
| Scanpan A/S |
| Zwilling J.A. Henckels AG |
| Others |
Supply & Pricing Matrix
Ninety-day coating qualification queues at ECHA-registered laboratories concentrate pricing power with German and French compounders possessing pre-approved ceramic formulations, compressing margins for mid-tier manufacturers while elevating premiums on REACH-compliant inventory.
Pricing Analysis
Certification level under EU Food Contact Materials Regulation creates the primary spread between premium and mass-market tiers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by induction efficiency rating and migration test documentation depth. Cost compression in entry stainless steel lines is intensifying because nickel and chromium spot volatility feeds directly into 18/10 alloy input costs. Household purchasers through German online platforms exhibit highest price sensitivity, while Lyon and Paris restaurant procurement managers prioritize thermal precision specifications over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Asian-sourced aluminum disc substrates, extending replenishment cycles for Central European distributors serving Polish and Romanian retail expansion. Manufacturing gravity centers on Germany's North Rhine-Westphalia cluster, Italy's Emilia-Romagna metalworking belt, and France's Auvergne-Rhône-Alpes heritage fabrication region. Raw material flows draw from Indonesian nickel ore, Ukrainian ferrochrome, and Chinese aluminum billet. Single-source vulnerability concentrates in specialized German ceramic coating compounders with limited qualified capacity. Distribution runs through Dutch foodservice wholesalers and French hypermarket chains for commercial and residential endpoints respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refurbishment and re-coating services for professional kitchen operators represent a recurring-revenue layer expanding faster than vessel hardware sales, as circular economy mandates in Belgium and Austria extend asset replacement cycles.
For Market Incumbents: Consolidate laboratory partnerships for ECHA migration testing to secure coating chemistry pipeline priority, and deepen captive supply of forged-aluminum disc bases through backward integration into North Rhine-Westphalia production clusters. Regulatory shift toward accelerated PFAS elimination threatens inventory grandfathering protection for existing fluoropolymer-coated stock. For New Entrants and Emerging Players: Differentiate on smart cookware integration with Bluetooth-enabled temperature sensors for German and Nordic residential automation systems. Polish and Romanian mass-market channels present the most penetrable geography for induction-compatible aluminum lines. Direct-to-restaurant digital procurement platforms offer the strongest go-to-market angle against entrenched Dutch and German hospitality distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming cookware divisions lacking REACH compliance infrastructure. Long-term viability across the analysis window favors manufacturers with captive ceramic coating capabilities and Central European retail channel control. Watch ECHA consultation timelines for PFAS restriction scope expansion as the inflection signal for coating chemistry asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | REACH PFAS compliance secures market access across French and Italian distribution. |
| Induction Base Certification | EN 12983-1 testing unlocks premium positioning in German metropolitan retail corridors. |
| Smart Cookware Integration | Bluetooth sensor deployment captures automation convergence in Nordic residential markets. |
| Refurbishment Service Launch | Circular economy models capture recurring revenue from Belgian hospitality operators. |
| Central European Retail Expansion | Polish and Romanian channel development addresses underpenetrated mass-market demand. |
Research Methodology
Initial hypotheses were tested against primary input from cookware brand managers, restaurant procurement directors, specialty retail buyers, and coating chemistry R&D leads and refined through secondary validation against customs records, EU Food Contact Materials compliance databases, and hospitality supply distributor catalog data. Bottom-up vessel shipment analysis triangulated with top-down spending estimates from national retail associations and commercial foodservice trade groups.
Variance decomposition across material substrate, end-use segment, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis weighted by revenue contribution. Forecast inputs incorporated induction cooktop penetration curves by metropolitan cluster and ECHA regulatory consultation timeline probabilities.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation and REACH enforcement intensity would require recalibration. Forecasts reflect assumptions regarding coating chemistry substitution rates and nickel price volatility persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Basin, Bowl, and Cup Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Mosquito Repellent Candles Market
Household Items
Air Humidifier Market
Household Items
Countertop Market
Household Items
Japan Digital Showers Market
Household Items
Car Air Freshener Market
Household Items
Liquid Hand Soap Market
Household Items
Sleeping Pods Market
Household Items
Latex Mattress Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
North America Glassware Market
Household Items
Wax Removal Aids Market
Household Items
Electric Brooms Market
Household Items
Global Laptop Tables Market