
 United States Commercial Bathroom Products Market | 2026-2036
United States Commercial Bathroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Bathroom Products Market Insights
Connected sensor technology is rewriting specification standards across the commercial bathroom category. Kohler Co. leverages embedded IoT diagnostics to sustain premium positioning in enterprise hospitality installations. Moen Incorporated anchors mid-market specification channels through consolidated distributor relationships. American Standard Brands competes on scale in institutional retrofit programs where replacement cycles dominate new construction.
Commercial bathroom products encompass water-delivery fixtures, sanitary ware, and accessory systems engineered for high-frequency public use, typically fabricated from vitreous china, brass alloys, or engineered polymers with flow rates constrained by federal and state efficiency mandates. These installations serve hygiene, accessibility, and water-conservation functions across non-residential built environments. Faucets command the largest share of product-type value pools due to sensor-actuated electrification and ongoing brass input cost volatility. Online delivery mode penetration is accelerating fastest among small-facility buyers seeking specification bypass and compressed lead times. Enterprise facility size segments concentrate margin capture through multi-site national account structures and captive maintenance contracts.
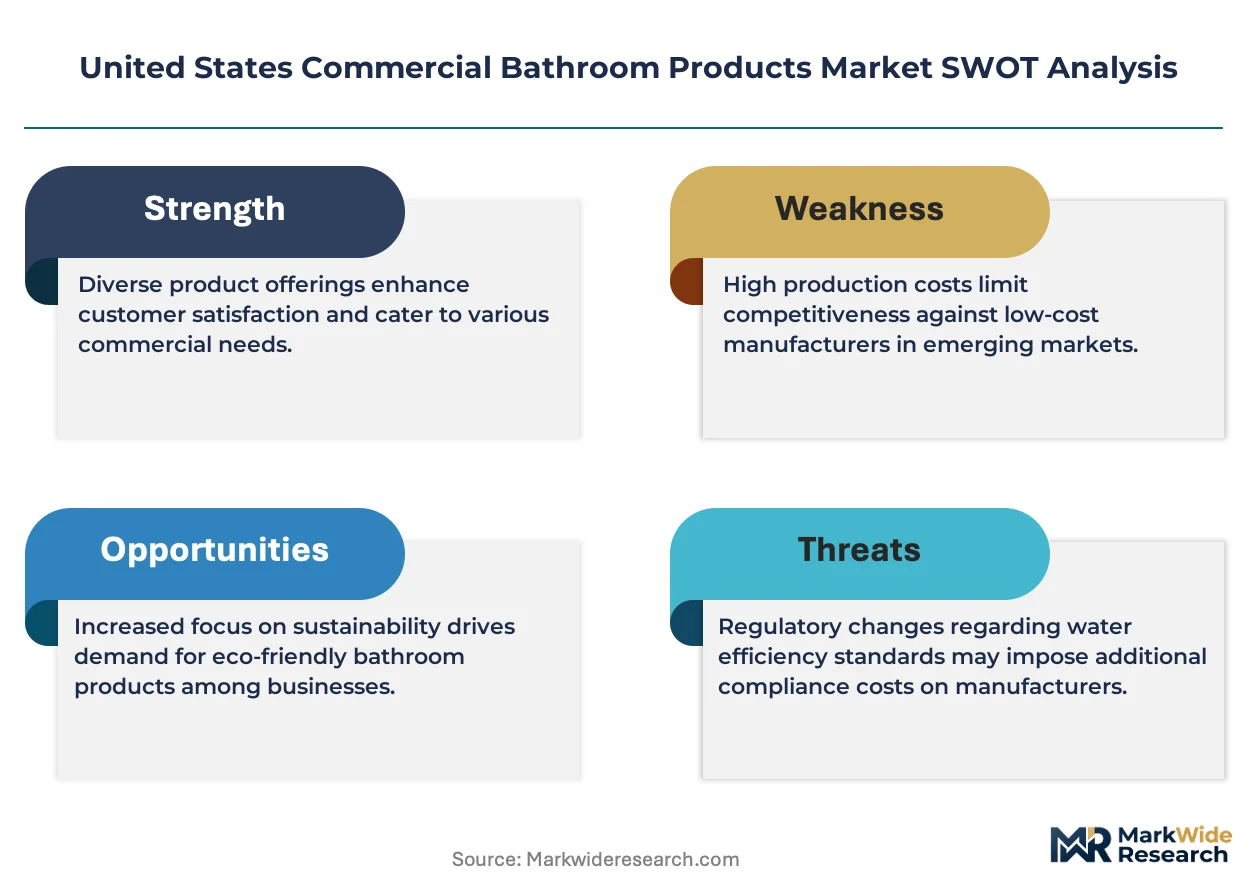
EPA WaterSense labeling and California Energy Commission Title 20 standards constrain maximum flow rates for faucets and showerheads, forcing manufacturers to redesign valve architectures or forfeit access to the largest state economy. ADA compliance requirements under DOJ enforcement extend grab-bar mounting specifications and clear-floor-space dimensions across all public accommodation renovations. Stakeholders must monitor state-level efficiency preemption battles and the trajectory of federal infrastructure spending for public facility modernization to calibrate capacity and specification pipelines.
Market Dynamics
Connected sensor technology is compressing replacement cycles and forcing fixture manufacturers to embed IoT diagnostics or forfeit specification-grade hospitality contracts to digitally native competitors.
Growth Catalysts
- Hospitality Renovation Cycles:Premium hotel chains are accelerating bathroom refresh timelines from seven-year to four-year intervals, pulling specification-grade sensor faucets and smart mirrors into guest room standards.
- California Title 20 Mandates:The state's efficiency standards now cap faucet flow rates at 1.2 gallons per minute, compelling manufacturers to redesign valve architectures for compliance or exit the nation's largest state market.
- Texas Urban Construction Corridors:Dallas-Fort Worth and Houston metropolitan permit volumes remain elevated, concentrating demand for commercial-grade vitreous china and brass fixtures in multi-tenant office and healthcare developments.
Market Restraints
- Brass Input Cost Volatility:Copper and zinc alloy price swings squeeze margin stability for faucet manufacturers who cannot pass through material adjustments in fixed-price municipal contracts.
- Supply Concentration in Guangdong:Ceramic cartridge and sensor module sourcing remains concentrated in southern Chinese manufacturing zones, exposing lead time vulnerability to port congestion and customs processing delays.
- Technical Limitation in Low-Flow Performance:EPA WaterSense flow rate ceilings compromise user satisfaction in high-traffic airport and stadium installations where perceived water pressure drives complaint volume.
Strategic Opportunities
- Florida Hospitality Zones:Orlando and Miami-Dade hotel construction pipelines remain robust, creating white space for specification-grade fixture providers with captive maintenance contracting capabilities.
- IoT-Converged Predictive Maintenance:Sensor-embedded fixtures transmitting usage data to facility management platforms enable subscription-based service revenue streams beyond hardware margins.
- Federal Infrastructure Spending:Bipartisan public facility modernization allocations channel through GSA procurement channels, favoring domestic manufacturers with Buy America Act certification.
Industry Challenges
- Certification Timeline Compression:EPA WaterSense and California Energy Commission approval cycles now span 14-18 months, delaying product launches and freezing engineering resources on legacy platform updates.
- Integration Complexity with Building Automation:BACnet and LonWorks protocol fragmentation forces fixture manufacturers to maintain multiple firmware branches, inflating QA overhead and field service training costs.
- Skilled Installer Scarcity:Union plumbing apprenticeships have not scaled to meet electrified fixture demand, creating bottlenecks for sensor-actuated valve deployment in union-governed metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Bathroom Products Market |
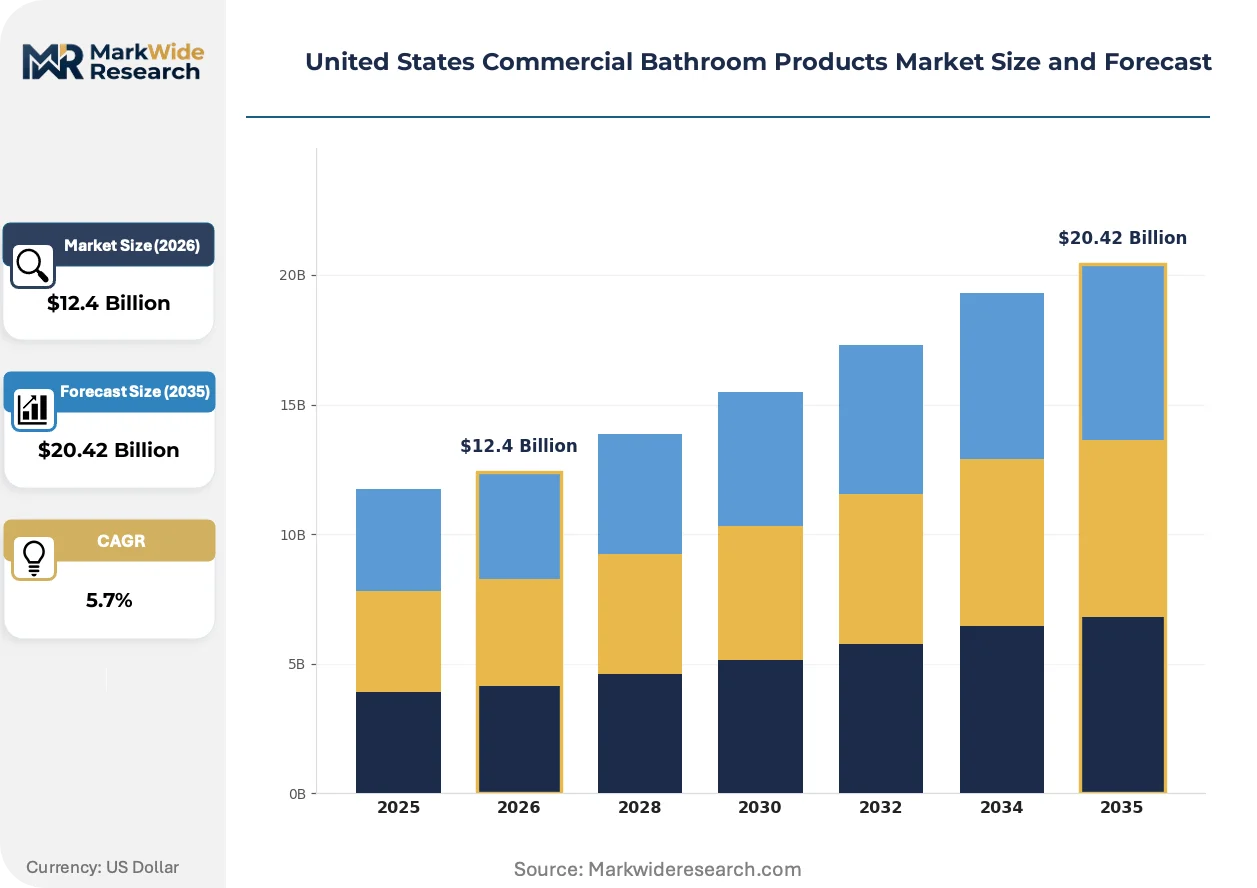
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Urinals, Faucets, Sinks Delivery Mode: Online, Retail, Direct Sales, Distributor End User: Hotels, Offices, Restaurants, Hospitals Facility Size: Small, Medium, Large, Enterprise |
| Companies Covered | Kohler Co., Moen Incorporated, American Standard Brands, Masco Corporation, LIXIL Group Corporation, TOTO Ltd., Delta Faucet Company, Grohe AG, Hansgrohe SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Bathroom Products Market Trends and Innovations
Sensor-actuated electrification is redefining fixture specification standards while efficiency mandates compress allowable flow rates and procurement patterns fragment across channel types.
Embedded IoT diagnostics is digitizing commercial bathroom infrastructure. Solid-state sensors now monitor valve wear, water temperature consistency, and usage patterns in real time. Enterprise hospitality chains are mandating these capabilities in new construction specifications. This technology is digitizing maintenance scheduling from reactive break-fix models to predictive intervention, compressing downtime liability and reshaping supplier-facility manager relationships.
EPA WaterSense certification requirements now extend to 37 states through voluntary adoption and procurement preference policies. The program's maximum flow rate specifications have forced brass valve manufacturers to invest in aerator and laminar flow engineering. Faucet product lines face the steepest redesign burden, with institutional retrofit programs representing the highest-volume compliance pathway for manufacturers with legacy inventory exposure.
Small-facility buyers are bypassing traditional specification channels through direct e-commerce procurement. Independent restaurants, boutique hotels, and municipal satellite offices now source ADA-compliant grab bars and sensor faucets through distributor-aligned digital platforms. This channel disintermediation concentrates in Texas and Florida metropolitan corridors where compressed lead times outweigh specification consulting value for sub-50-fixture orders.
United States Commercial Bathroom Products Market Segmentation
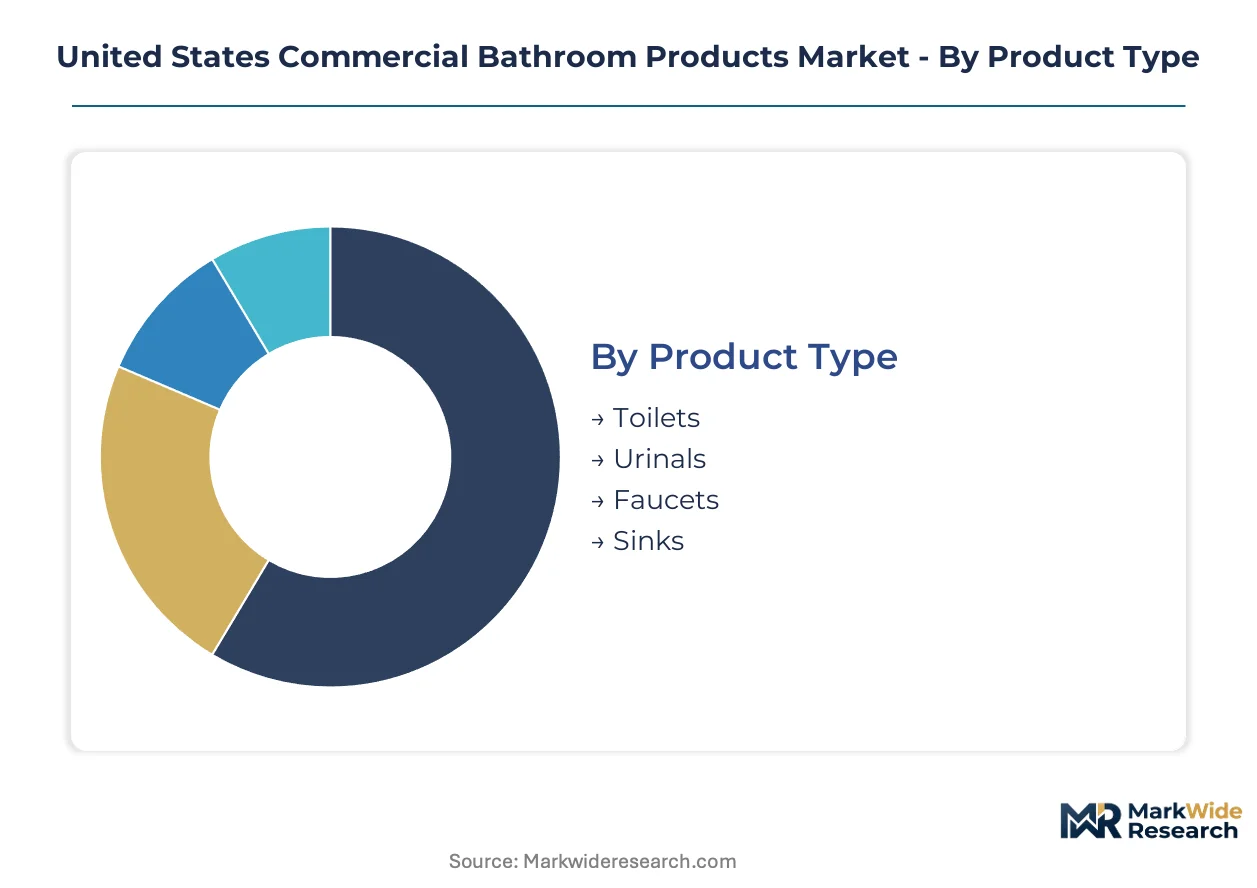
Segmentation in the United States commercial bathroom products market reveals divergent replacement rhythms and specification pathways. Cycle times vary dramatically across product categories, from annual faucet refreshes in high-traffic hospitality to decade-long toilet installations in institutional settings. Understanding these temporal patterns enables manufacturers to calibrate inventory and channel investments.
Product Type:
Faucets turn over fastest in renovation cycles, while toilets and urinals persist longest in building infrastructure. Replacement frequency directly shapes margin capture and specification access for each category.
- Faucets:Sensor-actuated brass fixtures dominate specification-grade procurement, with electrified valve architectures now standard in enterprise hospitality. Demand concentrates in Texas urban corridors and Florida hospitality zones where four-year renovation cycles compress replacement timelines.
- Toilets:Vitreous china fixtures with EPA WaterSense certification face extended replacement windows in institutional settings. California Title 20 mandates and ADA compliance requirements drive specification decisions in public facility retrofits.
- Urinals:Waterless and ultra-low-flow designs serve high-traffic stadium and airport installations.
- Sinks:Engineered polymer and solid-surface basins support accessibility mandates in healthcare and senior living.
Faucets anchor the volume base while sensor-enabled variants gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates specification-intensive channels from price-transparent alternatives. Premium installation support commands margin premiums that direct digital procurement cannot replicate.
- Distributor:Consolidated relationships with regional plumbing supply houses dominate mid-market specification. Moen Incorporated leverages these channels for institutional retrofit programs where contractor loyalty and technical support drive repeat procurement.
- Direct Sales:National account structures serve enterprise facility managers with captive maintenance contracts. Kohler Co. deploys direct teams for multi-site hospitality chains requiring IoT-integrated predictive service.
- Online:Digital platforms accelerate penetration among small-facility buyers in Texas and Florida metropolitan corridors.
- Retail:Big-box and specialty showroom channels address emergency replacement demand.
Distributor relationships capture the largest revenue pool while online delivery expands most quickly among sub-50-fixture orders.
End User:
Application-specific performance requirements segment demand across hygiene sensitivity, traffic intensity, and aesthetic specification. Each vertical imposes distinct regulatory and operational constraints on fixture selection.
- Hotels:Premium chains mandate sensor faucets and smart mirrors in four-year refresh cycles. Orlando and Miami-Dade construction pipelines concentrate specification-grade demand for connected fixtures with embedded diagnostics.
- Hospitals:Infection control protocols and ADA compliance drive specification for touchless activation and antimicrobial surfaces. Federal infrastructure spending through GSA procurement channels favors domestic manufacturers with Buy America Act certification.
- Offices:Multi-tenant developments in Dallas-Fort Worth and Houston drive volume for standard-grade vitreous china and brass fixtures.
- Restaurants:Independent operators bypass specification channels through e-commerce platforms.
Hotels generate the highest specification intensity while hospitals deliver the most stable replacement revenue.
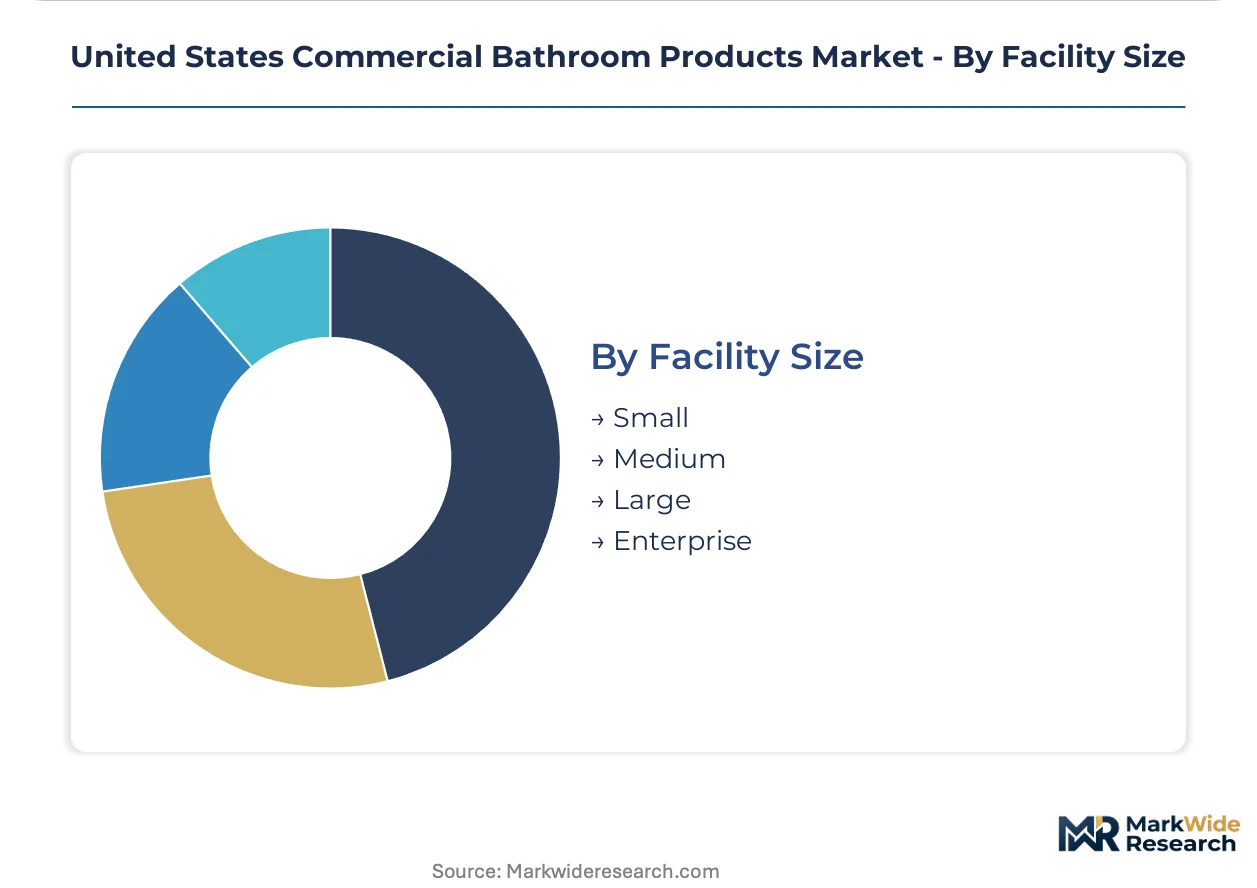
Facility Size:
Customer type determines procurement complexity and service attachment potential. Scale thresholds separate transactional hardware sales from integrated facility management relationships.
- Enterprise:Multi-site national accounts concentrate margin capture through predictive maintenance subscriptions and captive service contracts. IoT-converged platforms enable recurring revenue streams beyond initial hardware deployment.
- Large:Single-campus healthcare and educational institutions balance specification consulting against total cost of ownership. Union plumbing apprenticeships create installation bottlenecks for electrified fixtures in metropolitan markets.
- Medium:Regional hotel chains and municipal facilities represent the highest-volume compliance pathway for WaterSense-certified inventory.
- Small:Independent restaurants and boutique hotels source through distributor-aligned digital platforms.
Enterprise facilities command the deepest service relationships while small facilities drive channel disintermediation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese ceramic cartridge and sensor module exports feed directly into Texas and Florida distribution hubs, creating supply-chain dependencies that shape domestic specification timelines and inventory positioning across the southern United States.
Texas Urban Corridors
Dallas-Fort Worth and Houston metropolitan permit volumes sustain elevated demand for commercial-grade vitreous china and brass fixtures in multi-tenant office and healthcare developments. EPA WaterSense certification requirements govern specification decisions for institutional retrofit programs. San Antonio-Austin corridor construction activity concentrates mid-market distributor relationships where contractor loyalty drives repeat procurement.
California
Title 20 efficiency mandates cap faucet flow rates at 1.2 gallons per minute, forcing manufacturers to redesign valve architectures for compliance or exit the nation's largest state economy. Los Angeles and San Francisco Bay Area hospitality renovations accelerate sensor-actuated fixture replacement cycles. Sacramento regulatory preemption battles create compliance uncertainty for multi-state product lines.
Florida Hospitality Zones
Orlando and Miami-Dade hotel construction pipelines concentrate specification-grade demand for connected fixtures with embedded diagnostics. Four-year refresh cycles compress replacement timelines for premium hotel chains. Tampa-St. Petersburg healthcare facility expansions drive ADA-compliant grab bar and accessibility fixture procurement through GSA channels.
Northeast Corridor
New York Metro and Boston metropolitan markets exhibit extended replacement windows for institutional toilet installations in educational and government facilities. Union plumbing apprenticeships create installation bottlenecks for electrified fixtures in these union-governed markets. Philadelphia-Baltimore corridor municipal satellite offices increasingly bypass specification channels through distributor-aligned digital platforms.
Pacific Northwest
Seattle and Portland metropolitan areas prioritize water-conservation specifications in municipal and commercial construction, extending voluntary EPA WaterSense adoption beyond federal minimums. Oregon and Washington state procurement preference policies favor efficiency-certified fixtures in public facility modernization. Boise-Spokane corridor emerging construction activity represents incremental volume for standard-grade product lines.
United States Commercial Bathroom Products Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: integrated plumbing conglomerates with captive manufacturing, specialized fixture manufacturers with specification-grade positioning, and volume-oriented suppliers serving institutional retrofit channels. Strategic archetypes include IoT-converged platform builders, efficiency-mandate compliance specialists, and distributor-consolidated mid-market players. Dominant competitive moves encompass backward integration into ceramic cartridge production and predictive maintenance service bundling.
Within the integrated conglomerate tier, Kohler Co. and LIXIL Group Corporation exemplify scale-driven archetypes with multi-brand portfolio architectures. Moen Incorporated anchors mid-market specification channels through consolidated distributor relationships. American Standard Brands occupies a position emphasizing institutional retrofit program execution where replacement cycles dominate new construction procurement.
| Leading Market Players |
|---|
| Kohler Co. |
| Moen Incorporated |
| American Standard Brands |
| Masco Corporation |
| LIXIL Group Corporation |
| TOTO Ltd. |
| Delta Faucet Company |
| Grohe AG |
| Hansgrohe SE |
| Others |
Pricing and Supply Chain Analysis
Guangdong ceramic cartridge export dependency determines both specification-grade pricing spreads and domestic inventory positioning across southern distribution hubs. Brass input cost volatility feeds directly into valve architecture redesign budgets, compressing margin stability for manufacturers locked into fixed-price municipal contracts.
Pricing Analysis
Sensor-actuated electrification pricing gaps separate legacy brass fixtures from IoT-embedded diagnostics and next-generation predictive maintenance platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and captive service bundling. Cost compression in mid-market specification channels is intensifying because distributor consolidation limits pass-through flexibility for material adjustments. Small-facility buyers exhibit highest price sensitivity, while enterprise hospitality chains prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Export-control regime limitations on semiconductor components for sensor modules constrain Guangdong manufacturing flows to domestic assembly facilities. Ceramic cartridge and brass alloy sourcing centers on China, Vietnam, and domestic foundry operations. Supply chain risk manifests as single-source vulnerability for EPA WaterSense-certified valve architectures. Distribution runs through consolidated regional plumbing supply houses with national account overlay for enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected sensor penetration in commercial hospitality sits at early-cycle expansion, with four-year renovation pull-through accelerating specification-grade fixture adoption ahead of replacement baselines.
For Market Incumbents: Entrench specification-grade positioning through backward integration into ceramic cartridge production and captive predictive maintenance service bundling. Digitally native competitors threaten enterprise hospitality contracts without embedded IoT diagnostics. Certification investment in EPA WaterSense and California Title 20 compliance creates channel control leverage against mid-market challengers. For New Entrants and Emerging Players: Build out white-space presence in Florida hospitality zones where Orlando and Miami-Dade construction pipelines concentrate demand for connected fixtures with embedded diagnostics. Small-facility e-commerce procurement represents the most penetrable channel, bypassing traditional specification relationships through distributor-aligned digital platforms with compressed lead times. For Investors and Strategic Acquirers: EPA WaterSense timeline compression reshapes the acquisition landscape toward compliance-specialist manufacturers with frozen engineering resources on legacy platform updates. Five-to-ten-year viability favors targets with Buy America Act certification positioning for federal infrastructure spending through GSA procurement channels. Monitor state-level efficiency preemption battles as the signal for capacity and specification pipeline recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Diagnostics Platform Launch | Enterprise hospitality chains now mandate embedded sensor capabilities in new construction specifications. |
| Ceramic Cartridge Backward Integration | Captive supply of Guangdong-dependent components reduces lead time vulnerability to port congestion. |
| Predictive Maintenance Service Bundling | Subscription revenue streams extend margin capture beyond initial hardware deployment in enterprise accounts. |
| California Title 20 Compliance Investment | Valve architecture redesign secures access to the nation's largest state economy under efficiency mandates. |
| Small-Facility E-Commerce Channel Expansion | Digital platform penetration captures sub-50-fixture orders bypassing traditional specification consulting. |
Research Methodology
Initial hypotheses were tested against primary input from facility management executives, plumbing contractor operations leads, distributor procurement managers, and regulatory compliance officers and refined through secondary validation. Facility management executives provided enterprise account specification requirements and predictive maintenance adoption timelines. Plumbing contractor operations leads supplied installation bottleneck data for electrified fixtures in union-governed markets. Distributor procurement managers detailed channel consolidation patterns and small-facility digital platform penetration. Regulatory compliance officers clarified EPA WaterSense and California Energy Commission approval cycle dynamics. Secondary sources included EPA WaterSense certification databases, California Energy Commission Title 20 filings, U.S. Census construction permit data, and GSA procurement records. Bottom-up product-type volume estimates and top-down end-user spending patterns were triangulated for convergence.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, delivery mode, end-user vertical, and facility size tier. CAGRs were derived from replacement cycle compression rates and efficiency mandate adoption curves. Industry-specific forecast inputs incorporated hospitality renovation timeline acceleration and federal infrastructure spending allocation trajectories through GSA channels.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digitally native sensor-embedded fixture entrants would shift outcomes. Material shifts in California regulatory preemption battles or federal infrastructure spending authorization levels would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Ceramic Travel Mug Market
Household Items
Trash Can Market
Household Items
Mosquito Trap Market
Household Items
Coffin and Cremation Urn Market
Household Items
Mexico Cookware Market
Household Items
Leaf Blower Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Residential Air Purifiers Market
Household Items
Tiki Torch Market
Household Items
Aromatherapy Diffuser Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
Non-Stick Cookware Market
Household Items
US Air Fresheners Market
Household Items
Alarm Clocks Market
Household Items
Toilet Brush Market