
 Toilet Cistern Blocks Market | 2026-2036
Toilet Cistern Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Cistern Blocks Market Analytics
Commercial facilities is unwinding the historical dominance of residential users as the primary buyer archetype for toilet cistern blocks. SC Johnson & Son, Inc. leverages its brand strength and retail shelf presence across North American mass merchants. Reckitt Benckiser Group plc anchors its position through sustained R&D investment in sustained-release formulations. Henkel AG & Co. KGaA differentiates via geographic dominance in European private-label manufacturing.
Toilet cistern blocks are solid or semi-solid cleaning formulations designed for placement inside toilet cisterns, typically containing surfactants, fragrances, and antimicrobial agents that dissolve gradually to deliver continuous cleaning and deodorization with each flush. The product category spans standard blocks, eco-friendly blocks, scented blocks, and antibacterial blocks, with eco-friendly formulations capturing accelerated interest as biodegradable plastics and natural oils displace conventional polyvinyl chloride carriers. Tablet and gel forms dominate volume, while liquid variants occupy niche positions in commercial facilities requiring metered dosing systems.
REACH registration requirements in Europe, EPA Safer Choice standards in the United States, and BIS certification mandates in India collectively shape product composition thresholds and market access conditions for toilet cistern block manufacturers. These frameworks elevate compliance costs for chemical compound formulations while creating preferential pathways for natural oil and biodegradable plastic alternatives. Stakeholders must monitor evolving substance restriction lists and packaging waste directives to align formulation pipelines with compliance timelines.
Market Dynamics
Commercial facilities procurement of automated dispensing systems is compressing traditional residential channel dominance while REACH and EU Green Deal disclosure mandates force formulation transparency across European supply chains.
Growth Catalysts
- REACH substance registration:Chemical disclosure requirements under ECHA frameworks accelerate biodegradable carrier adoption and natural oil substitution for conventional polyvinyl chloride bases in European formulations.
- Facility automation:Commercial buildings in Germany, France, and the United Kingdom deploy metered dosing systems that standardize consumption patterns and lock in recurring supply contracts.
- Biodegradable plastics:Carrier material innovation enables manufacturers to satisfy BIS certification pathways in India while accessing preferential EPA Safer Choice positioning in the United States.
Market Restraints
- Fragrance compound volatility:Essential oil input costs fluctuate with agricultural yields in Madagascar and Indonesia, squeezing margin structures for scented block producers.
- Single-source surfactant concentration:Linear alkylbenzene sulfonate supply clusters in China and India expose formulators to shipping lane disruptions and tariff escalations.
- Technical dissolution limits:Sustained-release chemistry cannot achieve sub-30-day degradation cycles without compromising structural integrity during storage and transport.
Strategic Opportunities
- EU Green Deal tailwind:Packaging waste directive amendments create preferential market access for block formats using compostable wrappers versus conventional plastic films.
- Healthcare facility penetration:Antimicrobial block demand in hospitals and long-term care centers represents underdeveloped application space with stringent disinfection protocols.
- Direct-to-facility channels:Janitorial supply cooperatives and group purchasing organizations bypass traditional retail markups in North American institutional markets.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant-polymer compatibility and controlled-release kinetics concentrates among aging specialists in European and Japanese research centers.
- Multi-jurisdiction compliance timelines:Simultaneous EPA Safer Choice, REACH Annex XVII, and BIS IS 14634 certification processes extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Cistern Blocks Market |
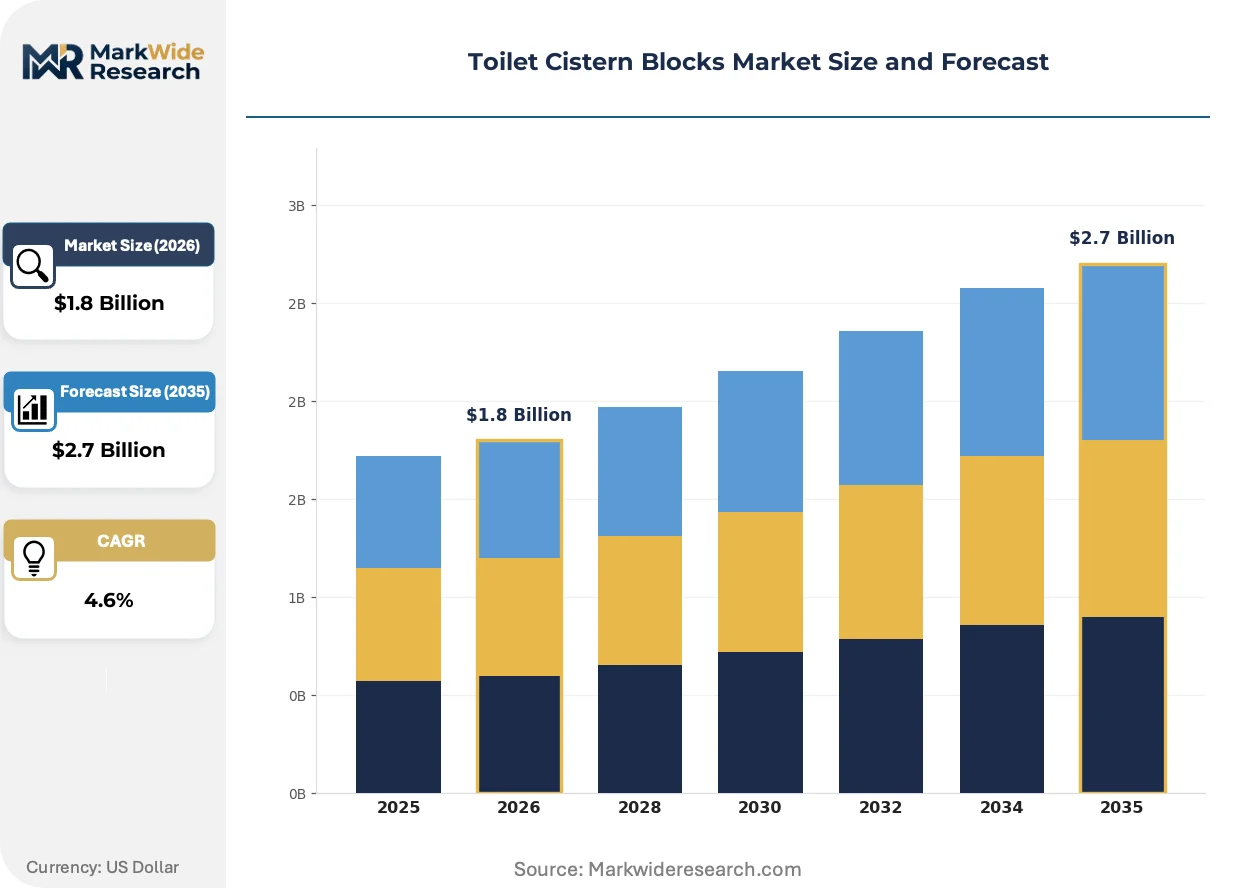
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blocks, Eco-Friendly Blocks, Scented Blocks, Antibacterial Blocks Material: Polyvinyl Chloride, Biodegradable Plastics, Natural Oils, Chemical Compounds Form: Tablets, Gels, Liquids, Powders End User: Residential Users, Commercial Facilities, Hospitality Sector, Public Restrooms |
| Companies Covered | SC Johnson & Son, Inc., Unilever, Reckitt Benckiser Group plc, McBride plc, Church & Dwight Co., Inc., Henkel AG & Co. KGaA, The Clorox Company, Diversey, Inc., Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Cistern Blocks Market Evolving Landscape
Formulation chemistry and dispensing hardware are converging to redefine product-service boundaries, with sustainability mandates and procurement centralization acting as twin accelerants of competitive differentiation.
Biodegradable polymer carriers derived from corn starch and polylactic acid blends are miniaturizing the environmental footprint of each flush while maintaining dissolution control. Commercial facility managers in the United Kingdom and Germany pilot these materials to preempt regulatory penalties. The technology is compressing acceptable carrier migration timelines from decades to months in wastewater treatment assessments.
EPA Safer Choice standard revisions are elevating surfactant biodegradability thresholds for products seeking federal procurement preference. Formulators must now document 28-day aquatic toxicity profiles and renewable carbon content percentages. Household cleaner segments in the United States face the steepest compliance gradients, with private-label manufacturers accelerating natural oil substitution programs.
Buyer concentration through integrated facility management contracts is consolidating purchasing authority away from individual property managers. Sodexo, Compass Group, and similar service providers negotiate multi-site supply agreements that specify performance metrics rather than product brands. This pattern is most visible in French and German commercial real estate portfolios where environmental reporting obligations cascade from landlord to service provider.
Toilet Cistern Blocks Market Segmentation
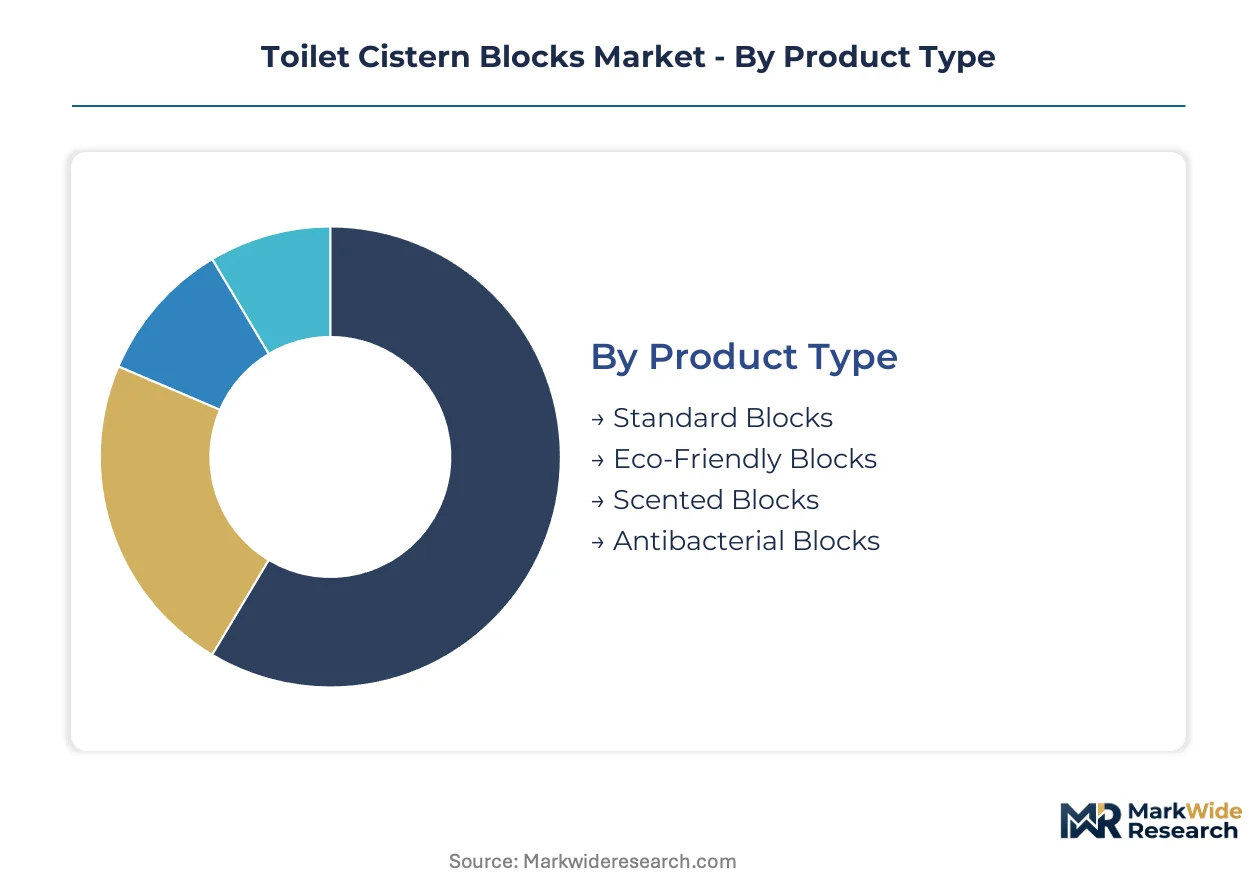
Toilet cistern block manufacturers align product architectures with divergent compliance burdens and facility infrastructure. Segmentation reveals where formulation chemistry, carrier materials, and dispensing hardware intersect with buyer procurement protocols.
Product Type:
REACH substance registration thresholds and EPA Safer Choice biodegradability standards split competitive positioning across four product categories.
- Eco-Friendly Blocks:Corn starch and polylactic acid carriers replace polyvinyl chloride bases to satisfy ECHA disclosure mandates and BIS certification pathways in India. German facility managers pilot these formats to preempt EU Green Deal packaging waste penalties.
- Antibacterial Blocks:Quaternary ammonium compounds and sustained-release silver ion matrices target healthcare facilities with Joint Commission disinfection protocols. Hospitals in France and long-term care centers in the United Kingdom specify these blocks in integrated facility management contracts.
- Standard Blocks:Conventional surfactant-fragrance formulations dominate retail shelf turnover in mass merchant channels.
- Scented Blocks:Essential oil infusions from Madagascar and Indonesian agricultural sources serve hospitality sector brand differentiation requirements.
Established volume favors standard blocks; emerging adoption favors eco-friendly blocks.
Material:
Cost tier stratification separates commodity chemical inputs from premium biodegradable alternatives with regulatory preferential access.
- Biodegradable Plastics:Polylactic acid and corn starch polymer blends compress wastewater treatment persistence timelines from decades to months. United Kingdom commercial real estate portfolios specify these carriers to satisfy landlord environmental reporting obligations.
- Natural Oils:Citronella, eucalyptus, and tea tree extracts displace synthetic fragrance compounds for EPA Safer Choice eligibility. Agricultural yield volatility in Madagascar and Indonesia squeezes margin structures for scented block producers.
- Polyvinyl Chloride:Legacy carrier material faces REACH Annex XVII restriction pressure across European supply chains.
- Chemical Compounds:Linear alkylbenzene sulfonate surfactant clusters in China and India expose formulators to shipping lane disruptions.
Polyvinyl chloride retains volume leadership; biodegradable plastics climb the fastest.
Form:
Dispensing hardware compatibility and dissolution control precision determine facility adoption patterns across four physical formats.
- Tablets:Compressed block geometry delivers calibrated dissolution kinetics for residential cistern geometries. German and French households sustain volume demand through retail replenishment cycles.
- Gels:Semi-solid matrices adapt to variable cistern shapes while maintaining structural integrity during storage. Commercial facilities in the United Kingdom deploy gel cartridges in automated metered dosing systems.
- Liquids:Concentrated solutions occupy niche positions in institutional settings requiring precise dilution control.
- Powders:Granular formats serve specialized industrial applications with bulk handling infrastructure.
Tablet formats anchor residential volume; gel systems gain share fastest in commercial procurement.
End User:
Customer type segmentation tracks the shift from individual household purchasing to centralized facility procurement authority.
- Commercial Facilities:Integrated facility management contracts with Sodexo and Compass Group consolidate multi-site supply agreements. Germany, France, and the United Kingdom lead automated dispensing system deployment.
- Hospitality Sector:Brand-consistent fragrance specifications and guest experience metrics drive premium block procurement in hotel chains.
- Residential Users:Mass merchant retail channels and private-label penetration sustain volume baseline across North American and European households.
- Public Restrooms:Municipal procurement protocols and janitorial supply cooperatives shape pricing structures in institutional settings.
Residential channels retain unit volume dominance; commercial facilities drive value expansion through recurring supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's dominance in surfactant formulation inputs, while the Rhine-Alpine rail corridor moves biodegradable polymer carriers from German manufacturing clusters to distribution hubs across the continent.
Germany
Commercial real estate portfolios in Frankfurt and Munich drive automated dispensing system procurement. ECHA REACH Annex XVII restrictions on polyvinyl chloride carriers force reformulation timelines. The Rhine-Ruhr industrial corridor concentrates private-label manufacturing capacity for eco-friendly block production.
United Kingdom
Integrated facility management contracts with Sodexo and Compass Group consolidate multi-site supply agreements. EU Green Deal packaging waste directive amendments create preferential access for compostable wrapper formats. Greater London commercial property managers pilot biodegradable polylactic acid carriers to satisfy landlord environmental reporting obligations.
France
Healthcare facilities in Paris and Lyon specify antimicrobial blocks with quaternary ammonium compounds for Joint Commission disinfection protocols. ANSM chemical disclosure requirements align with REACH substance registration thresholds. The Auvergne-Rhône-Alpes region hosts fragrance compound blending operations serving hospitality sector brand differentiation requirements.
United States
EPA Safer Choice standard revisions elevate surfactant biodegradability thresholds for federal procurement preference. Mass merchant retail channels in the Midwest and Southeast sustain residential volume baselines. The Gulf Coast petrochemical corridor supplies linear alkylbenzene sulfonate surfactants, exposing formulators to shipping lane disruption risks.
India
BIS IS 14634 certification mandates shape product composition thresholds for household cleaner market access. Mumbai and Delhi-NCR retail networks expand distribution for standard block formats. Gujarat's chemical manufacturing belt concentrates surfactant production capacity serving domestic formulation requirements.
Toilet Cistern Blocks Market Competitive Landscape
Concentration sits with diversified consumer goods conglomerates and specialized chemical manufacturers. The vendor base spans three tiers: multinational brand owners with retail shelf dominance, European private-label specialists, and regional contract manufacturers. Strategic moves center on formulation chemistry partnerships and automated dispensing system integration.
Among North American brand owners, SC Johnson & Son, Inc. and The Clorox Company exemplify the retail-channel archetype with mass merchant presence. Reckitt Benckiser Group plc anchors the European formulation-specialist position. These three represent divergent geographic emphases rather than direct segment overlap.
| Leading Market Players |
|---|
| SC Johnson & Son, Inc. |
| Unilever |
| Reckitt Benckiser Group plc |
| McBride plc |
| Church & Dwight Co., Inc. |
| Henkel AG & Co. KGaA |
| The Clorox Company |
| Diversey, Inc. |
| Procter & Gamble Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between commercial facility management providers and biodegradable polymer suppliers lock in price visibility while securing carrier material access ahead of EU Green Deal packaging waste enforcement timelines. These contracts compress margin volatility for formulators serving German and United Kingdom institutional buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA Safer Choice-certified blocks from conventional formulations and private-label alternatives. Price differentiation hinges on certification grade and volume scale, with hospitality chains absorbing premium tiers while municipal procurement drives economy-tier compression. Cost compression in standard blocks is intensifying because linear alkylbenzene sulfonate supply clusters in China face shipping lane disruption risks. Residential mass merchant channels exhibit highest price sensitivity; healthcare facilities demonstrate lowest sensitivity due to Joint Commission protocol compliance requirements.
Supply Chain Analysis
Inventory lead times for essential oil inputs stretch unpredictably with Madagascar and Indonesian agricultural yield cycles, forcing scented block producers to carry buffer stocks. Manufacturing gravity centers on Germany, China, and India, with the Rhine-Ruhr corridor hosting private-label formulation capacity and Gujarat's chemical belt supplying surfactant inputs. Raw material dependencies span corn starch polymers, quaternary ammonium compounds, and linear alkylbenzene sulfonates. Single-source surfactant concentration in Asia exposes formulators to tariff escalations. Distribution runs through janitorial supply cooperatives and group purchasing organizations in North America, bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as procurement authority consolidates through integrated facility management contracts, creating niche entry points for specialized formulators serving compliance-heavy healthcare and hospitality verticals.
For Market Incumbents: Shield formulation expertise advantages by deepening captive supply of biodegradable polymer carriers and accelerating REACH Annex XVII pre-registration timelines ahead of competitor compliance cycles. SC Johnson and Reckitt Benckiser should lock in multi-year offtake agreements with corn starch suppliers to defend margin position against essential oil volatility. Certification investment in EPA Safer Choice and BIS IS 14634 pathways creates switching costs for institutional buyers. For New Entrants and Emerging Players: Differentiate on compostable wrapper formats to capture EU Green Deal tailwinds in United Kingdom commercial real estate portfolios. Healthcare facility antimicrobial blocks represent the most penetrable white space, with Joint Commission protocols creating specification stickiness once established. Direct-to-facility channels through janitorial cooperatives bypass incumbent retail shelf dominance. For Investors and Strategic Acquirers: Capital is best deployed toward European private-label specialists with established REACH compliance infrastructure and automated dispensing system integration capabilities. Long-term viability over a decade hinges on formulation chemistry partnerships replacing commodity surfactant sourcing. Watch biodegradable polymer carrier cost parity with polyvinyl chloride as the inflection signal for mass-market transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Polymers | Corn starch and polylactic acid captive supply secures EU Green Deal compliance pathways ahead of restriction deadlines. |
| Healthcare Facility Certification Investment | Joint Commission antimicrobial block specifications lock in recurring supply contracts with disinfection protocol rigor. |
| Automated Dispensing System Partnerships | Sodexo and Compass Group multi-site agreements standardize consumption patterns and reduce customer acquisition costs. |
| Direct-to-Facility Channel Development | Janitorial supply cooperatives bypass retail markup compression in North American institutional procurement. |
| Sustainability Repositioning | EPA Safer Choice eligibility opens federal procurement preference and premium pricing in environmentally reporting portfolios. |
Research Methodology
Operator-level perspectives from facility managers at Sodexo and Compass Group, procurement leads at hospital systems, R&D directors at surfactant formulators, and category buyers at mass merchants anchored the qualitative base. Secondary validation drew from ECHA substance registration databases, EPA Safer Choice certified product listings, BIS IS 14634 certification records, and customs trade data on linear alkylbenzene sulfonate flows. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, form, and end user dimensions.
Sensitivity analysis tested forecast outputs against variable input assumptions across the projection horizon. Segmentation dimensions modeled include product category tier, carrier material compliance grade, dispensing hardware compatibility, and facility procurement authority concentration. CAGRs derived from installed base growth rates, replacement cycle frequencies, and pricing trajectory scenarios. Formulation chemist availability constraints and multi-jurisdiction certification timelines served as key industry-specific forecast inputs.
Material uncertainties — regulatory restriction list amendments, essential oil agricultural yield shocks, surfactant supply chain disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions on compliance timeline adherence and commercial facility automation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Drying Racks Market
Household Items
China Cookware Market
Household Items
Laundry Detergent Sheets Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Dishwashing Products Market
Household Items
Thermos Drinkware Market
Household Items
Smart Bathtub Market
Household Items
Portable Steamers Market
Household Items
Neck Pillows Market
Household Items
Global Tableware Market
Household Items
Electric Shoe Polisher Market
Household Items
Facial Tissue Paper Market
Household Items
Kitchen Towel Market
Household Items
Russia Residential Water Heaters Market
Household Items
Paper Towel Dispenser Market
Household Items
Countertop Market