
 Console Games Market | 2026-2036
Console Games Market Size, Share, and Industry Trends Forecast 2026-2036
Console Games Market Analysis
Buyer concentration around subscription services is hardening as casual gamers migrate from one-time purchases to recurring access models. Sony Interactive Entertainment leverages its PlayStation Plus ecosystem to lock in recurring revenue across tiered service levels. Nintendo sustains its position through proprietary hardware-software integration that shields its family-oriented user base from cross-platform competition. Microsoft Studios anchors its strategy in Game Pass, using cloud delivery to extend reach beyond console-exclusive households.
Console games are interactive software titles engineered for dedicated gaming hardware with standardized processing architectures, controller inputs, and display outputs typically ranging from 1080p to 4K resolution at 30-120 frames per second. These products generate revenue through unit sales, downloadable content, and ongoing service monetization within living-room entertainment environments. Action titles dominate unit sales volume across PlayStation, Xbox, and Nintendo Switch platforms where competitive players drive premium pricing for multiplayer-enabled releases. Subscription services represent the fastest-expanding distribution channel as digital download infrastructure displaces retail store shelf space. RPG content commands elevated margin pools through episodic downloadable content and season pass structures that extend monetization well beyond initial purchase.
The ESRB rating system in the United States, PEGI framework across European markets, and CERO standards in Japan shape content eligibility and marketing reach for publishers seeking multi-territory releases. National regulators increasingly scrutinize loot box mechanics and randomized reward systems, forcing studios to redesign monetization architectures or face distribution restrictions. Stakeholders must monitor how platform holders adjust revenue-sharing terms as cloud streaming and cross-platform play erode hardware-exclusive competitive advantages.
Market Dynamics
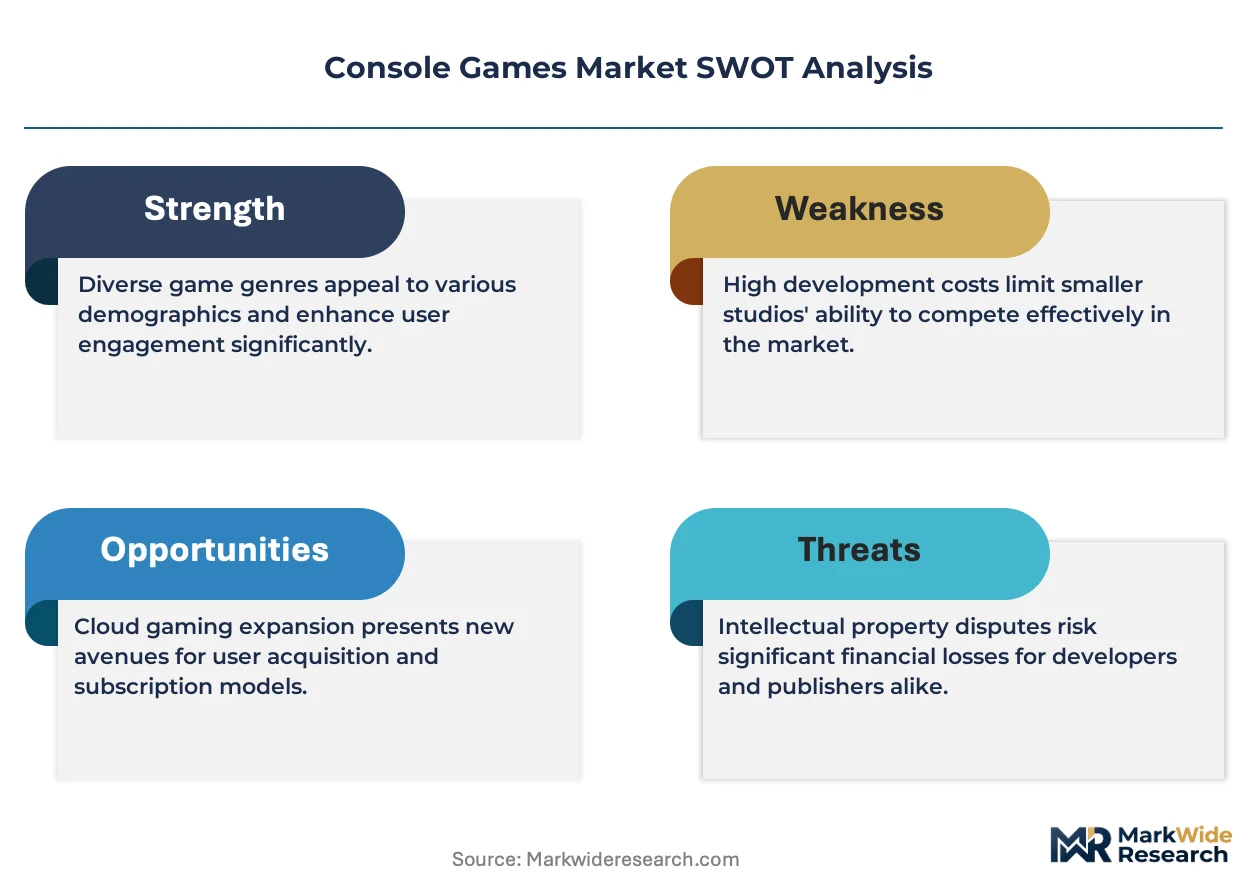
Subscription-based access models are hardening as the dominant consumption pattern, compressing unit sales velocity while extending lifetime value per user across cloud-enabled platform ecosystems.
Growth Catalysts
- Cloud Gaming Infrastructure:Low-latency streaming protocols eliminate hardware barriers for casual players, expanding addressable households beyond console-exclusive environments.
- PEGI Framework Expansion:Standardized age-rating harmonization across European markets reduces publisher compliance costs for multi-territory digital releases.
- Family-Oriented Hardware-Software Integration:Proprietary ecosystem lock-in shields dedicated user bases from cross-platform competitive pressure.
Market Restraints
- Semiconductor Supply Concentration:Advanced node fabrication for custom SoCs depends on Taiwan-based foundry capacity, creating vulnerability to geopolitical disruption.
- Loot Box Regulatory Friction:Belgium and Netherlands gambling authority rulings force redesign of randomized reward mechanics or complete market withdrawal.
- Mobile Gaming Substitution:Free-to-play smartphone titles capture discretionary entertainment time from price-sensitive casual segments.
Strategic Opportunities
- Saudi Arabia Market Liberalization:PIF-backed infrastructure investment and regulatory opening create new high-ARPU territory for platform holders.
- AI-Assisted Content Generation:Procedural narrative tools and automated localization compress development timelines for mid-budget releases.
- Cross-Platform Progression Systems:Cloud-save synchronization between console, PC, and mobile endpoints deepens engagement across device ecosystems.
Industry Challenges
- Live Service Expertise Gap:Transition from boxed-product to persistent operation models requires community management and data analytics capabilities scarce among traditional studios.
- Backward Compatibility Engineering:Preservation of legacy software libraries demands ongoing emulation investment without direct revenue attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Console Games Market |
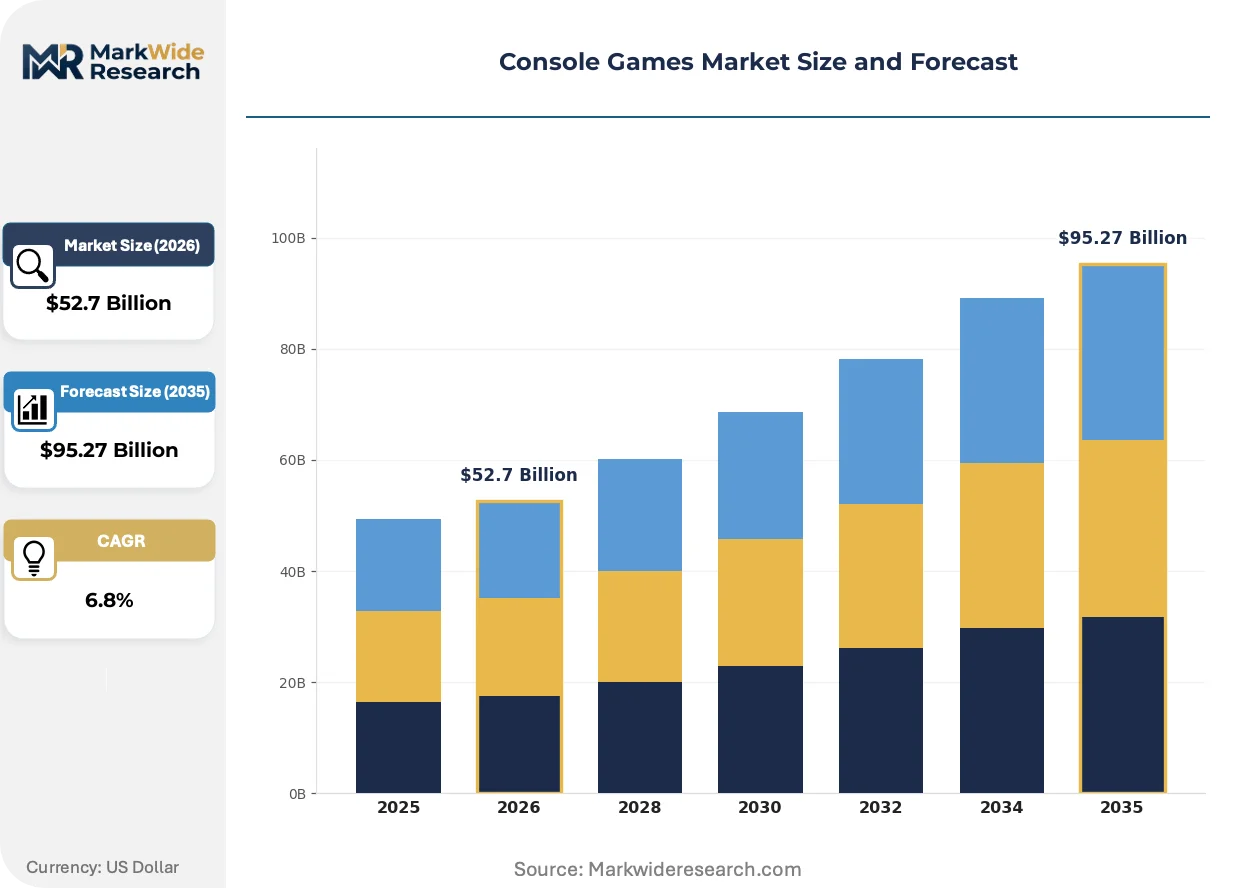
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Adventure, RPG, Sports Distribution Channel: Online Store, Retail Store, Subscription Service, Digital Download Target Audience: Casual Gamers, Hardcore Gamers, Families, Competitive Players Platform: PlayStation, Xbox, Nintendo Switch, Others |
| Companies Covered | Sony Interactive Entertainment, Nintendo, Microsoft Studios, Electronic Arts, Activision Blizzard, Ubisoft Entertainment, Capcom, Bandai Namco Entertainment, Valve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Console Games Market Emerging Trajectories
Digital-first distribution policies from national media regulators are redirecting developer investment toward service-based architectures while cloud delivery compresses hardware upgrade cycles.
Ray-traced real-time lighting is consolidating visual fidelity standards across action-oriented releases. Mid-tier studios adopt Unreal Engine 5's Nanite geometry streaming to match AAA production values without proprietary engine investment. This capability compression is consolidating competitive differentiation around live operations expertise rather than technical spectacle alone.
FTC scrutiny of subscription cancellation friction is reshaping platform holder billing practices in the United States. The commission's click-to-cancel rulemaking forces redesign of multi-step retention flows previously optimized for subscriber inertia. Family-tier plan providers face the steepest compliance burden as household account management complexity intersects with simplified termination requirements.
Season pass structures now dominate monetization for narrative-driven RPG content, unbundling episodic delivery from initial purchase commitment. Publishers extend engagement windows through battle pass tiers and cosmetic microtransactions rather than discrete expansion packs. Japan and South Korea exhibit the highest attach rates for these recurring content pipelines among core player demographics.
Console Games Market Segmentation
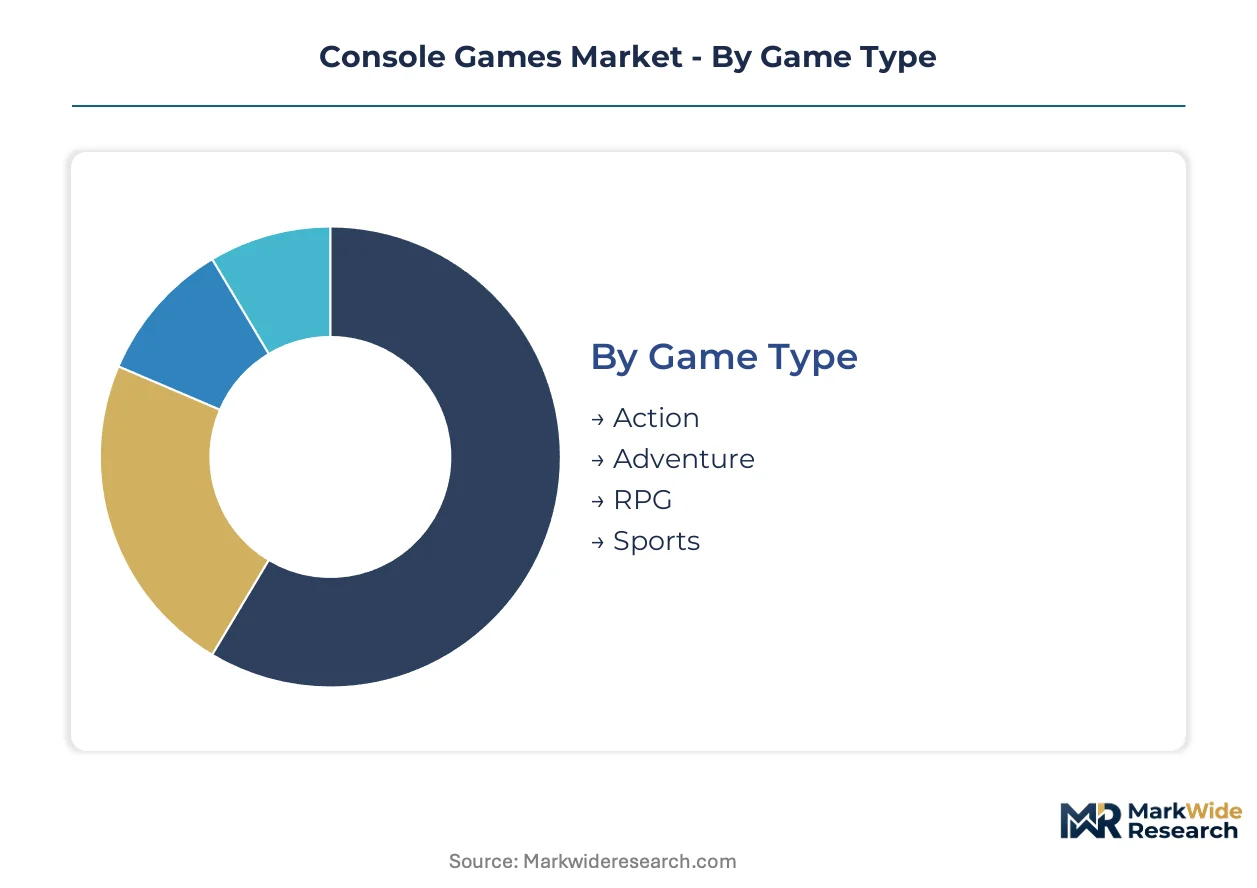
Segmentation in the console games market reveals how consumption patterns fragment across hardware ecosystems, monetization architectures, and player commitment levels. Publishers calibrate development budgets and live service roadmaps against these divides to optimize lifetime value extraction.
Game Type:
Standalone software products dominate revenue pools, while embedded narrative systems within persistent online worlds represent the fastest-climbing investment category.
- Action:High-twitch combat mechanics and multiplayer matchmaking engines drive the highest unit velocity across PlayStation and Xbox platforms. Competitive players in the United States and Japan sustain premium pricing for annualized franchise releases with battle pass integration.
- RPG:Narrative-driven character progression systems with episodic downloadable content architectures command extended monetization windows. South Korean and Japanese demographics exhibit the steepest attach rates for season pass structures and cosmetic microtransaction pipelines.
- Adventure:Exploration-focused design templates with lower mechanical complexity attract family-oriented households on Nintendo Switch hardware.
- Sports:Annualized roster updates and Ultimate Team card-pack mechanics generate recurring revenue through randomized reward systems subject to regulatory scrutiny in Belgium and the Netherlands.
Action leads volumes today; RPG is gaining share fastest.
Distribution Channel:
Cost tier stratification separates premium full-price releases from subscription-accessed catalogs and economy-tier promotional sales.
- Subscription Service:Cloud-enabled libraries with tiered access levels compress unit sales velocity while extending per-user lifetime value. Microsoft Studios anchors its competitive position through Game Pass ecosystem lock-in across console and PC endpoints.
- Digital Download:Direct-to-consumer storefront infrastructure eliminates retail margin extraction and enables dynamic pricing algorithms. Sony Interactive Entertainment leverages PlayStation Store control to maximize first-party attach rates.
- Online Store:Platform-holder digital marketplaces with curated discovery algorithms determine visibility for mid-tier publishers.
- Retail Store:Physical disc distribution retains residual importance for collectible editions and gift-purchase occasions in Japanese and United Kingdom markets.
Digital Download leads volumes today; Subscription Service is expanding most quickly.
Target Audience:
Customer type fragmentation maps directly to engagement intensity and monetization ceiling differentials.
- Hardcore Gamers:High-hour players with preference for mechanical depth and competitive ranking systems drive premium hardware adoption. This segment sustains the highest per-title expenditure through collector's editions and esports merchandise pipelines.
- Competitive Players:Skill-ranked multiplayer participants generate sustained engagement through seasonal content drops and tournament infrastructure. South Korea's PC bang culture and Japan's arcade heritage feed console competitive scene development.
- Casual Gamers:Intermittent players with lower mechanical literacy favor subscription access over full-price purchase commitment.
- Families:Multi-user households with content rating sensitivity concentrate on Nintendo Switch hardware with local multiplayer capabilities.
Hardcore Gamers leads volumes today; Competitive Players is climbing the fastest.
Platform:
Supply concentration around custom SoC fabrication binds platform performance to semiconductor foundry capacity allocation.
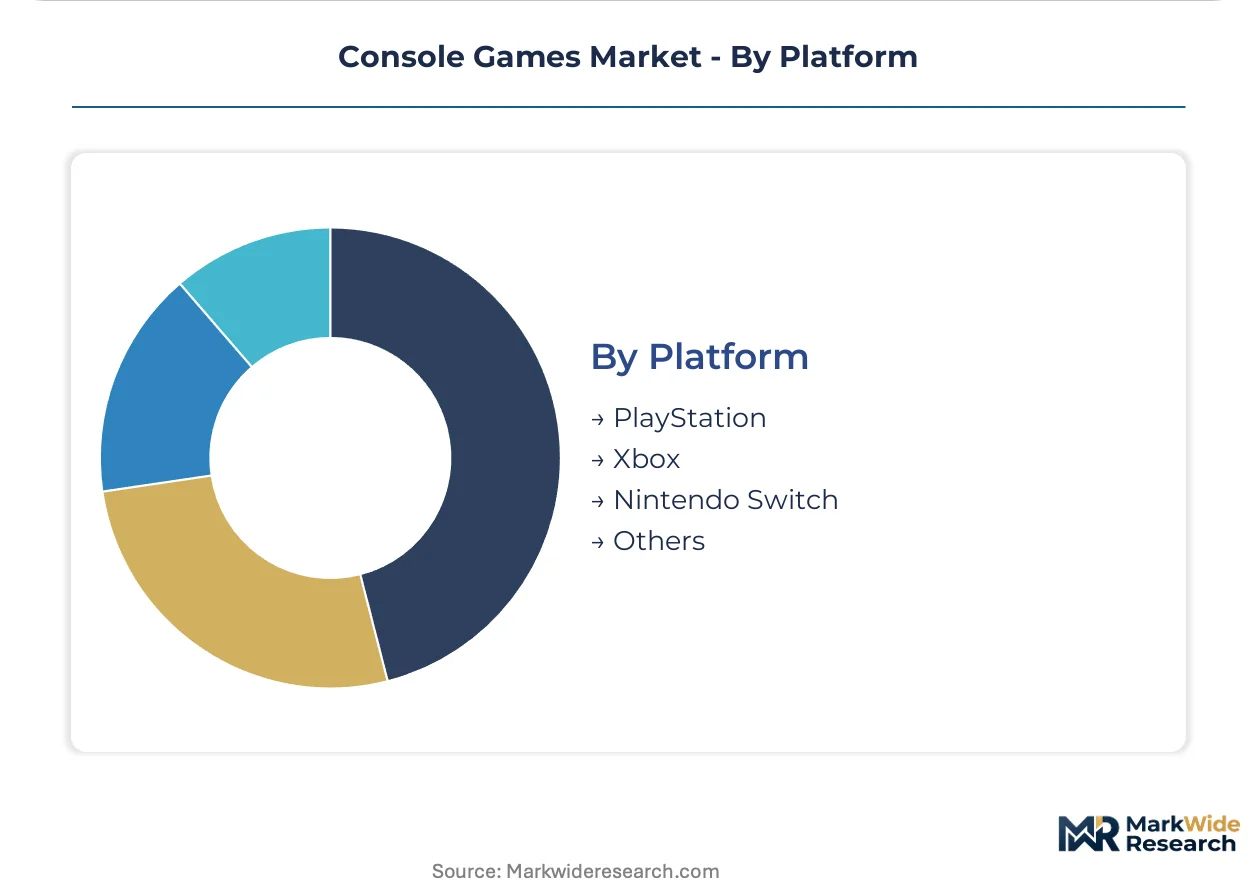
- PlayStation:Sony Interactive Entertainment's proprietary ecosystem with exclusive first-party studios commands the highest core demographic loyalty. The United States and United Kingdom represent the deepest installed base territories for premium pricing retention.
- Nintendo Switch:Hybrid portable-home hardware with proprietary software integration shields family-oriented users from cross-platform competition. Japan's domestic market sustains disproportionate software attach rates against global averages.
- Xbox:Microsoft Studios leverages cloud infrastructure and Game Pass subscription bundling to extend reach beyond console-exclusive households.
- Others:Emerging streaming devices and cloud-native platforms occupy niche positioning pending latency protocol maturation.
PlayStation leads volumes today; Nintendo Switch is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan generates the highest software attach rates per console globally, while the United States commands the deepest installed base for premium hardware pricing. Platform ecosystems in the United Kingdom sustain subscription penetration rates above continental European averages. Saudi Arabia's regulatory opening under Vision 2030 is creating new high-ARPU territory for international publishers.
United States
Hardcore gamers and competitive players drive the highest per-title expenditure through collector's editions and esports merchandise pipelines. The FTC's click-to-cancel rulemaking is forcing platform holders to redesign multi-step subscription retention flows. Seattle and Los Angeles anchor the largest concentration of first-party development studios and live service operations infrastructure.
Japan
Family-oriented households and dedicated fan communities sustain disproportionate software attach rates against global benchmarks. The CERO rating system shapes content eligibility for multi-territory releases with Japanese market requirements. Tokyo and Osaka host the densest clusters of arcade heritage studios transitioning their intellectual property to console platforms.
United Kingdom
Subscription service penetration exceeds continental European levels as casual gamers migrate from physical retail to digital access models. The PEGI framework harmonizes age-rating standards across EU member states for streamlined compliance. London's development corridor concentrates mid-tier studios specializing in narrative-driven RPG content with episodic delivery structures.
Saudi Arabia
PIF-backed infrastructure investment is attracting platform holders to establish regional data centers and localization operations. The General Commission for Audiovisual Media is liberalizing content approval timelines for international publishers. Riyadh and NEOM are emerging as hubs for gaming-themed entertainment districts and esports tournament infrastructure.
South Korea
PC bang culture feeds competitive player migration to console platforms with skill-ranked multiplayer capabilities. The Game Rating and Administration Committee enforces strict loot box disclosure requirements affecting monetization architecture design. Seoul's Pangyo Techno Valley houses the densest concentration of live service expertise and mobile-to-console crossover studios.
Console Games Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware platform and software publishing tiers. The market structure concentrates around three integrated platform ecosystems that control distribution infrastructure and captive development studios. Strategic archetypes include hardware-software integrators, multi-platform publishers with live service expertise, and cloud-native platform operators. Competitive moves center on subscription ecosystem lock-in and exclusive content acquisition to defend installed base positions.
Among platform-integrated conglomerates, Sony Interactive Entertainment and Nintendo exemplify contrasting hardware-software strategies, while Microsoft Studios anchors the cloud-subscription archetype. These entities represent the dominant competitive anchors whose ecosystem investments shape developer resource allocation and consumer access patterns across territorial markets.
| Leading Market Players |
|---|
| Sony Interactive Entertainment |
| Nintendo |
| Microsoft Studios |
| Electronic Arts |
| Activision Blizzard |
| Ubisoft Entertainment |
| Capcom |
| Bandai Namco Entertainment |
| Valve Corporation |
| Others |
Supply Flow & Price Mechanics
Carbon-neutral manufacturing mandates from the European Union's CSRD disclosure requirements gate qualified supply for premium-tier console hardware and elevate pricing access for compliant platform holders. These sustainability frameworks force foundry partners to certify low-carbon fabrication processes, concentrating qualified component supply among Taiwan Semiconductor Manufacturing Company and Samsung Foundry operations with verified renewable energy sourcing.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for advanced node semiconductors while subscription-tier access models dominate software monetization. Three-tier pricing structure across premium, standard, and economy levels separates collector's edition physical releases from digital deluxe tiers and subscription catalog access. Cost compression in mid-budget indie releases is intensifying because Unreal Engine 5 Nanite adoption erodes technical differentiation. Casual gamers accessing subscription libraries exhibit highest price sensitivity, while hardcore collectors sustain premium pricing for limited hardware variants.
Supply Chain Analysis
Direct-to-platform-holder channels handle hyperscale demand for custom SoC fabrication, with Taiwan, South Korea, and Japan anchoring advanced node production. Raw material dependencies center on high-purity silicon wafers, rare earth elements for controller magnetics, and cobalt-based alloys for thermal management. Single-source vulnerability concentrates around Taiwan-based foundry capacity for 5nm and below process nodes. Distribution runs through platform-holder controlled digital storefronts with curated discovery algorithms determining publisher visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The console games market functions as a stable compounder where subscription-based access models generate predictable recurring revenue streams that smooth hardware cycle volatility.
For Market Incumbents: Lock in exclusive content pipelines through first-party studio acquisition or long-term publishing partnerships to defend against cloud-native platform entrants. Expand backward integration into custom SoC design to reduce foundry allocation dependency. Prioritize live service expertise development through data analytics capability investment, as persistent operation models displace boxed-product releases.
For New Entrants and Emerging Players: Capture underserved family-oriented segments on emerging cloud streaming devices with latency-optimized casual game portfolios. Saudi Arabia's regulatory opening under Vision 2030 represents the most penetrable geography for platform establishment without incumbent ecosystem lock-in. Deploy direct-to-consumer subscription bundling with regional telecom operators to bypass platform-holder storefront control.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier RPG specialists with established season pass infrastructure because episodic content delivery extends monetization windows beyond initial purchase. The five-to-ten year viability horizon favors studios with proven live service operation capabilities over traditional boxed-product developers. Watch cloud gaming subscriber churn rates as the critical inflection indicator for platform ecosystem health.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Acquisition | First-party studio purchases by Sony Interactive Entertainment secure PlayStation ecosystem differentiation against Game Pass expansion. |
| Cloud Infrastructure Partnership | Regional data center deployments with Saudi PIF backing reduce latency for Middle Eastern subscriber growth. |
| Live Service Capability Buildout | Community management and data analytics investment addresses expertise gaps in traditional boxed-product studios. |
| Cross-Platform Progression Integration | Cloud-save synchronization deepens engagement across console, PC, and mobile endpoints for competitive player retention. |
| Regulatory Compliance Investment | Loot box mechanic redesign for Belgium and Netherlands gambling authority requirements preserves market access. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform holder strategy executives, first-party studio creative directors, third-party publisher business development leads, and live service operations specialists. Secondary validation drew from SEC filings of publicly traded publishers, platform ecosystem subscriber disclosures, CERO and PEGI rating database trends, and customs records for physical software imports. Bottom-up title-level revenue modeling and top-down platform ecosystem sizing were triangulated against reported segment performance.
Historical reference periods anchored volume and value trajectories across the projection horizon, with analytical frameworks modeling game type, distribution channel, target audience, and platform segmentation dimensions. CAGRs were derived from installed base growth curves, attach rate evolution, and subscription penetration assumptions. Industry-specific forecast inputs included semiconductor foundry capacity allocation schedules and regulatory timeline projections for loot box compliance.
Underlying measurement precision varies by segment; subscription service revenue carries tighter precision than physical retail estimates due to direct platform-holder disclosure practices. Forecasts reflect assumptions around cloud latency protocol maturation and national media regulator policy continuity. Periodic stress-testing of base assumptions is recommended given geopolitical semiconductor supply concentration and evolving gambling authority interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Battle Royale Games Market
Gaming
VR Gaming Market
Gaming
Racing Games Market
Gaming
VR Gaming Controller Market
Gaming
Global Esports Market
Gaming
Gaming Gadgets Market
Gaming
Arcade Cabinet Market
Gaming
Gaming Simulator Market
Gaming
Board Games Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
United States Gaming Market
Gaming
Slot Machine Market
Gaming
Mobile Gaming Market
Gaming
Metaverse in Gaming Market
Gaming
North America in-Game Advertising Market
Gaming
Australia Gaming Accessories Market