
 Connected Game Console Market | 2026-2036
Connected Game Console Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Game Console Market Analysis
Subscription bundling of hardware with cloud gaming libraries is repositioning purchase decisions away from standalone console sales. Sony Group Corporation leverages its first-party studio pipeline to anchor subscriber retention across PlayStation Plus tiers. Microsoft Corporation extends its Game Pass ecosystem across devices, competing on service breadth rather than console exclusivity. Nintendo Co., Ltd. differentiates through hybrid hardware-software integration that sustains premium pricing outside traditional spec competition.
A connected game console is a network-enabled computing device engineered around custom x86 or ARM SoC architectures with integrated GPUs, delivering interactive entertainment through local processing, cloud streaming, or hybrid execution. These systems serve commercial purposes spanning gaming, media consumption, social connectivity, and digital commerce. Traditional consoles still occupy the largest installed base and margin pool, while cloud gaming platforms represent the fastest-expanding segment as latency-sensitive streaming infrastructure matures. Handheld consoles are experiencing renewed structural relevance through semiconductor efficiency gains that enable portable AAA execution.
The FCC governs broadband quality benchmarks that directly shape cloud gaming service viability across the United States, while the EU AI Act imposes algorithmic transparency obligations on recommendation engines within European markets. ESRB and PEGI content rating frameworks additionally influence regional software distribution agreements and parental control feature mandates. Stakeholders must monitor how regulatory fragmentation between federal communications policy and emerging AI governance reshapes platform architecture decisions and geographic rollout sequencing.
Market Dynamics
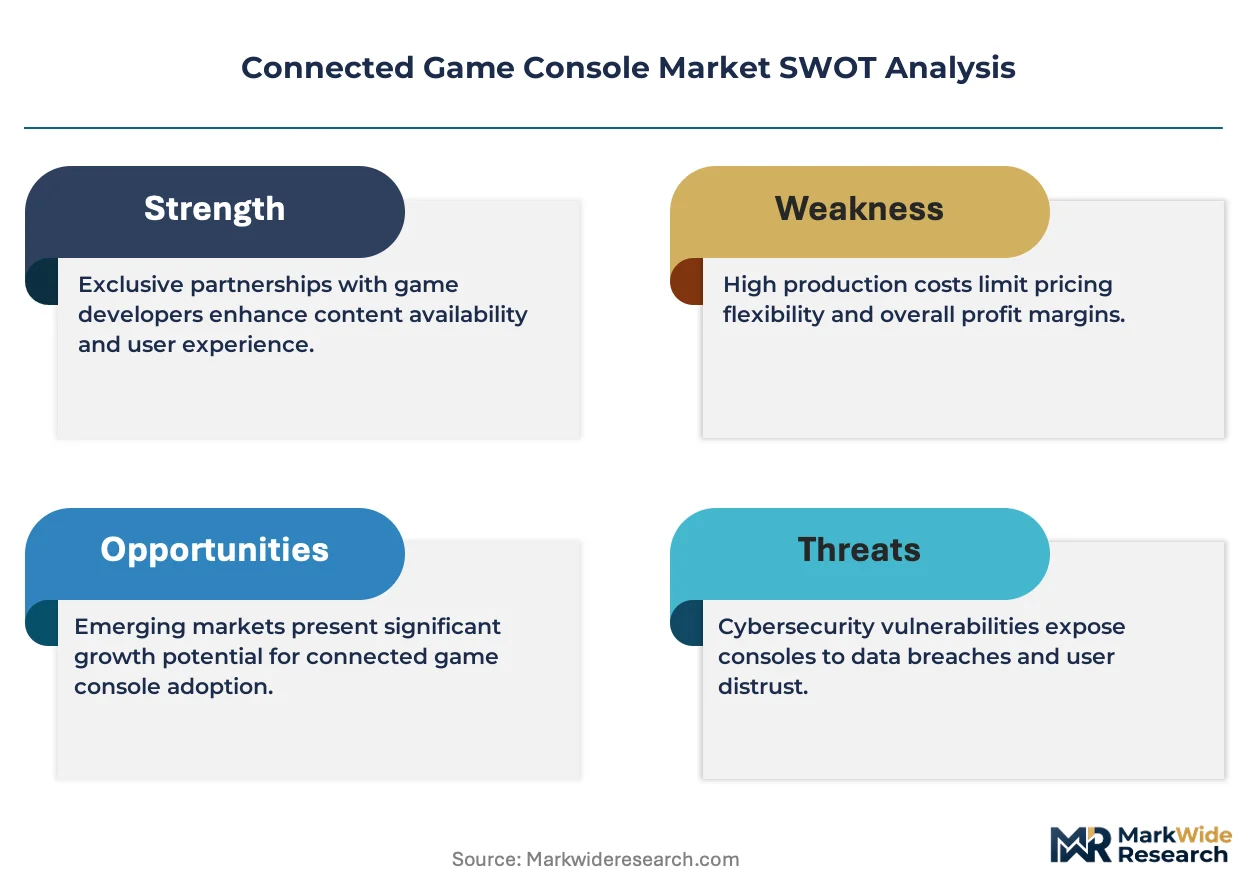
Cloud gaming subscription bundling is compressing traditional hardware purchase cycles while forcing platform operators to restructure margin allocation between device sales and recurring service revenue.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements are accelerating investment in explainable recommendation engines across European distribution platforms.
- Semiconductor efficiency gains:ARM-based SoC architectures now enable handheld form factors to execute AAA titles previously confined to stationary hardware.
- Broadband infrastructure expansion:United States FCC benchmark upgrades are extending viable cloud gaming addressable markets into secondary metropolitan areas.
Market Restraints
- Advanced node foundry concentration:Taiwan-based TSMC fabrication dominance creates single-point-of-failure exposure for custom GPU and SoC supply.
- ESRB content classification friction:Regional rating disparities between North American and European frameworks delay synchronized global software releases.
- Cloud latency physics:Speed-of-light constraints impose hard limits on streaming responsiveness for competitive multiplayer genres regardless of bandwidth.
Strategic Opportunities
- India TRAI broadband incentives:National digital infrastructure subsidies are opening subscription-accessible gaming populations in tier-two cities.
- Hybrid execution architectures:Convergence of edge computing with local rendering is enabling new service tiers that split processing between device and cloud.
- Direct-to-consumer storefronts:First-party digital distribution channels are capturing margin previously allocated to retail intermediaries.
Industry Challenges
- Real-time systems engineering talent:Scarce expertise in low-latency networking and predictive input buffering constrains cloud service quality improvements.
- Cross-platform certification complexity:Fragmented technical standards between console, PC, and mobile environments multiply QA cycles for multi-platform releases.
- Legacy hardware support obligations:Extended backward compatibility commitments drain engineering resources from next-generation feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Game Console Market |
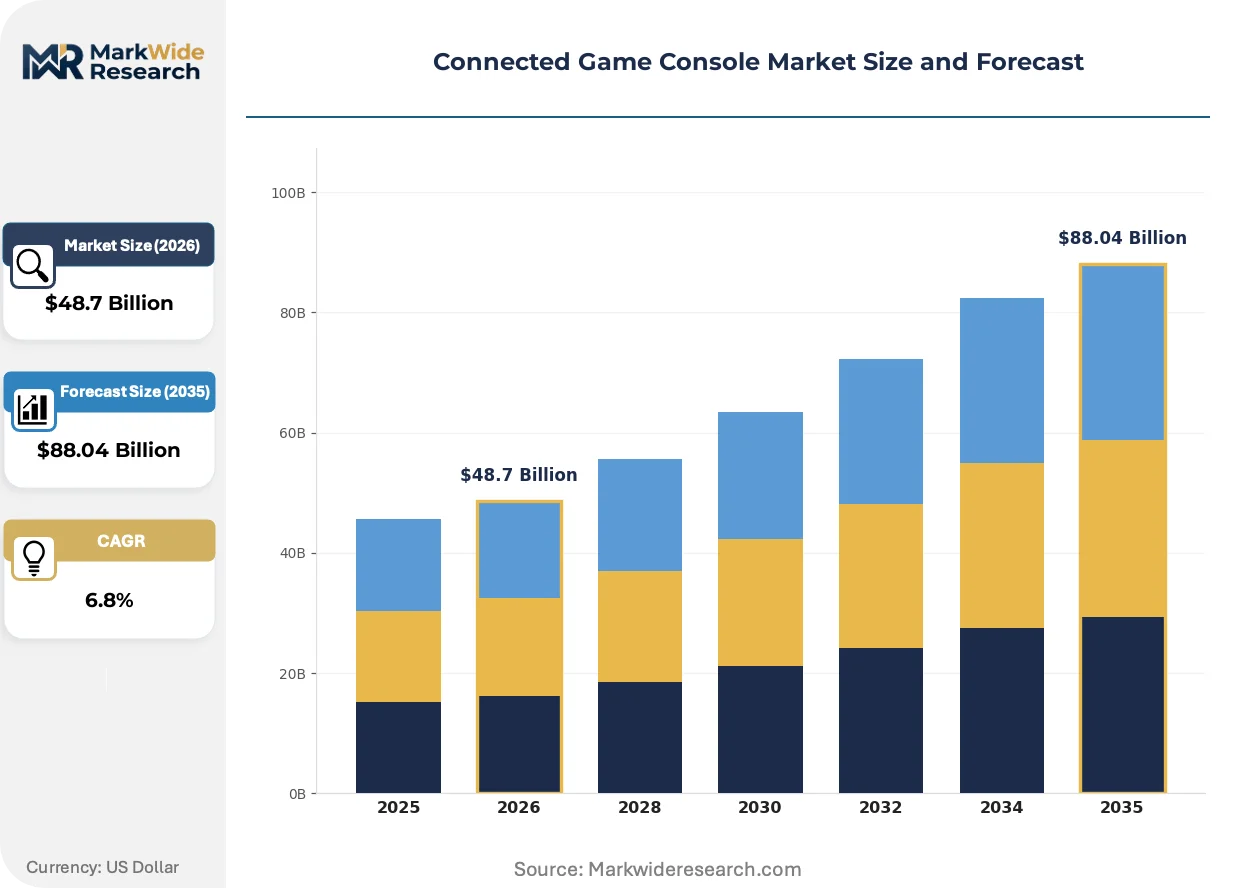
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Consoles, Micro Consoles, Traditional Consoles, Cloud Gaming Platforms End User: Casual Gamers, Hardcore Gamers, Streamers, Families Distribution Channel: Online Retailers, Specialty Stores, Big Box Retailers, Direct Sales Technology: Streaming, Virtual Reality, Augmented Reality, Blockchain |
| Companies Covered | Sony Group Corporation, Microsoft Corporation, Nintendo Co., Ltd., Tencent Holdings Ltd., Valve Corporation, Nvidia Corporation, Google LLC, Apple Inc., Amazon.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Game Console Market Emerging Trajectories
Platform operators are racing to embed generative AI tools into content creation pipelines while regulators scramble to impose guardrails on algorithmic systems that shape user engagement.
Edge-based AI inference acceleration is consolidating processing distribution for real-time upscaling and NPC behavior generation. First-party studios are adopting these capabilities fastest, integrating neural rendering into proprietary engines. This consolidation is compressing the performance gap between mid-tier hardware and flagship specifications.
REACH substance restrictions and RoHS amendments are tightening material compliance for console enclosures and printed circuit assemblies. Manufacturers are reformulating solder compositions and halogen-free flame retardants to maintain European market access. Handheld devices with higher battery densities face the steepest certification timeline extensions.
Subscription stacking fatigue is altering how households evaluate entertainment spend trade-offs. Casual gamers are consolidating paid services and prioritizing libraries with family-sharing provisions over exclusive content depth. This recalibration is most visible in United States coastal metros where multiple streaming subscriptions already saturate discretionary budgets.
Connected Game Console Market Segmentation
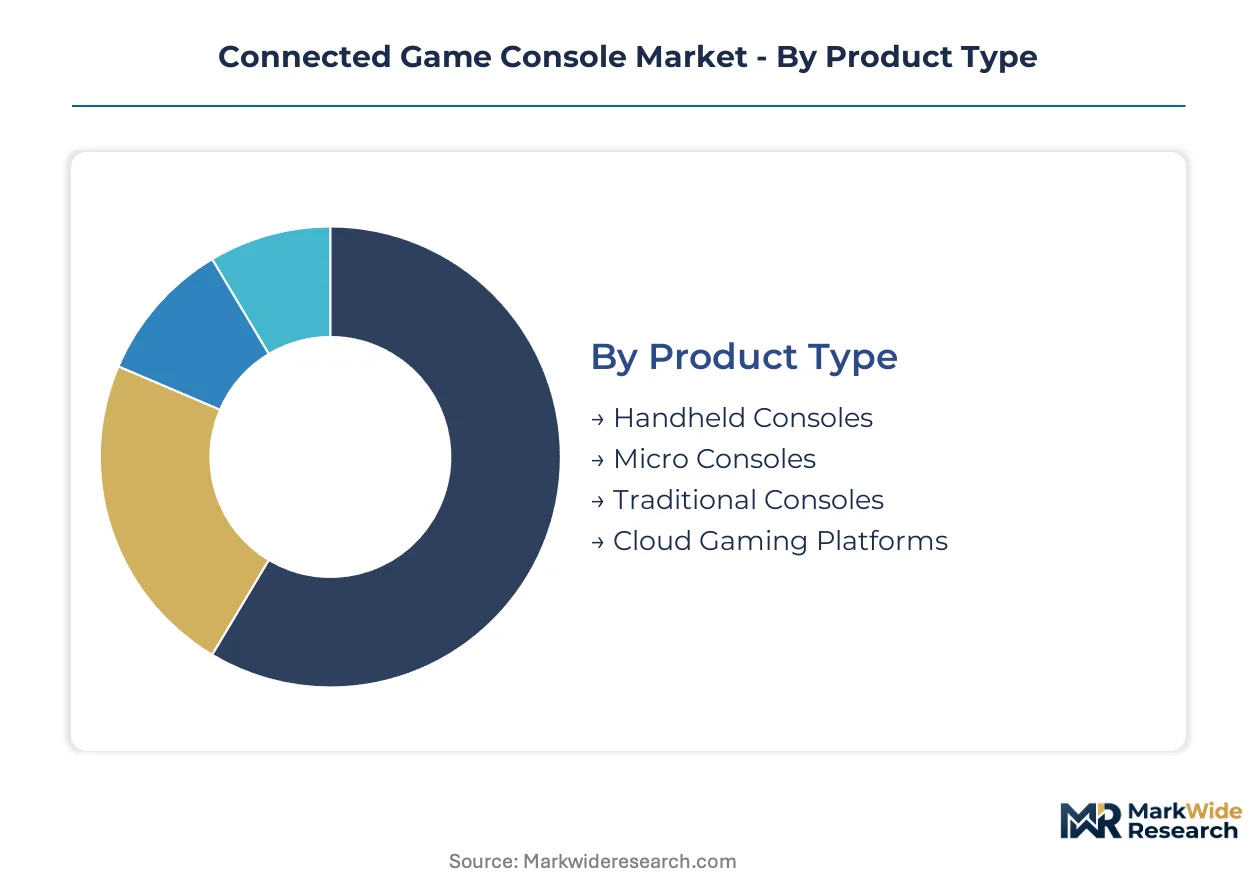
Segmentation in the connected game console market reveals how hardware form factors, user engagement patterns, and distribution economics split margin pools across fundamentally different business models. Understanding these divides helps stakeholders allocate R&D and channel investments where technology transitions are reshaping purchase behavior.
Product Type:
Form factor and processing architecture define the competitive set, with semiconductor efficiency gains redrawing the boundary between portable and stationary execution.
- Handheld Consoles:ARM-based SoC architectures now deliver AAA performance in battery-powered form factors, with demand concentrating in Japan and South Korea where dense urban transit use cases dominate. Nintendo's hybrid approach validates premium pricing outside traditional spec competition.
- Cloud Gaming Platforms:Latency-sensitive streaming infrastructure enables thin-client access to high-fidelity libraries, expanding fastest in United States coastal metros where FCC broadband benchmarks support sub-20ms round trips. Subscription bundling compresses hardware purchase cycles.
- Micro Consoles:Compact streaming sticks target secondary screens and emerging markets with limited upfront investment.
- Traditional Consoles:Custom x86 SoC architectures with discrete-class GPUs retain the largest installed base and margin pool through first-party exclusive pipelines.
Traditional consoles lead on scale; cloud gaming platforms lead on momentum.
End User:
Engagement intensity and session patterns determine monetization architecture, from one-time hardware sales to recurring service subscriptions.
- Casual Gamers:Fragmented session patterns favor cloud streaming and mobile-adjacent experiences, with demand concentrating in tier-two Indian cities where TRAI broadband subsidies expand addressable populations. Subscription stacking fatigue forces consolidation around family-sharing provisions.
- Hardcore Gamers:High-engagement users drive premium hardware cycles and first-party software attach rates, clustering in Germany and the United Kingdom where disposable entertainment spending remains resilient. Competitive multiplayer latency requirements favor local processing.
- Streamers:Content creators demand broadcast-integrated hardware with native capture and audience interaction tools.
- Families:Multi-user households prioritize parental control depth and content rating transparency under ESRB and PEGI frameworks.
Hardcore gamers anchor revenue per user; casual gamers expand the addressable base fastest.
Distribution Channel:
Channel economics reflect margin capture shifting from physical retail intermediaries toward first-party digital storefronts and direct fulfillment.
- Direct Sales:First-party digital distribution captures margin previously allocated to retail, with concentration in United States suburban markets where logistics density enables rapid fulfillment. Hardware-software bundling locks in subscriber lifetime value.
- Online Retailers:Platform-agnostic marketplaces compete on delivery speed and financing terms, gaining share in Brazilian and Mexican markets where e-commerce penetration in consumer electronics accelerates.
- Specialty Stores:Experiential retail maintains relevance for high-consideration purchases and trade-in programs.
- Big Box Retailers:Volume-driven seasonal promotions sustain hardware unit velocity during gift-giving periods.
Direct sales lead on margin retention; online retailers lead on geographic expansion.
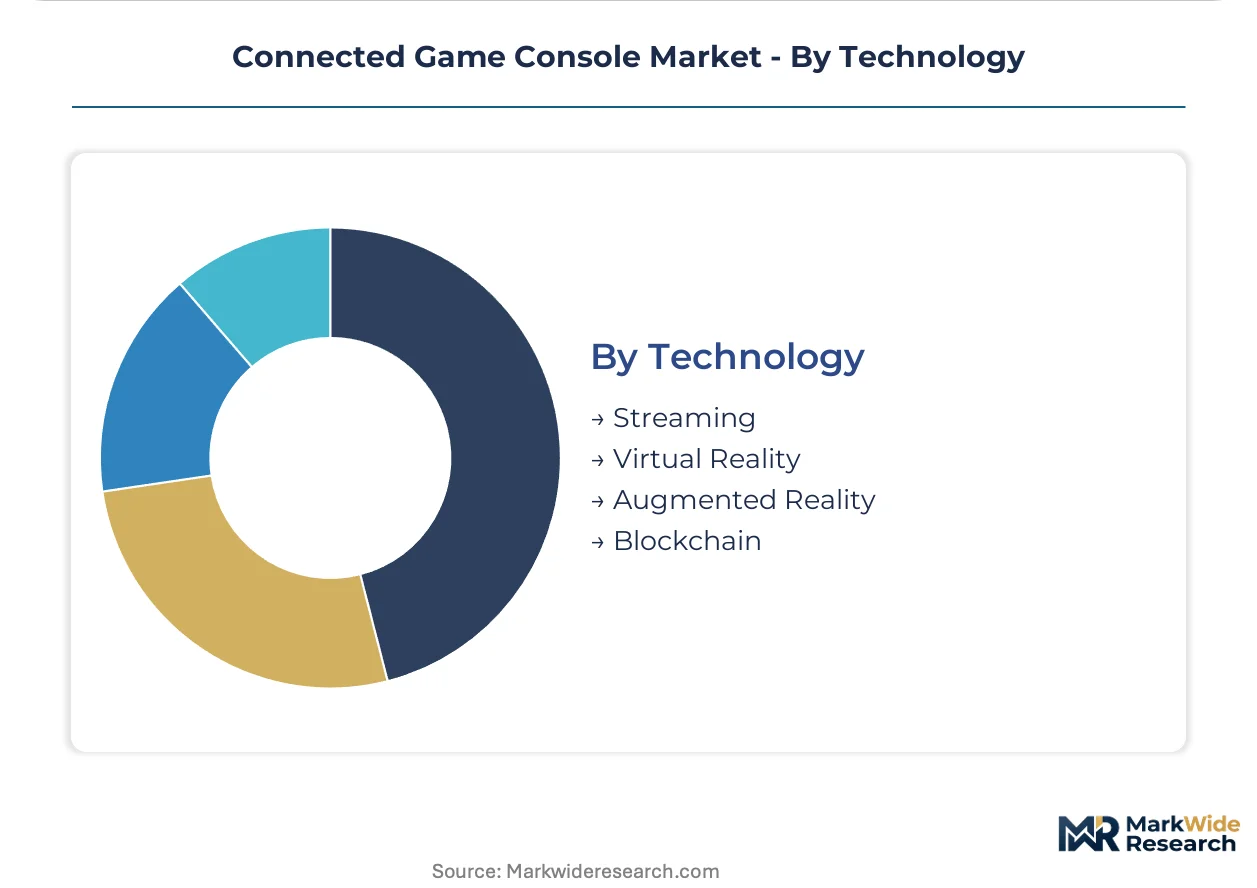
Technology:
Underlying technology stacks differentiate execution models, from local rendering to distributed processing and immersive display systems.
- Streaming:Edge computing convergence with predictive input buffering enables hybrid execution architectures, with investment concentrating in Netherlands and Sweden where data center proximity to population centers minimizes physics-bound latency.
- Virtual Reality:Tethered and standalone headsets demand specialized optics and tracking subsystems, facing REACH substance compliance complexity for European market access.
- Augmented Reality:Spatial computing overlays remain nascent in console-adjacent applications, constrained by field-of-view and battery limitations.
- Blockchain:Distributed ledger integrations for digital ownership verification attract speculative development, with regulatory uncertainty under SEC and EU MiCA frameworks limiting mainstream deployment.
Streaming leads on infrastructure investment; virtual reality leads on technical differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The connected game console industry traces its commercial origins to Japan's post-war electronics manufacturing clusters, where integrated circuit miniaturization first enabled affordable home computing entertainment.
United States
FCC broadband benchmark upgrades drive cloud gaming viability across coastal metros and secondary cities alike. The Commission's quality thresholds directly determine service addressable markets for latency-sensitive streaming platforms. Seattle and Austin anchor software engineering clusters where platform operators refine hybrid execution architectures.
Japan
Dense urban transit patterns sustain handheld console demand unmatched elsewhere in developed markets. METI semiconductor subsidies reinforce domestic SoC design capabilities for battery-efficient mobile processors. Tokyo-Osaka corridor concentration enables rapid prototyping cycles between hardware manufacturers and first-party studios.
Germany
EU AI Act algorithmic transparency mandates reshape content recommendation engine development for European distribution. REACH substance restrictions and RoHS amendments tighten material compliance timelines for console enclosures. Bavaria's precision manufacturing base supplies thermal management components for flagship hardware specifications.
South Korea
MFDS regulatory clarity on extended reality medical applications spills over into consumer VR peripheral certification pathways. World-leading fixed broadband penetration supports cloud gaming adoption at latency thresholds below 15 milliseconds. Seoul's Pangyo Techno Valley hosts edge computing facilities optimizing predictive input buffering.
India
TRAI broadband infrastructure subsidies expand addressable gaming populations in tier-two cities beyond Mumbai and Delhi. Central government PLI scheme incentives attract console assembly investment from multinational OEMs. Bengaluru's software corridor supplies backend engineering talent for platform localization and payment integration.
Connected Game Console Market Vendor Landscape
The competitive structure tilts toward integrated platform-service ecosystems rather than standalone hardware vendors. Three to five conglomerate-backed operators control the majority of installed base and recurring revenue pools. Strategic archetypes separate first-party content studios, cloud infrastructure operators, and hybrid hardware-software integrators. Dominant competitive moves include subscription bundling of hardware with content libraries and backward compatibility engineering to retain legacy customer migrations.
Within the integrated ecosystem tier, Sony Group Corporation, Microsoft Corporation, and Nintendo Co., Ltd. occupy positions defined by divergent architectural philosophies. Sony's Tokyo-based conglomerate structure exemplifies first-party studio pipeline anchoring. Microsoft's Redmond headquarters represents cloud-first service breadth across device categories. Nintendo's Kyoto operations occupy a position sustaining premium pricing through hardware-software integration outside specification competition.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Microsoft Corporation |
| Nintendo Co., Ltd. |
| Tencent Holdings Ltd. |
| Valve Corporation |
| Nvidia Corporation |
| Google LLC |
| Apple Inc. |
| Amazon.com, Inc. |
| Others |
Supply Flow & Price Mechanics
DRAM spot price indices cascade through console bill-of-materials into three distinct hardware pricing tiers, with memory cost volatility compressing margins on mid-range SKUs faster than flagship or entry-level alternatives. Contract negotiations for advanced node foundry capacity at TSMC and Samsung Foundry tether pricing power to semiconductor allocation cycles, while logistics costs from Asia-Pacific assembly hubs to North American and European distribution centers layer freight premiums onto landed hardware costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flagship consoles with discrete-class GPUs from handheld ARM-based systems and micro-console streaming sticks. Price differentiation rests on thermal design complexity and first-party software bundling depth, with premium tiers capturing subscribers through hardware-software lock-in. Cost compression in the standard tier intensifies because cloud gaming subscriptions displace hardware refresh urgency. Casual gamers in Indian tier-two cities exhibit highest price sensitivity, while hardcore German and UK users absorb premium pricing for exclusive content pipelines.
Supply Chain Analysis
Regional distribution centers in Netherlands and Germany operate hub-and-spoke patterns radiating into European retail channels, while United States fulfillment draws from Memphis and Louisville air cargo hubs. Component sourcing concentrates in Taiwan for custom SoC fabrication, Japan for precision thermal management subsystems, and South Korea for high-density memory modules. Raw material dependencies span rare earth elements for magnet assemblies, high-purity silicon wafers, and halogen-free flame retardants for REACH compliance. Single-source vulnerability at TSMC's N4 and N3 process nodes threatens flagship console launch cadences. Distribution runs through first-party digital storefronts capturing margin from direct-to-consumer hardware-software bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected game console market functions as a stable compounder where recurring subscription revenue from cloud gaming services dampens hardware cyclicality and sustains platform operator cash flows across console generations.
For Market Incumbents: Anchor subscriber retention through exclusive first-party studio output and backward compatibility engineering that reduces customer churn during hardware transitions. Cloud infrastructure operators represent the primary substitution threat as latency-sensitive streaming matures. Prioritize captive supply of advanced node foundry capacity through long-term offtake agreements with TSMC and Samsung Foundry. For New Entrants and Emerging Players: Direct-to-consumer digital storefronts offer the lowest-friction route to bypass retail margin extraction and establish hardware-software bundling relationships. White-space concentrates in Indian tier-two cities where TRAI broadband subsidies expand addressable populations without incumbent platform saturation. Target family-sharing subscription tiers where casual gamer consolidation creates entry points outside exclusive content arms races. For Investors and Strategic Acquirers: Asymmetric upside sits with edge computing infrastructure operators supplying predictive input buffering and hybrid execution architectures to platform operators. Five-to-ten-year viability favors companies controlling low-latency networking patents and real-time systems engineering talent pools. Monitor FCC broadband benchmark upgrades as the signal indicating expanded cloud gaming addressable markets in secondary United States metropolitan areas.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Studio Acquisition | Exclusive content pipelines anchor PlayStation Plus and Game Pass subscriber retention across hardware generations. |
| Edge Computing Infrastructure Partnership | Predictive input buffering deployments in Netherlands and Sweden reduce physics-bound latency for competitive multiplayer. |
| Direct-to-Consumer Storefront Expansion | Digital distribution captures retail margin and enables hardware-software bundling with subscriber lifetime value tracking. |
| Advanced Node Foundry offtake Agreement | TSMC N3 capacity commitments secure flagship SoC supply against single-source fabrication concentration risk. |
| Hybrid Execution Architecture Development | Split processing between local rendering and cloud streaming creates new service tiers for bandwidth-constrained users. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering directors, cloud infrastructure procurement leads, first-party studio executives, and retail channel partners with secondary validation against SEC filings, FCC broadband benchmark disclosures, hyperscaler capex reports, and ESRB content rating databases. Bottom-up console shipment modeling and top-down subscription revenue estimates triangulated market sizing across hardware form factors and service tiers.
Segment-weighting approaches applied differential growth assumptions across handheld, cloud, micro, and traditional console categories, with end-user splits between casual and hardcore gamers, and distribution channel shares for direct sales versus online and physical retail. CAGRs derived from installed base projections, replacement cycle compression effects, and subscription attach rate trajectories. Forecast inputs incorporated EU AI Act compliance timelines, REACH substance restriction amendments, and semiconductor node transition cadences.
The model assumes a particular technology adoption path; alternative pathways for ARM-based handheld AAA execution or standalone VR headset convergence would alter the outlook. Forecasts reflect documented assumptions regarding broadband infrastructure expansion rates, regulatory fragmentation between FCC and EU AI Act frameworks, and foundry capacity allocation priorities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Online Strategy Games Market
Gaming
Global Esports Market
Gaming
Global Tarot Cards Market
Gaming
VR Gaming Accessories Market
Gaming
Asia-Pacific Video Game Software Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
Global Game Testing Service Market
Gaming
France Online Gambling Market
Gaming
Online Casual Games Market
Gaming
VR Gaming Controller Market
Gaming
VR Racing Gaming Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Gaming Software Market
Gaming
India Gaming Market