
 Sugar Substitutes Market | 2026-2036
Sugar Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Substitutes Market Intelligence
ISO 22000 certification is collapsing the supplier base by disqualifying smaller fermenters and extractors from beverage-grade contracts. Cargill Incorporated leverages its vertically integrated stevia supply from South American leaf to finished Reb M. Tate & Lyle anchors European demand through its proprietary sucralose manufacturing in Singapore. Ajinomoto Co. Inc. dominates aspartame supply for tabletop and pharmaceutical applications through its amino acid fermentation expertise.
Sugar substitutes are non-nutritive or low-calorie compounds that provide sweetness without the metabolic glycemic load of sucrose, typically manufactured through fermentation, enzymatic conversion, or botanical extraction to achieve sweetness intensities ranging from 200 to 600 times that of sugar. Their primary commercial purpose centers on enabling calorie reduction in processed foods while maintaining consumer-acceptable taste profiles and functional properties like bulking and browning. Stevia extracts lead volume growth as beverage manufacturers replace artificial options, while erythritol captures margin pools in confectionery through its cooling effect and dental-friendly profile. Aspartame retains scale in tabletop sweeteners and pharmaceutical coatings despite clean-label headwinds.
The FDA governs GRAS self-affirmation and petition pathways for novel sweeteners, while the EPA regulates fermentation facility effluent from erythritol and xylitol bioreactors. EFSA's revised acceptable daily intake assessments for steviol glycosides directly shape European formulation ceilings and import tolerances. Stakeholders must monitor pending WHO guidance on non-sugar sweeteners and health outcomes, as any reclassification would force immediate reformulation across beverage and dairy alternative portfolios.
Market Dynamics
Beverage manufacturers are accelerating formulation shifts toward clean-label sweeteners as ISO 22000 certification collapses the supplier base and disqualifies smaller fermenters from beverage-grade contracts.
Growth Catalysts
- Clean-label mandates:Beverage manufacturers reformulate with stevia and erythritol to meet consumer expectations for recognizable ingredients, pulling volume away from artificial alternatives.
- Diabetic-friendly product expansion:Retail channels across the United States are expanding low-calorie product lines to serve prediabetic and diabetic populations seeking glycemic control.
- FDA labeling guidance:Updated FDA guidance on sweetener labeling accelerates manufacturer reformulation decisions and creates regulatory clarity for novel ingredient adoption.
Market Restraints
- Stevia leaf supply concentration:Premium Reb M production depends on South American leaf cultivation, exposing formulators to weather-driven harvest volatility and regional logistics constraints.
- Amino acid fermentation complexity:Aspartame manufacturing requires specialized amino acid fermentation expertise that concentrates production among limited suppliers with captive biotechnology capabilities.
- EFSA intake ceilings:Revised EFSA acceptable daily intake assessments for steviol glycosides directly constrain European formulation ceilings and limit maximum usage rates in single-serve beverages.
Strategic Opportunities
- Confectionery margin pools:Erythritol's cooling effect and dental-friendly profile create premium positioning opportunities in sugar-free confectionery applications where texture differentiation commands price premiums.
- Pharmaceutical coating applications:Aspartame retains stable demand in pharmaceutical tablet coatings and excipients, offering insulated volume against clean-label headwinds in food and beverage.
- WHO guidance anticipation:Stakeholders monitoring pending WHO guidance on non-sugar sweeteners and health outcomes can pre-position reformulation capabilities to respond to potential reclassification scenarios.
Industry Challenges
- Bioreactor effluent compliance:Erythritol and xylitol fermentation facilities face EPA effluent regulations requiring capital-intensive wastewater treatment upgrades to maintain operating permits.
- GRAS self-affirmation timelines:Novel sweetener developers navigate FDA petition pathways that extend commercialization timelines by 18-36 months and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Substitutes Market |
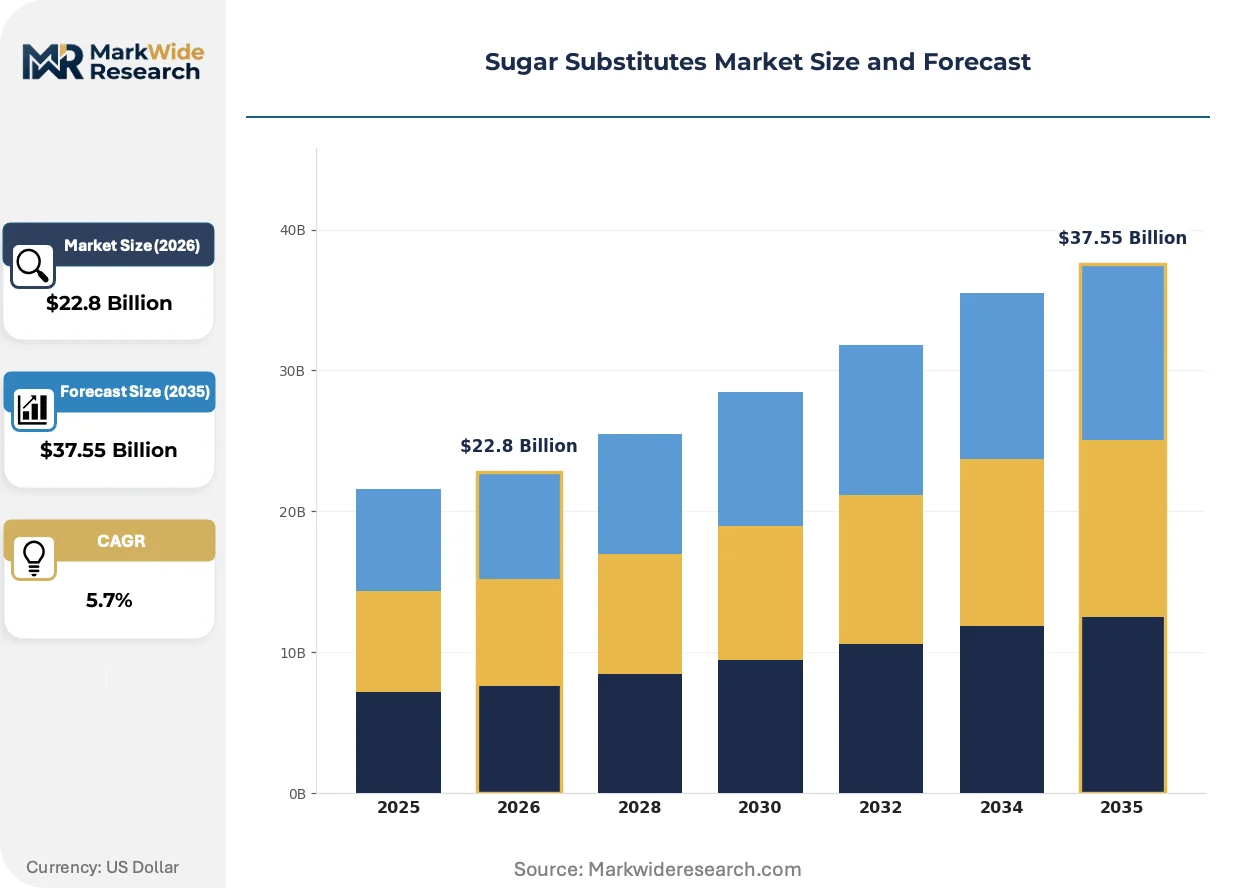
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Aspartame, Sucralose, Saccharin, Erythritol, Monk Fruit Application: Bakery Products, Beverages, Confectionery, Dairy Alternatives, Dietary Supplements, Sauces & Dressings End User: Food Processing Units, Beverage Manufacturers, Dietary Product Companies, Pharmaceutical Companies Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Stores, Wholesale Distributors |
| Companies Covered | Archer Daniels Midland Company, DuPont, Cargill Incorporated, JK Sucralose Inc., Ajinomoto Co. Inc., Ingredion Incorporated, Roquette Freres, SweeGen, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Substitutes Market Strategic Shifts & Innovations
Enzymatic conversion technologies and precision fermentation are rewriting cost curves for rare steviol glycosides while regulatory bodies on three continents recalibrate safety frameworks.
Enzymatic bioconversion of stevia leaf extract into Reb M is displacing traditional solvent-based extraction methods that yielded lower-purity glycoside mixtures. Large beverage manufacturers have adopted enzymatically produced Reb M at commercial scale since 2022. This displacement compresses cost differentials between natural and artificial high-intensity sweeteners and erodes the historical price premium for clean-label positioning.
EFSA's revised toxicological assessments for steviol glycosides are tightening formulation ceilings across European Union member states. Manufacturers must now reformulate to stay below revised acceptable daily intake thresholds or face import restriction. Dairy alternative portfolios and concentrated beverage bases in Germany, France, and Italy are most affected, with formulators blending multiple sweeteners to achieve target sweetness intensity without exceeding single-ingredient limits.
Direct-to-manufacturer procurement of certified sweetener grades is consolidating purchasing decisions away from traditional ingredient distributors. Large beverage and dairy processors now contract directly with ISO 22000-certified fermenters and extractors, bypassing regional distributors. This channel compression is most visible in North American and Western European markets where buyer concentration and volume scale justify dedicated supply agreements with audit rights and traceability requirements.
Sugar Substitutes Market Segmentation
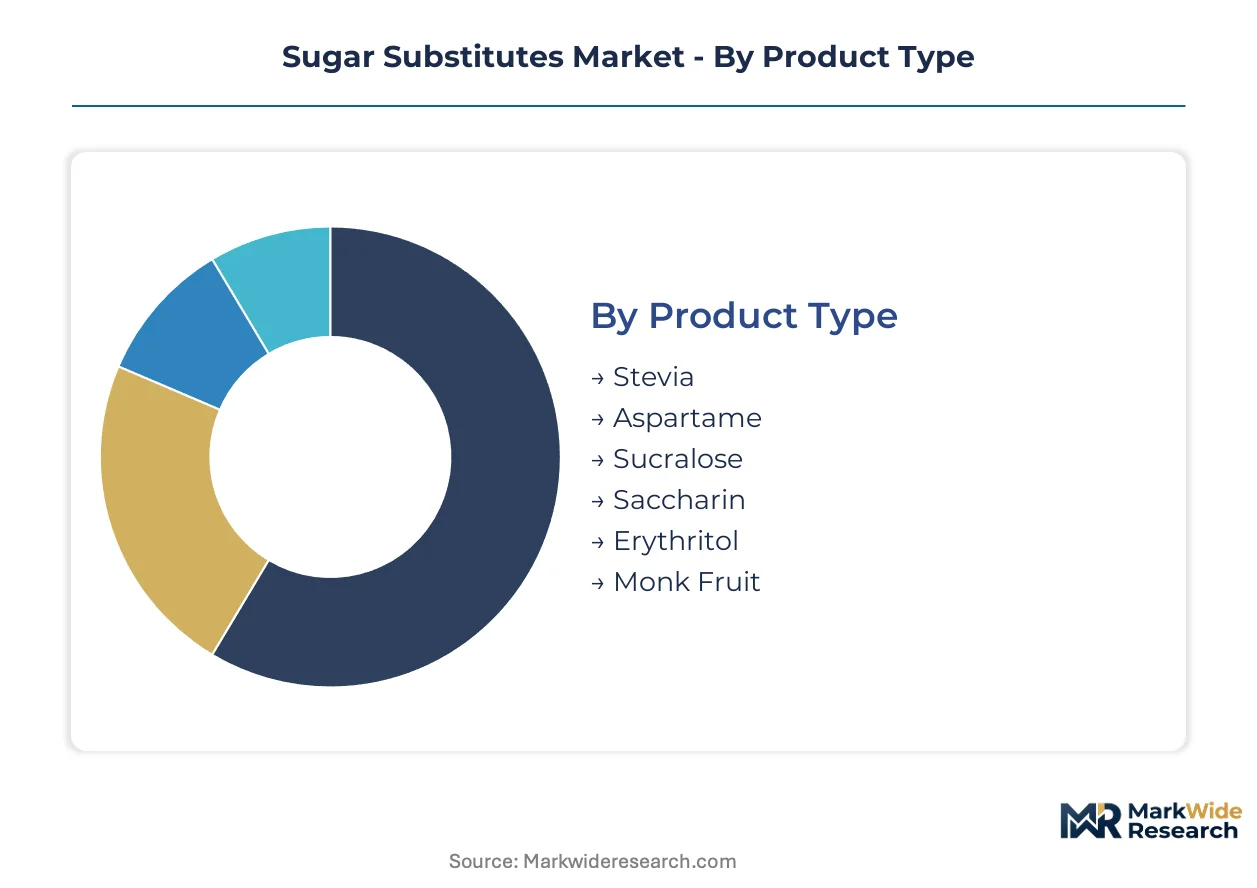
Sweetener procurement patterns fragment sharply across product grades and application requirements. ISO 22000 certification and direct-to-manufacturer contracting reshape which segments flow through traditional distribution versus dedicated supply agreements.
Product Type:
Channel mix varies by extraction complexity and certification tier, with enzymatically converted steviol glycosides bypassing distributors entirely.
- Stevia:Enzymatic bioconversion yields high-purity Reb M for beverage-grade contracts. Large North American processors contract directly with South American leaf suppliers and enzymatic converters, bypassing traditional ingredient distributors.
- Erythritol:Fermentation-derived polyol with cooling effect and zero glycemic impact. Confectionery manufacturers in Germany and France source through wholesale distributors for mid-volume applications, while major brands negotiate direct supply with ISO 22000-certified bioreactor facilities.
- Aspartame:Amino acid fermentation product concentrated among specialized suppliers.
- Sucralose:Chlorinated sugar derivative manufactured through multi-step chemical synthesis.
- Saccharin:Benzoic sulfimide compound retaining tabletop and industrial applications.
- Monk Fruit:Mogroside extract from Southeast Asian cultivation gaining clean-label positioning.
Stevia dominates installed base. Erythritol is where expansion concentrates.
Application:
Cost tier separation drives procurement channel selection, with premium clean-label applications commanding direct supply relationships.
- Beverages:Largest volume sink for high-intensity sweeteners. Carbonated soft drink and ready-to-drink tea manufacturers in the United States and Western Europe contract directly with stevia extractors and enzymatic converters, eliminating distributor margins for certified grades.
- Confectionery:Texture-critical applications favor erythritol and polyol blends. Sugar-free chocolate and hard candy producers balance cost tiers through wholesale distributors for standard grades while reserving direct supply for dental-certified premium lines.
- Bakery Products:Bulking agent requirements favor polyol and rare sugar combinations.
- Dairy Alternatives:EFSA intake ceilings constrain stevia loading in European oat and almond milk formulations.
- Dietary Supplements:Tablet and powder applications retain aspartame for coating and excipient functions.
- Sauces & Dressings:Acid-stable sweetener demand from ketchup and salad dressing manufacturers.
Beverages anchor volume scale. Confectionery commands the steepest expansion trajectory.
End User:
Customer type determines supply chain configuration, with beverage and pharmaceutical sectors pursuing opposite procurement strategies.
- Beverage Manufacturers:Consolidated buyers with dedicated supply agreements. ISO 22000 audit rights and traceability requirements are standard contract terms for North American and Western European operations.
- Food Processing Units:Fragmented base spanning bakery, sauce, and prepared food manufacturers. Procurement runs through wholesale distributors and specialty ingredient suppliers due to smaller volume scale and less stringent certification requirements.
- Dietary Product Companies:Hybrid procurement mixing distributor relationships for development volumes with direct supply for scaled launches.
- Pharmaceutical Companies:Insulated demand for aspartame in tablet coatings and excipients, sourced through validated pharmaceutical-grade distributors with GMP documentation.
Beverage manufacturers dominate direct contracting. Food processing units sustain distributor channel viability.
Distribution Channel:
Maturity gradient separates established retail formats from emerging digital procurement.
- Wholesale Distributors:Traditional channel for mid-tier food processors and regional beverage manufacturers. Inventory pooling and technical support services justify margin capture for buyers lacking volume scale for direct supply.
- Supermarkets & Hypermarkets:Primary channel for tabletop sweetener retail sales. Private-label stevia and erythritol products compete with branded aspartame and sucralose offerings on shelf placement and price positioning.
- Online Retailers:Growing share for specialty and organic-certified sweeteners. Direct-to-consumer monk fruit and rare steviol glycoside sales bypass traditional retail markup structures.
- Specialty Stores:Health food and diabetic supply outlets serving niche glycemic-control product demand.
Wholesale distributors retain institutional volume. Online retailers are climbing the fastest among consumer-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling guidance and EFSA intake ceilings are redirecting formulation investments toward certified supply chains in specific national markets. Beverage manufacturers in countries with stringent food safety frameworks command premium positioning through direct contracting with ISO 22000-certified extractors and fermenters.
United States
Clean-label mandates from Coca-Cola and PepsiCo are accelerating stevia and erythritol adoption in carbonated soft drinks and ready-to-drink teas. The FDA's updated sweetener labeling guidance provides regulatory clarity that reduces reformulation risk for novel ingredients. Chicago and Atlanta anchor beverage R&D clusters where manufacturers negotiate dedicated supply agreements with South American leaf processors.
Germany
EFSA's revised acceptable daily intake assessments for steviol glycosides are forcing dairy alternative formulators to blend multiple sweeteners beneath single-ingredient thresholds. The country's federal food safety authority enforces strict import tolerances that disqualify uncertified Asian suppliers. Bavaria's food technology corridor hosts confectionery manufacturers sourcing erythritol through wholesale distributors for mid-volume chocolate applications.
China
Domestic stevia cultivation in Guangxi and Yunnan provinces is expanding to serve both export demand and local beverage reformulation. SAMR's national food safety standards for sweetener labeling are converging with Codex Alimentarius frameworks to reduce technical barriers. The Yangtze River Delta concentration of flavor houses is driving precision fermentation investments for rare steviol glycoside production.
Brazil
Stevia leaf cultivation in Mato Grosso do Sul and Paraná is capturing margin from Asian competitors through vertically integrated extraction facilities. ANVISA's accelerated approval pathways for novel food ingredients are shortening commercialization timelines for enzymatically converted Reb M. São Paulo's beverage formulation labs are testing reduced-sugar prototypes for export to Mercosur markets.
Japan
Ajinomoto's amino acid fermentation expertise anchors domestic aspartame supply for pharmaceutical and tabletop applications resistant to clean-label substitution. METI's functional food labeling system creates premium positioning for rare sugar substitutes in senior nutrition products. The Kansai industrial corridor maintains specialized bioreactor capacity for high-purity polyol production serving confectionery exporters.
Sugar Substitutes Market Key Industry Players
Player mix skews toward diversified ingredient conglomerates with captive biotechnology capabilities and regional specialists with fermentation expertise. Three to five integrated multinationals control bulk volume through backward integration into leaf supply and enzymatic conversion infrastructure. Strategic archetypes include stevia-focused botanical extractors, amino acid fermentation specialists, and polyol bioreactor operators. Dominant competitive moves encompass direct-to-manufacturer contracting that eliminates distributor margins and ISO 22000 certification investments that collapse the supplier base.
Within the diversified conglomerate tier, Cargill Incorporated and Tate & Lyle occupy positions defined by geographic supply chain control. Cargill's South American leaf sourcing anchors stevia supply from cultivation through finished Reb M. Tate & Lyle's Singapore manufacturing base anchors European sucralose demand. Among amino acid fermentation specialists, Ajinomoto Co. Inc. exemplifies production concentration through biotechnology capabilities that limit viable competitors. These three entities represent distinct strategic archetypes rather than interchangeable substitutes.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| DuPont |
| Cargill Incorporated |
| JK Sucralose Inc. |
| Ajinomoto Co. Inc. |
| Ingredion Incorporated |
| Roquette Freres |
| SweeGen |
| Tate & Lyle |
| Others |
Cost & Logistics Intelligence
Ninety-day leaf-to-extract lead times for South American stevia shipments concentrate pricing power among ISO 22000-certified processors with captive enzymatic conversion capacity, while uncertified fermenters face margin compression from direct-to-manufacturer contracting that eliminates distributor buffers.
Pricing Analysis
Certification level creates the primary spread across the market, with ISO 22000 beverage-grade Reb M commanding substantial premiums over uncertified extract grades used in tabletop applications. Three-tier pricing structure across premium enzymatic-converted, standard solvent-extracted, and economy-grade blended glycosides reflects purity differentials and regulatory compliance depth. Cost compression in standard stevia tiers is intensifying because enzymatic bioconversion is displacing traditional extraction methods and eroding historical clean-label premiums. Beverage manufacturers with dedicated supply agreements show least price sensitivity due to reformulation lock-in costs, while regional confectionery producers remain most exposed to spot-market volatility.
Supply Chain Analysis
Strategic stockpiling of stevia leaf dominates procurement strategy among large North American beverage processors, while European formulators favor just-in-time erythritol deliveries from certified bioreactor facilities to minimize working capital tied to polyol inventory. Supply concentrates in Paraguay and Brazil for leaf cultivation, China for fermentation-derived polyols, and Singapore for sucralose synthesis. Raw material dependencies span South American stevia leaf, corn-derived dextrose for erythritol fermentation, and amino acid feedstocks for aspartame production. Single-source vulnerability runs through concentrated Reb M enzymatic conversion capacity. Distribution runs through wholesale distributors for mid-tier food processors lacking volume scale for direct supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of amino acid fermentation expertise and enzymatic bioconversion capabilities limits viable supplier expansion, concentrating margin capture among incumbents with captive biotechnology infrastructure.
For Market Incumbents: Shield installed base by accelerating backward integration into South American leaf supply and securing dedicated enzymatic conversion capacity ahead of competitor expansion. Prioritize ISO 22000 certification investments to disqualify smaller fermenters from beverage-grade contracts and collapse viable supplier alternatives. Defend against clean-label substitution by locking multi-year direct supply agreements with Coca-Cola and PepsiCo reformulation teams. For New Entrants and Emerging Players: Anchor in pharmaceutical coating applications where aspartame demand remains insulated from clean-label headwinds and regulatory switching costs are lowest. Target white-space in monk fruit mogroside extraction for premium organic-certified tabletop positioning. Pursue direct-to-manufacturer go-to-market through specialty ingredient distributors serving mid-volume confectionery producers in Germany and France. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized sweetener divisions lacking enzymatic conversion capabilities. Long-term viability favors assets with demonstrated FDA GRAS petition success and established South American leaf sourcing relationships. Watch WHO guidance publication timelines as the critical inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Conversion Scale-Up | Reduces Reb M production costs to parity with artificial high-intensity sweeteners. |
| Backward Integration into Leaf Supply | Secures South American cultivation capacity against weather-driven harvest volatility. |
| ISO 22000 Certification Investment | Qualifies suppliers for direct-to-manufacturer beverage contracts and collapses competitor base. |
| Pharmaceutical-Grade Capacity Expansion | Captures stable aspartame demand in tablet coatings resistant to clean-label substitution. |
| Direct-to-Manufacturer Contracting | Eliminates distributor margins and locks reformulation partnerships with PepsiCo and Coca-Cola. |
Research Approach
Initial hypotheses were tested against primary input from beverage formulation scientists, procurement directors at sweetener-consuming multinationals, fermentation facility operations managers, and regulatory affairs specialists at FDA and EFSA, then refined through secondary validation against FDA GRAS notices, EFSA scientific opinions, customs trade data for stevia leaf and extract flows, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand calculations from end-use consumption patterns.
Variance decomposition across the projection horizon separates volume drivers from price-mix effects and regulatory scenario impacts. Segmentation dimensions modeled include sweetener type, application category, end-user archetype, and certification tier. CAGRs were derived from fitted growth curves calibrated to historical adoption rates and forward-looking reformulation announcements. Industry-specific inputs incorporated enzymatic conversion cost curves, EFSA intake ceiling compliance requirements, and WHO guidance anticipation effects.
Decision-makers should treat outputs as directional under assumptions of continued clean-label preference acceleration and stable FDA GRAS pathways for novel sweeteners; material deviation would warrant model refresh. Revision becomes warranted when WHO guidance on non-sugar sweeteners crosses thresholds forcing immediate reformulation across beverage portfolios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Sucralose Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Cassava Syrup Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
South Korea Allulose Market
Sweeteners
North America Stevia Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Methyl Glucose Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Invert Sugar Market
Sweeteners
Trehalose Market
Sweeteners
Xylose Market