
 Marine Steering Systems Market | 2026-2036
Marine Steering Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Steering Systems Market Outlook
Recreational boat owners are unwinding the once-dominant share held by commercial fleet operators in aftermarket steering upgrades. Kongsberg Maritime leverages its hydroacoustic heritage to dominate dynamic positioning-integrated steering for offshore vessels. ZF Friedrichshafen anchors the European supply base through captive production of precision hydraulic actuators for commercial applications. Mercury Marine competes aggressively in the outboard-powered recreational segment with proprietary steering ecosystems.
Marine steering systems encompass the mechanical, hydraulic, and electronic assemblies that translate helm input into rudder or outboard movement, typically operating at hydraulic pressures between 1,000 and 3,000 psi in heavy-duty commercial configurations to ensure reliable vessel control under extreme sea states. Their primary purpose is to maintain course stability, enable precise maneuvering in confined waterways, and reduce operator fatigue across vessels ranging from small pleasure craft to ocean-going cargo ships. Electronic systems represent the fastest-expanding product category as steer-by-wire architectures displace mechanical linkages in newbuild recreational and naval contracts. Hydraulic systems still command the largest installed base among cargo ships and older commercial fleets, though margin pools are shifting toward integrated systems that bundle autopilot, joystick, and dynamic positioning functions.
The US Coast Guard and FCC shape equipment certification for domestic commercial operators, while the EU's CE marking and MDR frameworks govern product safety and electromagnetic compatibility across European waters. Japan's METI and JIS standards enforce reliability benchmarks for steering gear installed on vessels calling at Japanese ports, creating a compliance threshold for export-oriented manufacturers. Stakeholders must monitor how steer-by-wire cybersecurity standards evolve across flag-state regimes before committing to next-generation platform architectures.
Market Dynamics
Steer-by-wire architectures are compressing the traditional hydraulic supply chain as superyacht builders and naval contractors demand integrated helm-to-rudder digital pathways. This shift is redistributing margin pools from mechanical component suppliers toward software-integrated system architects.
Growth Catalysts
- F-Gas Regulation:The EU's phasedown of fluorinated greenhouse gases is forcing shipyards to abandon leak-prone hydraulic fluids in favor of sealed electronic steering circuits.
- Dynamic positioning convergence:Offshore support vessels now require steering systems that synchronize with GPS-hold algorithms, pulling integrated package demand from North Sea oil-service operators.
- Hamburg-Bremen engineering cluster:Germany's dense concentration of marine equipment R&D is accelerating prototype-to-production cycles for next-generation steering gear.
Market Restraints
- Specialized steel casting concentration:Rudder stocks and tiller arms rely on forged alloy inputs from a limited supplier base in East Asian heavy foundries.
- CE marking friction:The EU's MDR conformity assessment timeline adds 8-14 months to electronic steering system certification, delaying revenue recognition for new entrants.
- Mechanical linkage residual value:Aging commercial fleets in developing flag states retain hydraulic systems due to lower technical skill requirements for at-sea repair.
Strategic Opportunities
- Recreational retrofit channel:Outboard-powered boat owners in Florida and the Mediterranean are upgrading to electronic steering without full vessel replacement.
- Autonomous vessel protocols:The convergence of AI-driven collision avoidance with redundant steering actuators creates a new product tier for unmanned surface vehicle builders.
- Japanese port compliance:METI reliability benchmarks for vessels calling at Yokohama and Osaka are creating a certified-product premium that rewards early standardization investment.
Industry Challenges
- Cybersecurity certification gaps:No unified IEC 62443 implementation standard exists for steer-by-wire systems across flag-state regimes, forcing redundant testing.
- Electro-hydraulic integration complexity:Shipyards face commissioning delays when merging legacy hydraulic rudders with new electronic helm interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Steering Systems Market |
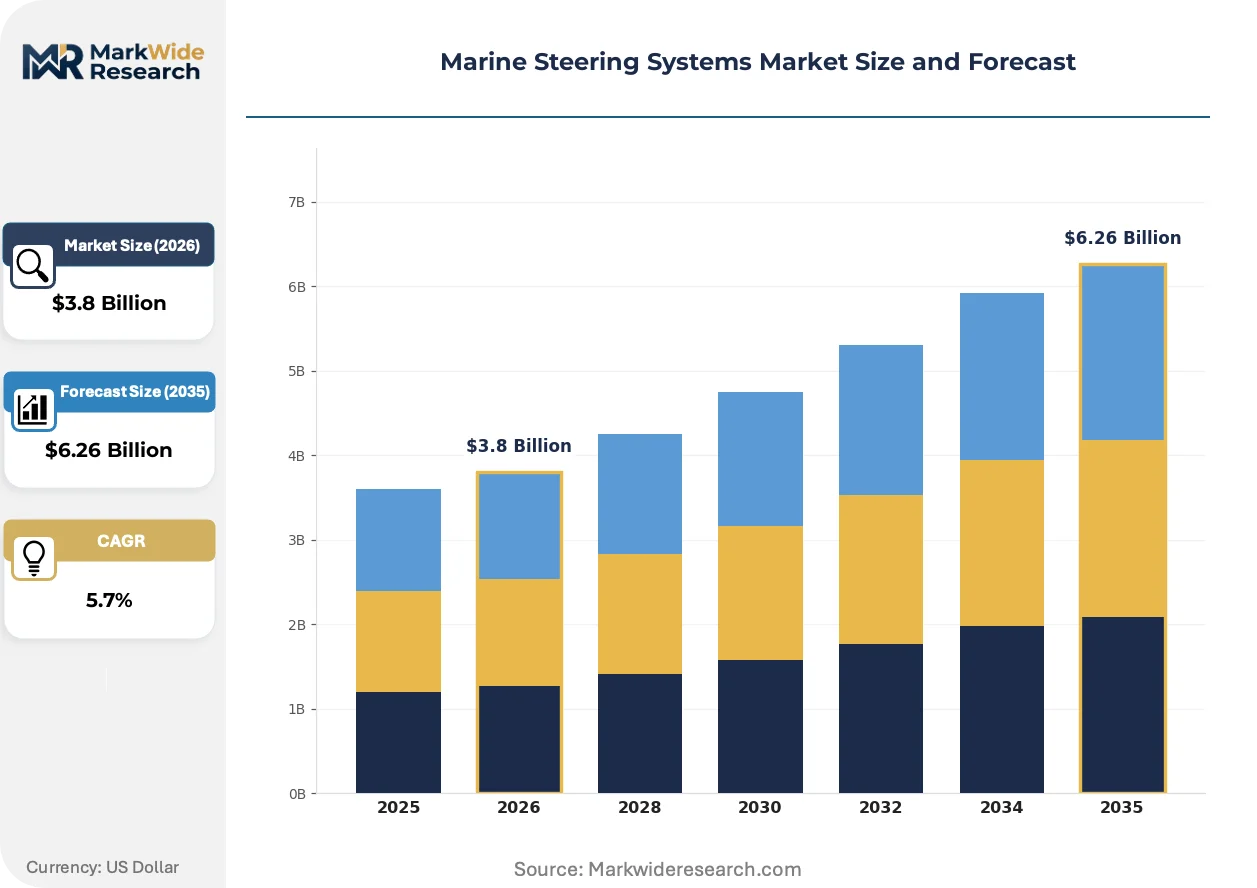
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Systems, Mechanical Systems, Electronic Systems, Integrated Systems Application: Commercial Vessels, Recreational Boats, Naval Ships, Cargo Ships End User: Shipbuilders, Fleet Operators, Maintenance Providers, Recreational Users Technology: Steer-by-Wire, Power Steering, Joystick Control, Traditional Mechanical |
| Companies Covered | Kongsberg Maritime, ZF Friedrichshafen AG, Mercury Marine, Bosch Rexroth, Dometic Marine, Wärtsilä, Northrop Grumman Sperry Marine, SeaStar Solutions, Vetus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Steering Systems Market Strategic Shifts
Digital helm architectures are collapsing the traditional separation between navigation, propulsion, and steering control. This convergence is redrawing competitive boundaries and forcing suppliers to recalibrate their hardware-software mix.
Steer-by-wire systems eliminate mechanical feedback paths between wheel and rudder, replacing them with torque-motor actuators and position sensors. Superyacht builders in northern Italy and the Netherlands are specifying these packages for vessels above 40 meters LOA. Electronic redundancy is supplanting hydraulic backup circuits as the preferred failsafe architecture, compressing demand for standalone power-steering pumps.
The EU's F-Gas Regulation mandates refrigerant and fluid containment protocols that directly affect hydraulic steering maintenance practices. Shipyards in Germany and France now face mandatory leak-detection systems and fluid-recovery documentation. Commercial operators running intra-European routes are accelerating electronic steering adoption to sidestep compliance costs and port-state inspection delays.
Recreational buyers are unbundling steering upgrades from full vessel replacement cycles. Marine dealerships in coastal Florida and the French Riviera report rising attachment rates for electronic helm retrofits on outboard boats aged 5-12 years. This behavior is shortening the effective replacement cycle for steering components and shifting aftermarket revenue toward electronics-heavy service packages.
Marine Steering Systems Market Segmentation
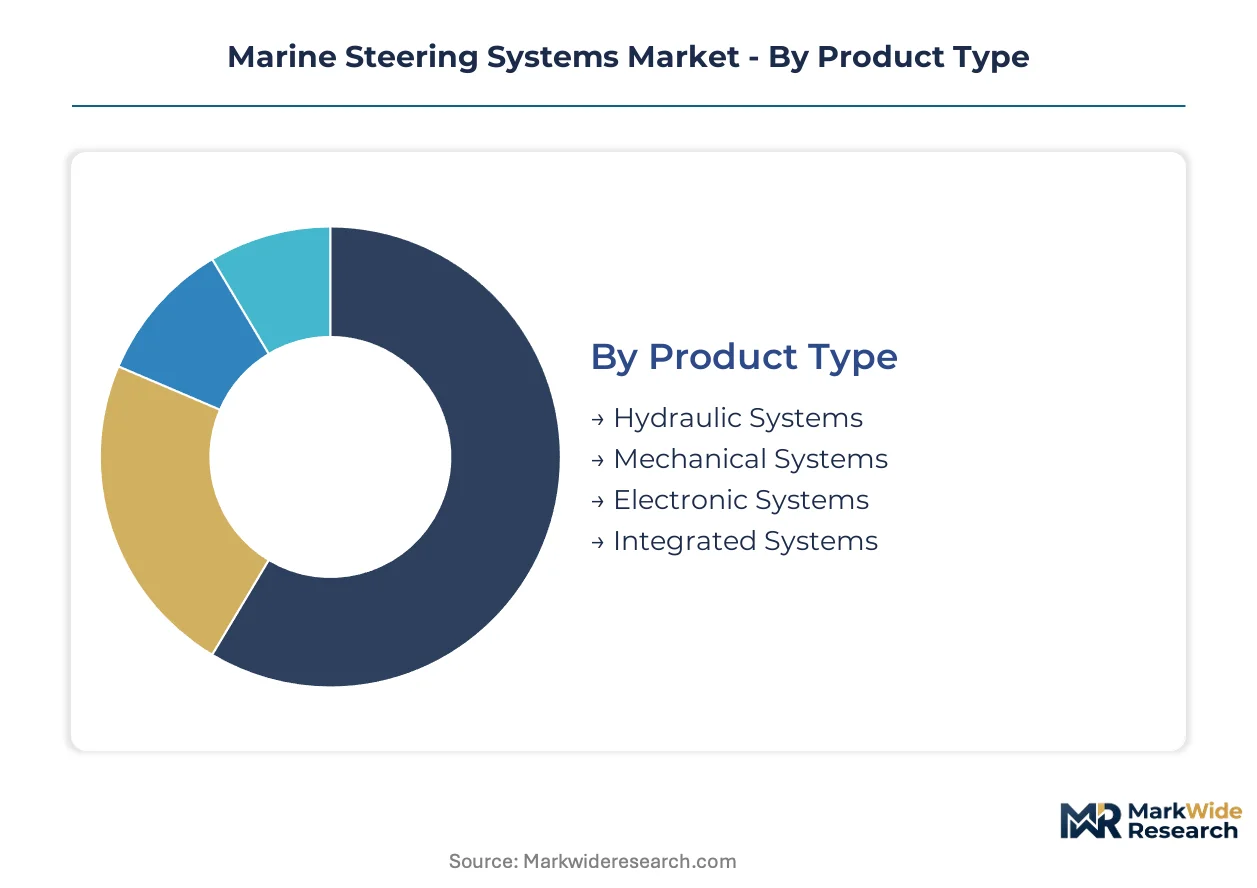
Marine steering systems fragment across four intersecting dimensions that determine procurement channels and margin capture. Product type governs whether sales flow through OEM shipyard contracts or aftermarket service networks, while application scope dictates regulatory compliance burdens and technology refresh cycles.
Product Type:
Hydraulic systems move through fleet operator maintenance contracts and shipyard refit programs, whereas electronic packages concentrate in newbuild superyacht and naval contracts.
- Hydraulic Systems:These assemblies operate at 1,000-3,000 psi using mineral oil or water-glycol fluids to translate helm torque into rudder movement. Demand concentrates among cargo ship operators in Hamburg and Singapore seeking proven reliability under extreme sea states. The EU's F-Gas Regulation is accelerating replacement timelines for leak-prone hydraulic circuits.
- Electronic Systems:Torque-motor actuators and position sensors replace mechanical feedback paths between wheel and rudder. Recreational boat owners in Florida and the Mediterranean are driving retrofit demand for outboard-powered vessels aged 5-12 years. These systems sidestep fluid containment compliance costs that burden hydraulic alternatives.
- Mechanical Systems:Cable-and-pulley linkages persist in developing flag states where at-sea repair capability favors low-technical-skill maintenance.
- Integrated Systems:Bundled autopilot, joystick, and dynamic positioning functions command premium positioning in offshore support vessels operating North Sea oil-service routes.
Hydraulic systems dominate installed base. Electronic systems are where expansion concentrates.
Application:
Cost tier stratification separates military-grade redundant architectures from price-sensitive recreational configurations.
- Commercial Vessels:Offshore support vessels and ferry operators specify integrated steering packages that synchronize with GPS-hold algorithms. METI reliability benchmarks for vessels calling at Yokohama and Osaka create certified-product premiums for this segment.
- Cargo Ships:Aging fleets in developing flag states retain hydraulic systems due to residual value considerations and lower technical skill requirements for at-sea repair.
- Recreational Boats:Electronic helm retrofits shorten effective replacement cycles for steering components in coastal Florida and French Riviera markets.
- Naval Ships:Redundant steer-by-wire architectures with cybersecurity-hardened actuators meet military specification requirements.
Cargo ships anchor volume. Commercial vessels are climbing the fastest.
End User:
Customer type determines whether procurement emphasizes total cost of ownership or upfront capital efficiency.
- Shipbuilders:Northern Italian and Dutch superyacht yards specify steer-by-wire packages for vessels above 40 meters LOA, compressing demand for standalone power-steering pumps.
- Fleet Operators:Intra-European route operators accelerate electronic steering adoption to avoid port-state inspection delays tied to hydraulic fluid documentation.
- Maintenance Providers:Marine dealerships report rising attachment rates for electronic helm retrofits unbundled from full vessel replacement cycles.
- Recreational Users:Outboard-powered boat owners upgrade steering without vessel replacement, shifting aftermarket revenue toward electronics-heavy service packages.
Fleet operators command procurement volume. Shipbuilders concentrate technology leadership.
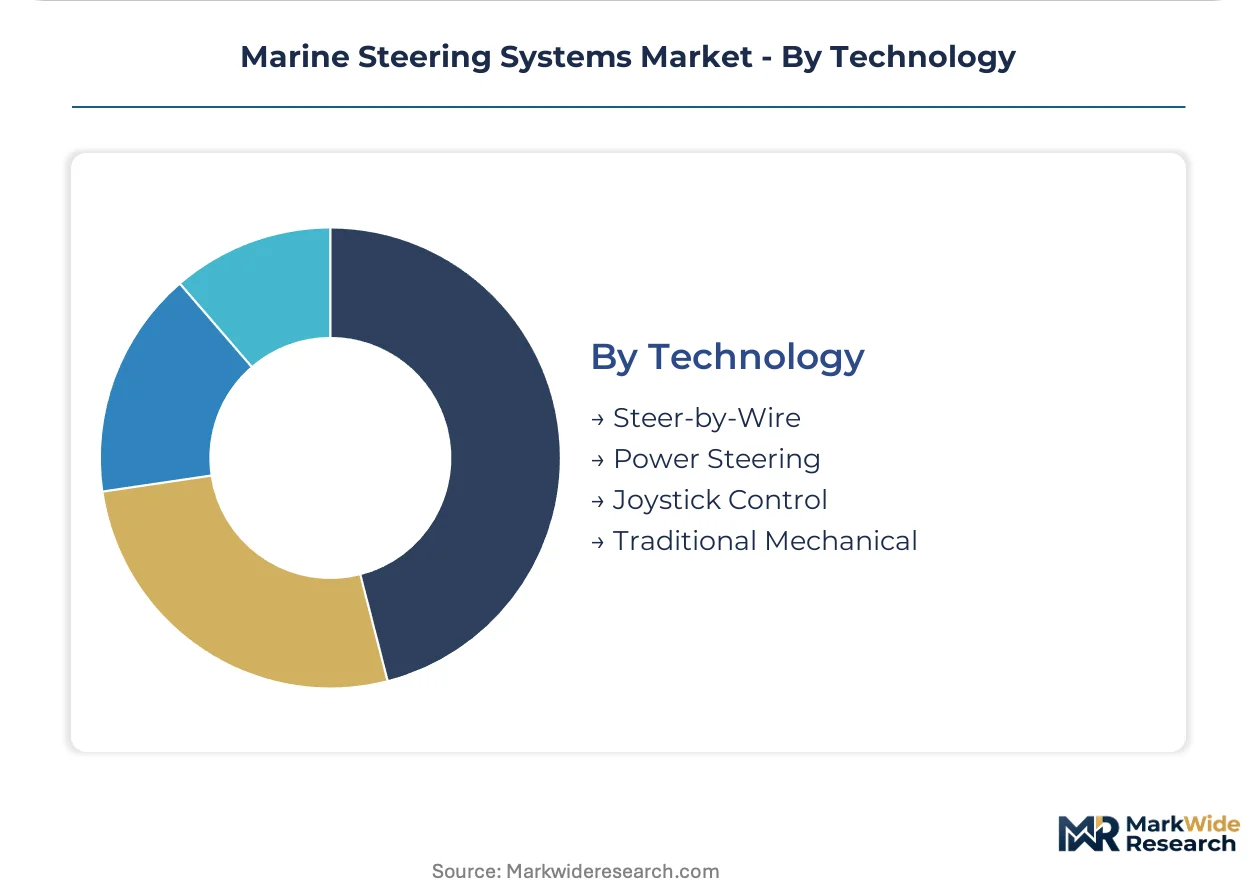
Technology:
Maturity curves separate legacy mechanical dominance from emerging digital architectures.
- Steer-by-Wire:Digital helm-to-rudder pathways eliminate mechanical linkages entirely. Superyacht builders and naval contractors demand these packages for integrated vessel management systems.
- Joystick Control:Precision maneuvering in confined waterways drives adoption among marina-operated charter fleets.
- Power Steering:Hydraulic assistance modules persist in mid-size commercial vessels where electronic redundancy remains cost-prohibitive.
- Traditional Mechanical:Cable systems retain niche positioning in small pleasure craft and developing-market commercial fleets.
Traditional mechanical retains residual volume. Steer-by-wire is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German marine equipment exports flow predominantly to Dutch superyacht builders and Norwegian offshore operators, anchoring a North Sea supply corridor that shapes steering system procurement patterns across northern Europe.
Germany
Shipyards in Hamburg and Bremen drive demand for integrated electronic steering packages as EU F-Gas Regulation compliance tightens. The MDR conformity assessment framework governs certification timelines for new electronic helm systems. The Hamburg-Bremen engineering cluster compresses prototype-to-production cycles through dense supplier networks.
Netherlands
Superyacht builders above 40 meters LOA specify steer-by-wire architectures from northern Italian and domestic yards. CE marking requirements under the EU's MDR framework extend certification periods for electronic steering components. The Amsterdam-Rotterdam corridor concentrates refit activity for electronic helm upgrades on aging pleasure craft.
United States
Recreational boat owners in Florida unbundle electronic steering retrofits from full vessel replacement cycles. The US Coast Guard and FCC shape equipment certification for commercial operators navigating domestic waters. Marine dealerships along the Gulf Coast report rising attachment rates for outboard-powered craft aged 5-12 years.
Japan
METI reliability benchmarks for vessels calling at Yokohama and Osaka create certified-product premiums for steering gear suppliers. JIS standards enforce technical specifications that filter import eligibility for foreign manufacturers. The Nagoya-Chubu industrial belt hosts precision actuator fabrication for domestic shipbuilder contracts.
Singapore
Cargo fleet operators maintain hydraulic steering systems under extreme sea state conditions for intra-Asian routes. The Maritime and Port Authority enforces safety standards that align with IMO conventions for vessel equipment. The Tuas marine hub concentrates maintenance provider networks serving aging commercial fleets.
Marine Steering Systems Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and technology integration dimensions, producing a tiered structure where scale-driven conglomerates share terrain with focused component architects. Consolidation pressure runs highest in electronic steering segments where software development costs favor integrated platform providers. Three archetypes dominate: diversified industrial conglomerates with captive marine divisions, pure-play steering system specialists, and navigation-electronics firms extending into helm control. Competitive moves concentrate on M&A for sensor technology access and strategic partnerships for cybersecurity-hardened actuator development.
Among diversified industrial conglomerates, ZF Friedrichshafen AG and Bosch Rexroth exemplify the European supply base archetype, while Kongsberg Maritime occupies a position representing hydroacoustic-heritage players extending into dynamic positioning-integrated steering. These three anchors span distinct strategic postures: precision hydraulic actuator production, industrial automation cross-over, and offshore vessel specialization.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| ZF Friedrichshafen AG |
| Mercury Marine |
| Bosch Rexroth |
| Dometic Marine |
| Wärtsilä |
| Northrop Grumman Sperry Marine |
| SeaStar Solutions |
| Vetus |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates both supplier qualification and price differentiation simultaneously, forcing shipyards to abandon leak-prone hydraulic circuits for sealed electronic architectures that command certification premiums. This regulatory threshold compresses margin pools for uncertified mechanical component suppliers while redistributing value toward software-integrated system architects with documented fluid-recovery protocols.
Pricing Analysis
Next-generation steer-by-wire packages for superyachts above 40 meters LOA trade at substantial premiums over prior-generation hydraulic systems and aging mechanical linkages still common in developing flag states. Three-tier pricing structure across premium, standard, and economy levels separates military-grade redundant architectures from price-sensitive recreational configurations and legacy commercial fleet retrofits. Cost compression in mid-tier electronic helm packages is intensifying because recreational boat owners in Florida and the Mediterranean unbundle steering upgrades from full vessel replacement cycles. Fleet operators running intra-European routes exhibit lowest price sensitivity due to port-state inspection avoidance value, while small pleasure craft owners in developing markets retain highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Strategic stockpiling of forged alloy rudder stocks and tiller arms dominates inventory strategy given concentration risk in East Asian heavy foundries, whereas just-in-time preferences govern electronic actuator sourcing from the Hamburg-Bremen engineering cluster. Component fabrication draws from Germany, Japan, and Singapore, with precision hydraulic actuators anchored in European captive production and torque-motor assemblies feeding from the Nagoya-Chubu industrial belt. Specialized steel casting dependencies, position sensor modules, and sealed electronic circuits rest on concentrated supplier bases. Single-source vulnerability in forged alloy inputs for heavy-duty commercial configurations creates structural exposure. Distribution runs through OEM shipyard contracts for newbuild superyacht and naval programs, with aftermarket service networks capturing recreational retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
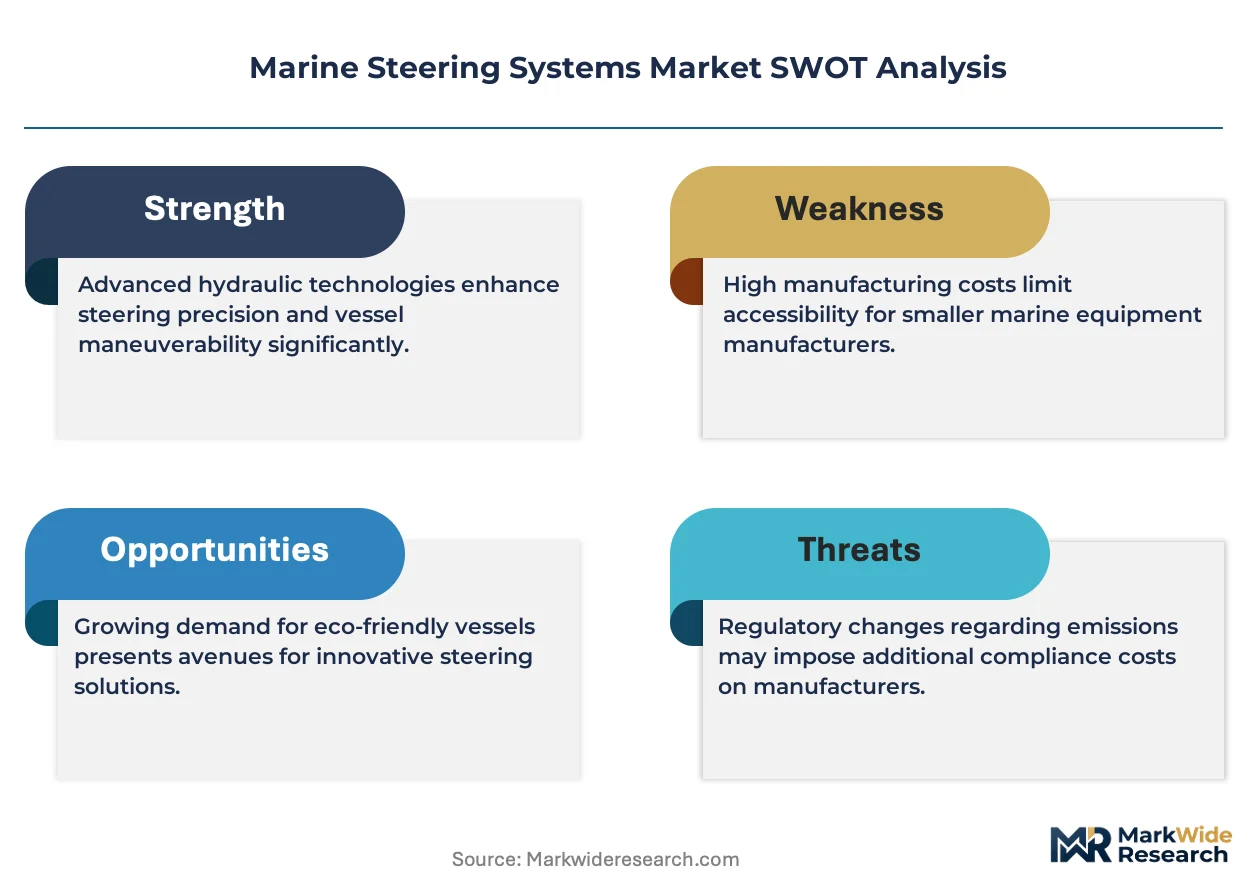
Marine steering systems constitute a defensive-moat market where regulatory entrenchment creates durable switching costs: shipyards face 8-14 month MDR conformity assessment timelines that lock in certified suppliers and penalize unproven entrants.
For Market Incumbents: Compound defensive positioning by deepening backward integration into precision actuator fabrication and securing captive supply of position sensor modules from the Nagoya-Chubu belt. Invest in cybersecurity-hardened actuator development to preempt IEC 62443 standardization gaps that threaten margin pools in naval contracts. Threat of steer-by-wire commoditization from navigation-electronics firms extending into helm control demands channel control through exclusive shipyard partnerships. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission offers the most viable entry path for electronic steering components targeting intra-European ferry operators. White-space concentrates in recreational retrofit channels serving outboard-powered vessels aged 5-12 years in Florida and Mediterranean marinas, plus autonomous surface vehicle protocols requiring redundant steering actuators. Go-to-market through marine dealerships with electronics-heavy service packages bypasses OEM shipyard procurement concentration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed navigation-electronics firms seeking sensor technology access to complete integrated helm-to-rudder platforms. Long-term viability favors targets with demonstrated METI certification for Japanese port compliance and established dynamic positioning integration for North Sea oil-service routes. Signal to watch is IEC 62443 cybersecurity standard finalization across flag-state regimes, which would trigger consolidation pressure on non-compliant actuator suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity-Hardened Actuator Development | Preempts IEC 62443 compliance gaps threatening naval contract eligibility. |
| Backward Integration into Sensor Modules | Captures position sensor supply from Nagoya-Chubu fabrication clusters. |
| Recreational Retrofit Channel Expansion | Captures unbundled demand from Florida and Mediterranean outboard owners. |
| METI Certification Investment | Unlocks certified-product premiums for vessels calling at Yokohama and Osaka. |
| Dynamic Positioning Integration Partnership | Synchronizes steering with GPS-hold algorithms for North Sea operators. |
Study Parameters
A standing panel of superyacht procurement directors, ferry fleet maintenance managers, marine equipment R&D heads, and aftermarket service dealers provided ongoing calibration across the study period. Primary interviews with shipyard specification engineers and hydraulic system procurement leads at Hamburg and Singapore operators combined with secondary validation from IMO convention documentation, EU MDR technical files, METI reliability benchmark publications, and customs trade data for marine equipment imports. Bottom-up vessel fleet analysis and top-down equipment spend estimates were triangulated to constrain projection variance.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, application scope, end-user category, and technology maturity, with additional stratification by vessel length class and regulatory compliance tier. CAGRs were derived from fitted growth curves anchored to documented newbuild order backlogs and retrofit attachment rate trends. Industry-specific forecast inputs included superyacht LOA distribution shifts and F-Gas Regulation phase-down compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable offshore oil-service activity; material deviation would warrant model refresh. Forecasts incorporate assumptions regarding certification timeline stability and hydraulic-to-electronic replacement velocity. Revision becomes warranted when IEC 62443 cybersecurity standard fragmentation across flag-state regimes crosses implementation threshold disparities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Yacht Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Boat Davits Market