
 Carrot Fiber Market | 2026-2036
Carrot Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Carrot Fiber Market Analytics
Food technologist expertise in plant-based texturization is bifurcating the competitive landscape between commodity suppliers and specialized innovators. Kerry Group leverages its global ingredient portfolio to integrate carrot fiber into multi-component clean-label systems for bakery and dairy clients. Fiberstar, Inc. specializes in citrus and vegetable fiber functionality, sustaining technical differentiation through proprietary extraction protocols that enhance water-binding capacity. Herbafood Ingredients GmbH anchors European supply security with regionally sourced raw material networks and ISO-certified processing facilities near German agricultural zones.
Carrot fiber consists of insoluble and soluble polysaccharides derived from carrot pomace, typically containing 60-85% dietary fiber with cellulose, hemicellulose, and pectin as dominant fractions; manufacturers recover this byproduct through mechanical separation, drying, and milling to produce ingredients with water-holding capacities exceeding 5-10 times their dry weight for use as fat mimetics, bulking agents, and texture modifiers in reduced-calorie formulations. Powder formats dominate industrial procurement due to superior dispersion characteristics and standardized dosing in automated bakery and sauce production lines. Snacks represent the fastest-growing application segment as extruded vegetable chips and puffed matrices incorporate carrot fiber to achieve structural integrity without gluten or synthetic binders.
EFSA evaluates novel fiber health claims under EU Regulation 1924/2006, while REACH governs chemical safety profiles of extraction solvents and processing aids, collectively raising compliance costs for non-European suppliers seeking market access. FDA GRAS self-determination pathways in the United States create parallel but less prescriptive entry routes, though FSMA preventive controls still mandate hazard analysis for imported vegetable fibers. Stakeholders must monitor evolving fiber definition harmonization between Codex Alimentarius and national food standards, as divergent analytical methods for soluble versus insoluble content directly determine label claims and premium positioning eligibility.
Market Dynamics
Clean-label reformulation mandates across Western European processed food sectors are compressing substitution timelines for synthetic hydrocolloids, forcing manufacturers to validate carrot fiber functionality at industrial scale before 2027 labeling deadlines.
Growth Catalysts
- EU Green Deal sustainability mandates:Processed food manufacturers in Germany and France must eliminate synthetic additives from reformulated products, accelerating plant-derived fiber procurement for fat replacement applications.
- REACH compliance acceleration:Chemical safety assessments for extraction solvents are favoring mechanical separation technologies over solvent-based pectin recovery, redirecting investment toward carrot pomace valorization infrastructure.
- Extruded snack structural demand:Gluten-free and clean-label snack producers require binding agents that achieve matrix integrity without synthetic additives, concentrating procurement on high water-holding capacity vegetable fibers.
Market Restraints
- Raw material geographic concentration:Premium carrot fiber supply chains cluster near German agricultural processing zones, exposing buyers to regional harvest volatility and limited alternative sourcing.
- EFSA novel fiber claim evaluation timelines:Health claim substantiation under EU Regulation 1924/2006 requires 18-24 month review cycles, delaying premium positioning for new market entrants.
- Cellulose ether substitution threat:Modified cellulose derivatives from wood pulp maintain cost advantages in high-volume sauce applications, constraining carrot fiber penetration in price-sensitive segments.
Strategic Opportunities
- Underpenetrated French bakery segment:Viennoiserie and artisan bread producers lag German counterparts in clean-label reformulation, creating first-mover advantage for technical service-equipped suppliers.
- CSRD supply chain disclosure requirements:Corporate sustainability reporting mandates are forcing food manufacturers to document ingredient provenance, favoring regionally traceable carrot fiber over imported alternatives.
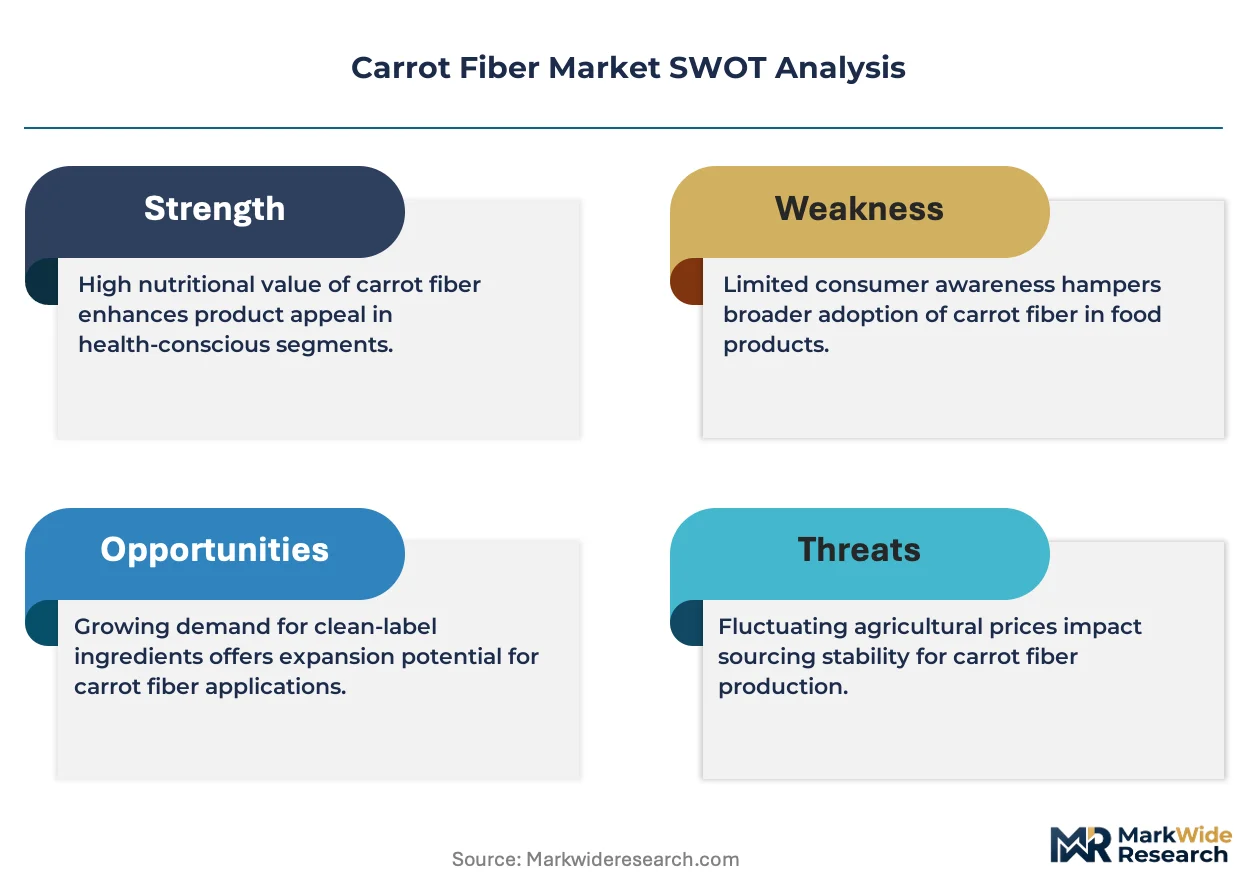
- Hybrid citrus-carrot fiber systems:Convergence of pectin-rich citrus fiber with cellulose-dominant carrot fiber enables tailored texturization for reduced-fat dairy spreads.
Industry Challenges
- Food technologist capability scarcity:Formulation expertise in plant-based texturization remains concentrated among specialized ingredient suppliers, limiting client self-sufficiency in fiber integration.
- ISO 22000 certification timelines:New processing facilities require 12-18 months for food safety management system accreditation, constraining rapid capacity expansion.
- Legacy hydrocolloid integration complexity:Reformulation teams must rebuild entire texture profiles when displacing established xanthan or guar systems, extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrot Fiber Market |
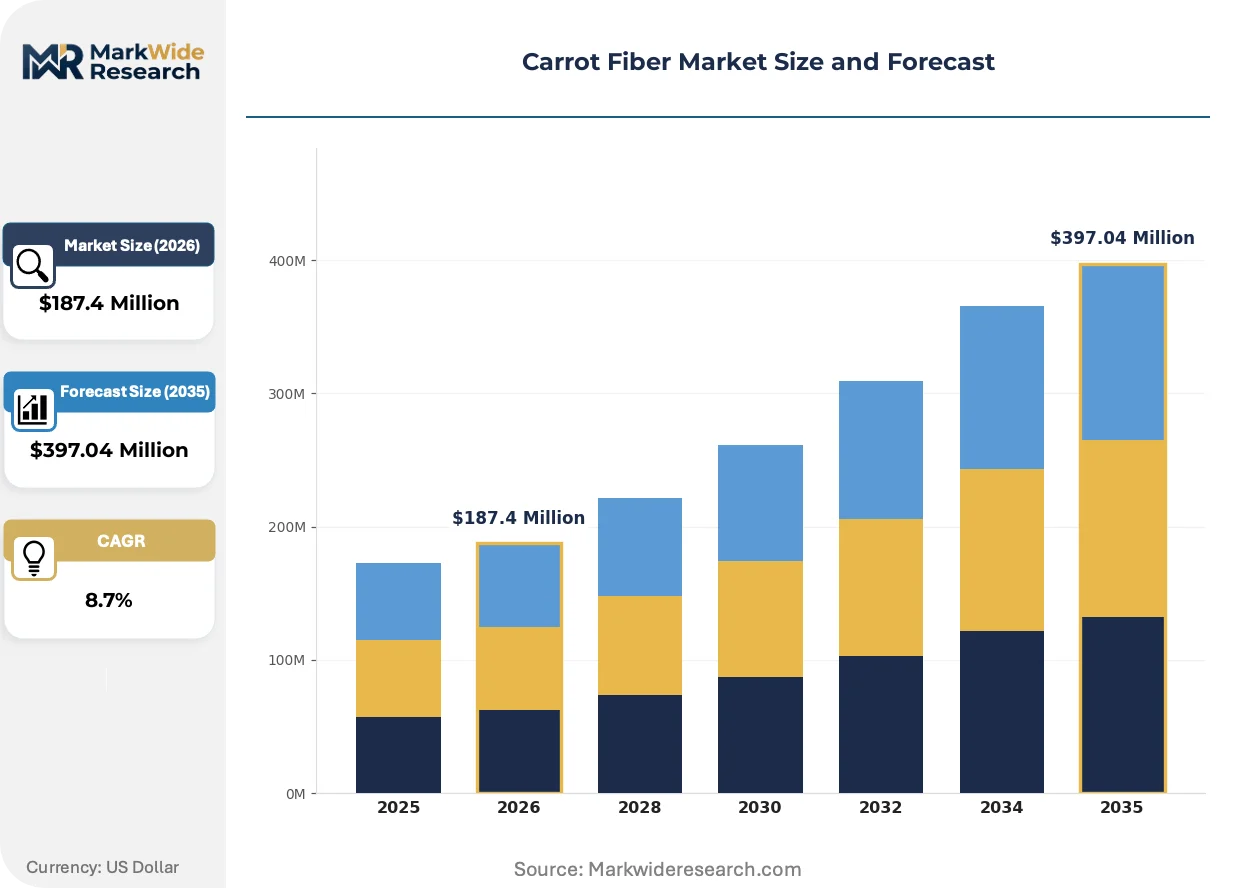
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Extracts Application: Baking, Sauces, Snacks, Dairy Products End User: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Kerry Group, Bolthouse Farms, Fiberstar, Inc., Herbafood Ingredients GmbH, BATA FOOD, Ingredion Incorporated, Arat Company, CP Kelco, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrot Fiber Market Evolving Landscape
Mechanical separation technologies are fragmenting traditional pectin extraction economics, while regulatory disclosure requirements and procurement centralization are compressing supplier qualification timelines across European food manufacturing.
Enzyme-assisted mechanical pressing is fragmenting the cost structure of carrot fiber production. Bakery and dairy manufacturers in Germany are adopting these systems at pilot scale to reduce energy-intensive drying requirements. The technology is fragmenting competitive advantage away from capital-intensive spray-drying infrastructure toward biotechnology-enabled process licensors.
EU Green Deal farm-to-fork sustainability targets are mandating 25% reduction in chemical pesticide use across agricultural supply chains. Carrot fiber processors must document residue testing compliance through ECHA-registered laboratories to maintain downstream food manufacturer contracts. Snack and ready-meal segments are responding by inserting sustainability clauses into multi-year supply agreements.
Buyer consolidation among European private-label food manufacturers is compressing supplier negotiation cycles. Procurement functions at major retail-aligned manufacturers are unbundling technical service from ingredient supply, forcing carrot fiber vendors to demonstrate standalone formulation support capabilities. France and Benelux markets exhibit the most pronounced centralization of sourcing decisions.
Carrot Fiber Market Segmentation
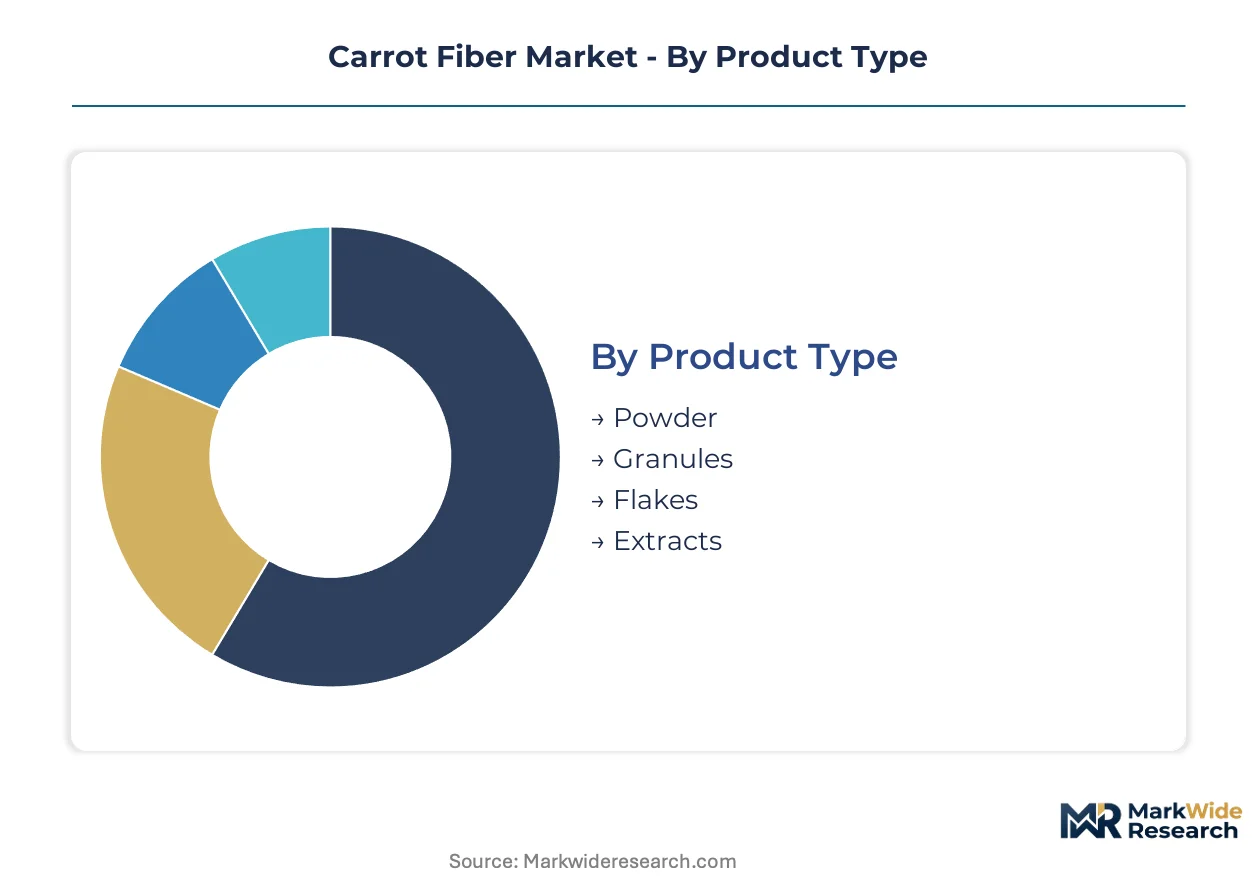
Channel configuration determines how carrot fiber specifications flow from extraction facilities to formulation labs. Product format, application requirements, and end-use regulatory standards each create distinct procurement pathways with divergent technical service needs.
Product Type:
Channel mix varies sharply by physical form: powder and granules move through high-volume wholesale contracts to industrial bakeries, while flakes and extracts concentrate in specialty ingredient distributors serving craft producers.
- Powder:Dominant format with standardized particle size distribution enabling automated dosing in extrusion and mixing equipment. German industrial bakeries and sauce manufacturers anchor procurement volumes under long-term supply agreements with fixed moisture specifications.
- Granules:Coarse fraction with enhanced mouthfeel contribution in meat analog and dairy spread applications. French clean-label reformulators are validating these for reduced-fat emulsions where powder dispersion creates textural defects.
- Flakes:Visual inclusions for artisan bread and premium snack positioning. Specialty stores and direct-to-manufacturer channels capture this low-volume, high-margin tier.
- Extracts:Pectin-enriched fractions targeting pharmaceutical and nutraceutical capsule formulations. EFSA novel food evaluations govern channel access for health claim positioning.
Powder dominates installed base. Extracts represent the steepest expansion trajectory as pectin recovery economics improve.
Application:
Cost tier stratification separates commodity volume applications from premium positioning segments with divergent formulation support requirements.
- Baking:Primary volume driver where carrot fiber replaces fat and gluten in clean-label bread and viennoiserie. Kerry Group and Herbafood anchor supply relationships with technical service teams embedded in German and French R&D facilities.
- Snacks:Extruded vegetable chips and puffed matrices require structural binders without synthetic additives. Water-holding capacity above 8x dry weight distinguishes qualified suppliers in this specification-intensive segment.
- Sauces:Viscosity modification in reduced-fat dressings competes directly with modified cellulose from wood pulp sources. Price pressure constrains carrot fiber penetration except in premium organic positioning.
- Dairy Products:Reduced-fat spreads and fermented products leverage pectin-protein interactions for creaminess simulation. Hybrid citrus-carrot systems are gaining formulation trials in Benelux dairy R&D centers.
Baking commands the largest procurement volumes. Snacks are gaining share fastest as extrusion technology adoption accelerates.
End User:
Customer type determines regulatory burden and technical validation depth, with food and beverage procurement teams requiring rapid reformulation support while pharmaceutical buyers demand extensive documentation packages.
- Food & Beverage:Core demand source spanning industrial manufacturers and private-label producers. REACH compliance and EU Green Deal sustainability clauses now appear in multi-year supply contracts.
- Pharmaceuticals:Excipient applications in tablet binders and controlled-release matrices require pharmacopeial-grade certification. EMA guidelines on vegetable-derived excipients govern supplier qualification timelines.
- Cosmetics:Natural texturizers for emulsions and masks, with lower volume but premium pricing. ISO 16128 natural origin standards determine positioning eligibility.
- Nutraceuticals:Dietary fiber supplements and prebiotic formulations. EFSA health claim substantiation under Regulation 1924/2006 creates 18-24 month market entry barriers.
Food and beverage anchors current revenue. Nutraceuticals concentrate expansion investment as gut health positioning gains regulatory clarity.
Distribution Channel:
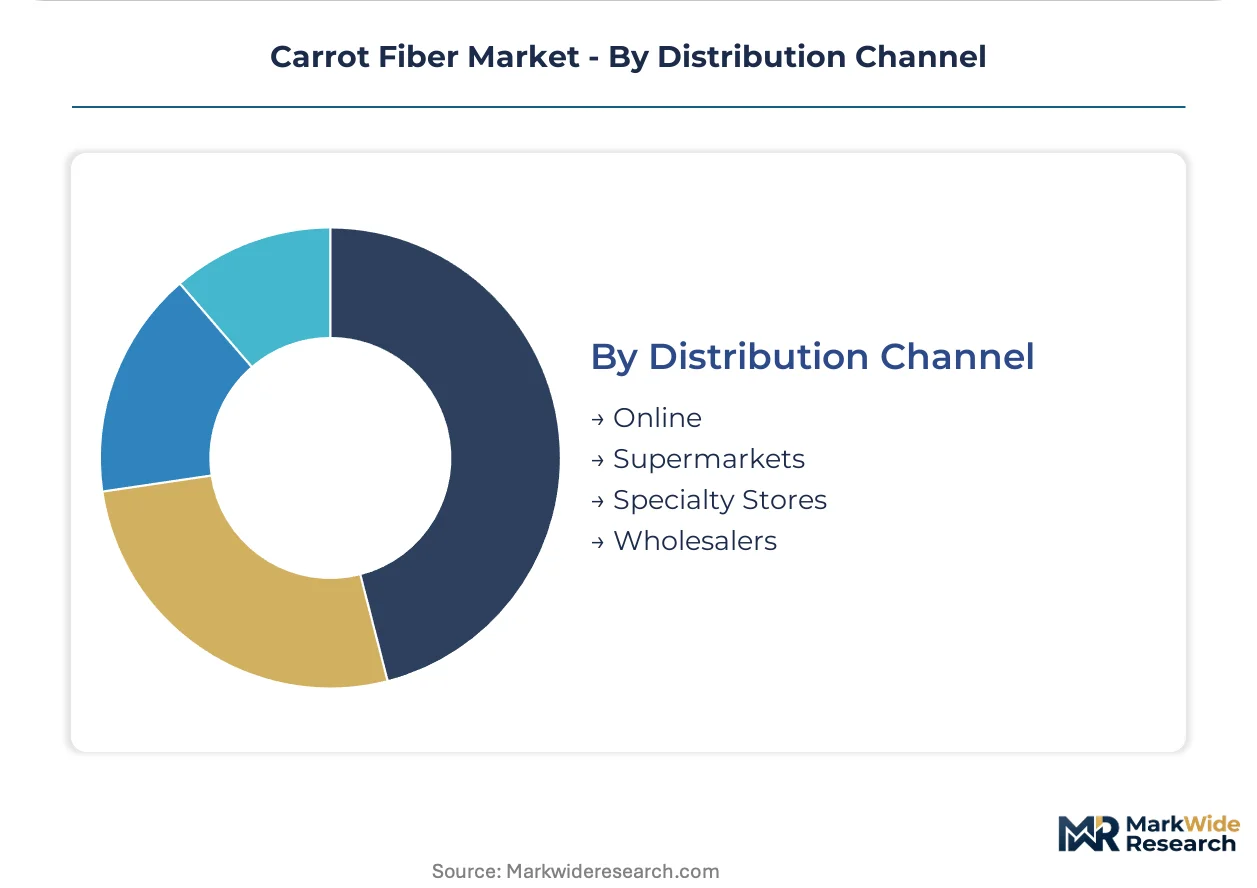
Supply concentration near German agricultural processing zones shapes channel efficiency, with proximity advantage favoring direct wholesale relationships over fragmented retail intermediation.
- Wholesalers:Primary channel for industrial-scale procurement, consolidating volumes from Herbafood and regional processors for redistribution to mid-size manufacturers.
- Online:Emerging pathway for sample procurement and small-batch orders from craft producers and R&D laboratories.
- Supermarkets:Limited to consumer-packaged finished goods; negligible for ingredient-grade carrot fiber.
- Specialty Stores:Niche channel for organic-certified and small-producer segments with traceability documentation requirements.
Wholesalers control volume flows. Online channels are climbing fastest as digital procurement platforms consolidate fragmented buyer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel fiber evaluations under EU Regulation 1924/2006 anchor regulatory gravity in Western Europe, where clean-label reformulation deadlines compress procurement timelines for carrot fiber suppliers.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia anchor European procurement volumes for carrot fiber powder. REACH compliance mandates on extraction solvents favor mechanical separation technologies over chemical recovery methods. Herbafood Ingredients GmbH operates ISO-certified processing facilities near Lower Saxony agricultural zones, securing regional supply chain dominance.
France
Viennoiserie producers in Île-de-France and Auvergne-Rhône-Alpes lag German counterparts in clean-label reformulation, creating technical service opportunities for equipped suppliers. EU Green Deal farm-to-fork targets mandate pesticide residue documentation through ECHA-registered laboratories. Artisan bread clusters in Provence-Alpes-Côte d'Azur are validating carrot fiber granules for reduced-fat emulsion applications.
United States
FDA GRAS self-determination pathways enable faster market entry for carrot fiber suppliers targeting clean-label snack manufacturers. FSMA preventive controls mandate hazard analysis for imported vegetable fibers, raising compliance barriers for non-domestic processors. California-based extruded snack producers are piloting high water-holding capacity fibers for gluten-free matrix applications.
Netherlands
Private-label food manufacturers in the Randstad region are consolidating procurement functions, compressing supplier qualification timelines. CSRD supply chain disclosure requirements force documentation of ingredient provenance, favoring traceable European carrot fiber over imported alternatives. Benelux dairy R&D centers are testing hybrid citrus-carrot fiber systems for reduced-fat spread applications.
United Kingdom
Post-Brexit regulatory divergence from EU fiber definition standards creates label claim uncertainty for carrot fiber importers. London and Southeast England food tech clusters are developing enzyme-assisted mechanical pressing to reduce energy-intensive drying requirements. Midlands-based sauce manufacturers face price pressure from modified cellulose competitors in high-volume applications.
Carrot Fiber Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the carrot fiber value chain. The market structure bifurcates between capital-intensive spray-drying operators and biotechnology-enabled process licensors. Three archetypes dominate: global ingredient conglomerates with embedded technical service teams, regional specialists with proprietary extraction protocols, and agricultural processors valorizing pomace byproducts. Competitive moves concentrate on geographic expansion through regional processing partnerships and portfolio diversification into hybrid fiber systems.
Among European specialists, Herbafood Ingredients GmbH and Fiberstar, Inc. exemplify technical differentiation archetypes, while Kerry Group occupies a position representing global-scale multi-component formulation capability. These three anchors illustrate the competitive tension between regional supply security and integrated clean-label system provision.
| Leading Market Players |
|---|
| Kerry Group |
| Bolthouse Farms |
| Fiberstar, Inc. |
| Herbafood Ingredients GmbH |
| BATA FOOD |
| Ingredion Incorporated |
| Arat Company |
| CP Kelco |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German industrial bakeries and Lower Saxony processing facilities lock in both supply access and price visibility across volatile agricultural cycles. These contracts bundle fixed moisture specifications with volume commitments, insulating buyers from spot-market spikes while anchoring supplier revenue stability under EU Green Deal procurement mandates.
Pricing Analysis
German powder-grade carrot fiber commands premium positioning against French and Benelux alternatives due to proximity advantages and ISO 22000 certification density. Three-tier pricing structure across organic-certified premium, standard food-grade, and economy-tier feed-grade levels stratifies the market, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because wood pulp cellulose ethers maintain cost advantages in high-volume sauce applications. Private-label manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize pharmacopeial-grade certification over unit cost.
Supply Chain Analysis
Inventory buffers of 8-12 weeks characterize German processing hubs, reflecting harvest seasonality and the absence of viable alternative sourcing regions. Supply concentrates in Germany, France, and the Netherlands, with carrot pomace feedstock drawn from regional juice extraction facilities. Mechanical separation equipment, energy-intensive drying infrastructure, and ECHA-registered laboratory testing create multi-point dependencies. Single-source vulnerability looms as premium supply chains cluster near Lower Saxony agricultural zones without geographic diversification. Distribution runs through wholesale consolidators serving industrial bakeries and private-label manufacturers, with digital procurement platforms fragmenting smaller craft producer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as European private-label manufacturers consolidate procurement functions, compressing supplier negotiation timelines and unbundling technical service from ingredient supply.
For Market Incumbents: Shield market position by embedding technical service teams within French viennoiserie R&D facilities before labeling deadlines force reformulation decisions. Deepen backward integration into carrot pomace supply through exclusive offtake agreements with juice processors in Lower Saxony, neutralizing raw material geographic concentration risks from harvest volatility and limiting entrant access to feedstock. For New Entrants and Emerging Players: Differentiate on enzyme-assisted mechanical pressing technology to reduce energy-intensive drying requirements and undercut capital-intensive spray-drying operators on production economics. Target the underpenetrated French artisan bread segment with granule-format technical validation, leveraging lagging clean-label reformulation timelines against established German suppliers. Lead with standalone formulation support capabilities as procurement centralization separates technical service from supply contracts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biotechnology-enabled process licensors over capital-intensive infrastructure owners. Long-term viability hinges on hybrid fiber system portfolios and regional processing partnerships rather than single-product concentration. Watch EFSA novel fiber claim evaluation timelines as inflection indicators—regulatory clarity on gut health positioning would unlock nutraceutical premiumization and reshape acquisition target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Citrus-Carrot Fiber System Development | Convergence of pectin-rich citrus with cellulose-dominant carrot enables tailored texturization for reduced-fat dairy spreads in Benelux R&D centers. |
| Enzyme-Assisted Mechanical Pressing Scale-Up | Biotechnology-enabled process licensors fragment competitive advantage away from spray-drying infrastructure through reduced energy requirements. |
| Regional Processing Partnership Expansion | Proximity to German agricultural zones secures supply chain resilience and CSRD-compliant provenance documentation for sustainability-mandated buyers. |
| Technical Service Team Embedding | Standalone formulation support capabilities satisfy procurement centralization trends unbundling service from ingredient supply contracts. |
| EFSA Health Claim Substantiation Investment | Novel fiber evaluations under Regulation 1924/2006 unlock premium nutraceutical positioning and 18-24 month competitive moats. |
Research Methodology
The analysis maps powder and granule formats, bakery and snack applications, and food-grade versus pharmaceutical-grade specifications, each validated through food technologists, procurement leads at private-label manufacturers, and regulatory affairs specialists. Primary interviews with ingredient supplier technical service directors, extruded snack R&D managers, and EFSA consultation respondents combined with secondary validation from REACH registration databases, EU Green Deal implementation trackers, and customs trade data for carrot pomace derivatives. Bottom-up volume builds from installed processing capacity and top-down demand estimates from clean-label reformulation mandates were cross-referenced for triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled physical form, application cost tier, end-use regulatory burden, and regional processing hub proximity as segmentation dimensions. CAGRs were derived from trend extrapolation of procurement contract volumes and substitution elasticity estimates for synthetic hydrocolloid displacement. Forecast inputs included EFSA evaluation timeline probabilities, enzyme-assisted processing adoption curves, and buyer consolidation trajectories in European retail-aligned manufacturing.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable mechanical separation technology diffusion; material deviation in regulatory stringency or processing cost economics would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Compressed Yeast Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Soy Flour Market
Ingredients
China Soy Protein Market
Ingredients
Glucosylglycerol Market
Ingredients
Rendered Products Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Yeast Flakes Market
Ingredients
Konjac Flour Market
Ingredients
Sesame Seed Extract Market
Ingredients
Europe Feed Yeast Market
Ingredients
Clean Label Starch Market
Ingredients
Icing Shortening Market
Ingredients
Sesame Oil Market