
 Global Web Analytics Software Market | 2026-2036
Global Web Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Web Analytics Software Market Foresight
GDPR enforcement is decoupling cross-site tracking from core analytics licensing, forcing vendors to reprice data-collection modules. Google LLC leverages its first-party data fortress to sustain premium positioning in attribution modeling. Adobe Inc. anchors enterprise workflows through deep Creative Cloud integration. Oracle Corporation competes on database-native query performance for high-velocity behavioral streams.
Web analytics software captures, processes, and visualizes user interaction data across digital properties through event-driven architectures processing billions of HTTP requests daily, enabling conversion optimization and audience segmentation. Cloud-Based deployment dominates new procurement as elastic compute absorbs traffic spikes without capital commitment. Conversion Optimization solutions command the highest per-seat pricing due to direct revenue linkage. User Behavior Tracking grows fastest among Solution Type categories as product-led growth methodologies spread beyond Silicon Valley.
FCC privacy guidelines, EU GDPR, and the EU AI Act collectively constrain how behavioral inference models train on consumer data, raising compliance engineering costs for vendors serving multinational clients. The US lacks comprehensive federal privacy law, creating a patchwork where CCPA in California, CPA in Colorado, and CTDPA in Connecticut force product fragmentation. Stakeholders must monitor whether emerging state-level AI disclosure requirements in the US merge with European algorithmic accountability standards before committing to platform architectures.
Market Dynamics
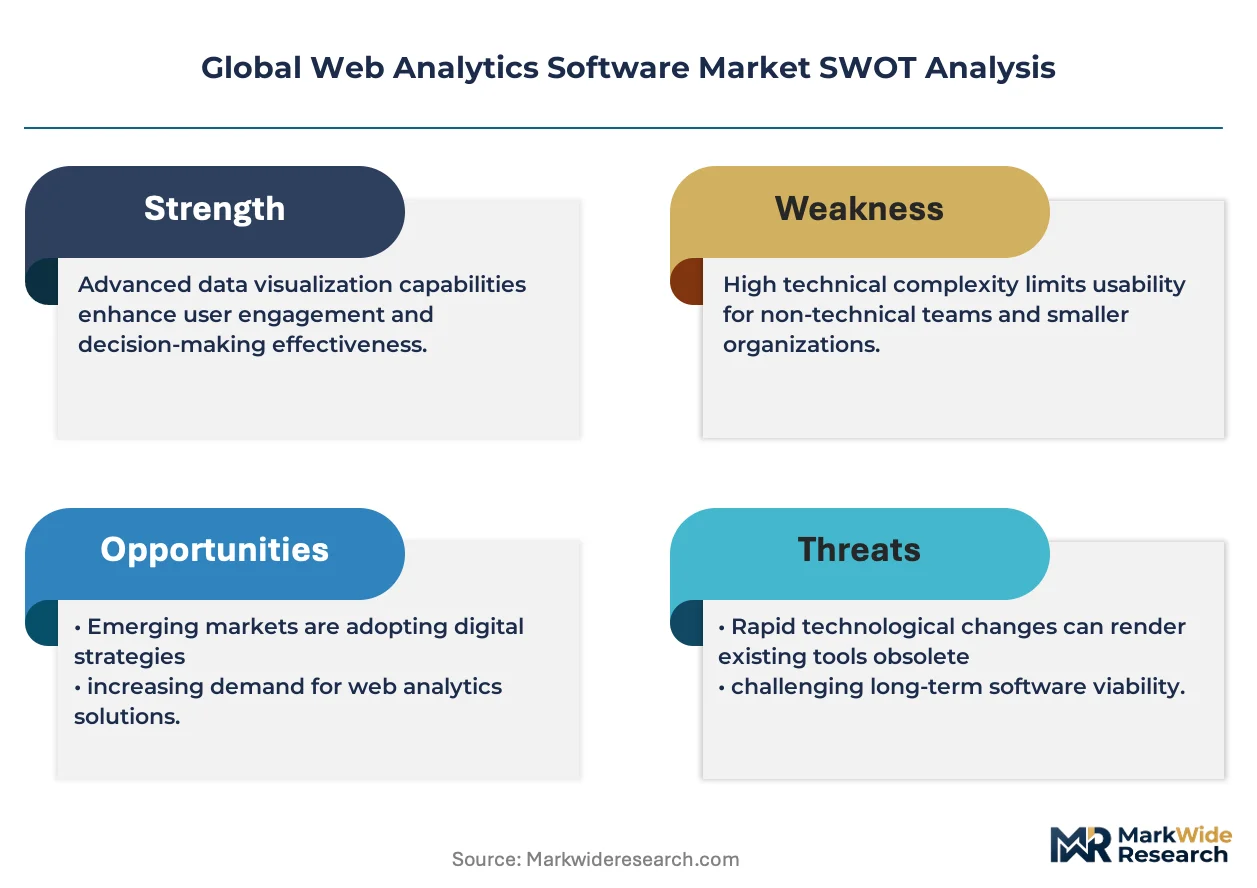
First-party data architecture replacement is restructuring vendor economics as third-party cookie deprecation eliminates cross-site tracking infrastructure. Platform providers must rebuild attribution engines around server-side collection and privacy-preserving computation, compressing margins while expanding engineering headcount.
Growth Catalysts
- EU AI Act convergence:Algorithmic accountability mandates are accelerating investment in explainable attribution models. Vendors deploying differential privacy and federated learning capture enterprise procurement cycles.
- E-commerce platform demand:Online retailers require granular funnel analysis as customer acquisition costs rise. Conversion optimization modules command premium licensing as direct revenue linkage justifies expenditure.
- Elastic cloud infrastructure:Traffic spike absorption without capital commitment enables mid-market adoption. Consumption-based pricing lowers entry barriers for high-velocity behavioral data processing.
Market Restraints
- Compliance engineering cost inflation:GDPR, EU AI Act, and emerging US state privacy laws force parallel product architectures. Multinational clients require jurisdiction-specific deployments, duplicating development overhead.
- Signal loss from identifier deprecation:Apple's ATT framework and Chrome's cookie phase-out degrade probabilistic attribution accuracy. Marketing mix modeling substitutes introduce latency and reduce actionability.
- Talent scarcity in privacy engineering:Cryptographers and differential privacy specialists command compensation premiums. Vendors compete with financial services and defense contractors for qualified personnel.
Strategic Opportunities
- Server-side tracking expansion:Cloud data warehouses and reverse ETL pipelines enable first-party data enrichment. Adobe and cloud-native competitors are integrating warehouse-native architectures to bypass browser restrictions.
- Product-led growth methodology spread:SaaS vendors outside Silicon Valley are adopting user behavior tracking for funnel optimization. This vertical extension opens mid-market segments previously served by basic analytics.
- India's digital commerce acceleration:Unified Payments Interface transaction data creates rich behavioral datasets. Local and global vendors are establishing data residency-compliant operations to serve this emerging demand center.
Industry Challenges
- Cross-functional data governance implementation:Legal, engineering, and marketing teams maintain conflicting definitions of consent and processing legitimacy. Organizational friction delays product releases and erodes competitive positioning.
- Legacy tag management migration:Decade-old client-side implementations resist server-side refactoring. Technical debt amortization timelines extend payback periods for platform replacement investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Web Analytics Software Market |
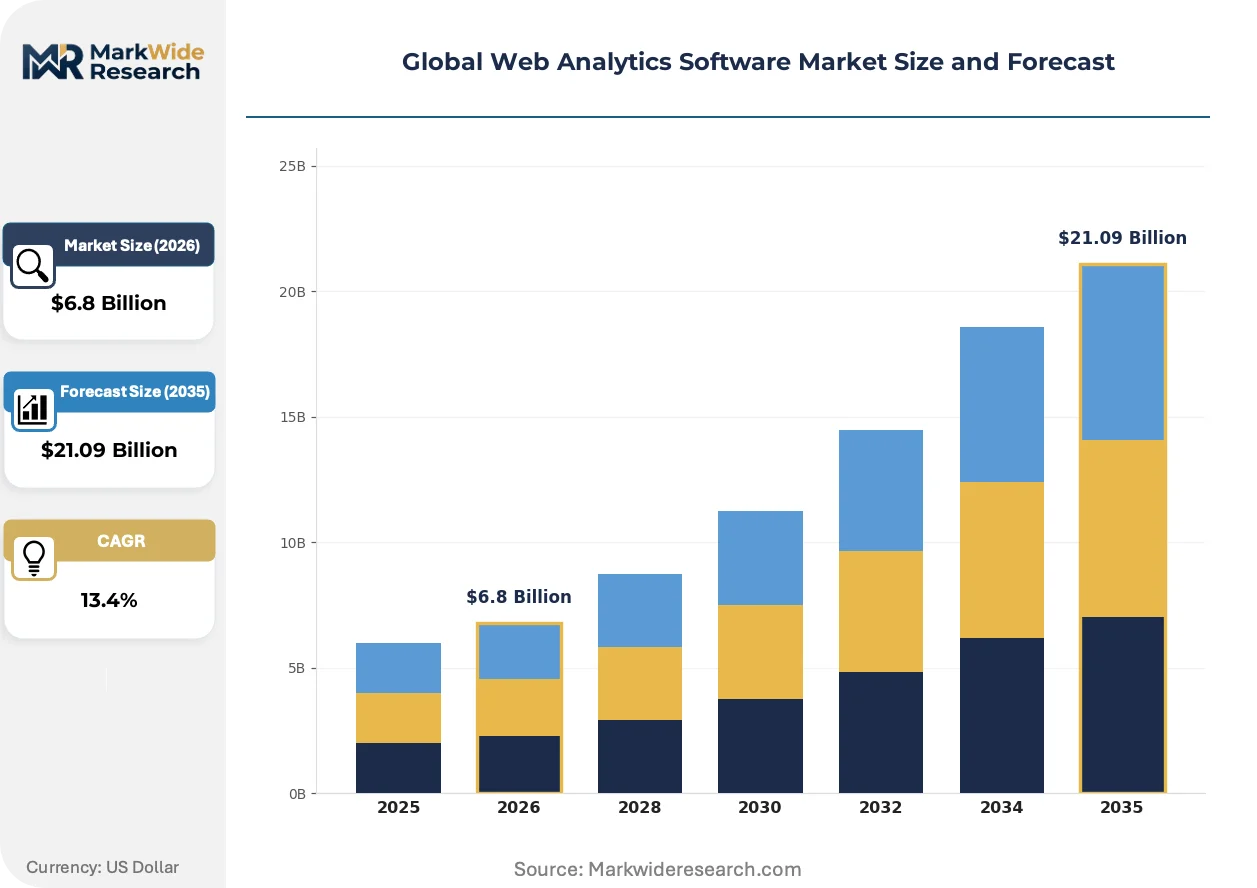
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Type: Traffic Analysis, Conversion Optimization, User Behavior Tracking, Campaign Analysis, Funnel Visualization Application: E-Commerce, Media & Publishing, Travel & Hospitality, Education Platforms, Financial Services End User: Digital Marketers, Content Creators, Product Managers, Data Analysts, SEO Specialists |
| Companies Covered | Google LLC, Adobe Inc., IBM Corporation, Oracle Corporation, Microsoft Corporation, SAP SE, SAS Institute Inc., Mixpanel, Inc., Amplitude, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Web Analytics Software Market Shifts & Advancements
Privacy-preserving computation and warehouse-native architectures are displacing traditional client-side collection. Vendor roadmaps now prioritize data minimization and jurisdictional sovereignty over feature velocity.
Differential privacy mechanisms are integrating into core attribution pipelines. E-commerce and financial services buyers are deploying these systems for cohort analysis without individual identification. The structural consequence is compressing competitive differentiation around data governance rather than visualization sophistication.
GDPR enforcement and the EU AI Act are mandating algorithmic impact assessments for behavioral inference models. Vendors must document training data provenance and decision logic for automated profiling. Enterprise procurement in Germany, France, and the Netherlands now requires compliance certification as a table-stakes evaluation criterion.
Buyer concentration among multi-brand retailers is consolidating vendor relationships through enterprise-wide platform standardization. Procurement teams are unbundling point solutions in favor of integrated suites with native consent management. This pattern is most visible in the United States, where CCPA litigation risk drives preference for vendors with established legal precedent and indemnification structures.
Global Web Analytics Software Market Segmentation
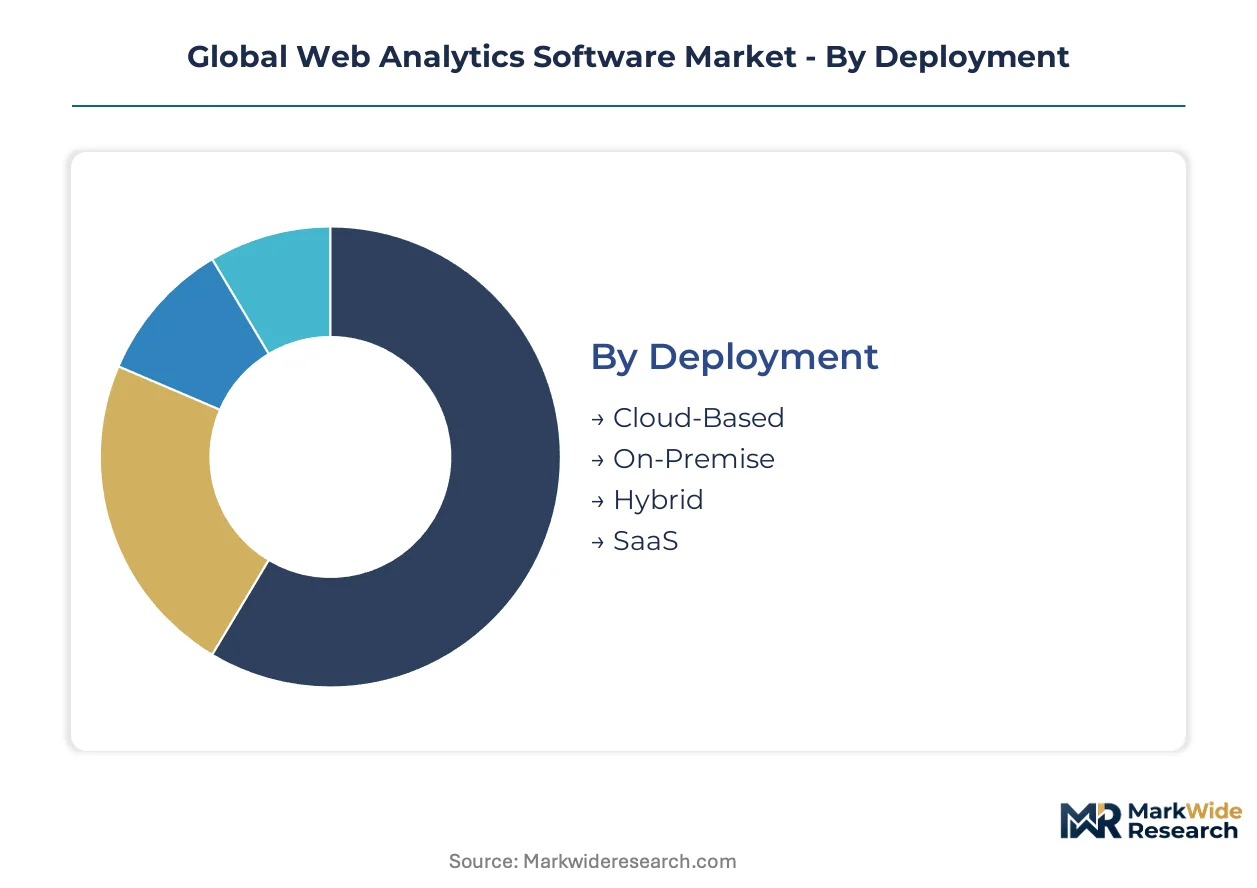
Vendor resource allocation across deployment modes, solution types, and user profiles determines competitive positioning in web analytics. Procurement patterns diverge sharply between enterprise martech consolidators and specialized point-solution buyers.
Deployment:
Supply concentration in cloud infrastructure has compressed provisioning timelines from weeks to hours for elastic workloads.
- Cloud-Based:Elastic compute architectures absorb traffic spikes without capital commitment. E-commerce platforms in the United States concentrate procurement here as seasonal volatility demands instantaneous scaling.
- On-Premise:Dedicated hardware installations within client data centers process sensitive behavioral streams. Financial services institutions in Germany maintain this deployment for GDPR-mandated data residency and sovereign control over inference models.
- Hybrid:Split architectures route anonymized aggregates to cloud while retaining PII on local servers. Retail conglomerates operating across EU and US jurisdictions deploy this configuration to satisfy divergent compliance thresholds.
- SaaS:Subscription licensing with zero infrastructure management lowers entry barriers for mid-market agencies. Content creators and independent publishers in India adopt this model for rapid funnel deployment without engineering overhead.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
Solution Type:
Margin structures vary dramatically based on whether modules tie directly to revenue outcomes or remain diagnostic utilities.
- Conversion Optimization:A/B testing and personalization engines that directly attribute revenue lift to specific interventions. Multi-brand retailers in France pay premium per-seat pricing as procurement teams justify expenditure through documented ROAS improvements.
- User Behavior Tracking:Event-stream capture for product-led growth methodologies including heatmaps, session replay, and cohort progression analysis. SaaS vendors outside Silicon Valley in Brazil and Southeast Asia are driving fastest adoption as PLG practices diffuse beyond technology hubs.
- Traffic Analysis:Visitor volume, source attribution, and geographic distribution reporting. Media publishers in the United Kingdom rely on this foundation for inventory valuation and programmatic advertising yield optimization.
- Campaign Analysis:Cross-channel performance aggregation for paid media efficiency measurement. Digital marketing agencies in Australia standardize on these modules for client reporting and budget reallocation recommendations.
- Funnel Visualization:Step-by-step dropout identification across user journeys. Travel booking platforms in the United Arab Emirates deploy these tools to reduce abandonment at payment and confirmation stages.
Conversion Optimization commands the highest per-seat pricing; User Behavior Tracking is gaining share fastest.
Application:
End-use concentration determines feature roadmaps as vertical-specific compliance requirements fragment product development.
- E-Commerce:Granular cart abandonment analysis and recommendation engine feedback loops. Online retailers in the United States undergoing martech stack replacement cycles represent the most aggressive procurement segment.
- Media & Publishing:Content engagement scoring and subscription conversion tracking. News organizations in the Netherlands deploy these systems to transition from advertising-dependent to reader-revenue models under EU AI Act transparency mandates.
- Travel & Hospitality:Booking path optimization and dynamic pricing integration. Hotel chains in Japan utilize behavioral data to personalize package offerings across domestic and inbound tourist segments.
- Education Platforms:Learning progression analytics and course completion prediction. Universities in Canada adopt these tools for student retention interventions and accreditation reporting.
- Financial Services:Secure session monitoring with fraud pattern detection. Banks in Switzerland require differential privacy implementations for wealth management client segmentation under national financial secrecy frameworks.
E-Commerce accounts for the dominant share of vendor revenue; Financial Services exhibits the steepest expansion trajectory.
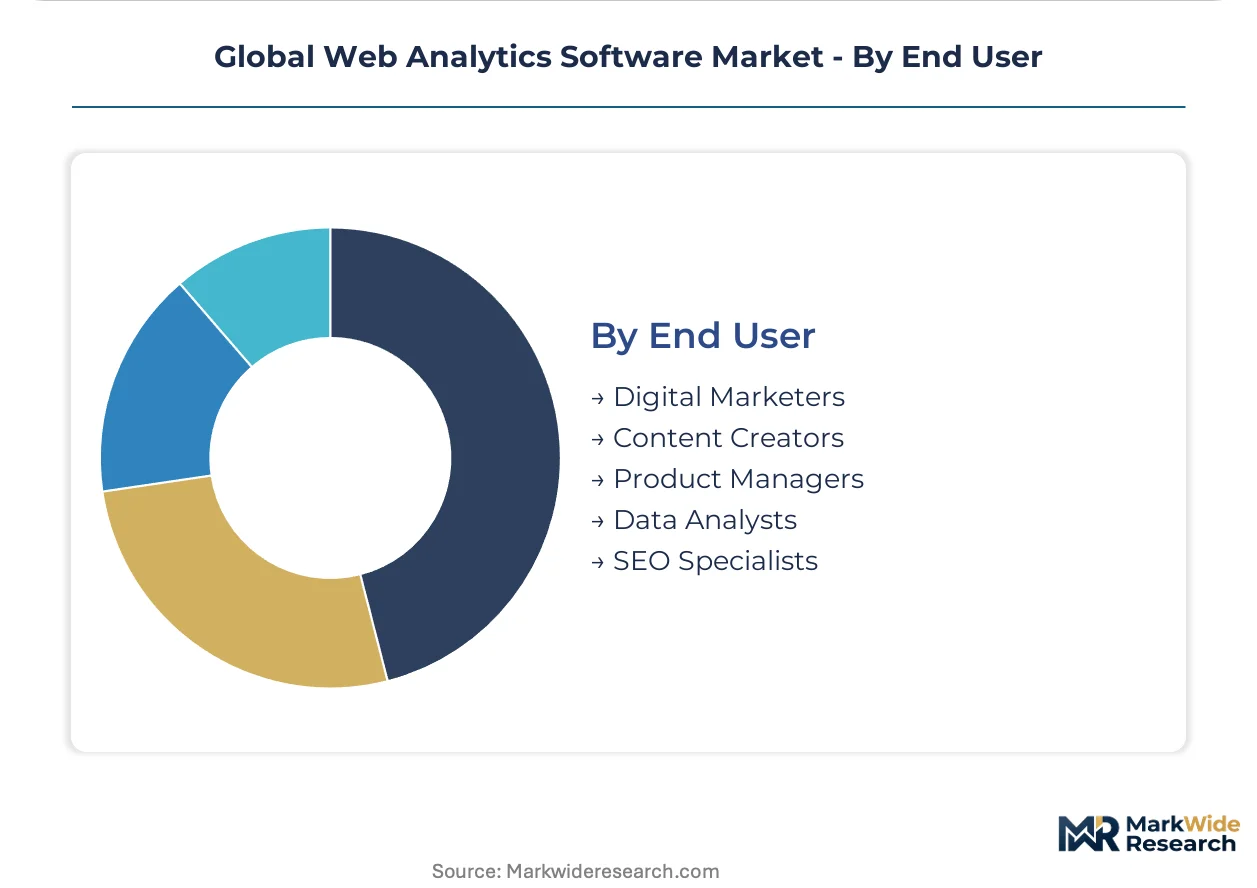
End User:
Persona-specific workflows dictate interface complexity and integration depth across marketing technology stacks.
- Digital Marketers:Campaign performance dashboards with automated alert configurations for ROAS thresholds. Performance marketing teams in the United States rely on real-time attribution to optimize Meta and Google ad spend.
- Product Managers:Feature adoption curves and user journey mapping for roadmap prioritization. SaaS product teams in Singapore integrate these insights with Jira and Linear for sprint planning.
- Data Analysts:Raw event export capabilities and SQL access for custom model development. Enterprise analytics groups in Germany demand warehouse-native architectures for unified business intelligence pipelines.
- Content Creators:Simplified engagement metrics and audience demographic breakdowns. Independent YouTube and Substack publishers in Brazil prefer stripped-down interfaces without technical configuration requirements.
- SEO Specialists:Organic search visibility correlation with on-page behavioral signals. Digital agencies in Australia combine these modules with rank tracking tools for comprehensive search strategy reporting.
Digital Marketers represent the largest installed base; Product Managers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dubai Internet City concentrate cloud infrastructure investment, accelerating vendor data center deployment for latency-sensitive analytics processing. Tax incentives in these zones reduce operational costs for multinational software providers serving adjacent markets.
United States
Enterprise martech stack replacement cycles drive procurement concentration among multi-brand retailers and SaaS vendors. FCC privacy guidelines intersect with emerging state-level AI disclosure requirements in California, Colorado, and Connecticut. Silicon Valley clusters in San Francisco and San Jose host headquarters operations for warehouse-native analytics architecture development.
Germany
GDPR-mandated data residency requirements sustain demand for sovereign cloud deployments in financial services and automotive sectors. The Federal Financial Supervisory Authority enforces strict segmentation protocols for wealth management client data. Berlin and Munich industrial corridors concentrate compliance engineering talent for differential privacy implementation.
India
Unified Payments Interface transaction volume generates behavioral datasets for e-commerce funnel optimization. The Reserve Bank of India mandates data localization for payment system operators, creating residency-compliant infrastructure requirements. Bangalore and Hyderabad technology parks host development centers for server-side tracking architecture serving domestic and export markets.
United Kingdom
Media publishers transitioning to reader-revenue models require content engagement scoring under EU AI Act transparency mandates. The Information Commissioner's Office enforces algorithmic accountability standards for automated profiling systems. London's financial district and Manchester media clusters drive procurement for privacy-preserving attribution models.
Japan
Hotel chains and travel platforms utilize behavioral data for dynamic pricing across domestic and inbound tourist segments. METI guidelines on data governance influence enterprise procurement criteria for cross-border data transfers. Tokyo and Osaka metropolitan areas concentrate demand for real-time conversion optimization in hospitality and retail applications.
Global Web Analytics Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and solution tiers. The market exhibits moderate consolidation with enterprise suites absorbing point-solution capabilities through platform integration. Three archetypes dominate: cloud-native specialists emphasizing warehouse-native architectures, legacy enterprise vendors leveraging database integration, and product-led growth platforms targeting mid-market SaaS. Competitive moves center on server-side tracking capability acquisition and consent management module integration.
Within the diversified technology tier, Google LLC and Microsoft Corporation exemplify platform ecosystem strategies that bundle analytics with cloud infrastructure and productivity suites. Adobe Inc. occupies a position bridging creative workflows and marketing automation. Oracle Corporation and SAP SE anchor the enterprise database-native segment. Among pure-play specialists, Amplitude, Inc. and Mixpanel, Inc. represent product-led growth methodology propagation beyond technology hubs.
| Leading Market Players |
|---|
| Google LLC |
| Adobe Inc. |
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| SAS Institute Inc. |
| Mixpanel, Inc. |
| Amplitude, Inc. |
| Others |
Supply & Pricing Matrix
Enterprise-mid-market capability divergence splits vendor economics between premium attribution suites and stripped-down behavioral tools, compressing margins in the middle tier while cloud infrastructure concentration in the United States and Ireland shapes delivery cost structures. Procurement teams at multi-brand retailers negotiate consumption-based SaaS contracts that absorb traffic volatility without capital commitment, whereas financial services institutions in Germany and Switzerland pay residency premiums for sovereign cloud deployments.
Pricing Analysis
Short lead-time deployment premiums reward vendors with pre-configured server-side tracking architectures, while extended implementation timelines for legacy tag migrations force discounting to win replacement cycles. The dominant pricing structure runs through tiered subscription licensing anchored to event volume tiers and seat counts, with differentiation driven by GDPR compliance certification levels and native data warehouse integration depth. Cost compression in the mid-market intensifies as open-source alternatives commoditize basic funnel visualization. Digital marketing agencies in Australia exhibit highest price sensitivity due to thin client margins, while banks in Switzerland show lowest sensitivity given regulatory indemnification requirements.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentrated in the United States, Ireland, and Singapore, where AWS, Azure, and GCP regions host the bulk of elastic compute for behavioral data processing. Software vendors draw from specialized talent pools in Germany and India for differential privacy engineering, alongside proprietary inference model training datasets licensed from e-commerce platforms. Tariff exposure on cross-border data transfers threatens margin stability for vendors serving EU-US hybrid deployments. Distribution runs through direct enterprise sales teams for large martech consolidators, supplemented by agency channel partners for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance engineering cost inflation is forcing vendor consolidation as smaller players lack capital to maintain parallel GDPR-EU AI Act product architectures. Platform providers with established legal precedent and indemnification structures are absorbing point-solution capabilities through acquisition.
For Market Incumbents: Extend warehouse-native architecture roadmaps to bypass browser-based collection restrictions, capturing enterprise procurement cycles in Germany and the United States. Deepen server-side tracking integration with cloud data platforms to defend against emerging cloud-native specialists. Prioritize consent management module acquisition to satisfy CCPA litigation risk requirements among multi-brand retailers.
For New Entrants and Emerging Players: Begin with product-led growth methodology tooling for SaaS vendors outside Silicon Valley in Brazil and Southeast Asia, where basic behavioral tracking remains underpenetrated. Target mid-market agencies in India seeking rapid funnel deployment without engineering overhead. Pursue freemium distribution through integration marketplaces to minimize customer acquisition costs.
For Investors and Strategic Acquirers: Re-rating potential sits with privacy-engineering-capable pure-plays given EU AI Act algorithmic accountability mandates expanding addressable market. Long-term viability favors vendors with demonstrated differential privacy implementations and established data residency operations. Watch for Federal privacy law harmonization in the United States as inflection indicator for enterprise platform standardization acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Tracking Architecture | Bypasses Apple ATT and Chrome cookie deprecation for attribution accuracy retention. |
| Consent Management Integration | Satisfies CCPA litigation risk requirements among United States multi-brand retailers. |
| Warehouse-Native Partnership | Enables Snowflake and Databricks connectivity for German enterprise analytics pipelines. |
| Differential Privacy Certification | Meets EU AI Act algorithmic impact assessment mandates for automated profiling systems. |
| India Data Residency Expansion | Captures UPI-generated behavioral datasets under RBI localization requirements. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory impact assessments formed the secondary backbone, supplemented by customs data on cloud infrastructure equipment flows. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners validated deployment mode preferences and pricing sensitivity across enterprise and mid-market segments. Bottom-up event-volume modeling and top-down martech spend allocation triangulated segment-level demand estimates.
Historical trendline analysis of vendor revenue disclosures and cloud consumption patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical application, integration complexity level, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating compliance cost pass-through and first-party data migration timelines.
Underlying measurement precision varies by segment; cloud-based deployment and e-commerce application estimates carry tighter precision than on-premise financial services projections. Forecasts assume sustained GDPR enforcement intensity and incremental US state privacy law proliferation. Deviation in Federal privacy law harmonization or EU AI Act implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Document Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Cloud Performance Management Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Edge Analytics Market
Analytics
Global Performance Analytics Market
Analytics
Text Analytics Market
Analytics
Global Talent Intelligence Software Market
Analytics
Contact Center Analytics Market
Analytics
Product Analytics Market
Analytics
Predictive Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Cloud-Based Predictive Analytics Platform Market
Analytics
Complex Event Processing Market
Analytics
Global AI Video Analytics Market