
 Mobile App Attribution Tool Market | 2026-2036
Mobile App Attribution Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile App Attribution Tool Market Insights
Israeli attribution technology providers is broadening the supply base for deterministic measurement. AppsFlyer leverages deep linking infrastructure to sustain enterprise retention across mobile gaming verticals. Adjust anchors European privacy compliance workflows, while Branch competes on cross-platform identity resolution without device-level identifiers.
A mobile app attribution tool is a software system that collects, correlates, and analyzes user touchpoints across advertising channels to assign credit for app installs and in-app events, typically processing probabilistic and deterministic signals through SDK integration and server-to-server APIs. Its primary commercial purpose is to optimize return on ad spend by revealing which campaigns, creatives, and publishers generate measurable user actions. Cloud-based deployment leads structural adoption because marketing agencies demand elastic compute for seasonal campaign spikes, while fraud detection functionality captures expanding margin pools as invalid traffic erodes advertiser budgets. Cross-platform attribution grows fastest where iOS and Android user bases overlap in single-app portfolios.
GDPR in Europe, CCPA in California, and Apple's ATT framework collectively restrict identifier availability, forcing attribution vendors to rebuild measurement stacks around aggregated and differential privacy models. India's draft Digital Personal Data Protection Bill and Brazil's LGPD add compliance layers for vendors operating in high-growth mobile markets. Stakeholders must decide whether to invest in privacy-preserving measurement infrastructure or cede ground to platform-native attribution walled gardens.
Market Dynamics
Apple's ATT framework has severed deterministic identifier flows, forcing attribution vendors to reconstruct measurement architectures around aggregated differential privacy and probabilistic modeling.
Growth Catalysts
- India's Digital Personal Data Protection Bill:Compliance mandates create procurement urgency among mobile gaming publishers operating in high-growth emerging markets.
- Server-to-server API architectures:Cloud infrastructure elasticity enables marketing agencies to scale compute resources during seasonal campaign surges without capital expenditure.
- Fraud detection functionality:Invalid traffic erosion of advertiser budgets drives margin capture through automated invalid traffic filtering and post-attribution verification.
Market Restraints
- Identifier fragmentation:Apple's ATT opt-out rates exceeding industry baselines compress deterministic signal availability and inflate probabilistic modeling costs.
- European supply concentration:GDPR enforcement variance across member states creates compliance complexity for vendors serving multi-jurisdiction campaigns.
- Platform-native attribution substitution:Google Ads App Campaigns and Apple Search Ads walled gardens displace independent measurement for budget-constrained advertisers.
Strategic Opportunities
- Brazil's LGPD maturation:Latin America's largest mobile market presents first-mover advantage for privacy-preserving attribution infrastructure deployment.
- Cross-platform identity convergence:SKAdNetwork and Privacy Sandbox interoperability creates whitespace for unified iOS-Android measurement without device-level identifiers.
- CTV-mobile convergence:Connected television ad spend flowing into mobile retargeting pipelines demands new attribution touchpoint correlation capabilities.
Industry Challenges
- Probabilistic data science talent scarcity:Differential privacy and federated learning expertise commands premium compensation, constraining vendor R&D velocity.
- Legacy SDK integration debt:Publisher apps maintain deprecated attribution SDK versions, creating version fragmentation and data quality inconsistency.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audits require twelve-to-eighteen month cycles, lagging behind privacy framework update velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile App Attribution Tool Market |
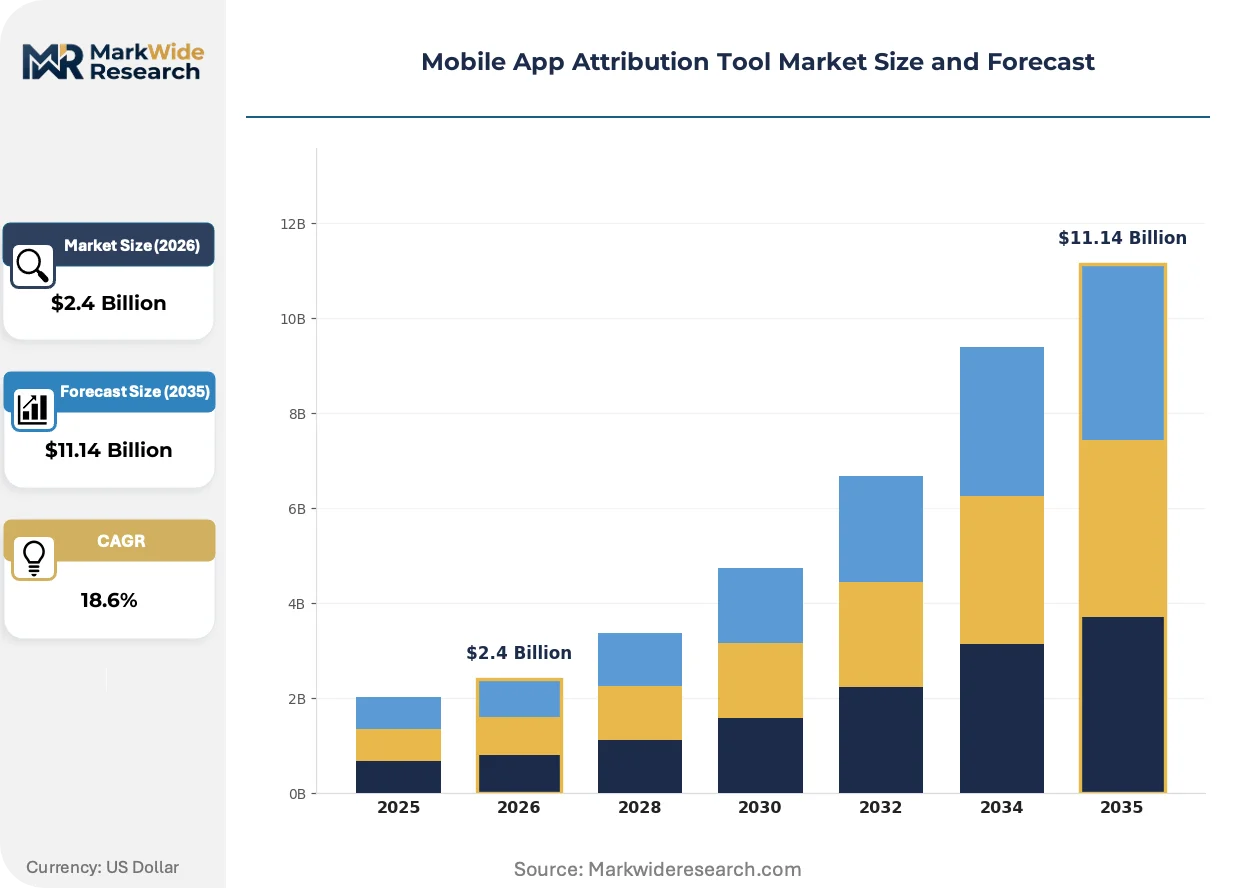
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.14 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud End User: Enterprises, Marketing Agencies, Startups, Developers Functionality: Real-Time Analytics, User Engagement Tracking, Attribution Reporting, Fraud Detection Platform: iOS, Android, Web, Cross-Platform |
| Companies Covered | AppsFlyer, Adjust, Branch, Singular, Kochava, Tenjin, Airbridge, Affise MMP, MoEngage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile App Attribution Tool Market Trends and Innovations
Measurement methodology is bifurcating between platform-compliant aggregated solutions and privacy-preserving cryptographic techniques, compressing competitive differentiation around data science sophistication rather than raw signal volume.
Probabilistic fingerprinting is absorbing diminished deterministic signal availability by stitching together device graph fragments, temporal patterns, and behavioral cohorts. Mobile gaming publishers in Southeast Asia deploy these techniques most aggressively, accepting higher uncertainty bands in exchange for campaign continuity. The technology is absorbing budget allocation decisions previously reserved for deterministic attribution, compressing confidence intervals through Bayesian hierarchical modeling.
GDPR's Article 25 data protection by design mandate forces attribution vendors to embed privacy controls at architecture inception rather than retrofit compliance. European gaming and fintech verticals face the strictest supervisory authority scrutiny, particularly from France's CNIL and Germany's data protection commissioners. Vendors respond by localizing data processing within EU sovereign cloud regions and minimizing cross-border data transfers.
Agency procurement teams now unbundle attribution services from media buying contracts, demanding standalone measurement verification. This disintermediation pressures holding companies to justify in-house attribution tool investments against independent vendor capabilities. The shift is most visible in India and Brazil, where marketing procurement functions mature rapidly alongside digital advertising infrastructure expansion.
Mobile App Attribution Tool Market Segmentation
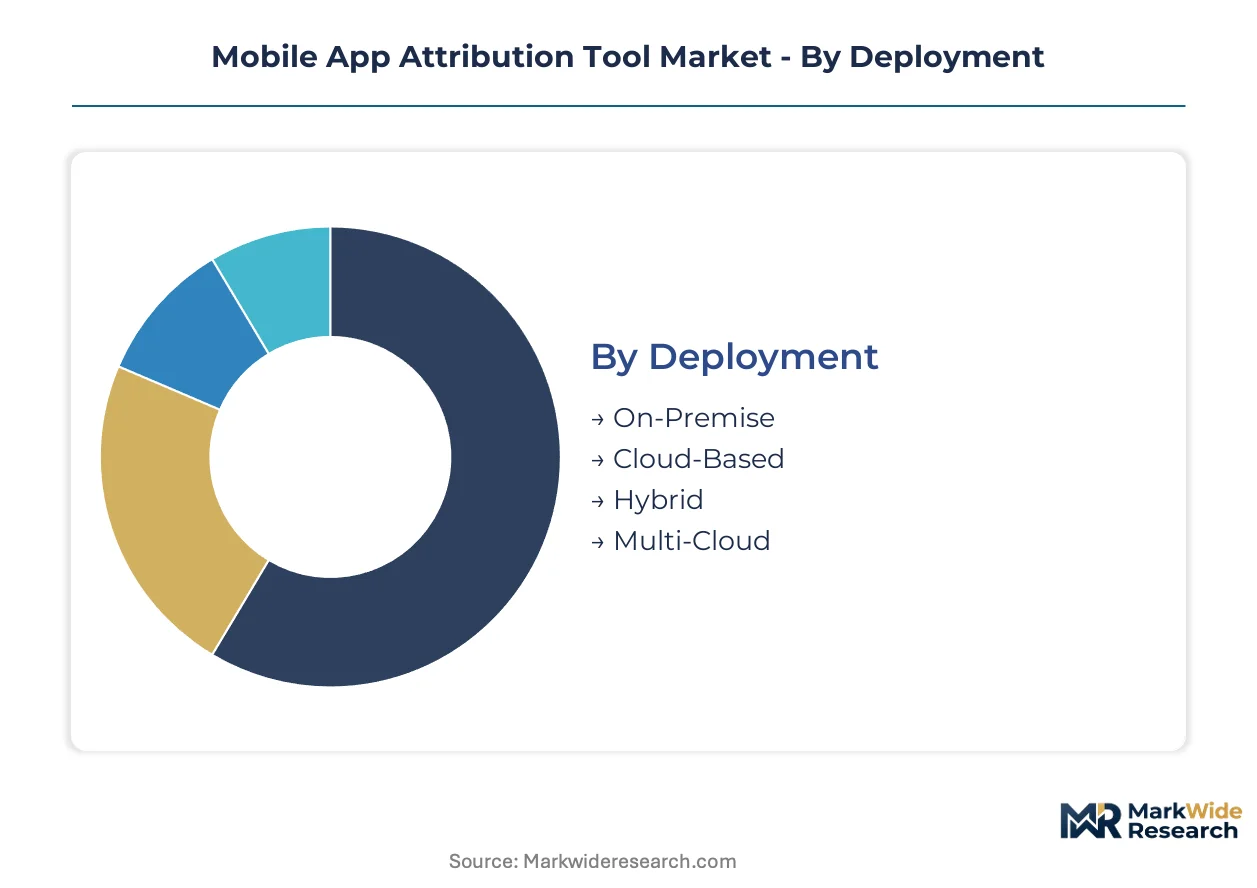
Attribution vendors structure pricing and certification requirements around deployment topology and end-user scale. Segment boundaries determine ISO 27001 audit scope, SOC 2 Type II coverage, and differential privacy architecture investments.
Deployment:
ISO 27001 and SOC 2 Type II certifications cluster heaviest in cloud-native deployments where multi-tenant data segregation demands formalized controls. On-premise installations face lighter recurring audit burdens but heavier upfront hardening costs.
- On-Premise:Dedicated hardware installations within advertiser or publisher data centers. Financial services firms in Frankfurt and Singapore mandate this topology for PCI-DSS compliance workflows.
- Cloud-Based:Elastic compute provisioning through AWS, Azure, or GCP infrastructure. Marketing agencies in São Paulo and Mumbai scale seasonal campaign spikes without capital expenditure.
- Hybrid:Split architectures processing sensitive identifiers on-premise while funneling aggregated analytics to cloud endpoints. European gaming publishers deploy this under GDPR Article 25 data protection by design mandates.
- Multi-Cloud:Redundant deployment across two or more hyperscaler environments. Vendors serving LATAM and Southeast Asia simultaneously favor this for sovereignty compliance.
Leading the category by volume: Cloud-Based. Expanding most quickly: Multi-Cloud.
End User:
Procurement sophistication varies sharply—enterprises demand enterprise-grade SLAs while startups prioritize SDK integration speed over compliance documentation.
- Enterprises:Fortune 500 retailers and banking apps operating across 15+ markets. These buyers mandate localized data residency clauses and dedicated customer success engineering.
- Marketing Agencies:Holding company media buyers managing $50M+ annual mobile ad budgets. Procurement teams now unbundle attribution from media contracts, demanding standalone measurement verification.
- Startups:Seed-stage gaming and fintech apps with sub-10 million user bases. Price sensitivity drives freemium tier adoption with upgrade triggers at $100K monthly ad spend.
- Developers:Individual app creators and small studios publishing through Apple App Store and Google Play. Self-serve onboarding and community documentation dominate vendor engagement models.
Revenue concentrates with: Enterprises. Fastest margin expansion: Marketing Agencies.
Functionality:
Feature bundling determines R&D allocation—fraud detection commands premium pricing while attribution reporting faces commoditization pressure from platform-native alternatives.
- Real-Time Analytics:Sub-second latency dashboards for programmatic bid optimization. Demand clusters with mobile gaming publishers in Jakarta and Manila running high-velocity user acquisition.
- User Engagement Tracking:Cohort-based retention analysis and LTV prediction models. Fintech apps in Brazil leverage this for credit product cross-sell attribution.
- Attribution Reporting:Standardized post-install event correlation and ROAS calculation. Budget-constrained advertisers increasingly substitute Google Ads App Campaigns native reporting.
- Fraud Detection:Automated invalid traffic filtering and post-attribution verification. Invalid traffic erosion of advertiser budgets drives margin capture through this functionality tier.
Highest attach rate: Attribution Reporting. Steepest expansion trajectory: Fraud Detection.
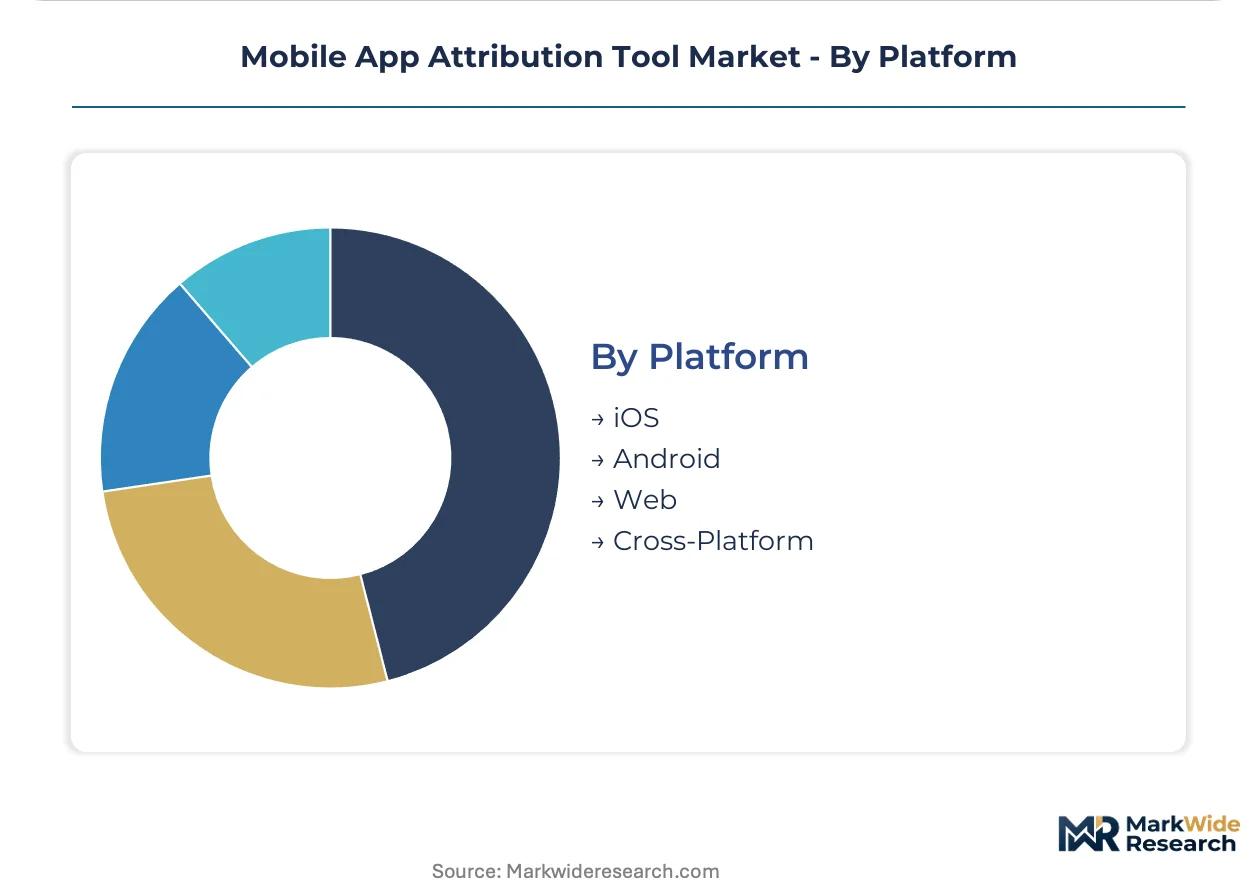
Platform:
Platform coverage dictates SDK complexity—cross-platform unification requires reconciling SKAdNetwork and Privacy Sandbox interoperability without device-level identifiers.
- iOS:SKAdNetwork-compliant measurement for Apple's privacy-preserving framework. ATT opt-out rates exceeding 70% compress deterministic signal availability.
- Android:Privacy Sandbox transition architectures replacing GAID-dependent tracking. Indian and Brazilian publishers accelerate migration timelines ahead of full deprecation.
- Web:Mobile web attribution bridging app and browser user journeys. E-commerce verticals in the United States deploy this for unified funnel analysis.
- Cross-Platform:Unified iOS-Android identity resolution without device-level identifiers. Whitespace opportunity as SKAdNetwork and Privacy Sandbox interoperability matures.
Installed base leader: Android. Gaining share fastest: Cross-Platform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli deep linking infrastructure and German privacy engineering anchor the attribution technology supply base. Cloud computing clusters in São Paulo and Mumbai concentrate demand-side procurement for elastic campaign analytics.
United States
Mobile gaming publishers and fintech apps in San Francisco and New York drive enterprise-grade attribution procurement. Apple's ATT framework and California's CCPA impose strict identifier limitations on measurement vendors. Seattle's cloud infrastructure corridor hosts AWS and Azure data centers processing seasonal advertising spikes for marketing agencies.
India
Draft Digital Personal Data Protection Bill compliance mandates accelerate vendor selection timelines among Bengaluru and Mumbai gaming studios. TRAI guidelines on data localization intersect with central government digital infrastructure programs. Hyderabad's SaaS corridor attracts attribution providers establishing sovereign cloud processing nodes for regional publishers.
Germany
GDPR Article 25 data protection by design requirements force architectural overhauls for vendors serving Frankfurt banking and Berlin gaming verticals. Federal data protection commissioners enforce stricter consent standards than EU baseline. Munich's enterprise software cluster hosts hybrid deployment specialists serving multi-jurisdiction campaigns.
Brazil
LGPD maturation creates first-mover opportunities for privacy-preserving infrastructure in São Paulo's advertising technology corridor. Central bank regulations on fintech data handling overlap with attribution requirements for credit product cross-sell. Rio de Janeiro's media buying agencies unbundle measurement contracts from holding company media deals.
Singapore
Southeast Asian gaming publishers headquartered in Singapore deploy probabilistic fingerprinting most aggressively for campaign continuity. Monetary Authority data governance guidelines affect fintech attribution workflows. The city's cloud region serves as multi-cloud failover hub for vendors operating across Indonesia, Thailand, and Philippines.
Mobile App Attribution Tool Market Competitive Landscape
Global majors compete with regional champions across privacy compliance depth and cloud infrastructure localization. The vendor base stratifies between enterprise-grade platform providers and specialized fraud detection boutiques. Three archetypes dominate: Israeli deep linking infrastructure specialists, German privacy-engineering firms, and Southeast Asian mobile gaming measurement boutiques. Competitive moves concentrate on M&A for probabilistic data science talent and strategic partnerships with hyperscaler cloud providers.
Within the infrastructure-specialist tier, AppsFlyer and Adjust exemplify contrasting geographic positioning—Tel Aviv-based deep linking capabilities versus Berlin-anchored GDPR compliance workflows. Branch occupies a position bridging cross-platform identity resolution without device-level identifiers. These three companies represent divergent responses to Apple's ATT framework constraints.
| Leading Market Players |
|---|
| AppsFlyer |
| Adjust |
| Branch |
| Singular |
| Kochava |
| Tenjin |
| Airbridge |
| Affise MMP |
| MoEngage |
| Others |
Pricing and Supply Chain Analysis
SKAdNetwork and Privacy Sandbox interoperability investments simultaneously inflate R&D cost structures and concentrate vendor capabilities among firms with differential privacy expertise. This technological transition compresses margins for attribution providers lacking probabilistic modeling talent while amplifying pricing power for cloud-native platforms serving seasonal campaign spikes.
Pricing Analysis
Service bundling separates enterprise-grade SLAs with dedicated customer success engineering from self-serve tiers with community documentation. Pricing stratifies across premium, standard, and economy tiers keyed to ISO 27001 certification depth and fraud detection functionality inclusion. Cost compression in the startup tier is intensifying because platform-native attribution from Google Ads App Campaigns displaces independent measurement for budget-constrained advertisers. Marketing agencies exhibit lowest price sensitivity due to unbundled procurement mandates, while individual developers show highest sensitivity driving freemium adoption.
Supply Chain Analysis
Cloud region latency costs shape vendor infrastructure decisions across São Paulo, Mumbai, and Singapore nodes. Attribution technology supply concentrates in Israel, Germany, and the United States, drawing from probabilistic data science talent pools and deep linking engineering expertise. Raw material dependencies include AWS Azure GCP compute provisioning, SDK integration frameworks, and server-to-server API architectures. Single-source vulnerability concentrates around hyperscaler concentration in specific sovereign cloud regions. Distribution runs through direct enterprise sales teams, agency holding company partnerships, and self-serve developer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around privacy-preserving measurement infrastructure as Apple's ATT framework and GDPR enforcement eliminate attribution vendors lacking differential privacy capabilities. Compliance complexity forces weaker players toward platform-native walled gardens or exit.
For Market Incumbents: Deepen vertical integration into probabilistic data science talent acquisition through targeted hiring in Tel Aviv and Berlin clusters. Anchor enterprise retention by localizing data processing within EU sovereign cloud regions under GDPR Article 25 mandates. Defend against platform-native attribution substitution by unbundling fraud detection as standalone margin capture.
For New Entrants and Emerging Players: Enter via Brazil's LGPD maturation window before established vendors deploy privacy-preserving infrastructure at scale. Target São Paulo fintech attribution workflows where central bank regulations on credit product cross-sell create compliance urgency. Pursue channel partnerships with Rio de Janeiro media buying agencies disintermediating holding company measurement contracts.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscaler cloud providers seeking attribution layer integration for advertising technology stacks. Long-term viability favors vendors with SKAdNetwork-Privacy Sandbox interoperability and multi-cloud deployment capabilities. Watch ATT opt-out rate trajectories as inflection indicator for probabilistic modeling demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Infrastructure Deployment | LGPD and GDPR compliance mandates in São Paulo and Berlin create first-mover procurement advantage. |
| Probabilistic Data Science Talent Acquisition | Differential privacy expertise scarcity in Tel Aviv commands premium compensation and constrains R&D velocity. |
| Multi-Cloud Sovereignty Compliance | Redundant AWS-GCP-Azure architectures satisfy India's draft Digital Personal Data Protection Bill localization requirements. |
| Fraud Detection Capability Unbundling | Standalone invalid traffic filtering captures margin pools as ad budget erosion from fake installs intensifies. |
| Cross-Platform Identity Convergence | SKAdNetwork-Privacy Sandbox interoperability addresses iOS-Android measurement whitespace without device identifiers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with mobile gaming publishers, marketing agency procurement leads, attribution platform CTOs, and privacy compliance officers combined with bottom-up and top-down triangulation. Secondary sources encompassed TRAI guidelines, CNIL enforcement actions, SEC 10-K disclosures from listed advertising technology firms, and hyperscaler capex reports. App Annie and Sensor Tower usage analytics provided install volume validation across Southeast Asian markets.
Segmentation granularity modeled deployment topology at the installation level, end-user scale at the procurement function maturity tier, and platform coverage at the SKAdNetwork-GAID-Privacy Sandbox transition stage. Value projections across the analysis window derived from elasticity modeling of seasonal campaign spend patterns and fraud detection attach rates. CAGRs were computed from triangulated vendor revenue disclosures and agency budget allocation surveys. Industry-specific inputs included ATT opt-out rate trajectories, LGPD implementation timelines, and cloud region expansion announcements.
Revisions become necessary when Apple's ATT framework modifications, GDPR enforcement variance, or Privacy Sandbox deprecation schedules materialize differently than modeled. Forecasts reflect assumptions around probabilistic modeling accuracy bands and cross-platform identity resolution timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global System Monitoring Market
Analytics
Global Industrial Analytics Market
Analytics
Business Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Global Telco Data Monetization Market
Analytics
Europe Retail Analytics Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Data Preparation Market
Analytics
APAC Data Wrangling Market
Analytics
Global Telecom Analytics Market
Analytics
Business Value Dashboard Market
Analytics
Brazil Geospatial Analytics Market