
 BI and Analytics Market | 2026-2036
BI and Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
BI and Analytics Market Analysis
GDPR is consolidating the cost-of-entry calculus for vendors serving European data environments. Microsoft Corporation leverages its Azure cloud fabric to anchor enterprise deployments across regulated industries. SAP SE sustains deep ERP integration that differentiates its analytics stack from point-solution competitors.
Business intelligence and analytics encompass software platforms that ingest structured and unstructured data, apply statistical models and machine learning algorithms, and render actionable insights through visual interfaces or automated alerts. These systems typically process petabyte-scale datasets with sub-second query response times to support operational and strategic decisions. Cloud-based deployment leads solution architecture as enterprises prioritize elastic compute and reduced capital overhead, while predictive analytics commands expanding R&D investment as organizations seek anticipatory rather than retrospective capabilities. Dashboarding remains the mature margin pool where standardization allows vendors to extract recurring revenue with minimal incremental engineering.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape product roadmaps for vendors operating across European jurisdictions. The US Securities and Exchange Commission mandates climate disclosure rules that drive demand for ESG analytics modules among publicly traded firms. Stakeholders must monitor how divergent regulatory timelines between Brussels and Washington create compliance complexity that favors modular, jurisdiction-configurable platform architectures over monolithic deployments.
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing vendors to re-architect platforms for algorithmic transparency and data residency, compressing deployment timelines while elevating compliance engineering to a core competitive differentiator.
Growth Catalysts
- Healthcare Analytics Expansion:Hospitals and health systems deploy predictive models for patient outcome optimization, embedding analytics into clinical workflows and revenue cycle management.
- GDPR Compliance Investment:European enterprises accelerate spending on governance tools to satisfy data residency and consent management requirements, creating sustained demand for jurisdiction-configurable platforms.
- Real-Time Infrastructure:Financial services and logistics operators build sub-second query capabilities for operational decision-making, pulling cloud-native architectures into mission-critical environments.
Market Restraints
- Data Engineering Talent Scarcity:Shortages of ML operations specialists and cloud architects constrain implementation velocity, particularly for mid-market buyers lacking captive technical resources.
- Legacy System Entrenchment:On-premise data warehouses and proprietary ETL pipelines resist migration, creating integration friction that extends deployment cycles and elevates professional services dependency.
- Cross-Border Data Friction:Divergent sovereignty requirements between Brussels and Washington fragment cloud architectures, forcing redundant infrastructure investments that compress vendor margins.
Strategic Opportunities
- Edge Analytics Deployment:Manufacturing and energy operators process sensor data at plant level, bypassing cloud latency for safety-critical and real-time optimization use cases.
- ESG Disclosure Automation:SEC climate rules and EU CSRD drive demand for carbon accounting modules integrated into existing BI stacks, opening new subscription revenue pools.
- Natural Language Interfaces:Conversational query tools lower adoption barriers for non-technical users, expanding addressable user bases beyond traditional analyst populations.
Industry Challenges
- Model Interpretability Requirements:Regulated industries face escalating demands for explainable AI, forcing engineering trade-offs between predictive accuracy and audit trail transparency.
- Multi-Cloud Orchestration Complexity:Enterprises distribute workloads across AWS, Azure, and GCP to avoid lock-in, creating data governance fragmentation that vendors must absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BI and Analytics Market |
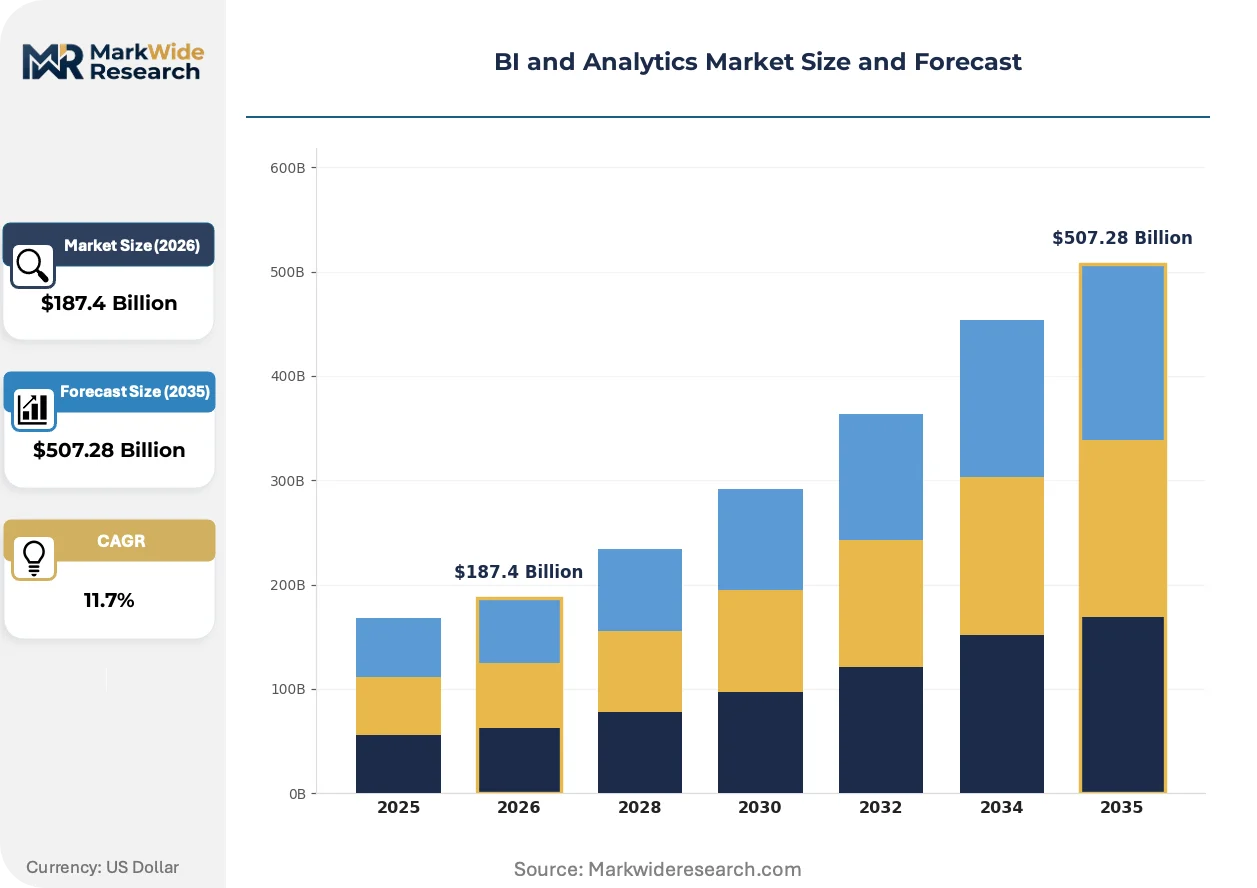
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Solution Type: Data Visualization, Reporting, Predictive Analytics, Dashboarding End User: Small Enterprises, Large Corporations, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Retail, Finance, Manufacturing |
| Companies Covered | Microsoft Corporation, SAP SE, Oracle Corporation, International Business Machines Corporation, SAS Institute Inc., Salesforce Inc., Amazon Web Services Inc., Google LLC, Tableau Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BI and Analytics Market Emerging Trajectories
Generative AI capabilities are embedding into analytics workflows, transforming query construction and insight narration while compressing the skill threshold for sophisticated data exploration.
Large language models are integrating with semantic layers to translate natural language into optimized SQL, enabling business users to interrogate petabyte-scale datasets without coding proficiency. Retail and professional services firms pilot these interfaces at departmental scale, with early adopters reporting 40-60% reduction in ad-hoc reporting queues. The technology is integrating exploratory analysis into daily operational rhythms previously reserved for dedicated analytics teams.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-stakes predictive applications, particularly credit scoring and hiring algorithms. Financial institutions and HR technology vendors face 12-18 month compliance roadmaps to satisfy conformity assessments. Automated model monitoring and bias detection tools command premium pricing as regulated buyers prioritize audit-ready deployments over raw predictive performance.
Buyers increasingly unbundle implementation and managed services from software subscriptions, treating analytics platforms as infrastructure commodities while sourcing specialized expertise through systems integrators. This pattern concentrates pricing pressure on pure-play vendors lacking professional services depth. Healthcare and public sector procurement in Germany and France most visibly exhibits this bifurcation, with RFP structures separating platform licensing from multi-year transformation partnerships.
BI and Analytics Market Segmentation
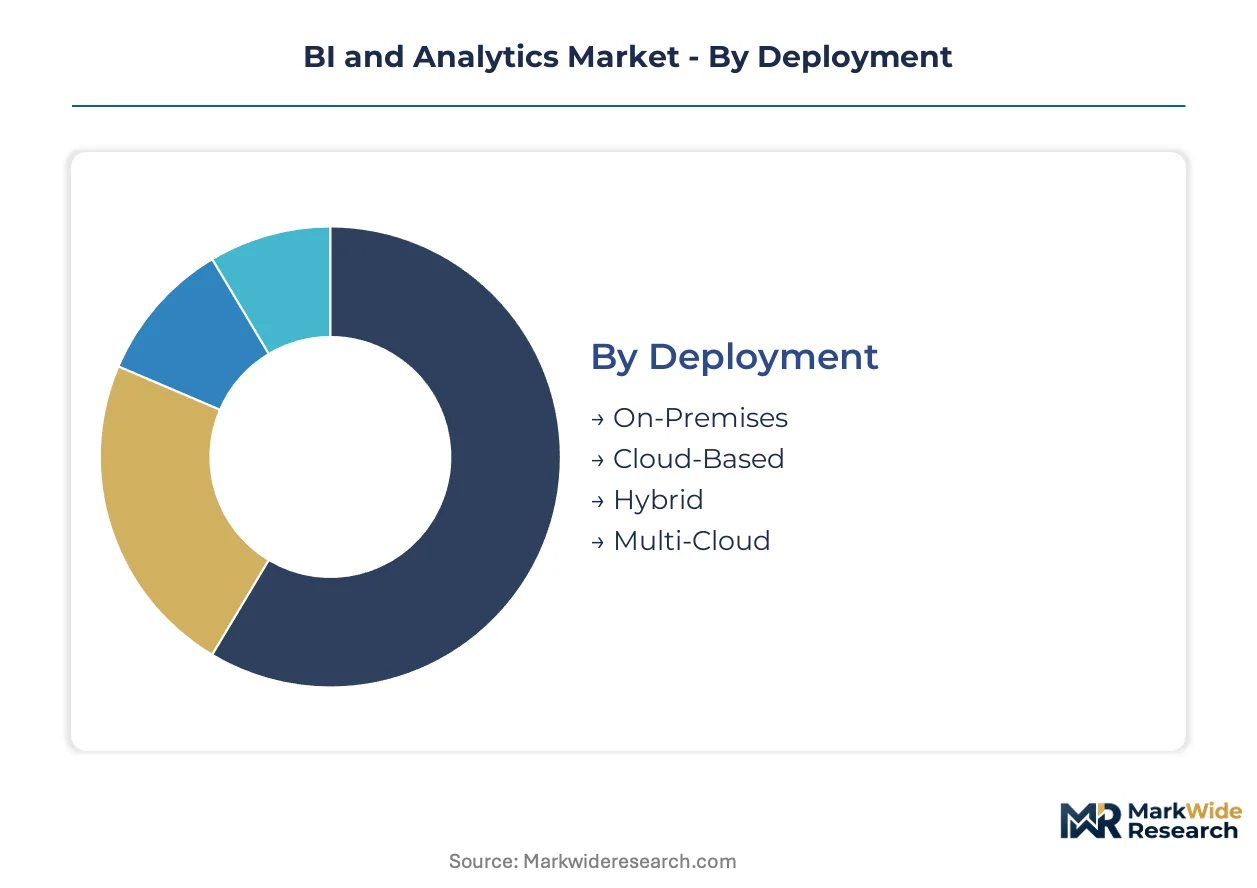
Segmentation in BI and analytics reveals how architectural choices, user sophistication, and regulatory exposure reshape vendor priorities. Cloud deployment models now dominate enterprise procurement, while predictive capabilities command premium engineering investment. Understanding these divisions exposes where margin pools concentrate and which configurations face compliance friction.
Deployment:
Technology architecture determines latency profiles, data sovereignty compliance, and capital commitment structures for buyers.
- On-Premises:Hardware-resident installations within enterprise data centers deliver sub-millisecond query response for sensitive workloads. Financial institutions in Germany and Switzerland maintain these configurations to satisfy FINMA and BaFin audit requirements for trading algorithms.
- Cloud-Based:Elastic compute provisioning through hyperscale providers eliminates upfront infrastructure spend. Healthcare systems in the United States deploy these environments for population health analytics, leveraging HIPAA Business Associate Agreements with AWS and Azure.
- Hybrid:Partitioned architectures keep regulated data on-premise while bursting analytics workloads to cloud. Manufacturing firms with OT/IT convergence requirements favor this model for predictive maintenance at plant level.
- Multi-Cloud:Distributed deployments across AWS, Azure, and GCP mitigate vendor lock-in risk. European enterprises pursuing EU AI Act compliance deploy these configurations to satisfy data residency without single-provider dependency.
Cloud-Based leads on scale; Multi-Cloud leads on momentum.
Solution Type:
Functional maturity separates commoditized visualization from predictive capabilities requiring specialized talent.
- Predictive Analytics:Machine learning pipelines forecasting demand, risk, and operational outcomes from historical patterns. Logistics operators in the Netherlands embed these tools for port congestion prediction, compressing container dwell times.
- Dashboarding:Standardized visual interfaces rendering KPIs through configurable widgets. These solutions extract recurring revenue with minimal incremental engineering as standardization matures.
- Data Visualization:Exploratory interfaces enabling ad-hoc pattern recognition without coding proficiency. Marketing departments in retail chains deploy these for campaign performance diagnostics.
- Reporting:Scheduled distribution of structured outputs to stakeholder distribution lists. Public sector procurement in France structures RFPs around these capabilities for transparency mandates.
Dashboarding captures the largest installed base; Predictive Analytics shows the steepest expansion trajectory.
End User:
Organizational scale dictates implementation complexity, governance requirements, and professional services attachment rates.
- Large Corporations:Multi-divisional deployments requiring semantic layer unification across ERP instances. These buyers command dedicated customer success teams and custom roadmap influence.
- Government Agencies:Procurement through framework agreements with extended security accreditation timelines. The US SEC and EPA drive demand for audit-trail capabilities in climate and financial disclosure.
- Small Enterprises:Departmental deployments with limited data engineering resources. These buyers favor pre-configured industry templates over customization.
- Educational Institutions:Research-oriented use cases with intermittent compute spikes and grant-funded procurement cycles. University medical centers in Massachusetts and California represent concentrated demand for clinical analytics.
Large Corporations anchor revenue concentration; Government Agencies drive compliance-feature roadmaps.
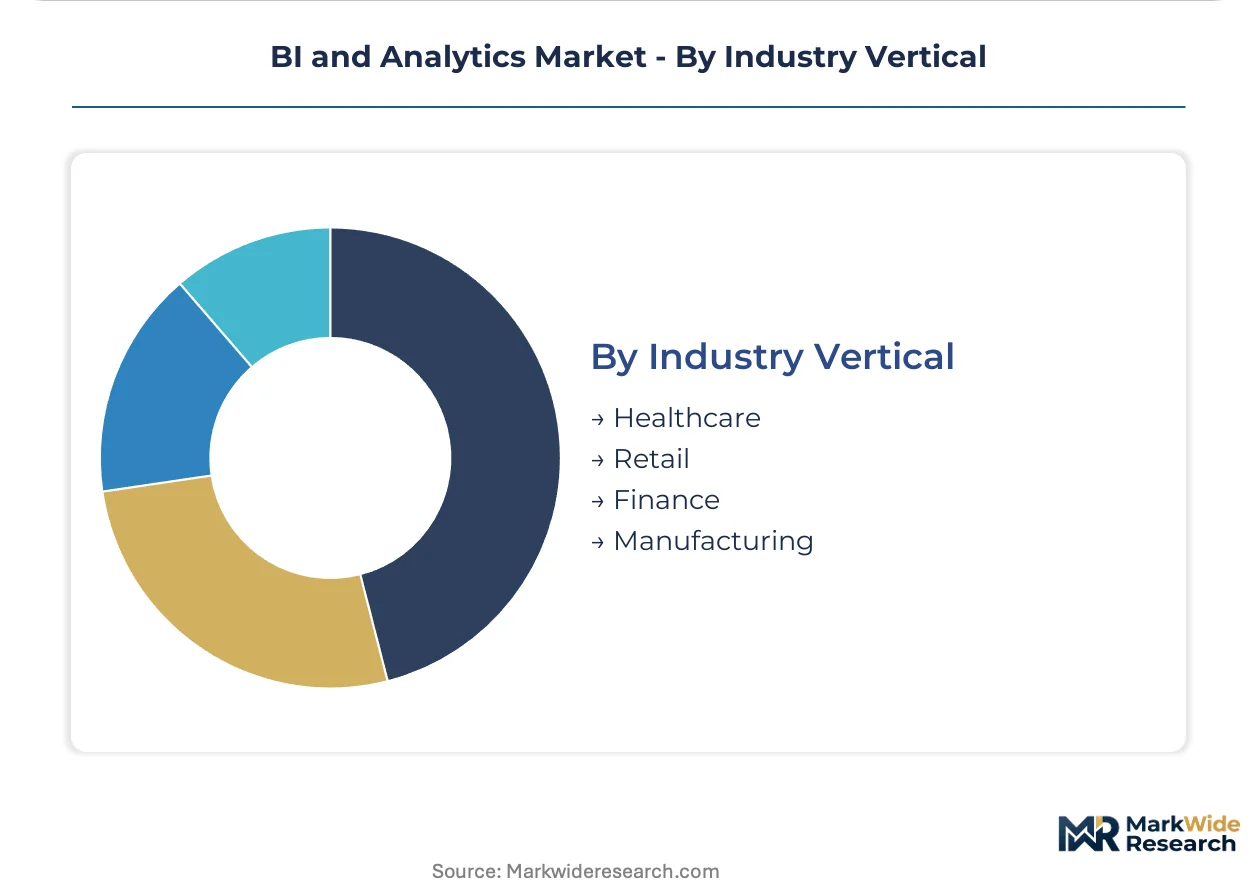
Industry Vertical:
Sector-specific data architectures and regulatory exposure create divergent vendor specialization incentives.
- Healthcare:Clinical workflow integration with HIPAA and GDPR privacy constraints. Hospital systems deploy predictive models for sepsis detection and readmission risk stratification.
- Finance:Real-time risk calculation with SEC and EU AI Act algorithmic transparency requirements. Investment banks maintain sub-second latency for trading analytics.
- Retail:Customer journey analytics across online and physical touchpoints. Merchandising teams use these tools for demand forecasting and inventory optimization.
- Manufacturing:Sensor data ingestion from production equipment for quality control and predictive maintenance. German automotive suppliers lead adoption of edge-deployed analytics.
Healthcare commands the highest compliance-driven pricing; Finance shows the fastest feature innovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data engineering talent concentrates in the United States, Germany, and India, anchoring analytics innovation clusters that shape regional deployment patterns and vendor specialization strategies.
United States
Enterprise buyers in financial services and healthcare drive demand for real-time decision infrastructure. SEC climate disclosure rules compel publicly traded firms to invest in ESG analytics modules. Hospital systems in Massachusetts and California deploy predictive models for patient outcome optimization at scale.
Germany
Automotive suppliers and industrial manufacturers prioritize edge analytics for predictive maintenance and quality control. BaFin and FINMA audit requirements sustain on-premise configurations for trading algorithms. The Stuttgart and Munich industrial clusters lead adoption of OT/IT converged analytics architectures.
United Kingdom
Financial services firms in London build sub-second query capabilities for operational risk management. The Information Commissioner's Office enforces GDPR consent management requirements across cloud deployments. The Cambridge-Oxford corridor sustains specialized ML operations talent pipelines for regulated industries.
India
IT services hubs in Bangalore and Hyderabad supply cloud architecture and data engineering capacity to global enterprises. RBI guidelines on data localization influence multi-cloud procurement patterns. Domestic healthcare providers accelerate analytics adoption for population health management in tier-1 cities.
Japan
Manufacturing conglomerates embed sensor analytics into production equipment for quality control. METI industrial policy promotes AI adoption with emphasis on explainable models for safety-critical applications. The Nagoya and Osaka industrial belts concentrate deployment of edge-deployed predictive maintenance systems.
BI and Analytics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and solution types. The market structure tilts toward consolidation as hyperscale cloud providers absorb analytics workloads into broader platform ecosystems. Three archetypes dominate: cloud-native infrastructure vendors, ERP-integrated suite providers, and independent analytics specialists. M&A activity concentrates on acquiring natural language interface capabilities and edge analytics startups, while strategic partnerships proliferate between platform vendors and systems integrators.
Within the cloud infrastructure tier, Microsoft Corporation and Amazon Web Services Inc. anchor enterprise deployments through elastic compute provisioning and compliance-certified environments. SAP SE occupies a position exemplifying deep ERP integration strategies that differentiate suite-based offerings from point solutions. These three entities represent the dominant competitive anchors shaping procurement patterns across regulated industries and geographic jurisdictions.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| International Business Machines Corporation |
| SAS Institute Inc. |
| Salesforce Inc. |
| Amazon Web Services Inc. |
| Google LLC |
| Tableau Software |
| Others |
Supply Flow & Price Mechanics
Horizontal integration through hyperscale cloud partnerships anchors supply positioning and pricing power for platform vendors serving regulated European and North American enterprises. This structural choice concentrates compute procurement leverage while compressing margins for pure-play analytics specialists lacking captive infrastructure.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes enterprise procurement patterns across the BI and analytics landscape. Subscription SaaS-tiered models dominate cloud-native deployments, with price differentiation resting on compliance certification level and customization depth. Cost compression in mid-market tiers is intensifying because buyers increasingly separate platform licensing from systems integrator partnerships. Small enterprises exhibit highest price sensitivity, while financial services buyers in Germany and Switzerland accept premium positioning for FINMA and BaFin audit-ready configurations.
Supply Chain Analysis
Regional distribution centers for cloud compute capacity concentrate in the United States, Ireland, and Singapore, anchoring global service delivery architectures. The supply chain draws from specialized semiconductor components, hyperscale data center infrastructure, and proprietary machine learning frameworks. Single-source vulnerability around GPU accelerators for generative AI workloads presents structural risk. Distribution runs through direct enterprise sales organizations supplemented by systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BI and analytics market reads as a late-cycle quality story. Demand is concentrating toward premium specifications as EU AI Act compliance mandates elevate algorithmic transparency requirements above raw performance metrics.
For Market Incumbents: Extend semantic layer unification investments to defend against point-solution disintermediation. Cloud-native entrants threaten ERP-integrated incumbents through faster deployment cycles. Vertical integration into edge analytics hardware preserves margin position for manufacturing and energy verticals.
For New Entrants and Emerging Players: Cloud-native channel partnerships offer the most penetrable route for mid-market healthcare providers lacking captive data engineering resources. Natural language interface capabilities represent white-space opportunity. Target departmental deployments in French and German public sector procurement, where framework agreements separate platform from services.
For Investors and Strategic Acquirers: Roll-up economics work for independent analytics specialists because buyer preference for modular, jurisdiction-configurable architectures fragments addressable markets. Five-to-ten year viability favors firms with explainable AI tooling depth. Watch SEC climate disclosure enforcement intensity as inflection indicator for ESG analytics module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics into ERP workflows at SAP SE and Oracle Corporation deepens switching costs. |
| Acquisition of Specialist Firm | Purchasing natural language interface startups accelerates conversational query roadmap for non-technical users. |
| Strategic Partnership | Systems integrator alliances unbundle implementation from subscription, satisfying German and French procurement patterns. |
| Product Launch | Edge analytics modules for predictive maintenance address manufacturing OT/IT convergence requirements in Stuttgart cluster. |
| Geographic Expansion | Multi-cloud deployments across AWS, Azure, and GCP satisfy EU AI Act data residency without single-provider dependency. |
Methodological Framework
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists combined with secondary validation against SEC filings, hyperscaler capex disclosures, and hospital procurement databases. Triangulation between demand-side adoption patterns and supply-side capacity expansion ensures cross-verified estimates.
Historical trendline analysis across deployment model, organization size, vertical, and integration complexity dimensions shaped the projection framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Inputs include regulatory timeline assumptions for EU AI Act implementation and healthcare analytics workflow penetration rates.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook. Forecasts reflect documented assumptions around compliance investment cycles and cloud migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Digital Analytics Solutions Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Global Social Intelligence Market
Analytics
Europe Data Monetization Market
Analytics
Europe Retail Analytics Market
Analytics
Speech Analytics Market
Analytics
Operational Intelligence Market
Analytics
Germany Geospatial Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Global Network Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Greece ICT Market
Analytics
Sentiment Analytics Market
Analytics
Europe Location Analytics Market
Analytics
RAN Analytics and Monitoring Market