
 Global Big Data Analytics in Banking Market | 2026-2036
Global Big Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Big Data Analytics in Banking Market Analysis
Retail banking is recalibrating its analytics priorities toward real-time personalization and predictive credit scoring. IBM Corporation leverages its hybrid cloud and AI stack to anchor enterprise deployments across tier-one institutions. SAP SE sustains competitive positioning through deep ERP integration that unifies transactional and analytical workloads. Microsoft Corporation dominates cloud-native banking analytics via Azure's specialized financial services compliance layers.
Big Data Analytics in Banking encompasses the collection, processing, and analysis of structured and unstructured financial datasets at petabyte scale, employing distributed computing frameworks, machine learning algorithms, and real-time stream processing to generate actionable intelligence for credit decisions, risk quantification, and customer engagement. Its primary commercial purpose is converting dormant data assets into measurable operational advantages across lending, treasury, and regulatory functions. Fraud detection applications command premium investment as institutions face escalating synthetic identity schemes and authorized push payment fraud. Machine learning technology represents the fastest-expanding capability layer, displacing rules-based systems in anomaly detection and portfolio optimization. Managed services generate durable recurring revenue as banks outsource infrastructure complexity to specialized providers.
The Federal Reserve's enhanced cyber risk management expectations, the European Banking Authority's ICT risk guidelines, and India's RBI directives on data localization collectively shape procurement standards and vendor qualification criteria. Compliance costs are redirecting budgets toward integrated governance platforms that embed regulatory reporting into core analytics workflows. Stakeholders must evaluate whether their current architecture can absorb forthcoming algorithmic accountability requirements without wholesale replacement cycles.
Market Dynamics
Real-time regulatory mandates are compressing legacy data architectures across tier-one institutions, forcing wholesale replacement of batch-processing systems with stream-native infrastructure that satisfies PSD2, GDPR, and RBI data localization simultaneously.
Growth Catalysts
- Open Banking Mandates:PSD2 in Europe and comparable frameworks in Australia and Brazil compel institutions to expose APIs, creating immediate demand for analytics platforms that monetize newly portable customer data.
- Synthetic Identity Fraud Epidemic:Authorized push payment schemes and deepfake-enabled account takeovers are electrifying investment in behavioral biometrics and transaction graph analysis.
- Cloud-Native Core Modernization:Tier-two banks in India and Southeast Asia are leapfroging mainframe dependencies, adopting serverless data lakes that slash time-to-insight from weeks to milliseconds.
Market Restraints
- Data Residency Fragmentation:Russia's data localization law, China's Cybersecurity Law, and Vietnam's cybersecurity decree fragment cloud architectures, multiplying compliance costs for multinational institutions.
- Specialized Talent Scarcity:Quantitative risk modelers with production-grade MLOps experience command premium compensation, constraining deployment velocity at regional banks.
- Legacy System Entrenchment:COBOL-dependent core banking platforms at North American and European incumbents resist API abstraction, prolonging hybrid infrastructure complexity.
Strategic Opportunities
- Embedded Finance Expansion:Non-bank platforms in Latin America and Africa require white-labeled risk scoring and KYC analytics, opening distribution beyond traditional FI boundaries.
- Climate Risk Quantification:ECB stress testing and BoE climate biennial exploratory scenarios mandate portfolio-level carbon exposure analytics, creating new service lines for data providers.
- Federated Learning Architectures:Privacy-preserving machine learning enables cross-institutional fraud pattern detection without raw data sharing, unlocking consortium models previously blocked by GDPR.
Industry Challenges
- Model Explainability Requirements:EU AI Act's prohibited-risk classification for credit scoring systems demands interpretable algorithms, complicating black-box neural network deployments.
- Data Quality Fragmentation:Inconsistent metadata standards across acquired subsidiaries and partner ecosystems corrupt training datasets, degrading predictive accuracy in production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Big Data Analytics in Banking Market |
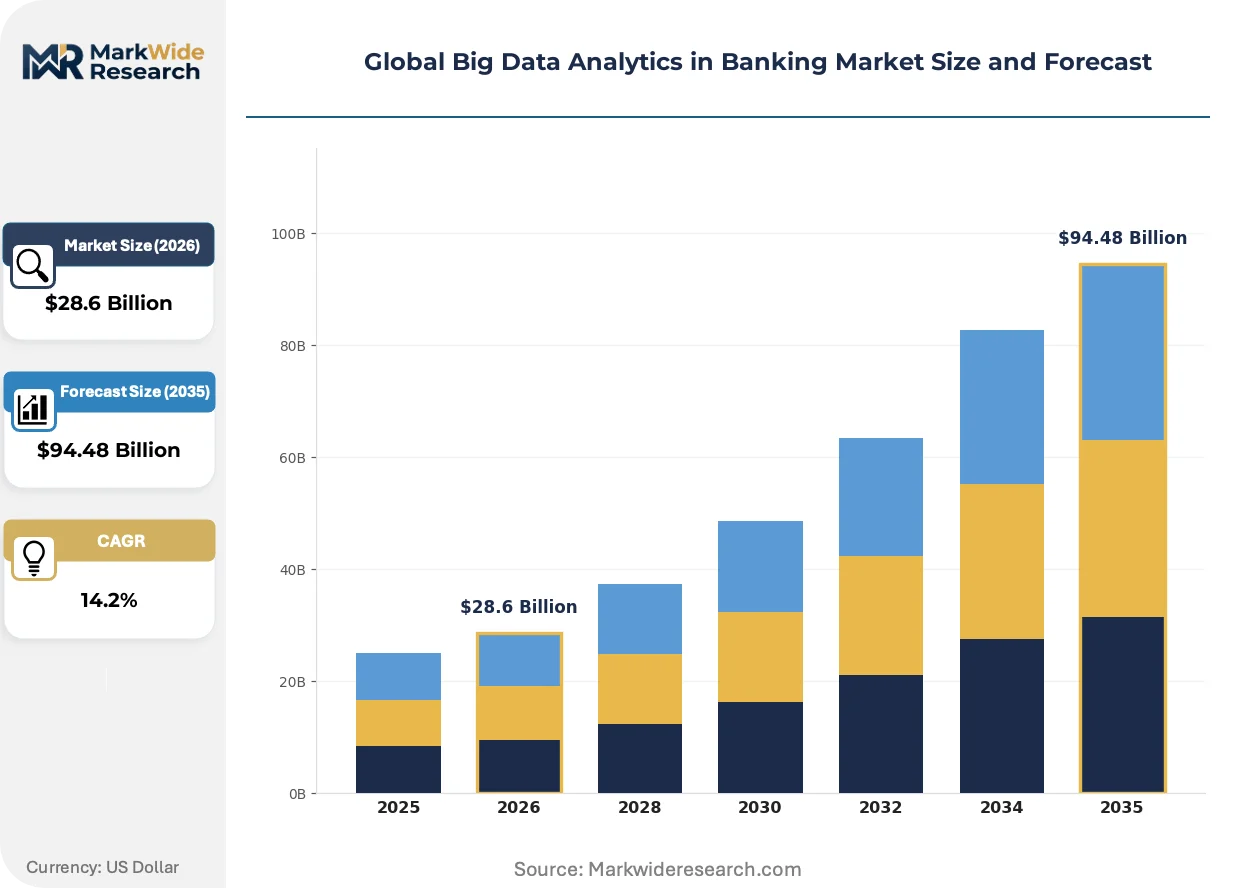
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Risk Management, Customer Analytics, Fraud Detection, Compliance Technology: NoSQL, Hadoop, Cloud Computing, Machine Learning End User: Retail Banks, Investment Banks, Credit Unions, Wealth Management Firms Service Type: Consulting, Managed Services, Training, Support |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Microsoft Corporation, SAS Institute Inc., Alteryx Inc., Amazon Web Services, Teradata Corporation, FICO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Big Data Analytics in Banking Market Emerging Trajectories
Stream processing architectures are displacing batch analytics as the default design pattern, compressing decision latency from days to sub-second intervals while embedding governance controls directly into data pipelines.
Apache Flink and Kafka Streams are electrifying real-time anomaly detection in payment networks, with tier-one institutions in Singapore and the United Kingdom deploying sub-100-millisecond fraud intervention. Capital markets desks are adopting identical infrastructure for pre-trade risk checks, collapsing the gap between transactional and analytical systems.
The EU AI Act's risk-based classification system is recalibrating procurement criteria for credit decisioning software, forcing vendors to document training data provenance and algorithmic fairness metrics. Retail banking divisions face the steepest compliance burden, reengineering model development pipelines to satisfy conformity assessment requirements before 2025 enforcement deadlines.
Buyers are consolidating vendor relationships around integrated data platforms that unify governance, analytics, and AI workloads under single commercial agreements. Regional banks in Germany and Australia are abandoning point solutions for Microsoft, Databricks, and Snowflake ecosystems, trading best-of-breed flexibility for reduced integration overhead and unified security posture.
Global Big Data Analytics in Banking Market Segmentation
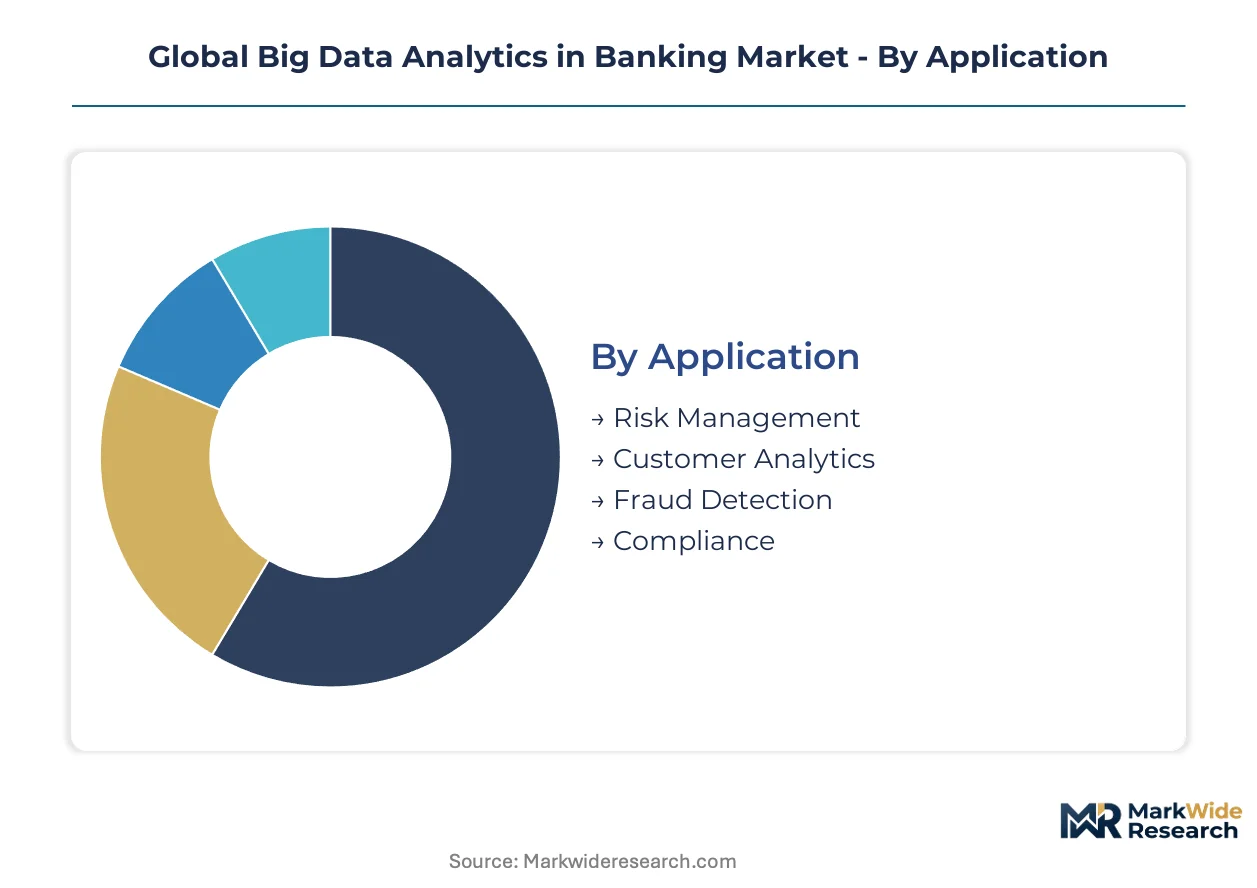
Big data analytics in banking fragments across four critical dimensions that determine procurement patterns and vendor specialization. Application requirements diverge sharply between real-time fraud intervention and batch regulatory reporting. Technology choices cascade into architectural lock-in that shapes multi-year infrastructure roadmaps.
Application:
Risk Management platforms concentrate procurement budgets at tier-one institutions rebuilding core systems under regulatory pressure.
- Risk Management:Portfolio-level credit scoring and market risk quantification consume petabyte-scale historical datasets. United States money-center banks drive demand for real-time Value-at-Risk calculations that satisfy Federal Reserve stress-testing mandates.
- Customer Analytics:Behavioral segmentation and lifetime-value modeling unify transactional, demographic, and digital channel data. Indian retail banks deploy these platforms to monetize open banking data flows under RBI guidelines.
- Fraud Detection:Graph analytics and anomaly detection identify synthetic identity schemes.
- Compliance:Automated regulatory reporting embeds audit trails directly into data pipelines.
Risk Management absorbs the bulk of installed capacity; Customer Analytics is expanding most quickly.
Technology:
Technology selection stratifies by institutional maturity, with cloud-native architectures displacing on-premise clusters at regional banks.
- Machine Learning:Production-grade MLOps pipelines automate model retraining and drift detection. United Kingdom institutions prioritize interpretable algorithms to satisfy EU AI Act conformity assessments for credit decisioning systems.
- Cloud Computing:Serverless data lakes and managed Kubernetes slash infrastructure overhead. Southeast Asian banks leverage these platforms to leapfrog mainframe dependencies without capital-intensive data center builds.
- Hadoop:Distributed batch processing retains relevance for historical risk simulations.
- NoSQL:Document and graph databases power real-time customer 360 views.
Cloud Computing dominates new deployment commitments; Machine Learning commands the steepest talent premiums.
End User:
End user categories reflect divergent data maturity and procurement sophistication across banking archetypes.
- Retail Banks:Branch networks and digital channels generate high-velocity transactional streams requiring real-time personalization engines. These institutions face the steepest compliance burden under open banking mandates and data localization requirements.
- Investment Banks:Trading desks and treasury functions demand sub-millisecond analytics for pre-trade risk checks. Singapore and London trading hubs drive adoption of stream-native architectures for market-making operations.
- Credit Unions:Member-owned structures constrain IT budgets toward managed service consumption.
- Wealth Management Firms:High-net-worth segmentation requires unified views across custody, tax, and estate planning data.
Retail Banks anchor aggregate spending; Investment Banks show the steepest expansion trajectory.
Service Type:
Service delivery models shift toward recurring revenue structures as banks outsource infrastructure complexity.
- Managed Services:Fully outsourced platform operations include 24/7 monitoring, patch management, and regulatory update implementation. German regional banks favor these arrangements to compensate for internal MLOps talent scarcity.
- Consulting:Architecture design and data governance framework development precede technology procurement. Australian institutions engage these services to navigate APRA cloud risk guidance and CPS 234 cybersecurity standards.
- Training:Certification programs upskill internal teams on vendor-specific platforms.
- Support:Tiered response contracts guarantee resolution timelines for production incidents.
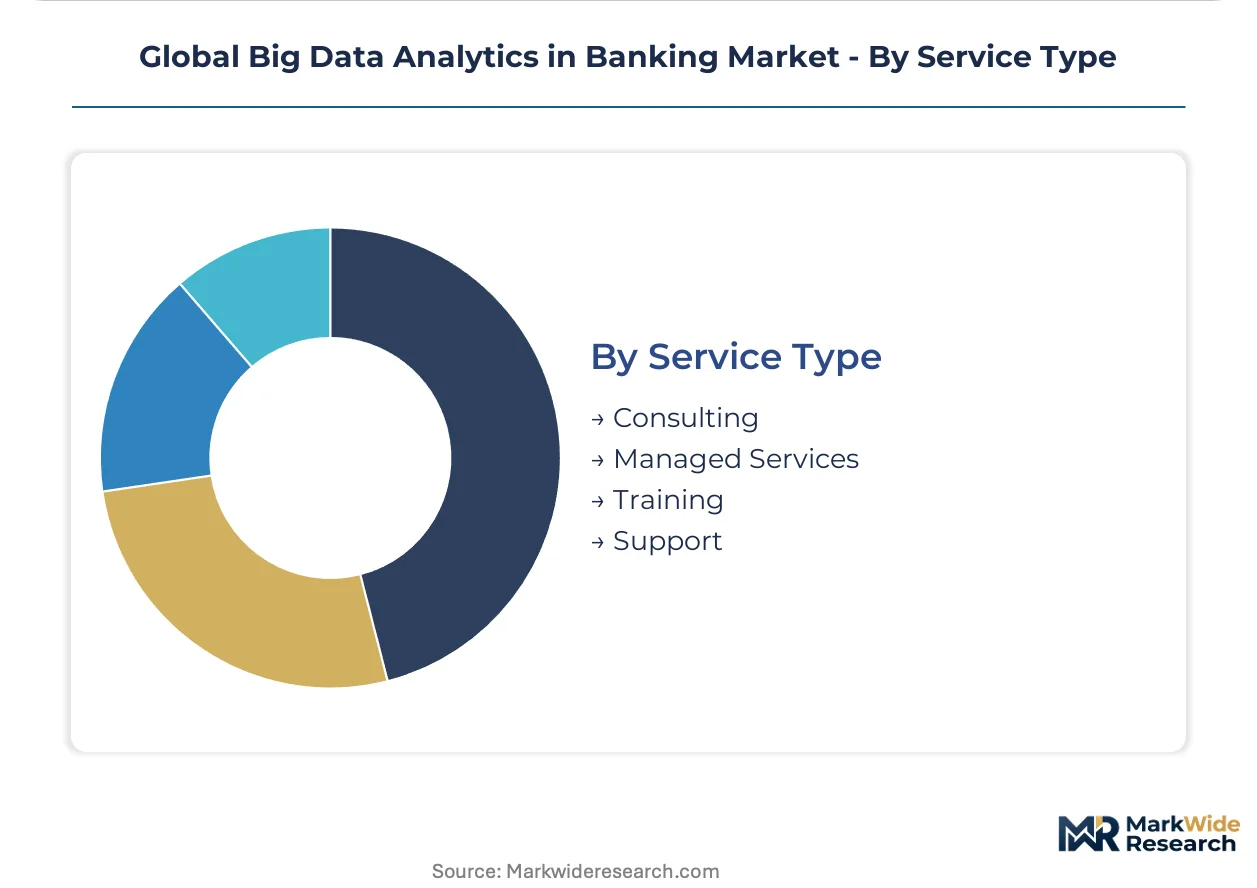
Managed Services captures the largest share of recurring revenue; Consulting shows the fastest climb in project pipeline value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Singapore, Dubai, and Bangalore concentrate fintech infrastructure investment, drawing hyperscale cloud deployments and regulatory sandbox frameworks that accelerate banking analytics modernization.
United States
New York-based money-center banks drive demand for real-time Value-at-Risk calculations and stress-testing platforms. The Federal Reserve's enhanced cyber risk management expectations reshape procurement standards for tier-one institutions. Chicago and San Francisco trading clusters adopt stream-native architectures for pre-trade risk checks.
United Kingdom
London's open banking ecosystem generates API monetization demand under PSD2 mandates. The EU AI Act's prohibited-risk classification for credit scoring forces interpretable algorithm adoption. Edinburgh and Manchester regional banks consolidate vendor relationships around integrated data platforms.
Germany
Frankfurt's banking hub rebuilds core systems under ECB climate stress-testing requirements. The Bundesbank's oversight of ICT risk guidelines shapes vendor qualification criteria. Bavarian regional banks favor managed services to compensate for MLOps talent scarcity.
India
Mumbai and Bangalore anchor retail bank adoption of real-time customer analytics platforms. RBI directives on data localization force cloud architecture redesigns. Hyderabad's fintech corridor leapfrogs mainframe dependencies with serverless data lake deployments.
Singapore
Marina Bay financial institutions deploy sub-100-millisecond fraud intervention systems. The Monetary Authority of Singapore's digital banking licenses accelerate cloud-native core modernization. The city-state's regulatory sandbox attracts ASEAN regional banks seeking compliant analytics infrastructure.
Global Big Data Analytics in Banking Market Vendor Landscape
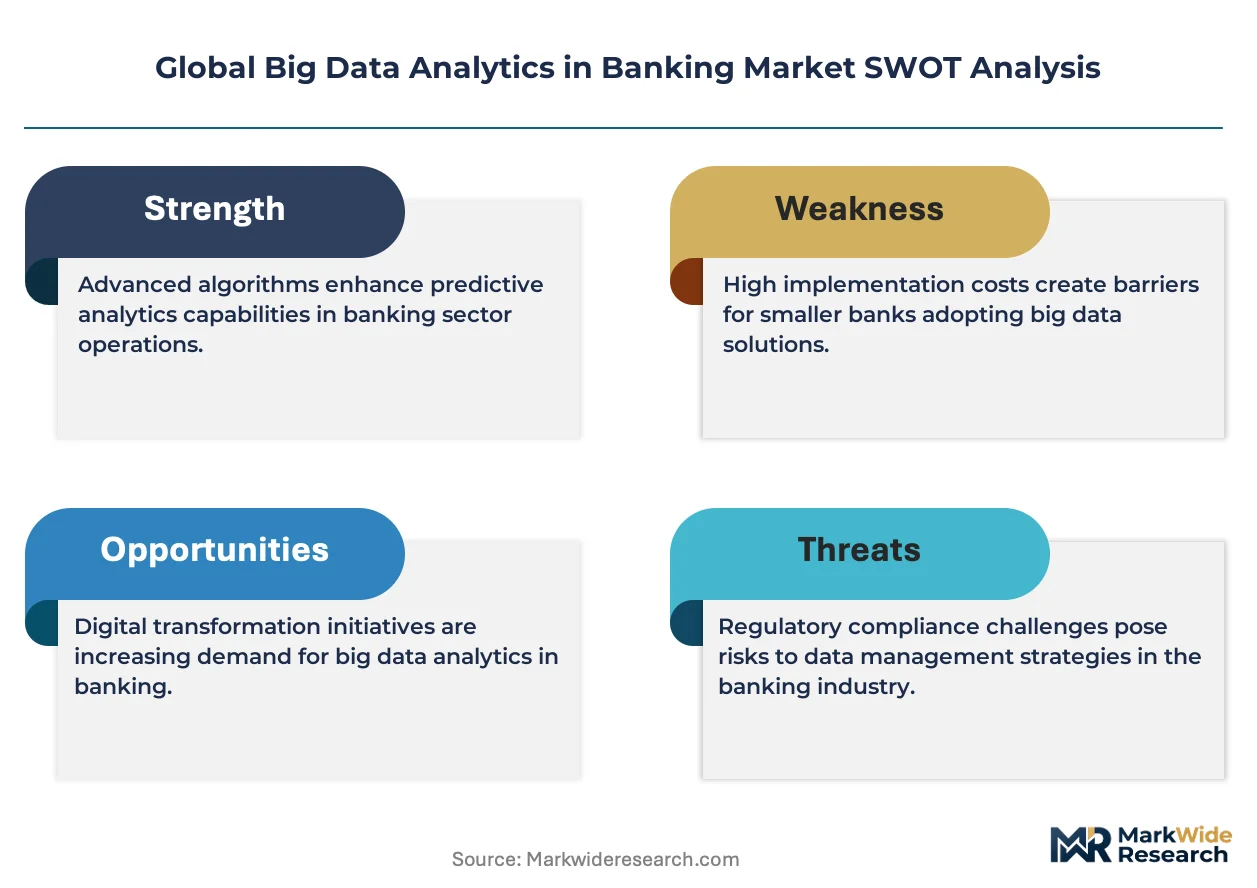
Branded specialists and contract manufacturers split share differently across segments, with consolidated hyperscale platforms dominating cloud-native deployments while boutique analytics firms retain pockets in regulatory compliance niches. The vendor base stratifies into three tiers: full-stack infrastructure providers, specialized AI/ML platform vendors, and managed service operators. Tier-one institutions favor integrated ecosystems that unify governance, analytics, and AI workloads under single commercial agreements. Dominant competitive moves include strategic partnerships between cloud providers and core banking software vendors, plus vertical integration into data pipeline tooling.
Within the full-stack infrastructure tier, IBM Corporation and Microsoft Corporation anchor enterprise deployments across tier-one institutions, exemplifying the hybrid cloud and AI stack archetype that unifies transactional and analytical workloads. SAP SE occupies a position representing deep ERP integration specialists, while Oracle Corporation sits within the database-centric platform category serving institutions with legacy data warehouse dependencies.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| SAS Institute Inc. |
| Alteryx Inc. |
| Amazon Web Services |
| Teradata Corporation |
| FICO |
| Others |
Supply Flow & Price Mechanics
ECB climate stress-testing mandates gate qualified supply for portfolio-level carbon exposure analytics platforms, restricting premium-tier pricing access to vendors with documented training data provenance and algorithmic fairness certifications under EU AI Act conformity assessment frameworks.
Pricing Analysis
Short lead-time deployments command substantial premiums as tier-one institutions face compressed replacement cycles for batch-processing systems under real-time regulatory mandates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments, with hyperscale cloud providers anchoring premium tiers through integrated governance-analytics-AI bundles. Cost compression in the standard tier intensifies because regional banks consolidate vendor relationships around unified platforms, trading flexibility for reduced integration overhead. Credit unions and member-owned structures exhibit the highest price sensitivity, while investment banks with sub-millisecond latency requirements demonstrate the lowest.
Supply Chain Analysis
Dual-sourcing requirements for MLOps talent and cloud infrastructure compel tier-one institutions to qualify multiple hyperscale providers alongside specialized AI platform vendors. Supply concentrates in the United States, India, and Germany, with Mumbai and Bangalore anchoring analytics engineering capacity and Frankfurt hosting regulatory compliance expertise. Raw material dependencies encompass GPU compute clusters, proprietary training datasets, and federated learning orchestration software. Single-source vulnerability in specialized quantitative risk modelers with production-grade MLOps experience elevates procurement risk. Distribution runs through direct enterprise sales teams and systems integrator partnerships for managed service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU AI Act's prohibited-risk classification for credit scoring systems erects a barrier-to-entry moat favoring vendors with pre-positioned interpretable algorithm portfolios and documented conformity assessment capabilities.
For Market Incumbents: Extend platform integration depth by embedding regulatory reporting directly into core analytics workflows, neutralizing substitute threats from point-solution specialists. Anchor capacity addition in Singapore and Bangalore to capture ASEAN and Indian regional bank modernization cycles. Prioritize certification investment in climate risk quantification modules to satisfy ECB and BoE stress-testing mandates. For New Entrants and Emerging Players: The premium-to-economy price-point gap in managed services for MLOps talent-scarce regional banks offers the most penetrable white-space target. White-labeled risk scoring and KYC analytics for embedded finance platforms in Latin America and Africa represent a second viable entry vector. Pursue channel partnerships with core banking software vendors rather than direct enterprise sales to accelerate credibility establishment. For Investors and Strategic Acquirers: Federated learning consortium announcements among European institutions are the leading indicator that privacy-preserving cross-institutional collaboration is shifting from pilot to production-scale deployment. Position acquisition screening around boutique analytics firms with regulatory compliance niches and documented EU AI Act readiness. Deviation in algorithmic accountability enforcement timelines would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying governance, analytics, and AI workloads under single commercial agreements reduces procurement friction for tier-one institutions. |
| Strategic Partnership | Alliances between hyperscale cloud providers and core banking software vendors collapse time-to-deployment for serverless data lake architectures. |
| Acquisition of Specialist Firm | Boutique regulatory compliance vendors with EU AI Act documentation capabilities command scarcity premiums in consolidated procurement cycles. |
| Geographic Expansion | Singapore's regulatory sandbox attracts ASEAN regional banks seeking compliant analytics infrastructure with sub-100-millisecond latency benchmarks. |
| Product Launch | Climate risk quantification modules embedding ECB and BoE stress-testing scenarios open new service lines for data providers. |
Methodological Framework
Independent corroboration across primary interviews with chief data officers, MLOps engineering leads, regulatory compliance officers, and procurement executives at tier-one and regional banks underwrites the qualitative findings. Secondary validation draws from SEC filings of publicly traded cloud providers, RBI directives on data localization, ECB climate stress-testing documentation, and EBA ICT risk guidelines. Bottom-up and top-down triangulation reconciles vendor-reported deployment metrics with institution-stated budget allocations.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window, modeling application segments including risk management, customer analytics, fraud detection, and compliance workflows alongside technology layers spanning machine learning, cloud computing, Hadoop, and NoSQL architectures. End-user stratification captures retail banks, investment banks, credit unions, and wealth management firms with divergent latency requirements and procurement sophistication. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion.
Inputs from regulatory filing databases and vendor disclosure documents were available through the study window; gaps in proprietary training dataset composition and model performance benchmarks introduce uncertainty bands around competitive positioning assessments. Deviation in EU AI Act enforcement intensity or RBI data localization implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Video Banking Service Market
Banking
Mobile Banking Market
Banking
ATM Market
Banking
North America Bank Kiosk Market
Banking
Saudi Arabia Retail Banking Market
Banking
Data Analytics in Banking Market
Banking
Global Neobanking Market
Banking
Global Retail Core Banking Systems Market
Banking
Singapore Neobanking Market
Banking
Brazil Retail Banking Market
Banking
US Retail Banking Market
Banking
Europe Neobanking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Smart Machines in Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Corporate Digital Banking Market