
 Europe Banking-As-A-Service Market | 2026-2036
Europe Banking-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Banking-As-A-Service Market Foresight
PSD2 compliance certification is collapsing the barrier between fintech entrants and licensed banking operations across Europe. Solaris leverages its German banking license to anchor embedded finance offerings for pan-European clients. Starling Bank competes through its proprietary technology stack, while Thought Machine differentiates via cloud-native core banking architecture that extends deployment flexibility.
Banking-as-a-Service denotes the provision of licensed banking infrastructure—encompassing account creation, payment rails, and regulatory compliance—via API-accessible platforms that integrate into third-party applications. The model eliminates capital-intensive charter acquisition, reducing time-to-market from years to months for financial product deployment. Payment processing and account management services dominate current revenue pools, though lending solutions represent the fastest-expanding segment as non-bank platforms embed credit origination. Cloud-based platform types lead deployment preferences, while hybrid configurations gain traction among established institutions navigating data sovereignty constraints.
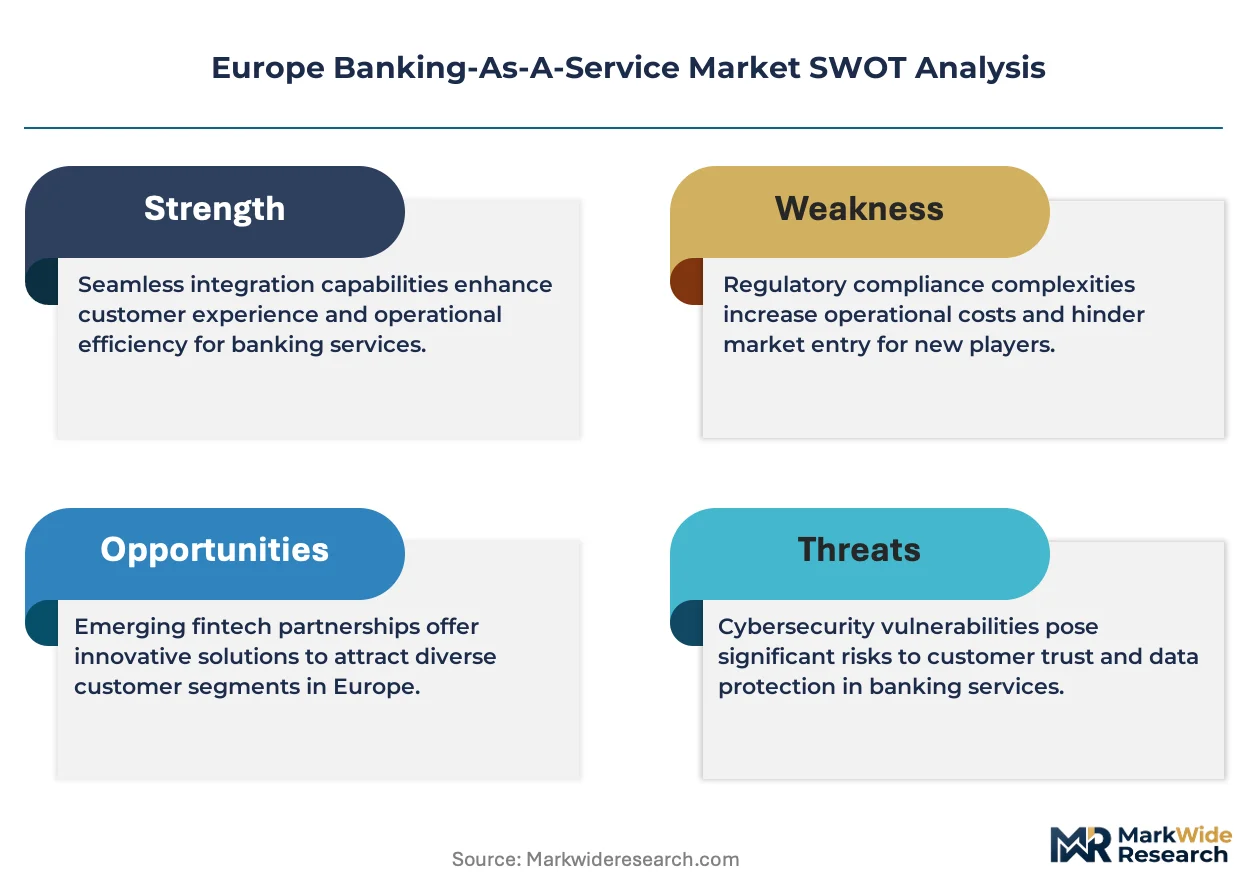
European Banking Authority guidelines, PSD2 operational standards, and national regulators such as BaFin in Germany and the FCA in the United Kingdom collectively determine licensing pathways and capital requirements for BaaS participants. EBA oversight of outsourcing arrangements specifically constrains how providers structure client bank partnerships and subcontract critical functions. Stakeholders must monitor evolving PSD3 negotiations and the European Commission's digital finance strategy to anticipate shifts in passporting rights and third-party liability frameworks.
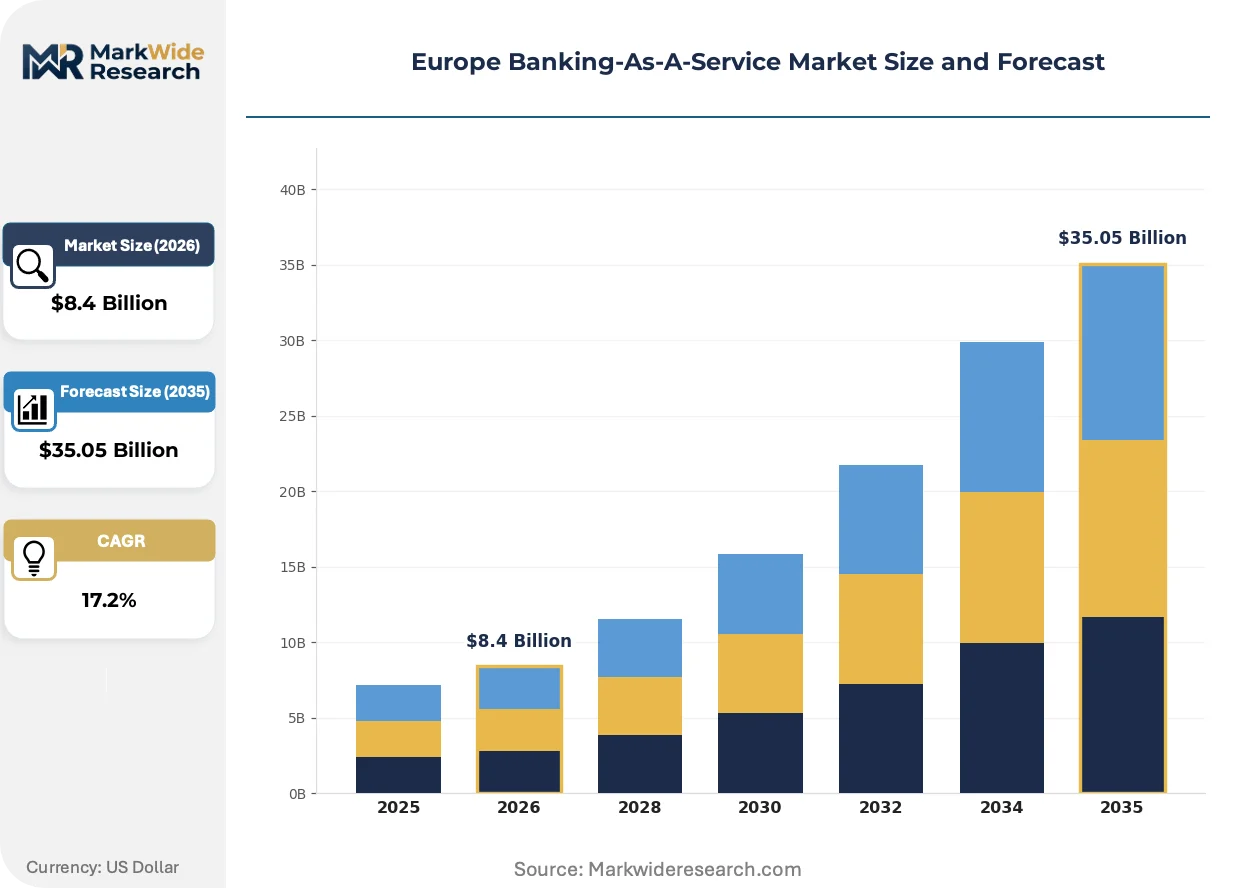
Market Dynamics
PSD2's open banking mandates have forced traditional deposit-taking institutions to expose payment infrastructure via standardized APIs, creating the regulatory substrate upon which Banking-as-a-Service platforms now compete for fintech distribution partnerships.
Growth Catalysts
- PSD3 framework anticipation:The European Commission's forthcoming directive promises to clarify third-party liability and strengthen passporting rights, reducing legal ambiguity for cross-border BaaS deployments.
- Embedded finance penetration:Non-financial platforms in e-commerce, logistics, and payroll services are integrating licensed banking products directly into customer journeys, expanding addressable demand beyond standalone fintech applications.
- German regulatory depth:BaFin's established licensing precedent and supervisory clarity have concentrated BaaS infrastructure investment in Berlin and Frankfurt, creating regulatory network effects that attract pan-European clients.
Market Restraints
- Capital reserve requirements:EBA guidelines mandate substantial liquidity buffers for institutions holding customer deposits, elevating fixed costs that constrain smaller BaaS entrants.
- Cloud concentration risk:Dominant hyperscale providers for EU data residency create single-point-of-failure exposure that national regulators increasingly scrutinize under outsourcing directives.
- Core banking substitution:Modern cloud-native ledger architectures threaten incumbent BaaS providers running legacy mainframe infrastructure, compressing technical differentiation windows.
Strategic Opportunities
- Eastern European expansion:Poland, Romania, and the Baltic states exhibit low banking infrastructure penetration relative to fintech startup density, creating first-mover positioning for licensed BaaS entrants.
- Credit origination embedding:Lending-as-a-Service remains underdeveloped relative to payments and account management, offering margin expansion for providers that master automated underwriting integration.
- CSRD alignment services:The EU's Corporate Sustainability Reporting Directive creates compliance-as-a-service demand that BaaS platforms can bundle with financial infrastructure.
Industry Challenges
- API standardization gaps:Inconsistent implementation of Berlin Group and STET specifications across national markets forces costly adapter development for pan-European BaaS coverage.
- Operational resilience certification:DORA's digital operational resilience act imposes incident reporting and stress testing obligations that stretch mid-tier BaaS engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Banking-As-A-Service Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $35.05 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Account Management, Lending Solutions, Compliance Management End User: Fintech Startups, Traditional Banks, Credit Unions, Investment Firms Platform Type: Cloud-Based, On-Premises, Hybrid, Mobile Licensing Model: Subscription, Pay-Per-Use, Tiered Pricing, One-Time Fee |
| Companies Covered | Solaris, Bankable, ClearBank, Treezor, Railsr, ConnectPay, Starling Bank, Thought Machine, Griffin, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Banking-As-A-Service Market Shifts & Advancements
Banking infrastructure is fragmenting into modular, API-first components that separate regulatory licensing from technology delivery, compressing the traditional vertical integration model that tied charter holding to proprietary software stacks.
Cloud-native core banking architecture is decomposing the monolithic ledger systems that previously anchored BaaS offerings. Tier-2 fintechs and neobanks are adopting containerized banking engines at accelerating velocity. This decomposition enables providers to swap regulatory jurisdictions without replacing entire technology stacks, reducing charter-dependent lock-in.
EBA guidelines on outsourcing arrangements are tightening scrutiny of critical function subcontracting across EU member states. The framework compels BaaS providers to maintain direct operational control over customer-facing processes. German and Dutch regulators have moved fastest in enforcing materiality assessments for cloud-dependent banking services.
Revenue model unbundling is displacing all-in-one BaaS subscriptions with granular, usage-based pricing for individual payment rails, compliance modules, and ledger services. Embedded finance buyers in retail and SaaS verticals are demanding component flexibility that matches their own product architecture. France and the Nordics show the steepest adoption curves for this procurement pattern.
Europe Banking-As-A-Service Market Segmentation
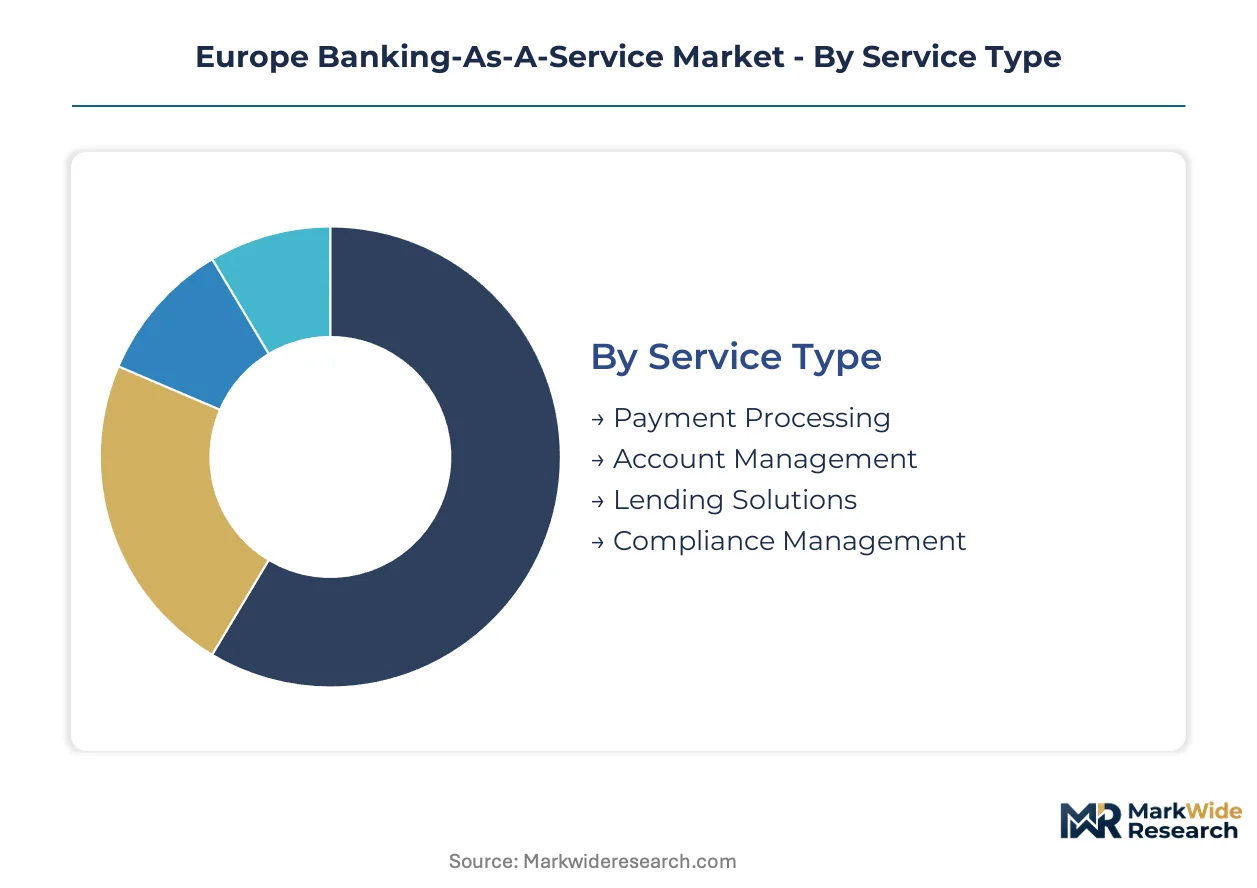
Segmentation in European Banking-as-a-Service reveals how revenue pools concentrate across service functions and platform configurations. Distinct buyer profiles and licensing preferences create divergent margin structures that providers must navigate strategically.
Service Type:
Margin pools concentrate in payment orchestration and account infrastructure, where transaction volume scales compound returns across client bases.
- Payment Processing:Real-time SEPA Instant and cross-border settlement rails form the technical backbone of most BaaS deployments. German fintech aggregators and Dutch e-commerce platforms drive concentrated demand for white-label payment acceptance. PSD2-mandated API standardization has commoditized basic connectivity, pushing providers toward value-added services.
- Lending Solutions:Automated credit origination and embedded buy-now-pay-later modules command premium pricing due to regulatory complexity and underwriting technology requirements. French retail marketplaces and Nordic payroll platforms are integrating salary-advance products fastest, drawn by higher yield spreads than pure payments.
- Account Management:Multi-currency IBAN provisioning and virtual account hierarchies support treasury centralization for cross-border merchants.
- Compliance Management:KYC orchestration, AML screening, and PSD2 Strong Customer Authentication modules address regulatory burden outsourcing.
The dominant share belongs to Payment Processing, while Lending Solutions is closing the gap fastest.
End User:
Customer acquisition costs and contract values diverge sharply across institutional maturity and regulatory sophistication.
- Fintech Startups:Venture-backed neobanks and embedded finance builders prioritize speed-to-market over customization depth. Berlin, Paris, and Amsterdam clusters exhibit highest onboarding velocity, though churn risk elevates as these firms graduate to in-house licensing.
- Traditional Banks:Incumbent institutions deploy BaaS for digital spin-offs and white-label partnerships without legacy core replacement. Spanish and Italian regional banks are outsourcing digital infrastructure fastest, constrained by internal IT capacity gaps.
- Credit Unions:Cooperative structures in Germany and Austria seek member-facing digital channels through partnership models.
- Investment Firms:Brokerage and wealth platforms require segregated account structures and custody-adjacent services.
Fintech Startups capture provider attention for volume, though Traditional Banks deliver superior contract duration and expansion revenue.
Platform Type:
Deployment architecture determines data residency compliance and operational control trade-offs that regulators scrutinize unevenly.
- Cloud-Based:Containerized core banking engines running on hyperscale infrastructure enable elastic scaling and rapid feature deployment. French and Irish regulators have established clearer outsourcing guidance than southern European counterparts, concentrating provider investment in these jurisdictions.
- Hybrid:Split configurations keep sensitive ledger data on private infrastructure while exposing customer-facing APIs through cloud edge. German automotive fleet managers and Belgian logistics platforms favor this model for operational resilience certification under DORA.
- On-Premises:Self-managed installations persist among state-affiliated institutions with sovereign data mandates.
- Mobile:SDK-first delivery targets app-native financial products with embedded onboarding flows.
Cloud-Based deployments hold the installed base majority, yet Hybrid configurations are expanding most quickly among mid-market buyers.
Licensing Model:
Revenue predictability and customer lifetime value calculations shift materially across pricing structure preferences.
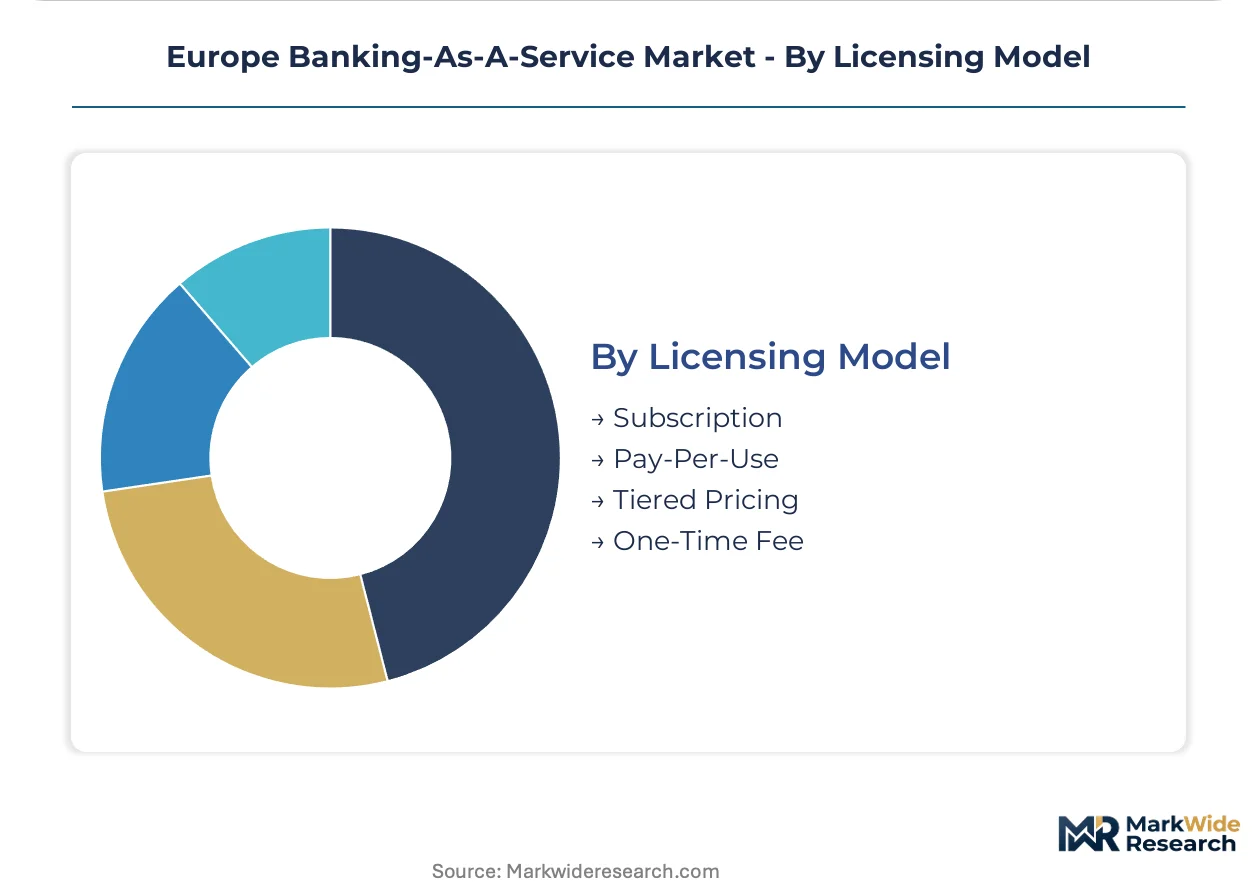
- Subscription:Fixed monthly fees for bundled API access and regulatory coverage provide cash flow stability. Nordic SaaS platforms and British payroll providers prefer this predictability for financial planning.
- Pay-Per-Use:Transaction-tied metering aligns costs with actual platform consumption. Seasonal retailers and event-ticketing ventures across southern Europe select this for demand volatility absorption.
- Tiered Pricing:Feature-gated packages separate basic connectivity from premium support and custom development.
- One-Time Fee:Perpetual licenses for isolated deployments persist in specialized institutional contexts.
Subscription structures anchor provider revenue, while Pay-Per-Use is gaining share fastest among embedded finance entrants with variable transaction profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Payment Services Directive and anticipated PSD3 framework are channeling BaaS infrastructure investment toward jurisdictions with established regulatory precedent and supervisory clarity. National implementations of open banking mandates create uneven competitive terrain across member states.
Germany
BaFin's licensing depth attracts pan-European fintech clients seeking regulatory certainty. The German central bank's oversight of outsourcing arrangements sets the standard for EU-wide compliance benchmarking. Berlin and Frankfurt clusters concentrate licensed banking infrastructure providers serving embedded finance builders across the continent.
United Kingdom
FCA's open banking regime and sandbox framework accelerate neobank partnerships with BaaS platforms. Post-Brexit regulatory divergence creates distinct compliance pathways for UK-focused versus EU-passported services. London's fintech density drives concentrated demand for API-accessible payment and account infrastructure.
France
ACPR supervision and STET payment standard implementation shape domestic BaaS deployment patterns. The country's retail marketplace sector integrates embedded lending products fastest among continental peers. Paris-based fintech aggregators leverage French banking licenses for SEPA-wide coverage.
Netherlands
DNB's early enforcement of EBA outsourcing guidelines positions Dutch BaaS providers as compliance benchmarks. Amsterdam's e-commerce platform density generates sustained demand for white-label payment acceptance infrastructure. The national regulator's clarity on cloud-based banking accelerates containerized core banking adoption.
Poland
KNF licensing frameworks and low legacy banking penetration create first-mover opportunities for licensed BaaS entrants. The country's fintech startup density exceeds incumbent digital infrastructure supply. Warsaw clusters attract embedded finance providers targeting Eastern European market expansion.
Europe Banking-As-A-Service Market Competitive Landscape
Player mix skews toward licensed banking entities with proprietary technology stacks rather than pure software vendors. Market structure concentrates around institutions holding deposit-taking charters in Germany and the United Kingdom. Three archetypes dominate: full-stack licensed banks, modular API platforms, and cloud-native core banking specialists. Competitive dynamics center on charter acquisition for regulatory passporting and technology licensing partnerships for rapid feature deployment.
Among German-licensed entities, Solaris and Treezor exemplify the full-stack archetype combining regulatory coverage with integrated payment infrastructure. Starling Bank occupies a distinct position as a UK-chartered institution competing through proprietary technology rather than third-party core banking partnerships. Thought Machine represents the cloud-native specialist tier, offering containerized ledger architecture that enables providers to swap jurisdictions without stack replacement.
| Leading Market Players |
|---|
| Solaris |
| Bankable |
| ClearBank |
| Treezor |
| Railsr |
| ConnectPay |
| Starling Bank |
| Thought Machine |
| Griffin |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservation locks in multi-year API access for embedded finance builders while insulating German-licensed providers from spot-market volatility in cloud infrastructure costs. This contract pattern concentrates pricing power with BaFin-regulated entities that can guarantee passporting rights across SEPA jurisdictions.
Pricing Analysis
Transaction volume scale creates the primary spread between tier-1 and tier-3 BaaS providers, with enterprise fintechs commanding per-call discounts below €0.001 while mid-market SaaS platforms absorb standard rates near €0.005. Three-tier pricing structure across premium compliance bundles, standard API access, and economy payment rails stratifies the market. Cost compression in the economy tier intensifies as containerized core banking engines commoditize basic ledger services. Fintech startups exhibit highest price sensitivity, while traditional banks negotiating white-label partnerships prioritize regulatory coverage over unit economics.
Supply Chain Analysis
Just-in-time provisioning of cloud-native banking infrastructure dominates buyer preferences, though German and Dutch providers maintain strategic reserves of dedicated server capacity for DORA compliance certification. Hyperscale infrastructure concentrates in Ireland, Germany, and the Netherlands, with compute capacity expansion tethered to EBA outsourcing guideline clarity. Critical dependencies span container orchestration platforms, real-time payment gateways, and KYC data enrichment APIs. Single-source vulnerability in cloud concentration risk threatens operational resilience certification timelines. Distribution runs through direct enterprise sales teams serving pan-European fintech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats for licensed banking entities, as BaFin and FCA charter acquisition timelines stretching 18-24 months create asymmetric barriers against unlicensed technology vendors.
For Market Incumbents: Compound network effects by embedding deeper into payroll and logistics verticals before cloud-native specialists achieve regulatory parity. Prioritize API standardization investments that lock in fintech clients through integration complexity. Defensive consolidation should target mid-tier providers in Poland and the Baltic states facing capital reserve requirement pressure.
For New Entrants and Emerging Players: Lending-as-a-Service infrastructure gaps in automated underwriting and credit decisioning expose white-space opportunities where incumbent BaaS platforms under-serve. Embedded finance penetration in French retail marketplaces and Nordic salary-advance products represents the most penetrable segment. Go-to-market positioning should emphasize CSRD alignment bundling to capture sustainability reporting compliance demand.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid-platform providers serving mid-market automotive and logistics buyers with DORA-certified operational resilience. Long-term viability over the projection horizon favors licensed entities with direct BaFin or FCA relationships over pure technology licensors. Acquisition targets should display proven API uptime metrics and expanding SEPA Instant transaction volumes. The signal to watch is PSD3 third-party liability clarification timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory License Expansion | BaFin charter acquisition enables passporting rights across 30 SEPA jurisdictions for embedded finance clients. |
| Cloud-Native Core Migration | Containerized ledger architecture reduces charter-dependent lock-in and accelerates cross-border deployment velocity. |
| Vertical API Unbundling | Granular pricing for payment rails and compliance modules matches embedded finance buyer procurement patterns. |
| Eastern European Market Entry | Polish and Baltic licensing frameworks offer first-mover positioning where fintech density exceeds infrastructure supply. |
| CSRD Compliance Bundling | Sustainability reporting integration captures Corporate Sustainability Reporting Directive-driven service demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECB payment statistics, EBA outsourcing guideline publications, and national regulatory filings. Primary interviews engaged BaaS platform CTOs, BaFin licensing officers, fintech procurement leads, and embedded finance product managers. Secondary validation drew from SEPA payment volume disclosures, cloud infrastructure capex reports, and EU Commission digital finance strategy documents. Bottom-up transaction volume modeling triangulates against top-down market sizing from licensed entity revenue disclosures.
Segmentation dimensions modeled span service type, platform architecture, licensing model, and end-user maturity tier across the analysis window. Deployment configuration splits between cloud-native, hybrid, and on-premises installations. CAGRs derive from transaction volume elasticity assumptions tied to embedded finance penetration curves and PSD3 implementation scenarios. Forecast inputs incorporate SEPA Instant adoption velocity and DORA operational resilience certification timelines.
Underlying assumptions cover stable EBA outsourcing guideline enforcement, with deviation risk concentrated in PSD3 liability framework negotiations and hyperscale cloud concentration regulatory intervention. Revision becomes warranted when cross-border passporting rights face material restriction or cloud infrastructure costs spike above historical elasticity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Corporate Digital Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
E-Banking Market
Banking
Machine Learning in Banking Market
Banking
Southeast Asia Commercial Banking Market
Banking
Blockchain in Retail Banking Market
Banking
Germany Banking As a Service Market
Banking
Latin America Data Analytics in Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Smart Banking Solutions Market
Banking
Cybersecurity in Banking Market
Banking
Performance Bank Guarantee Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Latin America Neo Banking Services Market
Banking
Australia Data Analytics in Banking Market