
 Video Banking Service Market | 2026-2036
Video Banking Service Market Size, Share, and Industry Trends Forecast 2026-2036
Video Banking Service Market Analysis
Retail customer onboarding is broadening as the fastest-growing end-use vertical for video banking deployments. Finastra leverages its core banking integration depth to anchor enterprise-grade video teller networks across North American credit unions. Backbase competes through its engagement banking platform, which sustains white-label video consultation tools for tier-two lenders. Temenos specializes in cloud-native architecture that extends real-time video advisory into wealth management workflows.
Video banking service denotes a secure, interactive audiovisual channel connecting financial institution representatives with remote clients through encrypted real-time streaming, typically operating at sub-200-millisecond latency to preserve conversational fidelity and meet financial-grade security protocols. The technology serves to replicate branch-based relationship banking while reducing physical infrastructure overhead and expanding geographic service coverage. Cloud-based deployment models are capturing the fastest expansion as banks abandon capital-intensive on-premise video infrastructure, while WebRTC protocols dominate technical implementations due to browser-native accessibility that eliminates client-side software friction. Financial advisory and loan consultation service types concentrate margin pools, given higher per-session value capture and regulatory documentation requirements that justify premium pricing.
US banks navigate FFIEC authentication guidelines and state-level biometric consent laws that shape identity verification workflows within video channels. European deployments face EBA strong customer authentication mandates under PSD2, plus GDPR constraints on session recording retention that increase compliance engineering costs. Stakeholders must monitor how divergent cross-border data localization rules affect multi-jurisdiction video banking architecture decisions.
Market Dynamics
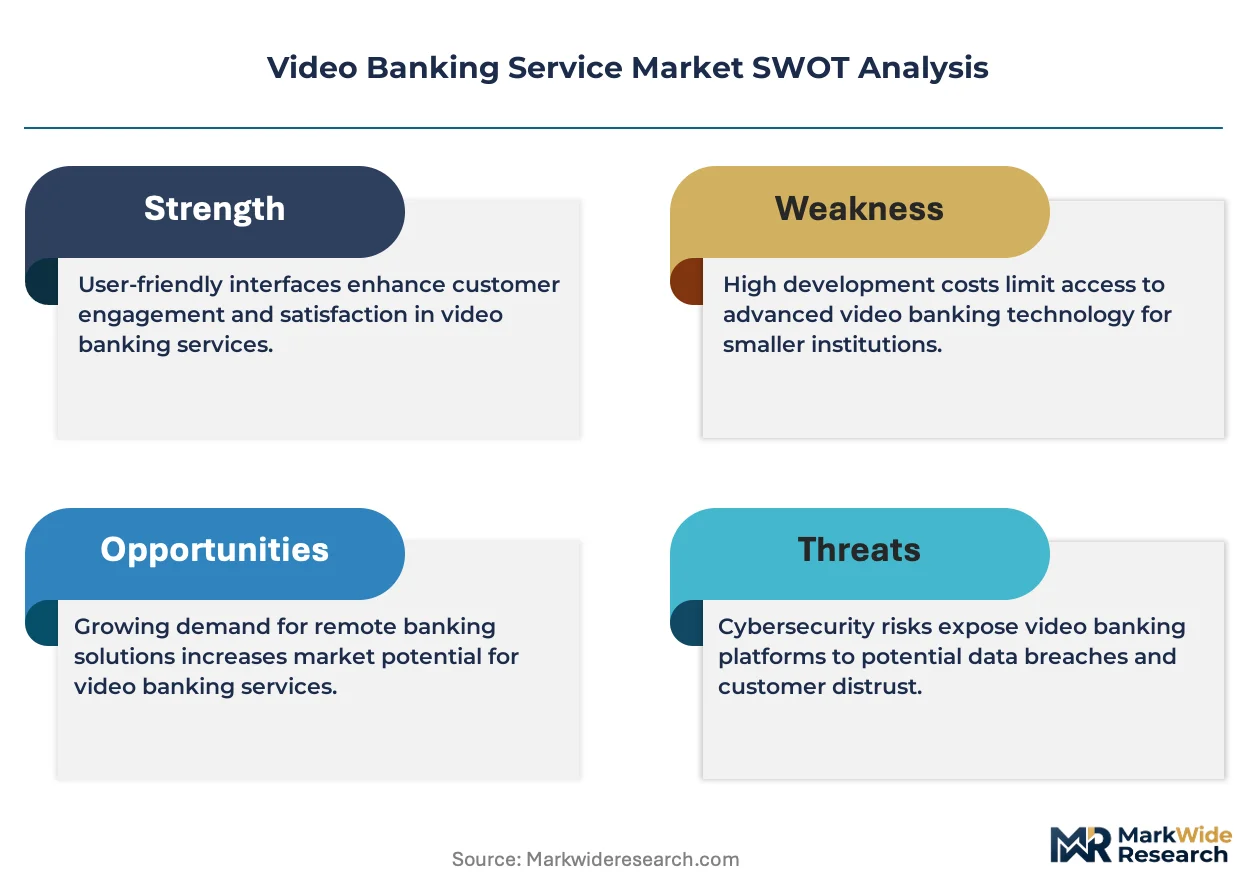
Cloud migration is collapsing capital barriers for regional banks while WebRTC protocols eliminate client software friction, fundamentally restructuring how financial institutions deploy video infrastructure at scale.
Growth Catalysts
- PSD2 Strong Customer Authentication:European banks must verify identity through multi-factor channels, driving compliant video onboarding solutions that satisfy EBA mandates while reducing branch dependency.
- Credit Union Branch Consolidation:North American cooperative banks are closing physical locations and redirecting capital toward virtual teller networks that preserve member relationships across dispersed geographies.
- WebRTC Browser-Native Streaming:Elimination of plugin downloads and dedicated apps removes adoption friction, enabling instant video sessions that match consumer expectations for seamless digital service.
Market Restraints
- GDPR Session Retention Limits:European data portability rules impose strict constraints on recorded video storage duration, forcing expensive compliance engineering for audit and dispute resolution workflows.
- Biometric Consent Fragmentation:US state-level laws governing facial recognition and voiceprint collection create jurisdictional complexity that multiplies legal review costs for interstate video banking deployments.
- Latency Infrastructure Requirements:Sub-200-millisecond streaming demands edge computing investments and premium bandwidth contracts that strain IT budgets at smaller institutions.
Strategic Opportunities
- Wealth Management Advisory Convergence:High-net-worth clients accept premium pricing for encrypted video consultations that document fiduciary recommendations and accelerate complex product approvals.
- India Digital Banking Push:RBI financial inclusion mandates and UPI infrastructure maturity create fertile ground for vernacular-language video banking targeting underbanked rural populations.
- Open Banking API Orchestration:PSD2-mandated data sharing enables contextual video sessions where advisors access real-time account aggregation to personalize recommendations during live conversations.
Industry Challenges
- Legacy Core Integration Complexity:Decades-old banking systems require expensive middleware development to synchronize video session data with customer records, transaction histories, and compliance audit trails.
- Specialized Talent Scarcity:Financial institutions compete for engineers possessing dual fluency in real-time streaming protocols and financial-grade security architecture, driving compensation inflation.
- Cross-Border Data Localization Conflicts:Divergent national requirements for where video session data must reside create architectural paralysis for multinational banks seeking unified platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Banking Service Market |
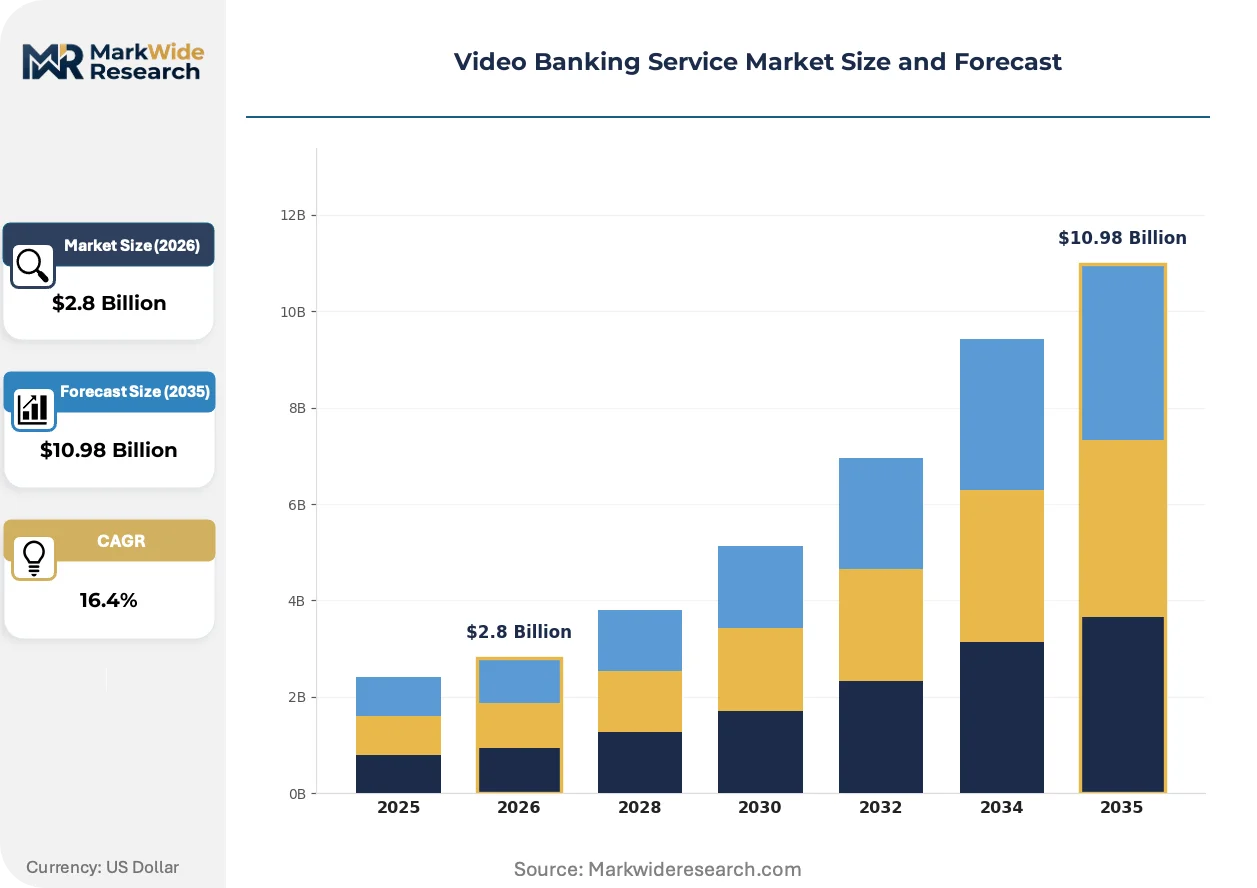
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Opening, Loan Consultation, Customer Support, Financial Advisory Client Type: Retail Customers, Small Enterprises, Corporates, High-Net-Worth Individuals Technology: WebRTC, SIP, Cloud-Based, Video Conferencing Deployment Model: On-Premise, Cloud, Hybrid, Mobile |
| Companies Covered | Finastra, SDK.finance, Backbase, nCino, Fiserv, Temenos, Thought Machine, Velmie, Mambu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Banking Service Market Emerging Trajectories
Real-time streaming architectures are converging with identity verification stacks to create seamless video banking experiences that eliminate friction between authentication and advisory service delivery.
AI-powered conversation analysis is automating compliance documentation by transcribing video sessions, flagging regulatory disclosures, and populating CRM records without manual advisor intervention. Regional banks in the United States are piloting these tools to reduce post-session administrative burden. The technology is automating workflows that previously required dedicated back-office staff, compressing operational costs for mid-tier institutions.
GDPR Article 17 right-to-erasure mandates are forcing European banks to engineer selective video redaction capabilities that remove individual data subjects from recorded sessions while preserving audit evidence. This regulatory pressure is reshaping vendor selection criteria toward platforms with granular data governance features. Wealth management divisions face the steepest compliance engineering costs given longer session retention requirements for fiduciary documentation.
Subscription-based advisory pricing is displacing transaction-fee models as credit unions and community banks seek predictable revenue streams from video-delivered financial planning. Members in rural United States markets demonstrate higher willingness-to-pay for unlimited video access than urban counterparts with branch proximity. The shift is compressing traditional commission structures while expanding addressable market for institutions previously constrained by physical footprint.
Video Banking Service Market Segmentation
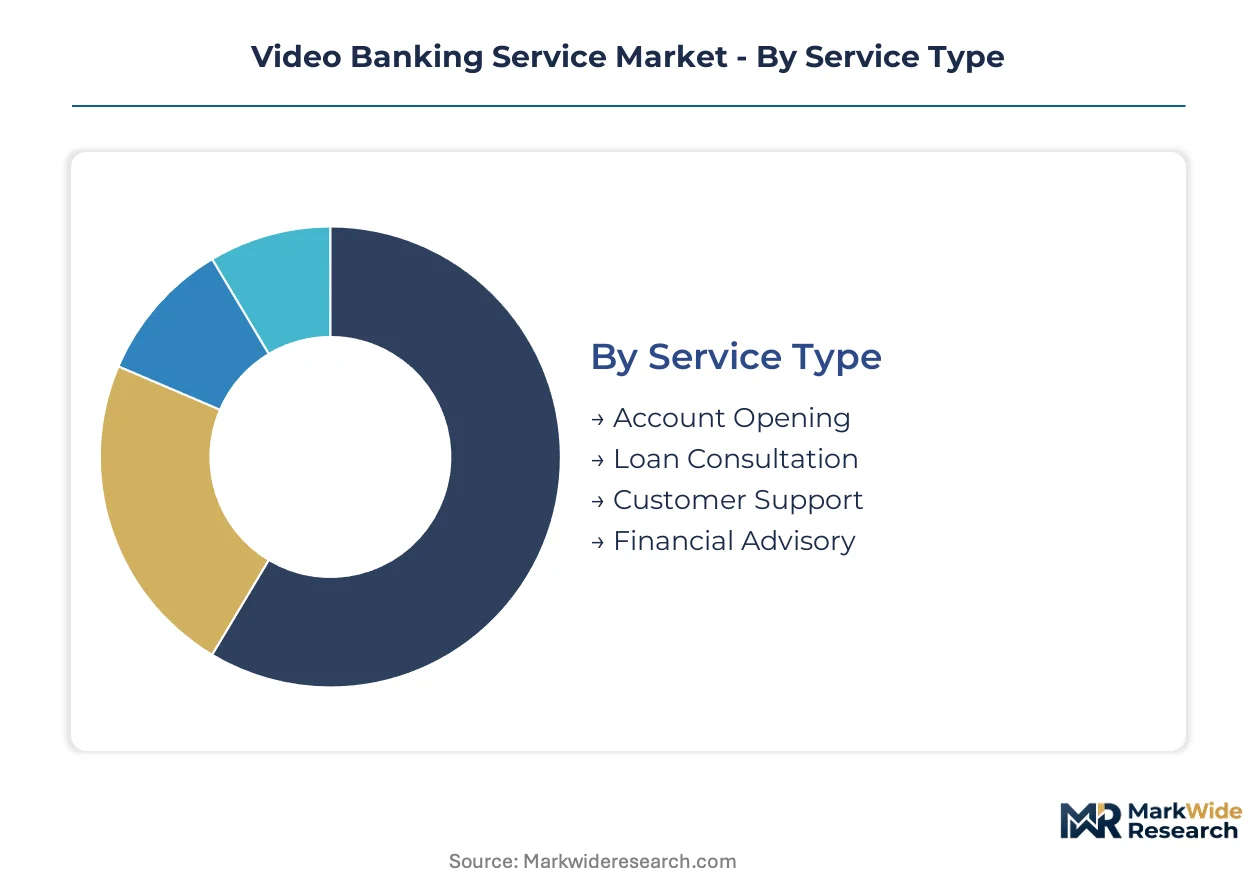
Video banking service providers differentiate through service specialization, client tier targeting, and infrastructure architecture choices. Each segmentation dimension carries distinct margin profiles and technical requirements that reshape competitive positioning.
Service Type:
Customization intensity varies sharply across service types, from standardized identity verification workflows to bespoke wealth advisory protocols.
- Financial Advisory:Fiduciary-grade video consultations document investment recommendations through encrypted session recording. Wealth management divisions in Switzerland and Singapore deploy these services for high-net-worth clients requiring compliant documentation trails.
- Loan Consultation:Real-time credit assessment combines video identity proofing with document upload portals. Regional banks across the United States concentrate procurement here to replace in-person mortgage origination.
- Account Opening:KYC-compliant video onboarding satisfies PSD2 strong customer authentication mandates.
- Customer Support:Transaction dispute resolution and general inquiry handling through browser-native channels.
Leading the category by volume: Customer Support. Growing fastest: Financial Advisory.
Client Type:
Revenue per session climbs across the sophistication spectrum from mass-market retail to institutional wealth management.
- High-Net-Worth Individuals:Dedicated video relationship managers deliver portfolio reviews and alternative investment access. Private banks in London and Geneva capture premium pricing through encrypted consultation suites with multi-jurisdiction compliance.
- Corporates:Treasury management and trade finance advisory through scheduled video sessions with assigned specialists.
- Small Enterprises:Business banking onboarding and working capital consultations.
- Retail Customers:Mass-market account services and basic product inquiries.
Highest margin concentration: High-Net-Worth Individuals. Broadest deployment base: Retail Customers.
Technology:
Protocol selection determines client friction, infrastructure cost, and integration complexity for financial institutions.
- WebRTC:Browser-native real-time streaming eliminates plugin dependencies and dedicated app downloads. Credit unions across the United States prioritize WebRTC implementations to minimize member adoption barriers.
- Cloud-Based:Elastic compute resources scale video infrastructure without capital expenditure commitment.
- SIP:Session Initiation Protocol trunking integrates with legacy telephony infrastructure.
- Video Conferencing:Third-party platform licensing for basic consultation needs.
Dominant protocol by deployment count: WebRTC. Steepest adoption curve: Cloud-Based.
Deployment Model:
Capital efficiency versus control intensity shapes how institutions architect video banking infrastructure.
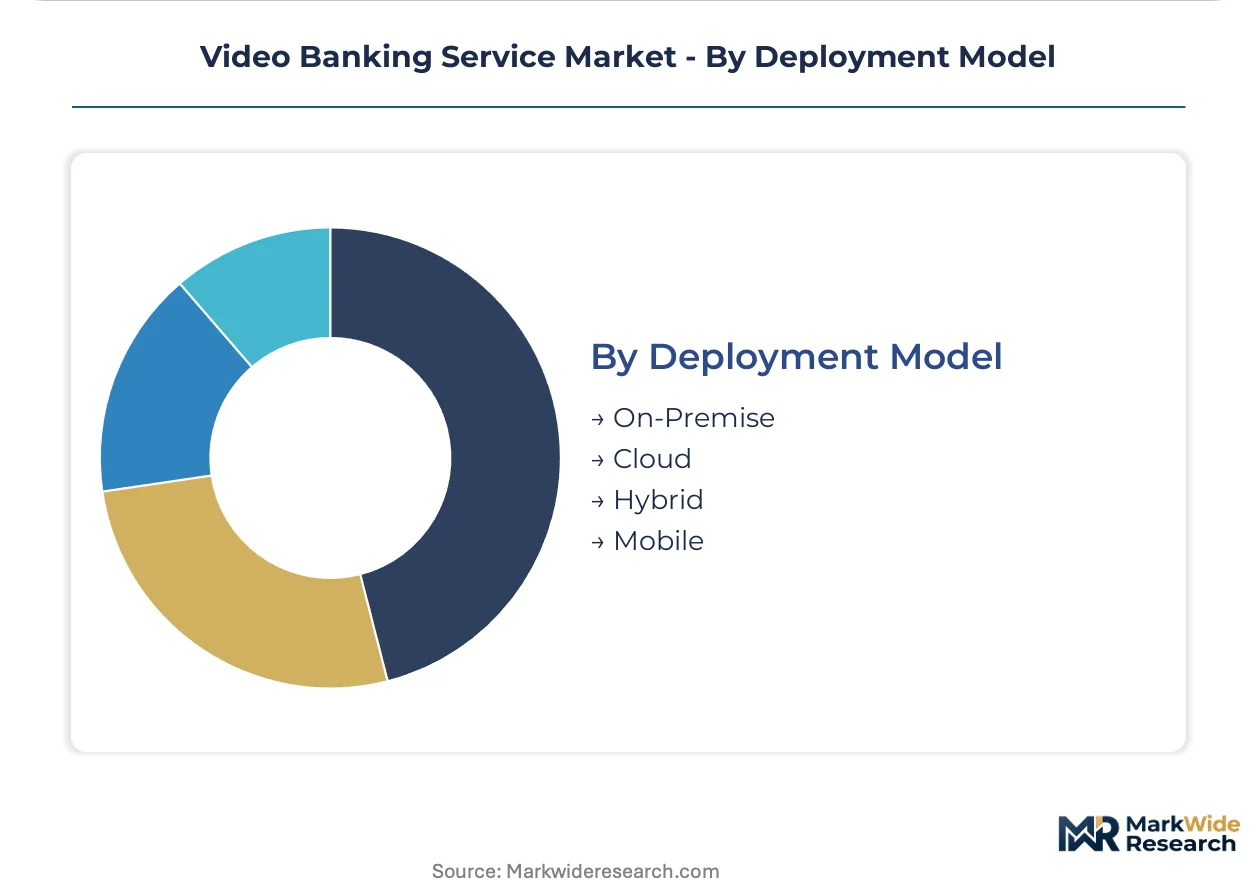
- Cloud:Subscription-based consumption eliminates data center investment and accelerates geographic expansion. Community banks in the United States redirect branch closure savings toward cloud video teller networks.
- Hybrid:Sensitive authentication workloads remain on-premise while advisory sessions leverage cloud elasticity.
- On-Premise:Dedicated infrastructure for institutions with strict data localization requirements.
- Mobile:Native application deployment for smartphone-first service delivery.
Fastest-growing architecture: Cloud. Highest control retention: On-Premise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the United States and India's digital infrastructure corridors are concentrating video banking deployment capital, while European regulatory harmonization under PSD2 and GDPR reshapes cross-border service architecture.
United States
Regional banks in the Southeast and Midwest are consolidating branches and redirecting capital toward cloud-based video teller networks. State-level biometric consent laws in Illinois and Texas create jurisdictional complexity for facial recognition workflows. Atlanta and Charlotte anchor the largest credit union video banking deployments, with Georgia-based institutions pioneering subscription advisory pricing models.
Germany
Sparkassen and cooperative banks are deploying hybrid cloud video infrastructure to satisfy data localization requirements under national banking supervision. EBA strong customer authentication mandates under PSD2 drive compliant onboarding solutions. Frankfurt's fintech cluster hosts multiple vendors engineering selective video redaction capabilities for GDPR Article 17 compliance.
India
RBI financial inclusion mandates and UPI infrastructure maturity are accelerating vernacular-language video banking for rural underbanked populations. The central bank's digital payment guidelines shape identity verification protocols. Mumbai and Bangalore concentrate vendor development centers, with Karnataka-based institutions piloting AI-powered conversation analysis for compliance documentation.
United Kingdom
Challenger banks and building societies leverage open banking APIs to contextualize video advisory sessions with real-time account aggregation. FCA consumer duty requirements elevate documentation standards for investment recommendations. London's wealth management corridors in the City and Canary Wharf deploy encrypted consultation suites for high-net-worth fiduciary services.
Singapore
MAS digital banking licenses and sandbox frameworks enable neobanks to launch video-first service models without legacy infrastructure burden. Cross-border data transfer agreements with ASEAN partners facilitate regional service expansion. The Marina Bay financial district concentrates private banking video advisory deployments targeting Southeast Asian wealth.
Video Banking Service Market Vendor Landscape
Top-tier vendors anchor enterprise-grade core banking integration, while mid-tier specialists compete through white-label engagement platforms and cloud-native architectures. The vendor base stratifies across three tiers: full-stack core providers, engagement banking specialists, and niche streaming infrastructure vendors. Two strategic archetypes dominate: core-integrated players leveraging existing bank relationships, and API-first challengers enabling rapid deployment without legacy migration. Competitive moves concentrate on open banking API orchestration and selective geographic expansion into regulatory-aligned markets.
Among core-integrated providers, Finastra and Temenos occupy positions exemplifying enterprise-grade video teller networks and cloud-native wealth management workflows respectively. Backbase represents the engagement banking specialist archetype, anchoring white-label video consultation tools for tier-two lenders seeking rapid deployment without core replacement. These three vendors illustrate the competitive tension between deep integration and deployment velocity that shapes procurement decisions across North American and European institutions.
| Leading Market Players |
|---|
| Finastra |
| SDK.finance |
| Backbase |
| nCino |
| Fiserv |
| Temenos |
| Thought Machine |
| Velmie |
| Mambu |
| Others |
Supply Flow & Price Mechanics
WebRTC browser-native streaming eliminates plugin dependencies and dedicated app downloads, collapsing software distribution costs while concentrating vendor development talent in Bangalore, Berlin, and San Francisco. Cloud-based deployment models simultaneously reduce capital barriers for regional banks and intensify margin competition among infrastructure providers racing to capture subscription revenue.
Pricing Analysis
Short lead-time deployment commands premium pricing as regional banks seek rapid branch replacement, while extended implementation timelines trigger standard-tier discounts. SaaS-tiered subscription models dominate, with price differentiation anchored in core banking integration depth and regulatory certification tier. Pricing pressure stems from open-source WebRTC commoditization of basic streaming infrastructure. Community banks exhibit highest price sensitivity, while private wealth divisions demonstrate lowest sensitivity given fiduciary documentation requirements.
Supply Chain Analysis
Engineering talent scarcity in India, Poland, and the United States constrains vendor scaling velocity and inflates compensation costs for dual-skilled streaming-security specialists. Cloud compute resources draw from AWS, Azure, and Google Cloud data center networks, while specialized video encoding hardware rests on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates in legacy core banking middleware providers. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architecture is displacing on-premise video infrastructure, creating a technology-transition window where deployment velocity determines competitive survival.
For Market Incumbents: Extend core banking integration depth to anchor enterprise-grade video teller networks against API-first challengers. Defend position by accelerating selective geographic expansion into RBI-regulated Indian markets before local vendors consolidate. Certification investment in GDPR Article 17 redaction capabilities represents a critical lever for European retention. For New Entrants and Emerging Players: Launch via white-label engagement platforms targeting tier-two credit unions seeking rapid deployment without core replacement. Underpenetrated rural United States markets offer the most penetrable geography, with subscription advisory pricing models enabling predictable revenue capture. Go-to-market angle: vernacular-language localization for RBI financial inclusion mandates. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native specialists given PSD2 open banking API orchestration catalyst. Long-term viability favors vendors with dual fluency in real-time streaming protocols and financial-grade security architecture. Acquisition target archetype: niche streaming infrastructure vendors with edge computing deployments. Signal to watch: cross-border data localization rule harmonization as inflection indicator for multinational platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking Integration | Finastra leverages existing credit union relationships to anchor enterprise video teller networks. |
| Cloud-Native Architecture | Temenos extends real-time video advisory into wealth management workflows through elastic infrastructure. |
| White-Label Platform Launch | Backbase enables tier-two lenders to deploy video consultation tools without core replacement burden. |
| Regulatory Compliance Engineering | GDPR Article 17 redaction capabilities reshape vendor selection criteria toward granular data governance. |
| Vernacular Localization | RBI financial inclusion mandates create entry opportunity for vernacular-language video banking in rural India. |
Methodological Framework
SEC filings, EBA regulatory guidance documents, and RBI circulars formed the secondary backbone, supplemented by trade association disclosures from credit union networks and core banking vendor annual reports. Primary interviews with CTOs at regional banks, digital channel executives at credit unions, integration specialists at systems integrators, and compliance officers at wealth management divisions validated quantitative assumptions. Bottom-up and top-down triangulation reconciled vendor-reported deployment counts with institution-level procurement patterns.
Bottom-up modeling aggregated individual bank deployment decisions across service type, client tier, and technology protocol dimensions, while top-down analysis tracked aggregate cloud infrastructure spending and regulatory compliance cost trends. Segmentation dimensions modeled included deployment model, institution size tier, integration complexity level, and regional regulatory framework cluster. CAGRs derived from fitted growth curves incorporating WebRTC adoption velocity, branch consolidation rates, and open banking API maturity indicators.
PSD2 regulatory reinterpretation, cross-border data localization rule divergence, and cloud infrastructure cost volatility are the dominant revision risks to projection assumptions. Material deviation in any trigger warrants strategic pause and re-evaluation of vendor positioning and geographic expansion sequencing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
In Vitro Fertilization Banking Services Market
Banking
Retail Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Germany Banking As a Service Market
Banking
UK Banking as a Service Market
Banking
US Data Analytics in Banking Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Global Chatbot for Banking Market
Banking
Banking Software Market
Banking
US Investment Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Brazil Retail Banking Market
Banking
Bank Management Software Market
Banking
Digital LED Retail Banking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Global IoT in Banking and Financial Services Market