
 Silver Mining Market | 2026-2036
Silver Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Mining Market Analysis
The capital-intensity divergence between mid-tier developers and established producers is rotating strategic priorities across the silver mining sector. Coeur Mining leverages its integrated Rochester operation to sustain low-cost heap-leach output in Nevada. Pan American Silver anchors its position through underground bulk-tonnage capacity at La Colorada in Mexico. Hecla Mining Company competes via deep vertical shafts at the Lucky Friday complex in Idaho's Silver Valley.
Silver mining encompasses the extraction of elemental silver and its compounds from epithermal veins, porphyry deposits, and polymetallic sulfide ores, typically yielding grades between 30 and 500 grams per metric ton depending on deposit type and depth. The metal serves indispensable roles in electrical conductivity applications, antimicrobial coatings, and photovoltaic metallization pastes where substitution remains technically constrained. Underground mining dominates margin pools in high-grade Mexican districts, while open-pit methods sustain volume leadership at lower-grade byproduct operations tied to copper and zinc circuits. Silver concentrates command premium offtake terms when arsenic and mercury impurities stay below smelter thresholds, positioning refining flexibility as a decisive cost variable.
EPA enforces cyanide heap-leach monitoring under CERCLA provisions, while Mexico's SEMARNAT regulates tailings dam integrity across Zacatecas operations, and ISO 14001 certification shapes access to European electronics supply chains. These frameworks elevate closure bonding requirements and water recycling mandates, squeezing marginal project economics. Stakeholders must track permitting velocity against concentrate treatment capacity bottlenecks to calibrate development timelines.
Market Dynamics
Photovoltaic metallization paste specifications are tightening purity requirements faster than smelter upgrade cycles, forcing concentrate suppliers to pre-invest in refining capacity or accept price penalties for elevated selenium and tellurium content.
Growth Catalysts
- IRA clean energy tax credits:Domestic content bonuses for U.S.-assembled solar panels are redirecting silver offtake toward compliant North American concentrate streams.
- TOPCon cell architecture:Tunnel oxide passivated contact designs consume 20-30% more silver per watt than PERC predecessors, embedding permanent demand uplift.
- Zacatecas-Durango corridor:Underground vein systems in these Mexican states host the world's highest-grade primary silver reserves, sustaining cost-competitive supply.
Market Restraints
- Cyanide transport restrictions:EPA and Transport Canada permitting delays for sodium cyanide rail shipments are extending heap-leach commissioning timelines by 8-14 months.
- Concentrate smelter concentration:Chinese and Korean smelters process 70% of global silver-bearing concentrates, creating single-geography offtake vulnerability.
- Copper byproduct displacement:Chilean and Peruvian copper operations generate 55-60% of annual silver supply, subordinating output decisions to base metal economics.
Strategic Opportunities
- Indian photovoltaic manufacturing:PLI scheme subsidies for domestic module assembly are creating new silver paste demand outside traditional Chinese supply chains.
- Antimicrobial medical coatings:FDA 510(k) pathway expansion for silver-ion wound dressings is opening pharmaceutical-grade refining contracts.
- EU Battery Regulation traceability:Digital product passport mandates for critical raw materials are favoring vertically integrated miners with blockchain-verified chain-of-custody systems.
Industry Challenges
- Deep-level mining engineering:Lucky Friday-style vertical shaft operations below 2,000 meters require rare geotechnical and ventilation expertise that retirement waves are depleting.
- Tailings dam recertification:Global Industry Standard on Tailings Management compliance is forcing 18-24 month engineering reviews at legacy Mexican and U.S. facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Mining Market |
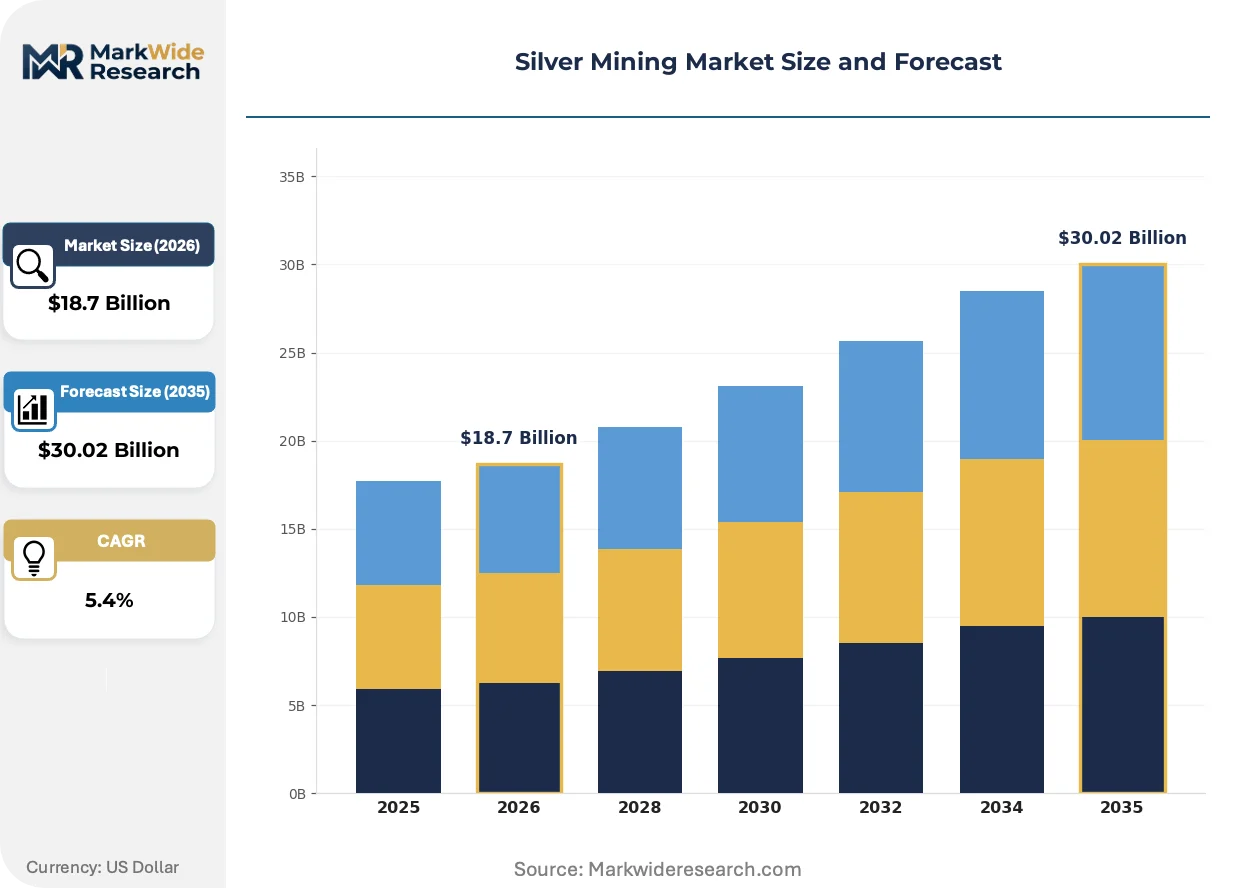
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Silver, Silver Alloys, Silver Concentrates, Silver Oxides Extraction Method: Underground Mining, Open-Pit Mining, Placer Mining, Heap Leaching End User: Jewelry, Electronics, Solar Energy, Investment Process Type: Refining, Milling, Smelting, Electrolysis |
| Companies Covered | Coeur Mining, SilverCrest Metals, Pan American Silver, Wheaton Precious Metals, Americas Gold and Silver, Hecla Mining Company, MAG Silver, Endeavour Silver, First Majestic Silver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Mining Market Emerging Trajectories
Processing technology and offtake contracting are diverging along purity-grade lines, with high-specification solar paste requirements separating from traditional photographic and brazing alloy feedstock markets.
Silver paste formulation is bifurcating between high-temperature fired compositions for conventional silicon cells and low-temperature curable variants for heterojunction and perovskite tandem architectures. DuPont and Heraeus are scaling pilot lines for the latter while maintaining legacy capacity for the former. This technical split is compressing margins for undifferentiated concentrate suppliers unable to certify to both specifications simultaneously.
EPA's revised CERCLA financial assurance rules for heap-leach operations are mandating full-cost closure bonding upfront rather than phased accruals. This policy shift is freezing development timelines for Nevada and Arizona greenfield projects. Junior developers are responding by pivoting toward toll-milling arrangements with existing permitted infrastructure.
Long-term offtake contracting is fragmenting from 5-7 year fixed-volume agreements toward shorter 18-24 month contracts with price-reopener clauses tied to LBMA spot differentials. Chinese solar panel assemblers are driving this behavioral shift to preserve working capital flexibility. The practice is most visible in concentrate purchase agreements originating from Peruvian polymetallic operations.
Silver Mining Market Segmentation
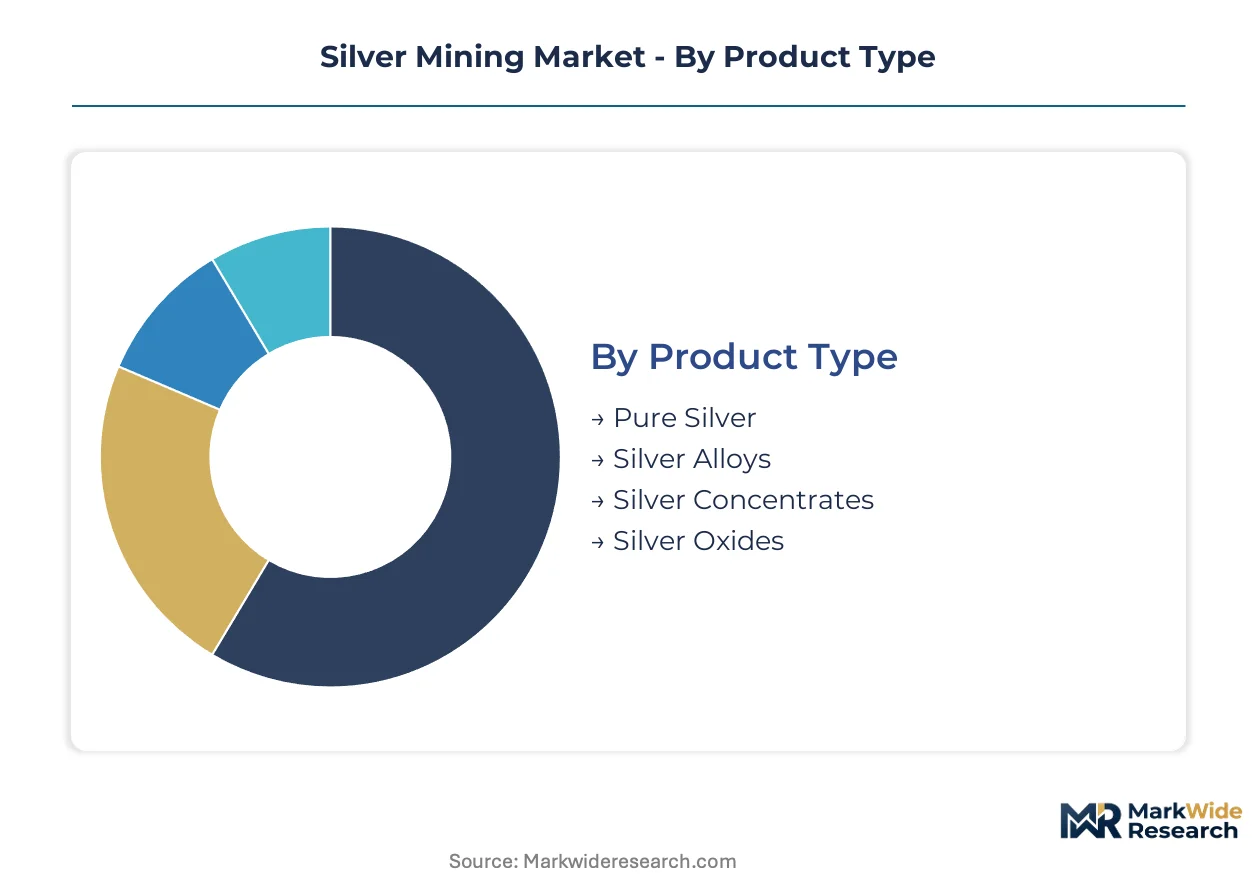
Silver mining segmentation reveals how regulatory frameworks and metallurgical specifications fragment procurement decisions across end-use markets. Product purity grades, extraction techniques, and processing pathways each trigger distinct compliance obligations that reshape supplier economics.
Product Type:
EPA tailings standards and ISO 14001 certification requirements create divergent cost structures across purity grades, with solar paste specifications imposing the tightest impurity ceilings.
- Silver Concentrates:These sulfide-based intermediate products typically assay 30-500 grams per metric ton and require smelter contracts specifying arsenic and mercury thresholds. Mexican Zacatecas-Durango corridor operations dominate supply, with Chinese and Korean smelters processing the majority of global offtake.
- Pure Silver:Refined bullion meeting LBMA Good Delivery standards commands premium pricing in photovoltaic metallization paste applications. IRA domestic content bonuses are redirecting procurement toward North American concentrate streams that feed compliant refining capacity.
- Silver Alloys:Copper-silver and zinc-silver formulations serve brazing and electrical contact applications with less stringent purity requirements than solar feedstock.
- Silver Oxides:Battery-grade and catalyst-grade specifications support antimicrobial medical coating and electronic component manufacturing.
Established volume favors Silver Concentrates; emerging adoption favors Pure Silver.
Extraction Method:
Capital intensity and permitting velocity separate extraction approaches, with underground operations sustaining margin leadership in high-grade districts while open-pit methods anchor byproduct volume.
- Underground Mining:Vertical shaft and decline access methods target epithermal vein systems at depths exceeding 2,000 meters. Lucky Friday-style operations in Idaho's Silver Valley and La Colorada-style bulk tonnage in Mexico concentrate expertise here, though retirement waves deplete geotechnical talent pools.
- Heap Leaching:Cyanide-based solution extraction of oxide ores sustains low-cost output at Nevada operations like Rochester. EPA CERCLA financial assurance rules now mandate full-cost closure bonding upfront, freezing greenfield development timelines and pushing juniors toward toll-milling arrangements.
- Open-Pit Mining:Large-scale excavation of porphyry and polymetallic deposits ties silver output to copper and zinc circuit economics, with Chilean and Peruvian operations generating the majority of annual supply.
- Placer Mining:Alluvial recovery from sedimentary deposits remains marginal to global supply, concentrated in legacy districts with depleted reserves.
Margin concentration sits with Underground Mining; regulatory headwinds burden Heap Leaching.
End User:
Application-specific purity requirements and contracting structures fragment demand, with solar energy procurement driving the steepest expansion trajectory while investment demand responds to monetary policy cycles.
- Solar Energy:TOPCon cell architecture consumes 20-30% more silver per watt than PERC predecessors, embedding permanent demand uplift. Indian PLI scheme subsidies and IRA clean energy tax credits are diversifying procurement geography beyond traditional Chinese supply chains.
- Electronics:Conductive adhesives, printed circuit boards, and switch contacts require high-purity feedstock with tight selenium and tellurium limits. EU Battery Regulation traceability mandates favor vertically integrated miners with blockchain-verified chain-of-custody systems.
- Jewelry:Sterling silver and decorative alloy fabrication operates on longer-term contracting cycles with less volatility than industrial offtake.
- Investment:Bullion coin and bar fabrication responds to interest rate environments and currency hedging demand, with LBMA spot differentials driving price-reopener clauses in concentrate purchase agreements.
Technology upgrade cycles favor Solar Energy; macro sensitivity defines Investment.
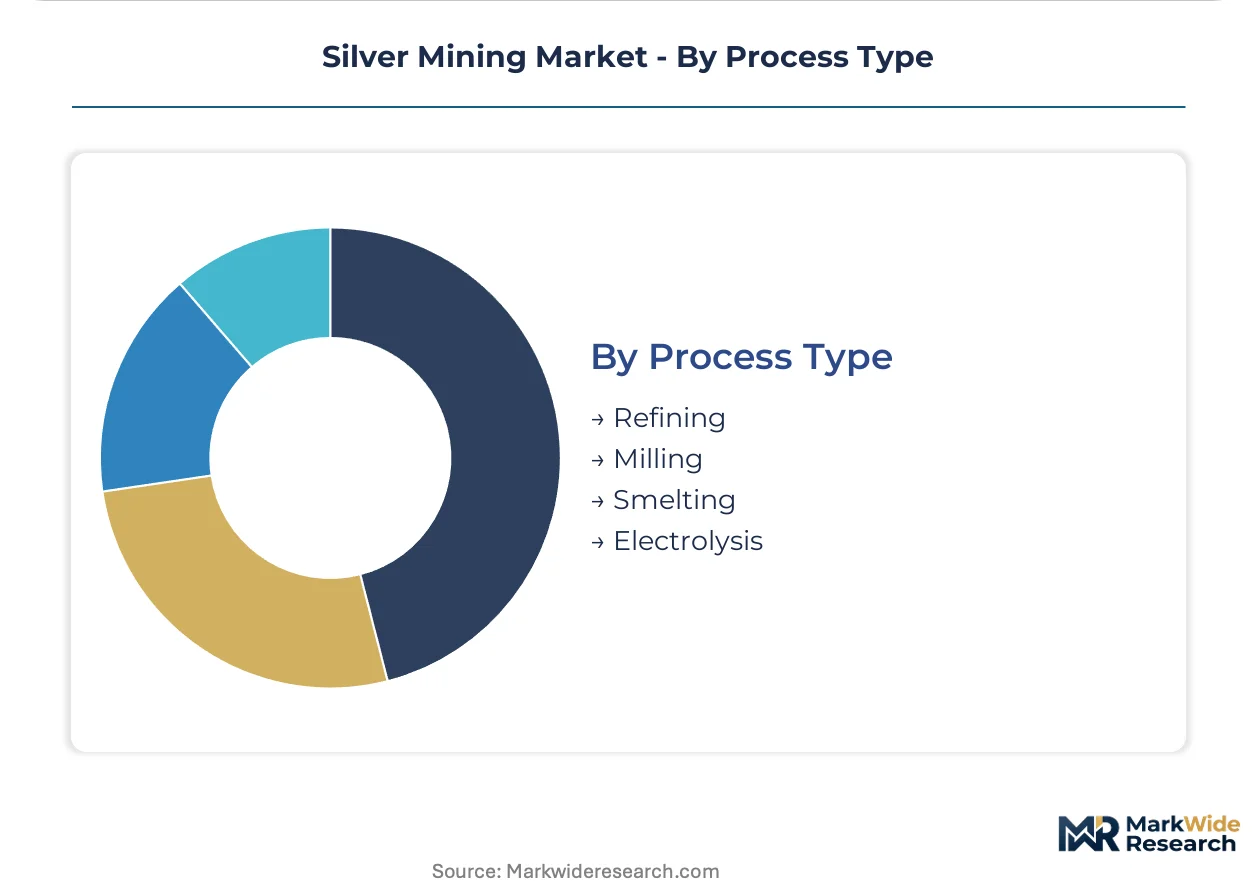
Process Type:
Downstream configuration determines access to premium offtake markets, with refining flexibility separating solar-grade from industrial-grade suppliers.
- Smelting:Pyrometallurgical concentration of silver-bearing concentrates into doré bars requires energy-intensive furnace operations. Chinese and Korean smelter concentration creates single-geography offtake vulnerability that concentrate suppliers must navigate through diversified contracting.
- Refining:Electrolytic and chemical purification to 99.99% purity enables photovoltaic paste certification. DuPont and Heraeus pilot lines for low-temperature curable formulations are compressing margins for undifferentiated suppliers unable to certify to both high-temperature and low-temperature specifications.
- Milling:Comminution and flotation concentration prepares feedstock for smelter delivery, with grind size and recovery rates determining concentrate grade.
- Electrolysis:Electrowinning of silver from solution supports specialized high-purity applications with exacting trace metal limits.
Capacity bottlenecks concentrate in Smelting; technology differentiation rewards Refining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photovoltaic manufacturers in China exhibit the least price elasticity for high-purity silver feedstock, while jewelry fabricators in India demonstrate acute sensitivity to London spot differentials. This demand-elasticity contrast shapes regional procurement strategies and concentrate flow patterns across the analysis window.
Mexico
Underground bulk-tonnage operations in Zacatecas and Durango sustain the world's highest-grade primary silver reserves. SEMARNAT tailings dam integrity regulations are extending recertification timelines for legacy facilities by 18-24 months. The Zacatecas-Durango corridor concentrates expertise in deep-level vein extraction, though retirement waves deplete geotechnical talent pools.
United States
IRA clean energy tax credits are redirecting silver offtake toward domestic content-compliant concentrate streams for solar panel assembly. EPA CERCLA financial assurance rules now mandate full-cost closure bonding upfront for Nevada heap-leach operations. The Rochester complex in Nevada anchors low-cost oxide ore production, while Lucky Friday-style vertical shafts in Idaho's Silver Valley target deep epithermal systems.
Canada
Transport Canada permitting delays for sodium cyanide rail shipments are extending heap-leach commissioning timelines by 8-14 months. Federal environmental assessment requirements under the Impact Assessment Act are elevating closure bonding requirements for new projects. British Columbia and Ontario host polymetallic operations where silver output ties to copper and zinc circuit economics.
Peru
Copper porphyry operations generate 55-60% of annual silver supply as byproduct output subordinated to base metal price cycles. The Ministry of Energy and Mines regulates concentrate export licensing with escalating community consultation mandates. The Andean copper belt concentrates polymetallic output where smelter contracts specify arsenic and mercury thresholds.
Australia
ISO 14001 certification requirements are shaping access to European electronics supply chains for concentrate exporters. The Western Australian Department of Mines, Industry Regulation and Safety enforces tailings storage facility design standards aligned with the Global Industry Standard on Tailings Management. Kalgoorlie and the Eastern Goldfields host legacy operations where placer deposits face reserve depletion pressures.
Silver Mining Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the silver mining sector. The market structure consolidates around vertically integrated majors with captive refining capacity and mid-tier developers dependent on toll-milling arrangements. Three archetypes dominate: established producers with underground bulk-tonnage expertise, heap-leach operators sustaining low-cost oxide output, and polymetallic byproduct generators tied to copper economics. Competitive moves center on permitting velocity acceleration and concentrate treatment capacity securing through strategic offtake partnerships.
Among North American established producers, Coeur Mining, Pan American Silver, and Hecla Mining Company occupy positions across the technology-cost spectrum. Coeur Mining exemplifies the integrated heap-leach archetype with Nevada-based oxide operations. Pan American Silver anchors the underground bulk-tonnage tier through Mexican vein system expertise. Hecla Mining Company represents deep vertical shaft capability targeting Idaho's Silver Valley epithermal deposits.
| Leading Market Players |
|---|
| Coeur Mining |
| SilverCrest Metals |
| Pan American Silver |
| Wheaton Precious Metals |
| Americas Gold and Silver |
| Hecla Mining Company |
| MAG Silver |
| Endeavour Silver |
| First Majestic Silver |
| Others |
Supply Flow & Price Mechanics
Spot-to-contract lead times stretching 45-90 days for Mexican concentrate shipments concentrate pricing power with Chinese and Korean smelters while forcing North American producers to absorb logistics premiums or forfeit volume. This inventory compression cycle binds concentrate grade certification to LBMA spot differentials, embedding quality premiums into supplier selection criteria.
Pricing Analysis
After-sales revenue from long-term offtake renegotiations and concentrate treatment charges drives lifetime value for established producers. Three-tier pricing structure across solar-grade, industrial-grade, and byproduct concentrate levels separates LBMA-certified refiners from undifferentiated suppliers. Pricing pressure stems from TOPCon paste specifications tightening faster than smelter upgrade cycles, compressing margins for non-compliant concentrate streams. Photovoltaic manufacturers exhibit the least price sensitivity for high-purity feedstock, while jewelry fabricators in India demonstrate acute responsiveness to London spot movements.
Supply Chain Analysis
Inbound logistics costs from Zacatecas-Durango rail corridors to Pacific port terminals concentrate supply chain vulnerability on container availability and customs clearance velocity. Geographic supply concentrates in Mexico, Peru, and Chile, with Chinese and Korean smelters processing the majority of global silver-bearing concentrates. Raw material dependencies span sodium cyanide for heap-leach operations, diesel for underground haulage, and grinding media for milling circuits. Single-geography offtake vulnerability at Chinese smelters creates structural risk for concentrate suppliers lacking diversified contracting. Distribution runs through long-term offtake agreements with price-reopener clauses, toll-milling arrangements for junior developers, and spot market sales for surplus concentrate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep-level mining engineering expertise is depleting faster than training pipelines can replenish, constraining development timelines for Idaho-style vertical shaft operations and Mexican bulk-tonnage projects. This capability scarcity elevates permitting velocity and talent retention as decisive competitive variables.
For Market Incumbents: Compound geotechnical talent pools through apprenticeship partnerships with mining engineering programs at Idaho and Zacatecas technical institutes. Secure toll-milling capacity commitments for oxide ore streams before EPA CERCLA bonding rules freeze Nevada greenfield timelines. Vertical integration into refining capacity buffers against Chinese smelter concentration risk while capturing solar-grade premiums. For New Entrants and Emerging Players: Differentiate on blockchain-verified chain-of-custody systems that satisfy EU Battery Regulation traceability mandates for electronics supply chains. Target Indian photovoltaic manufacturing clusters where PLI scheme subsidies are creating silver paste demand outside traditional Chinese procurement channels. Pursue toll-milling partnerships with permitted Nevada heap-leach infrastructure rather than greenfield development. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified majors spinning non-core silver assets where copper byproduct economics have subordinated management attention. Long-term viability hinges on exposure to solar energy procurement growth and refining flexibility for dual high-temperature and low-temperature paste certification. Watch for inflection signals in IRA domestic content bonus uptake rates for U.S.-assembled solar panels redirecting concentrate flows toward North American supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Refining Capacity Expansion | Captures solar-grade premiums as TOPCon specifications tighten faster than smelter upgrades. |
| Toll-Milling Partnership | Bypasses EPA CERCLA upfront bonding requirements freezing Nevada greenfield development timelines. |
| Blockchain Traceability Implementation | Unlocks EU Battery Regulation-compliant electronics supply chain access for concentrate exporters. |
| Geotechnical Talent Pipeline Investment | Addresses retirement-wave depletion threatening Lucky Friday-style deep vertical shaft operations. |
| Indian Market Development | Diversifies offtake beyond Chinese solar panel assemblers through PLI scheme procurement channels. |
Methodological Framework
Initial hypotheses were tested against primary input from mine operations managers, concentrate procurement officers at photovoltaic paste manufacturers, smelter contract negotiators, and tailings engineering consultants, then refined against secondary validation from SEC 10-K filings, Mexican Ministry of Energy and Mines production statistics, LBMA trade flow reports, and EPA enforcement and compliance databases. Bottom-up concentrate supply modeling and top-down end-use demand estimation were triangulated to constrain forecast variance.
Variance decomposition across extraction method, product purity grade, and end-use application segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume projections calibrated to solar capacity installation forecasts and silver loadings per watt across cell architecture transitions. Industry-specific inputs included TOPCon adoption curves, IRA domestic content bonus eligibility rates, and Chinese smelter capacity utilization assumptions.
Decision-makers should treat outputs as directional under base assumptions of continued photovoltaic silver intensity and stable Mexican regulatory enforcement; material deviation in cell technology substitution or SEMARNAT tailings recertification timelines would warrant model refresh. Recalibration cycles align with material shifts in solar paste specification standards and concentrate smelter contracting patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zellerite Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Chromite Market
Metals & Minerals
Manganese Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Recycled Aluminum Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Coalingite Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Bauxite Market