
 Motorcycle Anti-Lock Braking System Market | 2026-2036
Motorcycle Anti-Lock Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Anti-Lock Braking System Market Foresight
The EU Green Deal is rebalancing motorcycle safety procurement across European OEM supply chains. Robert Bosch GmbH leverages its integrated systems portfolio to anchor factory-fit contracts with premium manufacturers. Continental AG competes through hydraulic unit specialization across mid-volume motorcycle platforms. Brembo S.p.A differentiates via performance-oriented ABS calibration for sport and racing segments.
A motorcycle anti-lock braking system modulates hydraulic pressure to individual wheel calipers through wheel-speed sensors and electronic control units, preventing wheel lock during deceleration. The system operates on a threshold-based or slip-ratio algorithm with typical activation cycles below 15 milliseconds, primarily serving to preserve rider stability and reduce stopping distances on variable road surfaces. Integrated systems dominate value capture due to bundled sensor-controller architectures, while aftermarket solutions represent the fastest-growing installation channel as retrofit mandates expand across emerging markets. Combined Braking Systems technology leads unit volume where cost-sensitive OEMs prioritize single-actuation simplicity over full ABS complexity.
The European Commission's F-Gas Regulation and CE marking requirements shape ABS hydraulic fluid specifications and electromagnetic compatibility testing for market access. India's BIS certification and Central Motor Vehicles Rules mandate ABS fitment on motorcycles above 125cc engine displacement, directly compelling OEM sourcing volumes. NHTSA's Federal Motor Vehicle Safety Standards govern ABS performance thresholds in the United States. Stakeholders must monitor divergent homologation timelines across these jurisdictions to align product development cycles with compliance windows.
Market Dynamics
Mandatory ABS fitment regulations across Indonesia, India, and Brazil are compressing OEM sourcing timelines and forcing hydraulic unit suppliers to triple certification throughput. This regulatory wave is restructuring supplier-buyer power dynamics faster than production capacity can adapt.
Growth Catalysts
- Commercial delivery fleet mandates:Indonesia's tightening two-wheeler safety rules for logistics operators are accelerating factory-fit ABS procurement. Last-mile operators now face insurance penalties for non-compliant vehicles.
- Sensor-controller integration:Bundled IMU-ABS architectures are reducing per-unit wiring complexity and calibration labor. Integrated systems now dominate value capture in premium motorcycle segments.
- Central Motor Vehicles Rules:India's displacement-based mandate above 125cc is compelling domestic OEMs to redesign braking architectures. Compliance deadlines have compressed supplier qualification windows.
Market Restraints
- Semiconductor input volatility:Wheel-speed sensor ASICs face allocation constraints from automotive MCU foundry competition. Lead times for ABS-specific microcontrollers now exceed 26 weeks.
- Hydraulic unit supply concentration:Precision solenoid valve manufacturing clusters in Germany and Japan create geographic chokepoints. Single-source dependencies for high-pressure sealing technology persist.
- Aftermarket retrofit friction:India's BIS certification requirements for non-factory installations create documentation burdens. Independent mechanics lack diagnostic tool access for ECU parameter matching.
Strategic Opportunities
- Combined Braking Systems convergence:CBS-ABS hybrid architectures are penetrating cost-sensitive OEM portfolios in Vietnam and Thailand. Single-actuation simplicity preserves margin while meeting baseline safety mandates.
- Rural fleet retrofit channels:Brazil's commercial motorcycle operators represent an underpenetrated aftermarket segment. Mobile installation units can bypass dealership infrastructure gaps.
- F-Gas Regulation alignment:EU hydraulic fluid specifications are creating export-ready product lines for Southeast Asian OEMs serving European markets. CE marking pre-certification opens premium sourcing contracts.
Industry Challenges
- Calibration engineer scarcity:Slip-ratio algorithm tuning requires specialized brake dynamics expertise. OEM technical centers in India and Indonesia compete for finite talent pools.
- Homologation timeline compression:Divergent NHTSA, EU, and BIS test protocols force parallel validation tracks. ABS suppliers must maintain multiple electromagnetic compatibility test benches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Anti-Lock Braking System Market |
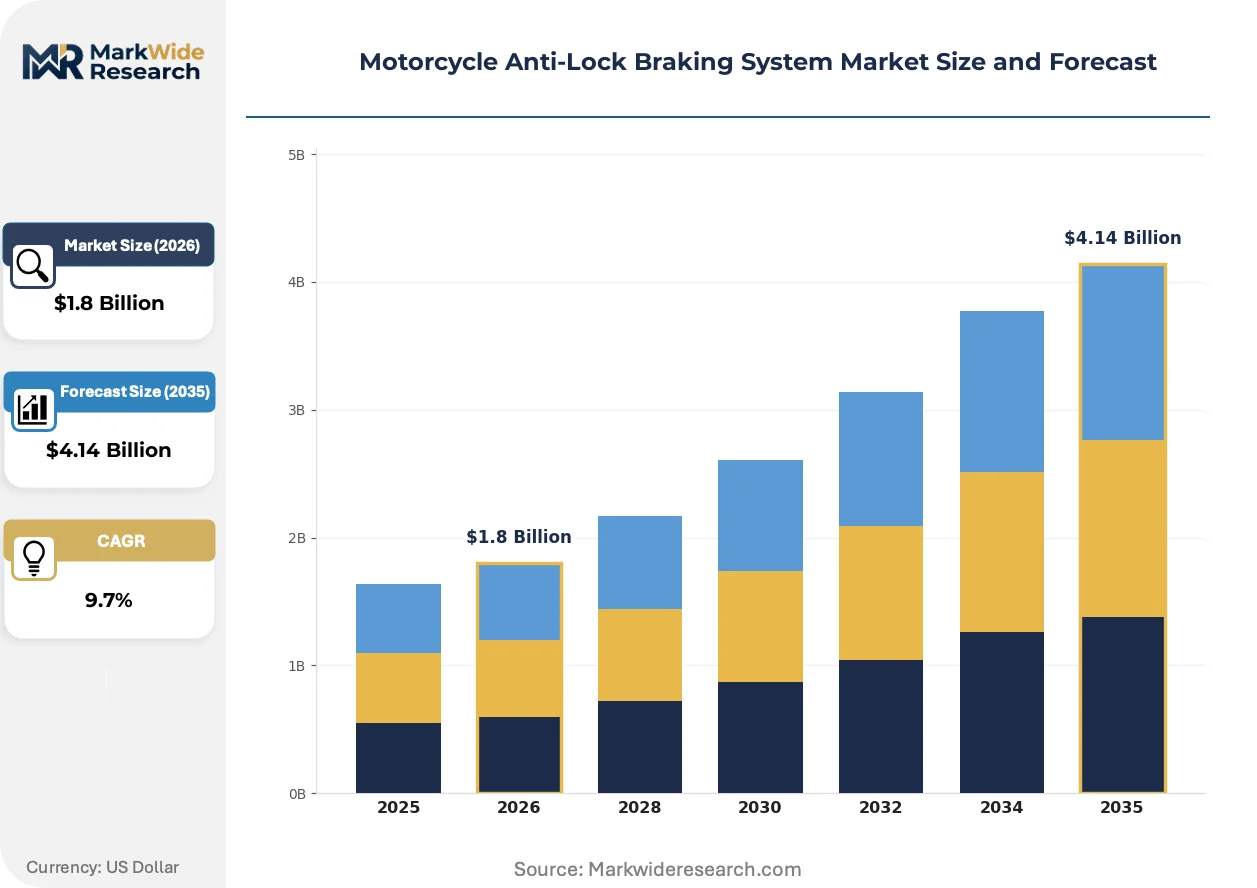
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Aftermarket Solutions, Electronic Units, Hydraulic Units Technology: ABS, Combined Braking Systems, Enhanced Stability Control, Traction Control Installation: Factory-Fitted, Retrofitted, Dealer-Installed, Custom Installations End User: OEMs, Fleet Operators, Individual Consumers, Training Institutions |
| Companies Covered | Robert Bosch GmbH, Continental AG, Brembo S.p.A, ZF Friedrichshafen AG, Honda Motor Company, Ltd, Nissin Kogyo Co., Ltd., BWI Group, Knorr-Bremse AG, Hitachi Astemo, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Anti-Lock Braking System Market Shifts & Advancements
Wheel-speed sensor fusion with inertial measurement units is redefining ABS activation precision. This convergence is enabling cornering-aware braking modulation that preserves rider stability during lean-angle deceleration.
Cornering-ABS technology is expanding into mid-displacement motorcycles previously limited to premium sport segments. OEMs in Italy and Japan are adopting IMU-assisted hydraulic modulation for 300-500cc commuter platforms. This expansion is compressing the feature differentiation window between premium and volume manufacturers.
The EU Green Deal's F-Gas Regulation is restricting hydrofluorocarbon-based hydraulic fluid formulations. ABS suppliers must reformulate brake fluid compatibility and retest seal material degradation profiles. European OEM supply chains are absorbing these specification changes ahead of 2027 enforcement windows.
Fleet procurement teams now bundle ABS compliance verification with total cost of ownership calculations. Commercial operators in Indonesia and Brazil are unbundling after-sales service contracts from hardware purchase agreements. This recalculation is most visible in Jakarta's delivery logistics sector where insurance premium discounts now hinge on documented ABS maintenance records.
Motorcycle Anti-Lock Braking System Market Segmentation
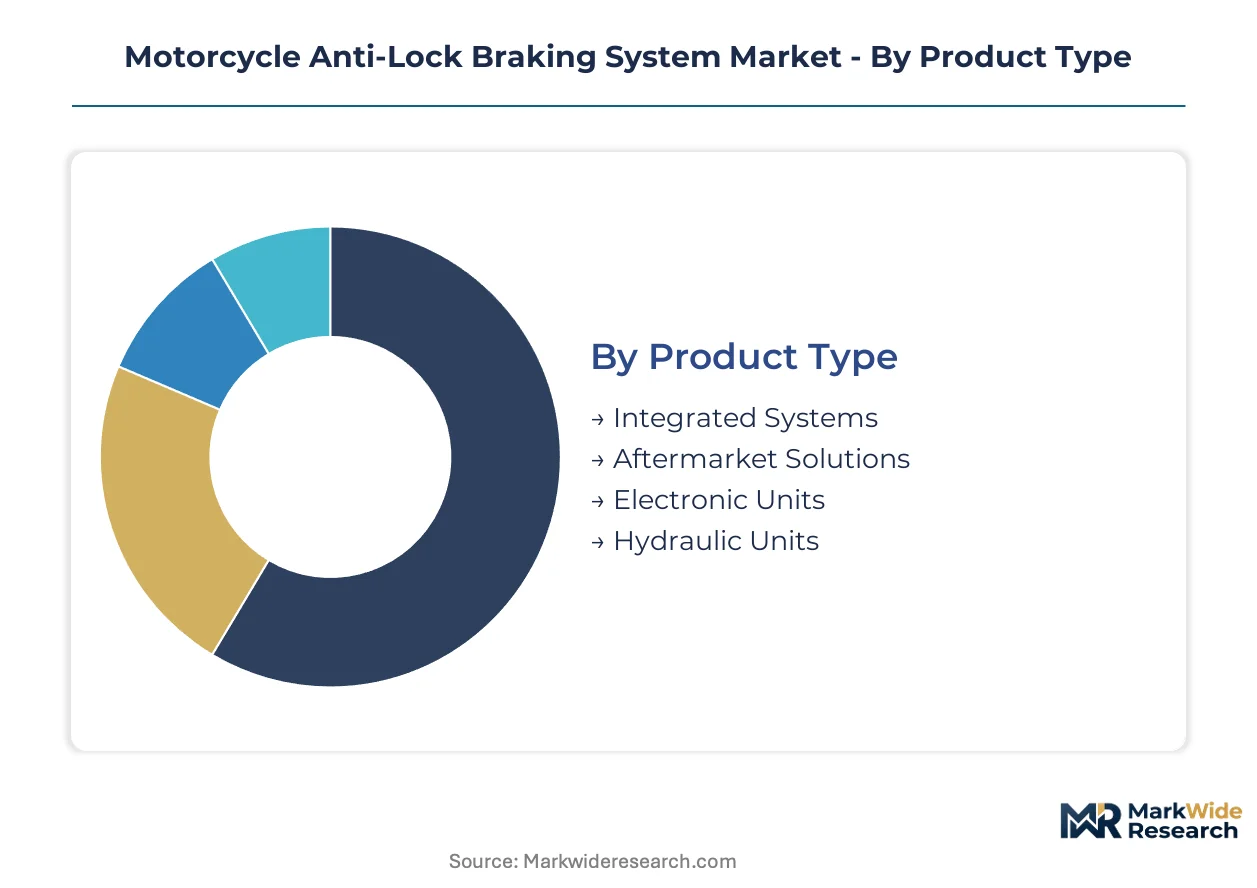
Motorcycle ABS procurement patterns diverge sharply across product architectures and installation channels. Upgrade cycles for hydraulic units and sensor-controller bundles reshape how suppliers allocate engineering resources and inventory.
Product Type:
Replacement demand for hydraulic and electronic subsystems accelerates as fleet operators in Indonesia and India compress maintenance intervals under tightening safety mandates.
- Integrated Systems:Bundled sensor-controller architectures combine wheel-speed monitoring with ECU processing in single housings. Factory-fit contracts with premium European OEMs concentrate demand here, driven by CE marking pre-certification requirements and electromagnetic compatibility streamlining.
- Aftermarket Solutions:Standalone retrofit kits target commercial delivery fleets facing insurance penalties for non-compliant vehicles. India's BIS certification documentation burdens constrain independent mechanic penetration, though mobile installation units in Brazil bypass dealership infrastructure gaps.
- Electronic Units:Discrete ECU modules enable tiered ABS functionality upgrades across mid-volume motorcycle platforms.
- Hydraulic Units:Precision solenoid valve assemblies face geographic supply concentration in German and Japanese manufacturing clusters.
Integrated Systems sits at the top of the volume ranking, with Aftermarket Solutions climbing the fastest.
Technology:
Cost-tier differentiation separates premium slip-ratio algorithms from threshold-based implementations across Southeast Asian OEM portfolios.
- ABS:Threshold-based and slip-ratio modulation algorithms activate hydraulic pressure cycles below 15 milliseconds. India's Central Motor Vehicles Rules mandate this technology above 125cc displacement, compelling domestic OEMs to redesign braking architectures with compressed supplier qualification windows.
- Combined Braking Systems:Single-actuation architectures distribute braking force across front and rear wheels without full ABS complexity. Vietnam and Thailand OEMs prioritize CBS-ABS hybrids to preserve margin while meeting baseline safety mandates in cost-sensitive commuter segments.
- Enhanced Stability Control:IMU-assisted yaw and pitch correction extends cornering-aware functionality into mid-displacement platforms.
- Traction Control:Wheel-slip mitigation during acceleration complements ABS deceleration logic in premium sport motorcycles.
ABS dominates current procurement volumes, though Combined Braking Systems gains share fastest among 300-500cc commuter platforms.
Installation:
Customer-type stratification splits procurement between factory-integrated supply chains and post-sale service networks.
- Factory-Fitted:OEM assembly-line integration ensures calibration precision and warranty alignment. Indonesian commercial delivery fleets now mandate factory-fit documentation for insurance premium discounts, shifting procurement away from retrofit channels.
- Retrofitted:Post-purchase installation targets existing fleet assets in Brazil's underpenetrated commercial motorcycle segment. Mobile service units address dealership infrastructure gaps in rural operating regions.
- Dealer-Installed:Authorized service networks maintain ECU parameter matching through proprietary diagnostic tools.
- Custom Installations:Specialized racing and performance applications require individualized hydraulic routing and calibration.
Factory-Fitted leads value capture, with Retrofitted expanding most quickly in emerging market fleet segments.
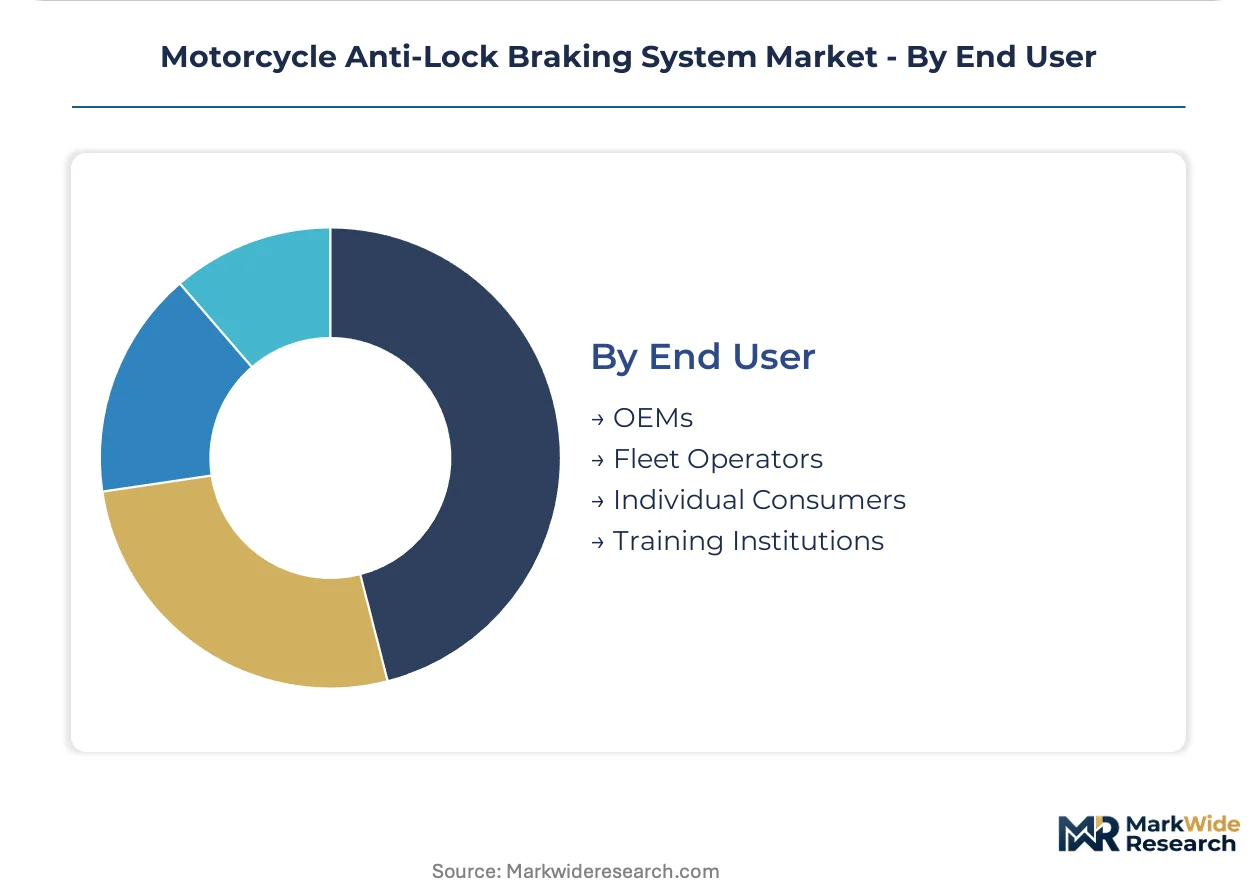
End User:
Application-specific performance requirements drive divergent specification priorities across procurement stakeholders.
- OEMs:Volume manufacturers redesign braking architectures to comply with India's displacement-based mandates and Indonesia's tightening commercial vehicle rules. Sourcing timelines compress as homologation deadlines approach.
- Fleet Operators:Last-mile logistics providers in Jakarta and São Paulo unbundle after-sales service contracts from hardware purchases. Total cost of ownership recalculations now weight documented ABS maintenance records against insurance premium discounts.
- Individual Consumers:Premium sport and touring motorcycle buyers demand cornering-ABS functionality previously limited to racing segments.
- Training Institutions:Rider safety courses require standardized ABS-equipped demonstration fleets for curriculum certification.
OEMs command the largest procurement volumes, with Fleet Operators showing the steepest expansion trajectory under regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ABS technology first achieved commercial scale in Germany during the 1980s through automotive supplier engineering, then migrated to motorcycle applications as Japanese manufacturers refined compact hydraulic architectures for two-wheeler stability control.
Germany
Precision solenoid valve manufacturing clusters around Stuttgart and Munich supply tier-one automotive hydraulic systems. The KBA enforces electromagnetic compatibility testing for CE marking compliance. Continental AG and Robert Bosch GmbH anchor factory-fit contracts with premium European OEMs from Baden-Württemberg engineering centers.
India
Domestic OEMs redesign braking architectures for motorcycles above 125cc displacement under Central Motor Vehicles Rules mandates. BIS certification requirements compress supplier qualification windows. Manufacturing concentrates in Pune and Chennai industrial corridors where tier-two hydraulic component suppliers triple certification throughput.
Indonesia
Commercial delivery fleets in Jakarta face insurance penalties for non-compliant vehicles under tightening two-wheeler safety rules. The national transport ministry mandates ABS documentation for logistics operator licensing. Last-mile procurement teams unbundle after-sales service contracts from hardware purchases.
Japan
IMU-assisted cornering-ABS architectures originate from Chubu and Kansai engineering centers. METI standards govern wheel-speed sensor fusion protocols for export-ready product lines. Nissin Kogyo Co., Ltd. and Hitachi Astemo, Ltd. occupy positions within integrated sensor-controller supply chains.
Brazil
Commercial motorcycle operators in São Paulo represent underpenetrated aftermarket retrofit demand. ANVISA aligns with Mercosur technical regulations for brake system homologation. Mobile installation units bypass dealership infrastructure gaps in rural operating regions.
Motorcycle Anti-Lock Braking System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ABS value chain. The supplier base concentrates around integrated system bundlers and discrete hydraulic specialists. Tier-one automotive suppliers exemplify full-system architects, while brake-focused engineering houses occupy performance-calibration niches. Dominant competitive moves include electromagnetic compatibility pre-certification for CE marking alignment and backward integration into wheel-speed sensor ASIC sourcing.
Among German-based integrated system architects, Robert Bosch GmbH and Continental AG anchor factory-fit supply relationships with premium OEMs. Brembo S.p.A represents the performance-calibration archetype from its Italian engineering base. These three companies exemplify how geographic proximity to automotive manufacturing clusters shapes ABS procurement hierarchies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Brembo S.p.A |
| ZF Friedrichshafen AG |
| Honda Motor Company, Ltd |
| Nissin Kogyo Co., Ltd. |
| BWI Group |
| Knorr-Bremse AG |
| Hitachi Astemo, Ltd. |
| Others |
Supply & Pricing Matrix
Captive solenoid valve production in German and Japanese manufacturing clusters anchors both supply security and premium pricing power for integrated ABS system architects. This backward integration into precision hydraulic components insulates tier-one suppliers from semiconductor allocation volatility while enabling three-tier pricing stratification across factory-fit, dealer-installed, and aftermarket retrofit channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated sensor-controller bundles from discrete hydraulic units and basic CBS-ABS hybrid architectures. Price differentiation hinges on CE marking pre-certification status and bundled after-sales service contracts. Cost compression in the retrofit tier intensifies because India's BIS documentation burdens force mobile installation units to absorb compliance overhead. Fleet operators in Indonesia exhibit lowest price sensitivity due to insurance mandate penalties, while independent mechanics in Brazil face acute margin pressure from diagnostic tool access gaps.
Supply Chain Analysis
CE marking and BIS certification gating compresses supplier qualification windows and concentrates procurement relationships around pre-qualified tier-one architects. Precision solenoid valve manufacturing draws from Germany, Japan, and select Indian industrial corridors near Pune and Chennai. Wheel-speed sensor ASICs and high-pressure sealing polymers constitute critical input dependencies. Single-source vulnerability persists for electromagnetic compatibility test bench capacity. Distribution runs through OEM assembly-line integration, authorized dealer networks, and emerging mobile retrofit units in rural Brazilian operating regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's Central Motor Vehicles Rules displacement mandate and Indonesia's commercial fleet safety directives mechanically expand addressable demand regardless of macroeconomic cycling.
For Market Incumbents: Cement factory-fit supply relationships through CE marking pre-certification investment and backward integration into wheel-speed sensor ASIC sourcing. Capacity addition in Indian industrial corridors near Pune addresses compressed OEM sourcing timelines. Defensive positioning requires countering emerging mobile retrofit entrants in Brazil's underpenetrated commercial motorcycle segment through dealer-installed channel control. For New Entrants and Emerging Players: Launch via mobile installation units targeting Brazil's rural commercial motorcycle operators where dealership infrastructure gaps persist. White-space concentration sits in aftermarket retrofit demand from Jakarta's last-mile logistics providers facing insurance penalties. Go-to-market execution should prioritize BIS certification documentation services bundled with hardware to bypass independent mechanic capability constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration engineer scarcity intersects with divergent NHTSA-EU-BIS homologation timeline compression. Long-term viability favors integrated system architects with captive electromagnetic compatibility test bench capacity and established premium OEM factory-fit contracts. Watch for inflection when India's domestic OEM braking architecture redesign cycle completes and procurement volumes shift from qualification-phase sampling to production-scale offtake.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification Investment | Opens premium European OEM sourcing contracts ahead of F-Gas Regulation enforcement windows. |
| Backward Integration into Sensor ASICs | Reduces allocation risk from automotive MCU foundry competition exceeding 26-week lead times. |
| Mobile Retrofit Unit Deployment | Bypasses dealership infrastructure gaps in Brazil's rural commercial motorcycle operating regions. |
| CBS-ABS Hybrid Architecture Development | Preserves margin for Vietnam and Thailand OEMs facing cost-sensitive commuter segment procurement. |
| Calibration Engineer Talent Acquisition | Addresses slip-ratio algorithm tuning scarcity competing OEM technical centers in India and Indonesia. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down hydraulic unit supplier production tracking forms the analytical core of this study. Primary interviews with ABS system procurement managers at Indonesian commercial delivery fleets, braking architecture engineers at Indian domestic OEMs, tier-one supplier sales directors, and BIS certification consultants combined with secondary validation from Central Motor Vehicles Rules filings, KBA electromagnetic compatibility test protocols, ANVISA brake system homologation records, and vehicle production databases. Triangulation across these sources ensures volume and value estimates align with regulatory mandate implementation timelines.
Historical trendline analysis of ABS fitment penetration rates across displacement categories and fleet segments established baseline growth trajectories. The projection framework models technology segmentation across integrated systems, aftermarket solutions, and CBS-ABS hybrids; installation channel splits between factory-fitted, retrofitted, and dealer-installed; and end-user stratification across OEMs, fleet operators, and individual consumers. CAGRs derive from regulatory deadline clustering and supplier capacity expansion announcements. Industry-specific forecast inputs include semiconductor allocation cycles and hydraulic fluid formulation transitions under F-Gas Regulation constraints.
Several conditions sit outside the modeled scope, including unannounced displacement threshold adjustments in Indian regulations, Mercosur technical regulation harmonization delays, and abrupt automotive MCU foundry capacity reallocations. Forecasts reflect assumptions about regulatory enforcement consistency and supplier qualification timeline adherence. A model refresh is warranted upon material change in India's BIS certification documentation requirements or Indonesia's insurance penalty enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Lane Departure Warning (LDW) Market