
 Global Antimicrobial Medical Textiles Market | 2026-2036
Global Antimicrobial Medical Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antimicrobial Medical Textiles Market Foresight
A shift from single-source silver suppliers toward multi-source copper and chitosan feedstock partnerships is recalibrating raw material security across the supply base. BASF SE leverages its polymer science portfolio to anchor antimicrobial masterbatch production in Europe. DuPont de Nemours Inc. competes through fiber engineering expertise that sustains durability claims under repeated sterilization cycles. Microban International differentiates by controlling licensing networks that extend its additive technology into medical-grade textile finishes globally.
Antimicrobial medical textiles are engineered fabrics incorporating biocidal agents such as silver ions, copper nanoparticles, or chitosan biopolymers to inhibit microbial colonization on surfaces contacting patients or clinical environments, typically manufactured through melt extrusion, pad-dry-cure finishing, or electrospinning processes to achieve specified log-reduction rates against Staphylococcus aureus and Escherichia coli. Wound dressings and surgical drapes occupy the largest product positions due to direct patient contact requirements and reimbursement alignment with hospital-acquired infection reduction protocols. Silver-based technology leads the antimicrobial agent landscape, though chitosan-coated alternatives are gaining traction in burn care applications where biocompatibility and biodegradability priorities outweigh metal persistence concerns.
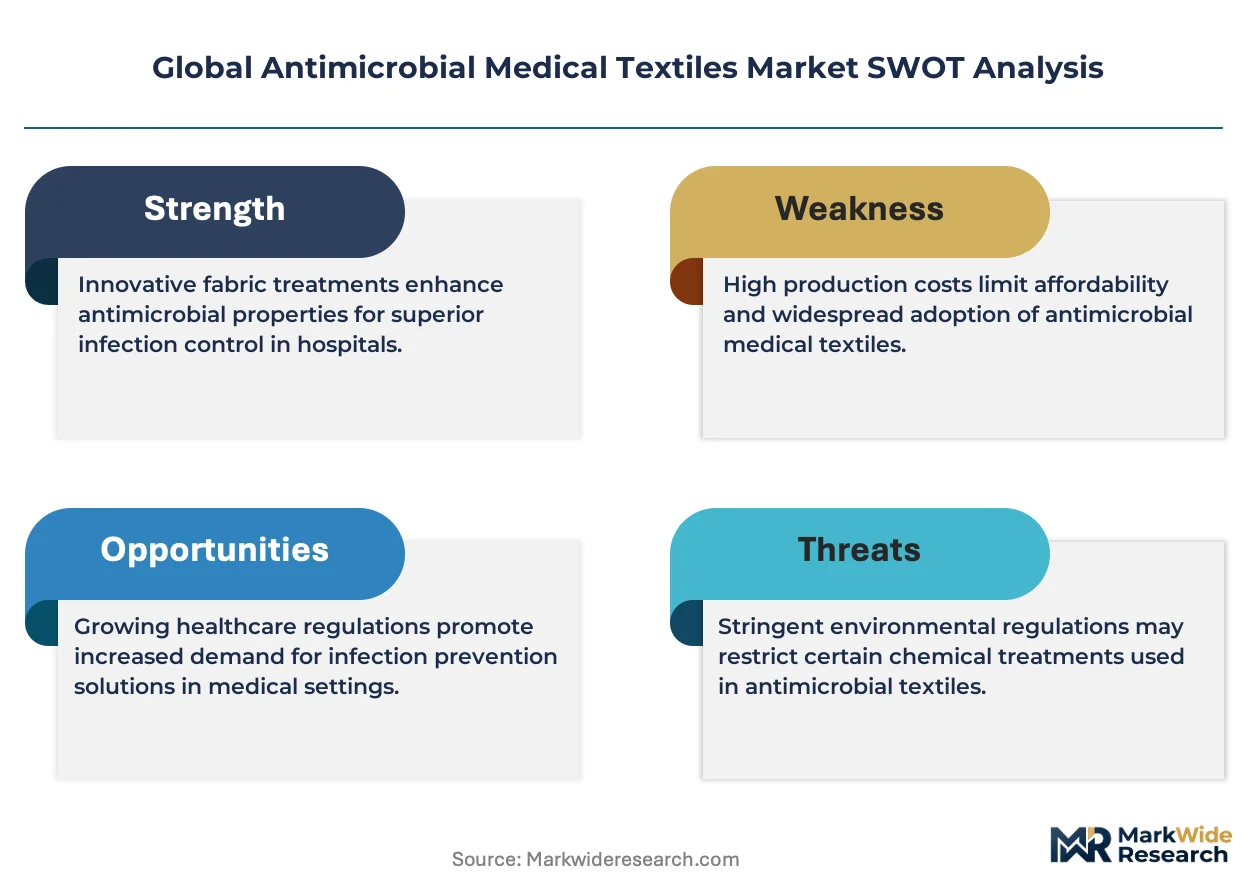
The FDA enforces 510(k) premarket notification requirements for antimicrobial claims on medical textiles, while the EU Medical Device Regulation mandates clinical evidence under updated classification rules that reclassify many antimicrobial fabrics from Class I to higher-risk categories. Health Canada and Japan's PMDA maintain parallel substantiation frameworks that create compliance complexity for manufacturers seeking multi-regional approval. Stakeholders must monitor evolving EPA and ECHA assessments on nanosilver environmental persistence, as these evaluations threaten to restrict certain antimicrobial chemistries regardless of clinical efficacy demonstrations.
Market Dynamics
The antimicrobial medical textiles sector is contending with a fundamental recalibration of raw material sourcing strategies as silver supply concentration risks accelerate diversification into copper nanoparticles and chitosan biopolymers.
Growth Catalysts
- EU Medical Device Regulation reclassification:The MDR's elevation of antimicrobial fabrics to higher-risk device categories forces hospital procurement departments toward validated, reimbursable products with established clinical evidence packages.
- Surgical site infection protocols:Tertiary hospitals in the United States, Germany, and China are mandating silver-impregnated wound dressings for post-operative care pathways, embedding these textiles into standard surgical bundles.
- Electrospinning process maturation:Nanofiber manufacturing advances enable chitosan coating uniformity at commercial scale, opening burn care applications where biocompatibility requirements previously blocked synthetic alternatives.
Market Restraints
- Silver price volatility:Concentration of primary silver refining in specific geopolitically sensitive regions exposes masterbatch producers to input cost spikes that compress margin structures.
- ECHA nanomaterial assessments:Pending environmental persistence evaluations for nanosilver threaten to impose usage restrictions regardless of demonstrated clinical efficacy, creating regulatory overhang.
- Chitosan supply fragmentation:Crustacean-derived biopolymer sourcing remains dispersed across small-scale regional processors, limiting batch consistency for medical-grade specifications.
Strategic Opportunities
- India hospital infrastructure expansion:Government infection control mandates in tier-2 and tier-3 cities are creating first-mover advantages for suppliers establishing localized finishing capabilities.
- Reusable surgical textile programs:Sustainability pressures are reviving commercial interest in durable antimicrobial fabrics capable of withstanding 100+ sterilization cycles without efficacy degradation.
- Japan PMDA parallel track harmonization:Alignment initiatives between Japanese and FDA 510(k) pathways are reducing multi-regional approval timelines for antimicrobial claims.
Industry Challenges
- Log-reduction testing standardization:Inconsistent ISO 20743 interpretation across notified bodies creates certification delays and redundant laboratory expenditures.
- Polymer-antimicrobial bonding expertise:Scarce technical talent capable of engineering durable ion-release kinetics in melt-extruded fibers commands premium compensation and constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antimicrobial Medical Textiles Market |
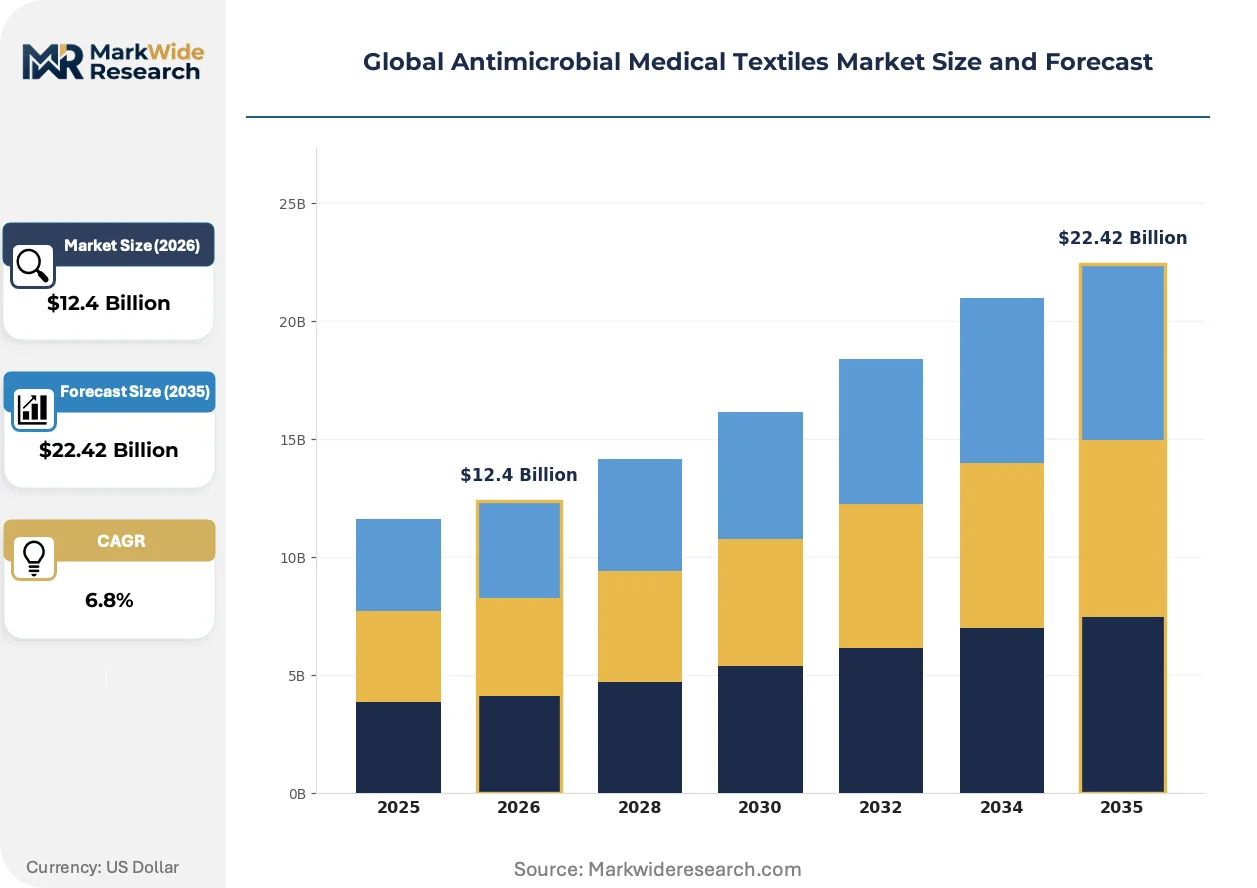
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound Dressings, Surgical Drapes, Hospital Linens, Medical Gowns, Orthopedic Supports Technology: Silver-based, Copper-infused, Chitosan-coated, Zinc Oxide-treated, Polyhexamethylene Biguanide Application: Surgical Sites, Infection Control, Burn Care, Chronic Wounds, Dental Care End User: Hospitals, Specialty Clinics, Wound Care Centers, Dental Practices, Long-term Care Facilities |
| Companies Covered | Milliken & Company, Microban International, BASF SE, DuPont de Nemours Inc., Sanitized AG, Indorama Ventures Fibers Germany, UNITIKA LTD, BioCote Limited, HeiQ Materials AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antimicrobial Medical Textiles Market Shifts & Advancements
Active innovation fronts in antimicrobial textiles center on material science breakthroughs, evolving regulatory substantiation requirements, and procurement model transformations that favor integrated solution providers over commodity suppliers.
Chitosan biopolymer coatings are absorbing market attention in specialized wound care segments where metal persistence concerns dominate clinician preference. Burn centers in Germany and the United States are piloting chitosan-impregnated nanofiber matrices for partial-thickness injuries, with early adoption compressing the addressable market for conventional silver alginate dressings in these high-acuity settings. The technology is absorbing share fastest in pediatric and geriatric applications where biocompatibility testing requirements are most stringent.
REACH authorization procedures for nanosilver are reshaping formulation strategies across European manufacturing operations. The ECHA's ongoing restriction proposal evaluations are forcing textile finishers to document environmental release profiles and aquatic toxicity data that previously sat outside standard medical device dossiers. Surgical drape producers with integrated European finishing capacity are responding by accelerating copper-based alternative development to preserve market access regardless of regulatory outcome.
Hospital procurement departments are consolidating vendor relationships around full-category suppliers capable of delivering antimicrobial textiles alongside complementary infection control products. Group purchasing organizations in the United States are displacing single-product contracts with multi-year agreements bundling surgical drapes, wound dressings, and staff apparel under unified quality assurance frameworks. This concentration is most visible in integrated delivery networks spanning multiple states, where standardization incentives override legacy supplier preferences.
Global Antimicrobial Medical Textiles Market Segmentation
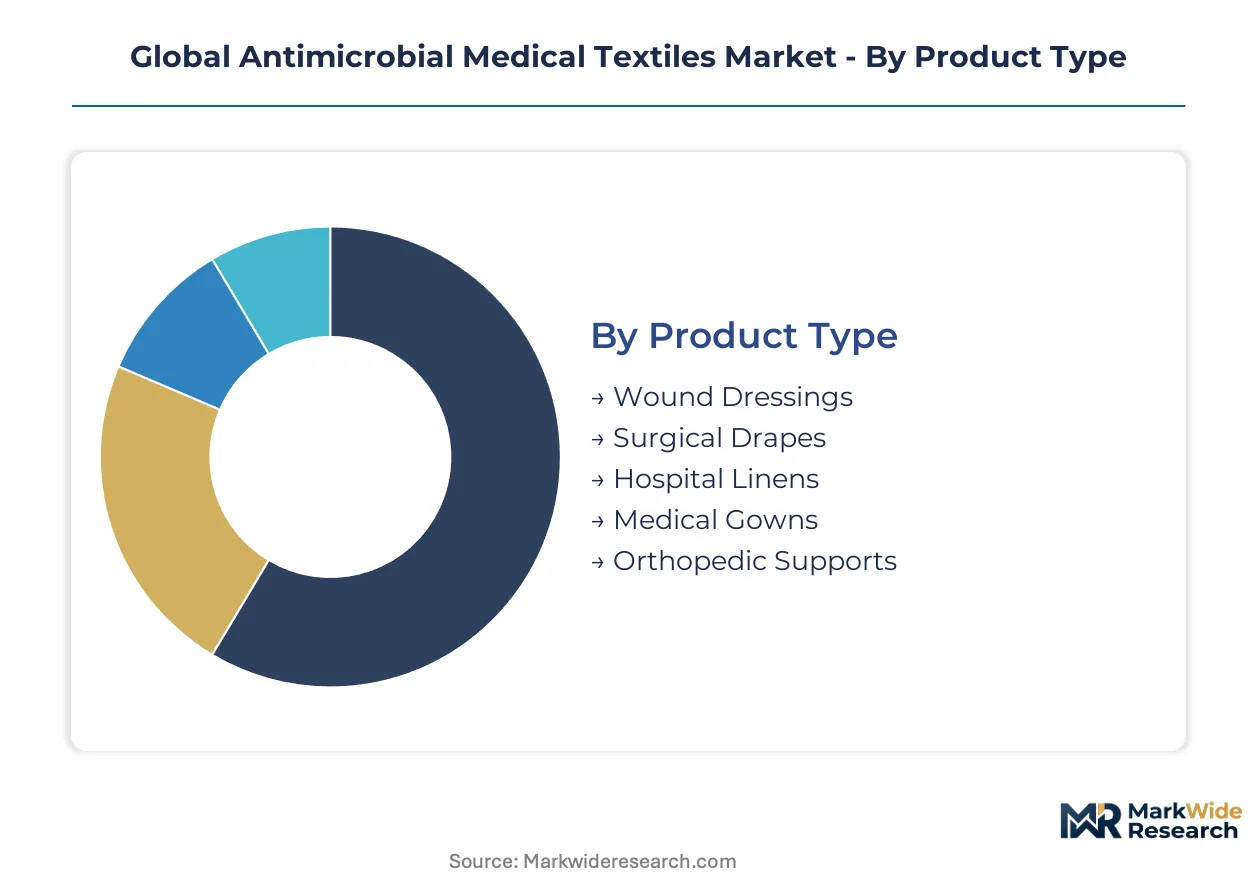
Segmentation in antimicrobial medical textiles reveals distinct value capture zones where embedded biocidal technologies command premium positioning against standalone commodity alternatives. Product architecture and antimicrobial chemistry together determine reimbursement eligibility and sterilization durability requirements across clinical settings.
Product Type:
Standalone wound care products absorb the majority of procurement budgets, while embedded surgical textiles integrate into broader infection control bundles requiring systemic validation.
- Wound Dressings:Silver-impregnated alginate and hydrofiber constructions deliver sustained ion release against Staphylococcus aureus colonization. Tertiary hospitals in the United States and Germany mandate these for post-operative protocols, embedding them into standardized surgical bundles with dedicated reimbursement codes.
- Surgical Drapes:Multi-layer polypropylene laminates with integrated antimicrobial masterbatches maintain barrier integrity across extended procedures. Demand concentrates in integrated delivery networks pursuing vendor consolidation under unified quality assurance frameworks.
- Hospital Linens:Cotton-polyester blends with durable antimicrobial finishing withstand industrial laundering cycles in high-throughput facilities.
- Medical Gowns:Spunbond-meltblown-spunbond constructions with surface-bound biocides address fluid resistance and microbial inhibition simultaneously.
- Orthopedic Supports:Elastic and rigid bracing textiles with odor-control antimicrobial treatments target ambulatory and post-surgical rehabilitation settings.
Volume placements concentrate in wound dressings; the faster expansion belongs to surgical drapes as procurement consolidation accelerates.
Technology:
Cost tier stratification separates metal-ion platforms with established clinical dossiers from emerging biopolymer alternatives competing on biocompatibility premiums.
- Silver-based:Elemental and ionic silver embedded through melt extrusion or pad-dry-cure finishing achieves specified log-reduction rates against gram-positive and gram-negative pathogens. FDA 510(k) clearance pathways and EU MDR clinical evidence requirements favor this chemistry due to decades of substantiation data.
- Copper-infused:Nanoparticle and micron-scale copper oxide integration offers alternative metal persistence profiles with lower environmental toxicity concerns. European surgical drape manufacturers are accelerating development to preserve market access pending ECHA nanosilver restriction outcomes.
- Chitosan-coated:Crustacean-derived biopolymer finishes provide biodegradable antimicrobial action with superior biocompatibility for pediatric and geriatric applications.
- Zinc Oxide-treated:Broad-spectrum antimicrobial with lower cytotoxicity profiles supports consumer-facing medical textile segments.
- Polyhexamethylene Biguanide:Cationic polymer biocide effective against biofilm formation in wound contact layers.
Silver-based chemistry dominates current procurement volumes; chitosan-coated alternatives are climbing the fastest as burn centers prioritize biocompatibility over metal persistence.
Application:
Customer type differentiation separates acute care settings with infection control mandates from specialized facilities managing chronic or complex wound populations.
- Surgical Sites:Antimicrobial textiles deployed in operating theaters and immediate post-operative care require validation against hospital-acquired infection reduction protocols. Tertiary hospitals in China are expanding infrastructure and enforcing stricter mandates that accelerate uptake of validated products.
- Infection Control:Broad-spectrum antimicrobial deployment across high-touch surfaces and staff apparel in clinical environments. Group purchasing organizations in the United States favor bundled procurement spanning drapes, dressings, and apparel under single quality frameworks.
- Burn Care:Partial-thickness injury management demands biocompatibility-optimized materials with minimal cytotoxicity. German and United States burn centers are piloting chitosan nanofiber matrices, compressing addressable share for conventional silver alternatives.
- Chronic Wounds:Long-duration dressing applications for diabetic foot ulcers and pressure injuries require sustained antimicrobial release without cytotoxicity.
- Dental Care:Antimicrobial textiles in surgical bibs, chair covers, and protective apparel address aerosol-generating procedure risks.
Surgical site applications anchor current volume; burn care demonstrates the steepest expansion trajectory as biocompatibility priorities reshape clinician preferences.
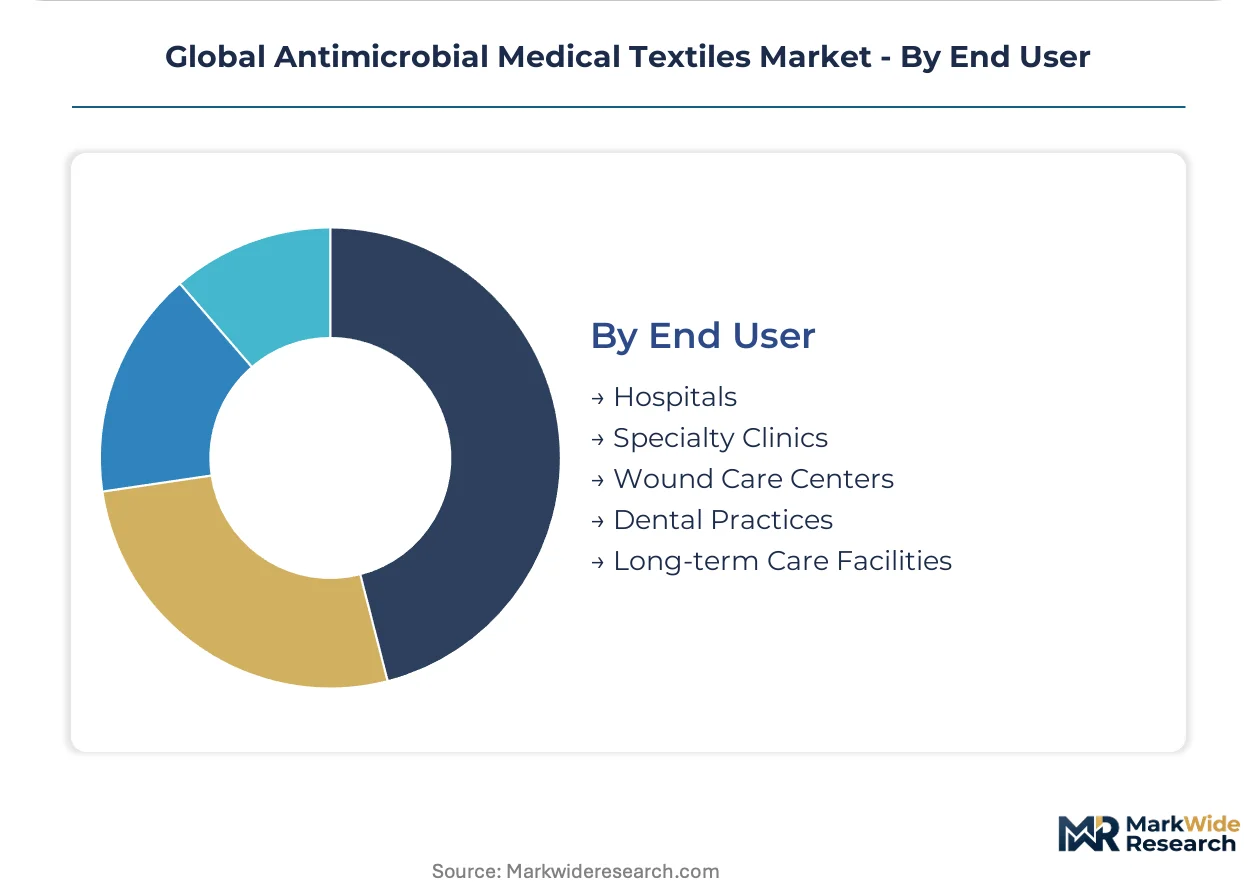
End User:
Supply concentration patterns favor hospital systems with centralized procurement authority over fragmented outpatient and long-term care channels.
- Hospitals:Acute care facilities with dedicated infection control committees and standardized protocol enforcement drive antimicrobial textile specification. India hospital infrastructure expansion in tier-2 and tier-3 cities creates first-mover advantages for suppliers establishing localized finishing capabilities.
- Specialty Clinics:Outpatient surgical and wound care facilities with narrower product portfolios and price-sensitive procurement.
- Wound Care Centers:Dedicated facilities managing complex and chronic wounds with specialized dressing requirements.
- Dental Practices:Smaller-scale procurement with emphasis on disposable antimicrobial barriers and protective apparel.
- Long-term Care Facilities:Pressure injury prevention and incontinence management drive demand for antimicrobial linens and support surfaces.
Volume concentrates in hospitals; specialty clinics are gaining share fastest as ambulatory surgical migration accelerates procedure decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authority concentrates antimicrobial textile demand in the United States, Germany, and China, where infection control mandates and infrastructure expansion create validated market entry points for suppliers with established regulatory dossiers.
United States
Tertiary hospitals in Texas and California mandate silver-impregnated wound dressings for post-operative protocols under standardized surgical bundles. The FDA enforces 510(k) premarket notification requirements that favor manufacturers with decades of antimicrobial substantiation data. Group purchasing organizations in the Midwest are consolidating vendor relationships around full-category suppliers capable of delivering integrated infection control solutions.
Germany
Burn centers in Bavaria and North Rhine-Westphalia pilot chitosan nanofiber matrices for partial-thickness injuries, compressing demand for conventional silver alternatives. The EU Medical Device Regulation reclassifies antimicrobial fabrics to higher-risk categories, forcing procurement departments toward validated products with clinical evidence packages. Industrial finishing clusters around Stuttgart anchor masterbatch production for surgical drape manufacturers.
China
Tier-2 and tier-3 cities expand hospital infrastructure under government infection control mandates that accelerate uptake of validated antimicrobial textiles. The NMPA maintains parallel substantiation frameworks with FDA pathways, reducing multi-regional approval complexity for compliant manufacturers. Yangtze River Delta textile processors are establishing localized finishing capabilities to capture first-mover advantages in provincial procurement.
India
Government infection control mandates in Maharashtra and Gujarat create procurement opportunities for suppliers establishing regional finishing operations. The CDSCO aligns medical device classification with evolving international standards, though batch consistency requirements challenge crustacean-derived biopolymer sourcing. Tamil Nadu textile hubs are investing in electrospinning capacity to address burn care applications with domestic chitosan coating production.
Japan
PMDA alignment initiatives with FDA 510(k) pathways reduce approval timelines for antimicrobial claims on surgical textiles. Kanto region hospitals enforce stricter hospital-acquired infection protocols that embed validated products into standardized care pathways. Osaka-based fiber engineering specialists concentrate R&D investment in durable ion-release kinetics for reusable surgical textile programs.
Global Antimicrobial Medical Textiles Market Competitive Landscape
Strategic partnerships dominate the current landscape as specialty additive suppliers align with polymer science and fiber engineering houses to secure raw material security and distribution reach. The vendor base stratifies across three tiers: multinational chemical conglomerates with integrated masterbatch production, dedicated antimicrobial technology licensors controlling global finish networks, and regional textile processors with localized coating capabilities. Two archetypes capture value: polymer science anchors supplying validated masterbatches under long-term hospital procurement contracts, and technology licensors extending additive platforms through royalty-based partnerships with finished goods manufacturers. Capacity expansion in Asian finishing operations and technology licensing agreements for copper-based alternatives represent the dominant competitive moves.
Among European chemical conglomerates, BASF SE and Sanitized AG occupy positions anchoring antimicrobial masterbatch supply for surgical drape and wound dressing manufacturers. Microban International exemplifies the technology licensor archetype, controlling additive networks that extend into medical-grade textile finishes. DuPont de Nemours Inc. represents fiber engineering specialization, with durability claims under repeated sterilization cycles serving procurement consolidation trends in United States integrated delivery networks.
| Leading Market Players |
|---|
| Milliken & Company |
| Microban International |
| BASF SE |
| DuPont de Nemours Inc. |
| Sanitized AG |
| Indorama Ventures Fibers Germany |
| UNITIKA LTD |
| BioCote Limited |
| HeiQ Materials AG |
| Others |
Supply & Pricing Matrix
Silver masterbatch feedstock costs cascade through three distinct pricing tiers as the metal journeys from primary refiners in geopolitically sensitive regions through European polymer compounders to finished surgical drape manufacturers. Hospital procurement departments in the United States and Germany absorb these input fluctuations differently, with integrated delivery networks leveraging volume scale to compress margins at commodity-grade suppliers while premium chitosan-coated alternatives command biocompatibility premiums in burn care settings.
Pricing Analysis
High-volume wound dressing contracts sacrifice margin for procurement security while specialized chitosan nanofiber matrices capture premium positioning. Pricing stratifies across FDA-cleared silver formulations, CE-marked copper alternatives, and experimental biopolymer tiers differentiated by clinical evidence depth. Cost compression in standard silver-alginate segments intensifies as Chinese textile processors expand electrospinning capacity. Group purchasing organizations exhibit lowest price sensitivity for bundled infection control solutions, whereas outpatient wound care centers prioritize per-unit economy.
Supply Chain Analysis
Direct-to-hospital channels handle tier-one procurement demand from integrated delivery networks, while regional distributors serve fragmented specialty clinic markets. Raw material sourcing concentrates in China for silver refining, Germany for polymer masterbatch production, and Vietnam for crustacean-derived chitosan processing. Feedstock dependencies span silver bullion, medical-grade polypropylene, and purified chitosan biopolymers. Single-source vulnerability in nanosilver supply threatens European surgical drape manufacturers pending ECHA restriction outcomes. Distribution runs through GPO-authorized vendor networks in North America and hospital procurement consortiums in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antimicrobial medical textiles sector occupies a technology-transition phase as chitosan biopolymer coatings displace legacy silver-ion platforms in pediatric and burn care applications where biocompatibility testing requirements are most stringent.
For Market Incumbents: Cement masterbatch supply security through backward integration into copper nanoparticle sourcing or exclusive chitosan processor partnerships. Accelerate FDA 510(k) dossier expansion for reusable surgical textiles capable of withstanding repeated sterilization cycles. Defend against emerging Asian electrospinning specialists by locking multi-year contracts with United States integrated delivery networks. For New Entrants and Emerging Players: Begin with localized finishing capabilities in India's tier-2 and tier-3 hospital markets where government infection control mandates outpace domestic supply. Target burn care centers in Germany and the United States with chitosan nanofiber matrices that bypass silver persistence concerns. Pursue technology licensing arrangements with established additive suppliers rather than competing on capital-intensive masterbatch production. For Investors and Strategic Acquirers: ECHA's pending nanosilver restriction proposal is the leading indicator that copper-based alternative developers will capture displaced market share regardless of clinical efficacy demonstrations. Position acquisition screening around European surgical drape manufacturers with integrated finishing capacity and established clinical evidence packages. Monitor PMDA-FDA harmonization announcements as signals for accelerated multi-regional approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Based Formulation Development | Preserves European market access pending ECHA nanosilver restriction outcomes. |
| Electrospinning Capacity Expansion | Enables commercial-scale chitosan coating uniformity for burn care applications. |
| Hospital System Partnership | Secures procurement consolidation benefits within United States integrated delivery networks. |
| Regulatory Dossier Harmonization | Reduces approval timelines across FDA, EU MDR, and Japan PMDA parallel pathways. |
| Reusable Textile Program Investment | Captures sustainability-driven demand for durable antimicrobial fabrics. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, ECHA restriction proposal evaluations, and hospital procurement databases, complemented by interviews with polymer science R&D directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at antimicrobial additive suppliers. Secondary validation drew from customs trade data, SEC 10-K disclosures, and ISO 20743 testing laboratory records. Bottom-up volume estimates triangulated against top-down market sizing from raw material consumption patterns.
Cross-referencing historical antimicrobial textile adoption curves against expert panel input on chitosan biopolymer maturation timelines anchored the analytical framework. Segmentation modeling spanned product architecture, antimicrobial chemistry, acute versus chronic care applications, and hospital system procurement authority. CAGRs were derived from log-linear trend fitting adjusted for regulatory inflection points. Forecast inputs included silver price volatility scenarios and electrospinning yield improvement trajectories.
Underlying measurement precision varies by segment; wound dressing volumes carry tighter precision than emerging chitosan nanofiber matrices where pilot adoption data remains sparse. Forecasts reflect assumptions regarding ECHA regulatory outcomes, hospital infrastructure buildout rates in India and China, and polymer-antimicrobial bonding technology advancement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market