
 Antibacterial Washcloth Market | 2026-2036
Antibacterial Washcloth Market Size, Share, and Industry Trends Forecast 2026-2036
Antibacterial Washcloth Market Outlook
Multi-source procurement is repositioning how hospital systems contract for infection control textiles. Kimberly-Clark Corporation leverages its institutional distribution network to sustain volume commitments with group purchasing organizations. Medline Industries anchors its competitive stance through private-label manufacturing scale across North American distribution centers. GAMA Healthcare specializes in chlorine-based antimicrobial chemistries that differentiate its washcloth portfolio from alcohol-based alternatives.
Antibacterial washcloths are nonwoven or woven textile substrates impregnated with antimicrobial agents such as chlorhexidine gluconate, benzalkonium chloride, or silver ions, manufactured through hydroentanglement or needlepunch processes to achieve specified bacterial log reduction rates against Staphylococcus aureus and Escherichia coli. Disposable product types dominate hospital procurement budgets due to single-use protocols that eliminate cross-contamination risks and simplify waste-stream compliance. Online retail channels represent the fastest-expanding distribution pathway for household and gym end users seeking direct-to-consumer antimicrobial skincare solutions.
FDA oversight of healthcare antiseptics under the Tentative Final Monograph shapes active ingredient selection and label claims for U.S. market participants. EPA registration requirements for antimicrobial-treated articles create additional compliance thresholds for products making public health pest control assertions. Stakeholders must monitor evolving monograph rulings to determine whether reformulation investments or portfolio pruning becomes the more capital-efficient response.
Market Dynamics
Hospital infection control protocols are hardening procurement standards for single-use antimicrobial textiles, compressing supplier qualification timelines while expanding volume commitments to pre-qualified vendors with validated log-reduction testing.
Growth Catalysts
- EPA-registered silver ion chemistry:Manufacturers embedding ionic silver into hydroentangled nonwovens achieve persistent antimicrobial efficacy without chlorhexidine's skin irritation profile, satisfying pediatric and geriatric care requirements.
- Long-term care facility expansion:Skilled nursing operators in the United States are mandating daily chlorhexidine bathing protocols for central line-associated infection prevention, creating institutional pull-through for pre-moistened washcloth formats.
- Chlorine dioxide release systems:GAMA Healthcare's patented fabric technology enables controlled biocide release that outperforms alcohol saturation in sporicidal claims, differentiating acute care offerings.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester staple fiber costs fluctuate with crude oil indices, squeezing nonwoven substrate margins for disposable product lines.
- FDA Tentative Final Monograph uncertainty:Pending reclassification of benzalkonium chloride and chlorhexidine gluconate as Category III ingredients forces manufacturers to maintain dual formulation pipelines without clarity on final monograph requirements.
- Reusable surgical textile substitution:Central sterile processing departments in cost-constrained hospital systems are re-evaluating disposable protocols against validated laundering cycles for antimicrobial-finished woven alternatives.
Strategic Opportunities
- Home health agency channel penetration:Medicare-certified home health services in the United States lack standardized infection prevention supplies, creating first-mover advantage for direct-ship antimicrobial bathing systems.
- Biodegradable substrate innovation:Cellulose-based lyocell fibers combined with bio-based quaternary ammonium compounds address sustainability procurement criteria emerging in California and Washington state hospital systems.
- CMS Hospital-Acquired Condition reduction program:Federal reimbursement penalties for catheter-associated urinary tract infections and central line-associated bloodstream infections drive capital allocation toward evidence-based bathing interventions.
Industry Challenges
- Antimicrobial resistance surveillance integration:Manufacturers must align efficacy claims with CDC NHSN tracking protocols, requiring ongoing clinical validation studies that strain R&D budgets.
- Dual EPA-FDA jurisdictional navigation:Products making both cosmetic cleansing and public health pest control assertions face overlapping registration requirements with inconsistent review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibacterial Washcloth Market |
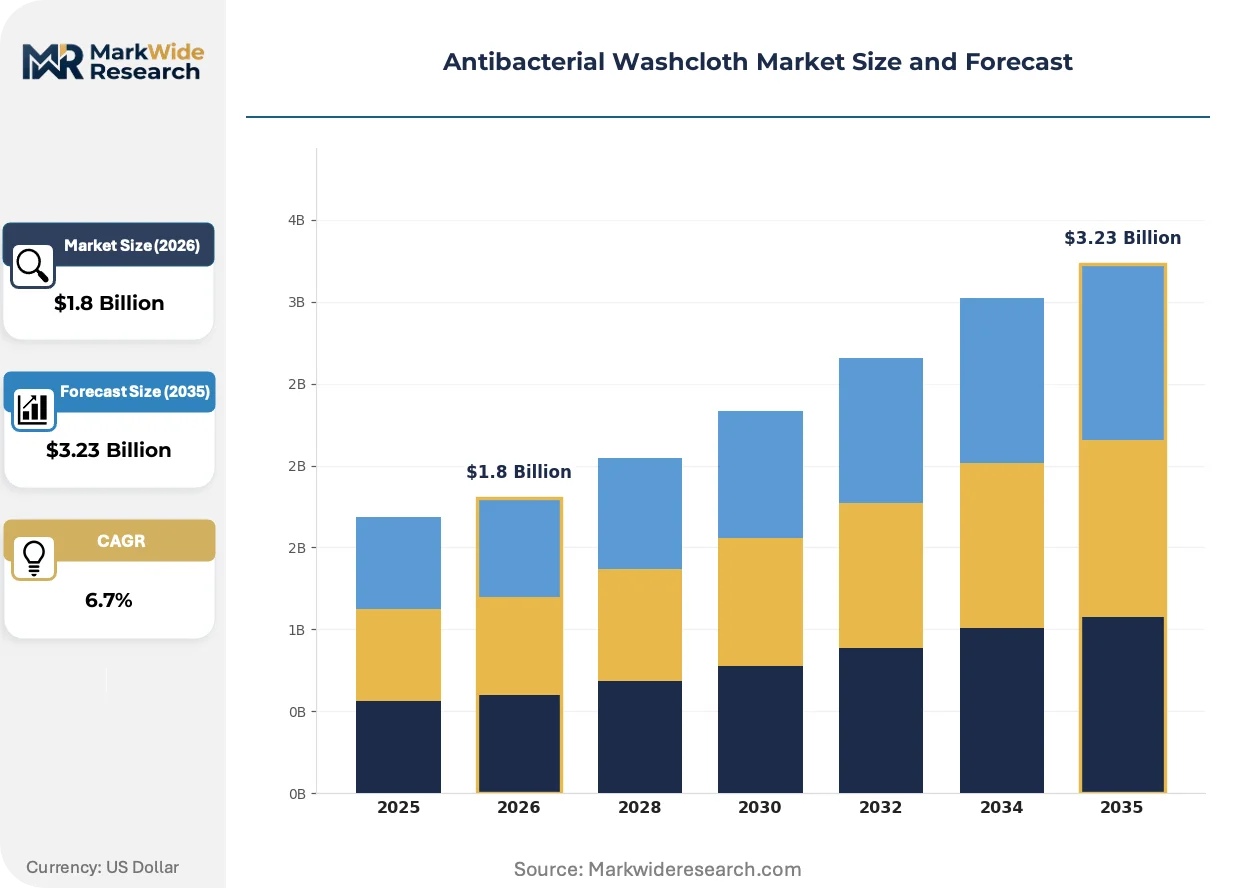
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Microfiber, Bamboo Fabric Composition: Cotton, Polyester, Rayon, Hemp Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores End User: Healthcare Facilities, Households, Schools, Gyms |
| Companies Covered | 3M Company, Kimberly-Clark Corporation, Medline Industries, Stryker, Berk International, TIDI Products, GAMA Healthcare, Clinicept Healthcare, Reynard Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibacterial Washcloth Market Strategic Shifts
Active ingredient selection is bifurcating between legacy chlorhexidine formulations and next-generation metal-ion technologies as regulatory scrutiny intensifies and end-use specifications diverge across care settings.
Silver nanoparticle impregnation is consolidating as the preferred antimicrobial mechanism for neonatal intensive care units and burn centers where cytotoxicity concerns restrict chlorhexidine exposure. Major children's hospital systems in Boston and Philadelphia have completed formulary transitions to silver-ion washcloths for patients under thirty days gestational age. This substrate chemistry is consolidating supplier relationships around vendors with validated biocompatibility testing and FDA 510(k) clearance for compromised skin contact.
REACH authorization requirements for biocidal active substances are forcing European manufacturers to submit chlorhexidine dossiers for renewed approval, with ECHA's Biocidal Products Committee scrutinizing environmental fate data. Industrial consequence includes accelerated reformulation toward silver-based and PHMB alternatives that hold existing Union authorizations. German and French hospital procurement consortia are now requiring proof of active substance compliance status in tender documentation, disadvantaging suppliers dependent on legacy chemistries.
Direct contracting between infection prevention departments and manufacturers is bypassing traditional distributor markups for high-volume bathing protocols. Group purchasing organizations are responding with tiered commitment frameworks that reward sole-source agreements with price protection clauses. This channel restructuring is most visible in the southeastern United States, where Ascension and HCA Healthcare systems have consolidated antimicrobial textile procurement through dedicated supply chain subsidiaries with direct manufacturer negotiation authority.
Antibacterial Washcloth Market Segmentation
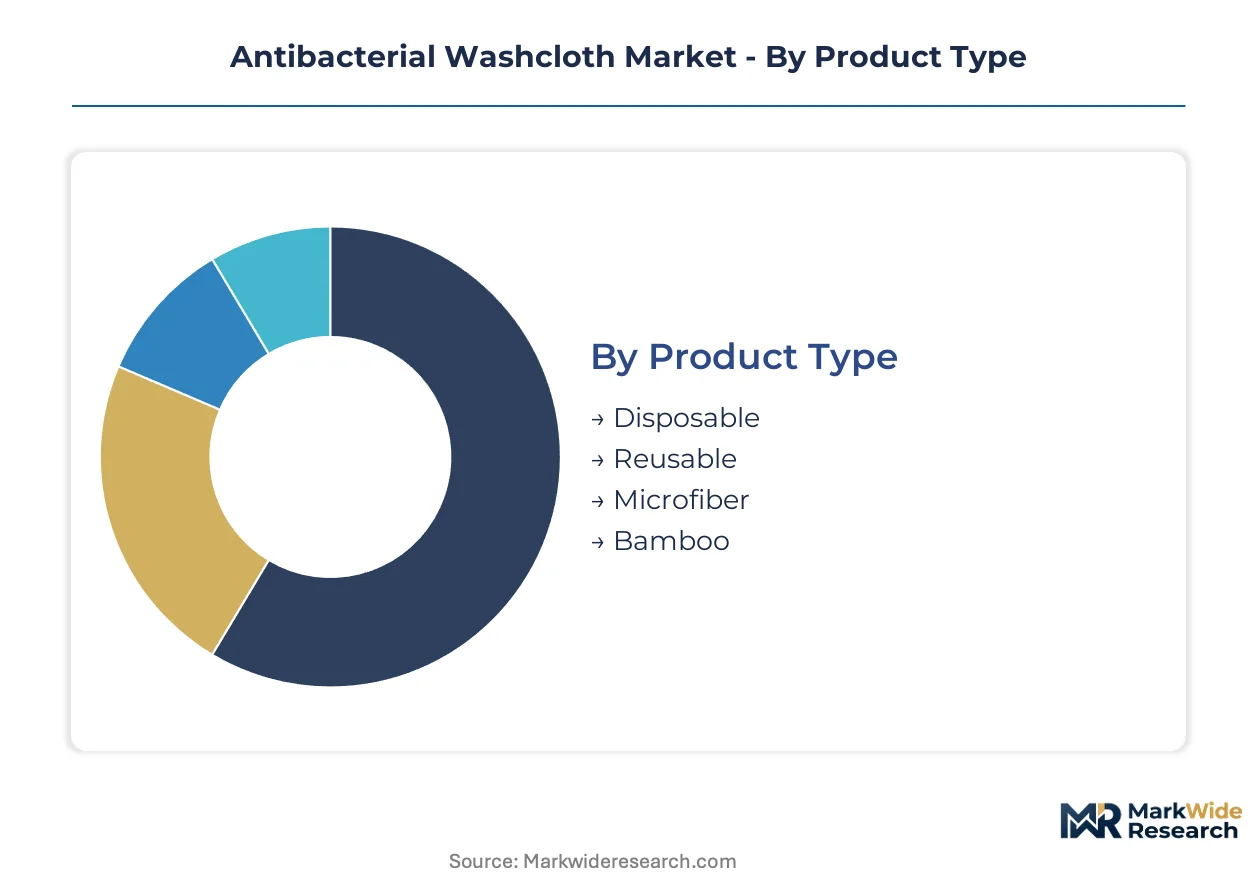
Segmentation in the Antibacterial Washcloth Market reveals how procurement specifications diverge across care settings and consumer channels. Supply concentration patterns within each category determine which manufacturers capture volume commitments from institutional buyers versus retail distributors.
Product Type:
Supply concentration in disposable formats dominates hospital procurement budgets, while reusable alternatives concentrate around specialized laundering service providers and cost-conscious long-term care operators.
- Disposable:Single-use nonwoven substrates impregnated with chlorhexidine or silver-ion chemistries achieve specified log-reduction rates without cross-contamination risk. Hospital infection control protocols in the United States mandate disposable formats for central line-associated infection prevention, with group purchasing organizations consolidating volume around pre-qualified vendors with validated EPA registrations.
- Reusable:Antimicrobial-finished woven textiles withstand validated laundering cycles for multiple patient uses. Cost-constrained hospital systems in the southeastern United States are re-evaluating disposable protocols against central sterile processing alternatives, particularly for non-critical care applications where bioburden requirements permit lower-cost cycling.
- Microfiber:Ultra-fine synthetic filaments enhance mechanical removal of microorganisms during skin cleansing procedures.
- Bamboo:Cellulose-based natural fibers appeal to sustainability-focused procurement criteria in California and Washington state hospital systems.
Today's leader: Disposable. Tomorrow's challenger: Reusable.
Fabric Composition:
Cost tier differentiation separates premium natural fiber offerings from commodity synthetic staples, with raw material volatility compressing margins disproportionately across the polyester supply base.
- Cotton:Natural cellulose fibers provide superior absorbency and skin compatibility for pediatric and geriatric applications. Long-term care facilities in the United States specify cotton substrates for daily chlorhexidine bathing protocols, though supply concentration among agricultural commodity traders exposes procurement to price volatility.
- Polyester:Petroleum-derived synthetic staple dominates hydroentangled nonwoven production for disposable medical textiles. Crude oil index fluctuations directly squeeze manufacturer margins, forcing polyester-dependent suppliers toward volume-commitment contracts with group purchasing organizations to stabilize unit economics.
- Rayon:Regenerated cellulose from wood pulp offers intermediate absorbency between cotton and synthetics.
- Hemp:Bast fiber alternatives gain traction in European markets with stringent biocidal product authorization requirements under REACH.
Cotton commands premium positioning. Polyester maintains volume dominance.
Distribution Channel:
Volume concentration is accelerating through direct contracting arrangements that bypass traditional distributor markups for high-throughput institutional accounts.
- Online Retail:Direct-to-consumer platforms enable household and gym end users to access antimicrobial skincare solutions without intermediary stocking constraints. Medicare-certified home health agencies in the United States lack standardized infection prevention supply chains, creating first-mover advantage for direct-ship bathing systems that bypass traditional medical distribution.
- Supermarkets:Mass-market retail placement concentrates consumer brand visibility for household hygiene applications.
- Pharmacies:Professional recommendation channels drive clinical credibility for over-the-counter antimicrobial claims.
- Specialty Stores:Premium positioning targets athletic and wellness consumer segments with performance-oriented specifications.
Institutional procurement gravitates toward direct manufacturer negotiation. Consumer channels fragment across digital and physical touchpoints.
End User:
Application maturity separates regulated healthcare environments with validated protocols from emerging consumer segments where efficacy claims face less stringent oversight.
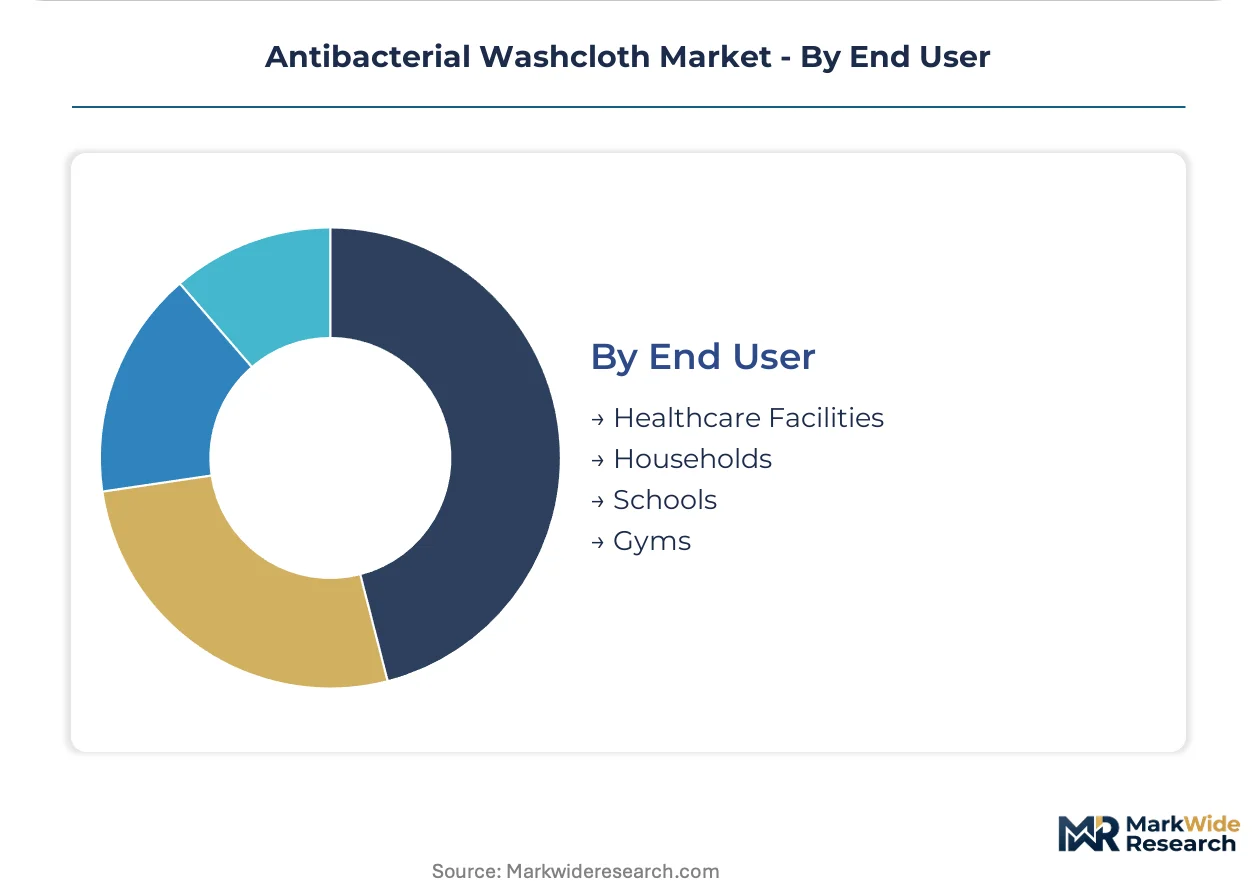
- Healthcare Facilities:Acute care hospitals, skilled nursing facilities, and neonatal intensive care units drive specification-grade demand with documented log-reduction requirements. CMS Hospital-Acquired Condition reduction program penalties for catheter-associated urinary tract infections and central line-associated bloodstream infections direct capital allocation toward evidence-based bathing interventions in United States reimbursement systems.
- Households:Consumer hygiene applications concentrate around immunocompromised individuals and post-surgical recovery protocols.
- Schools:Institutional procurement for infection prevention in educational settings remains underpenetrated relative to healthcare benchmarks.
- Gyms:Athletic facility demand centers on methicillin-resistant Staphylococcus aureus prevention in high-contact equipment environments.
Healthcare Facilities anchor revenue concentration. Households represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States hospital procurement corridor anchors antibacterial washcloth demand through CMS infection prevention mandates and group purchasing organization consolidation. Regulatory divergence across major economies is fragmenting formulation standards and supplier qualification protocols.
United States
Hospital-acquired condition penalty programs from CMS drive capital allocation toward evidence-based bathing interventions in acute care settings. FDA Tentative Final Monograph scrutiny of chlorhexidine and benzalkonium chloride forces manufacturers toward dual-formulation pipelines. The southeastern hospital corridor—Ascension and HCA Healthcare systems—has consolidated procurement through dedicated supply chain subsidiaries with direct manufacturer negotiation authority.
Germany
REACH authorization requirements for biocidal active substances accelerate reformulation toward silver-based and PHMB alternatives with existing Union authorizations. ECHA's Biocidal Products Committee scrutinizes environmental fate data for chlorhexidine dossiers. German hospital procurement consortia now require proof of active substance compliance status in tender documentation, disadvantaging suppliers dependent on legacy chemistries.
United Kingdom
NHS infection prevention protocols standardize pre-moistened washcloth formats for central line-associated infection prevention in acute trusts. MHRA alignment with ECHA biocidal product review timelines creates regulatory coordination with continental suppliers. GAMA Healthcare's chlorine dioxide release systems originate from UK-based R&D clusters serving Commonwealth hospital systems.
Japan
PMDA medical device classification for antimicrobial-impregnated textiles creates distinct registration pathways from cosmetic cleansing claims. METI industrial standards for nonwoven medical textiles specify bacterial log-reduction testing protocols. Osaka-based textile converters supply neonatal intensive care units with silver-ion substrates validated for compromised skin contact.
Australia
TGA medical device regulations for antimicrobial washcloths align with FDA 510(k) clearance requirements for hospital procurement. Private hospital chains in New South Wales and Victoria specify EPA-registered silver ion chemistry for pediatric and geriatric care applications. Sydney-based distributors serve as regional hubs for Pacific island healthcare infrastructure projects.
Antibacterial Washcloth Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable substrate innovation and direct-to-consumer channel penetration. Market structure concentrates around institutional distributors with validated group purchasing organization relationships and private-label manufacturing scale. Three archetypes dominate: multinational healthcare conglomerates with institutional distribution networks, specialized antimicrobial chemistry developers with patented release systems, and regional nonwoven converters with hydroentanglement capacity. Competitive moves center on direct contracting arrangements that bypass traditional distributor markups and portfolio diversification into sustainable fiber alternatives.
Within the multinational tier, Kimberly-Clark Corporation and 3M Company represent institutional distribution archetypes with volume commitments to group purchasing organizations. Medline Industries exemplifies private-label manufacturing scale across North American distribution centers. GAMA Healthcare occupies the specialized chemistry position with chlorine-based antimicrobial differentiation. Stryker anchors the acute care equipment integration vector, while TIDI Products and Berk International represent mid-scale regional fabricators serving secondary hospital systems.
| Leading Market Players |
|---|
| 3M Company |
| Kimberly-Clark Corporation |
| Medline Industries |
| Stryker |
| Berk International |
| TIDI Products |
| GAMA Healthcare |
| Clinicept Healthcare |
| Reynard Health |
| Others |
Value Chain & Pricing Dynamics
Group purchasing organization consolidation in United States hospital systems concentrates procurement leverage among three to five national GPOs, compressing supplier margins and forcing tiered pricing structures that reward volume commitments with price protection clauses.
Pricing Analysis
Petrochemical feedstock pass-through dominates polyester-based nonwoven substrate economics, with crude oil index fluctuations squeezing manufacturer margins unpredictably. Three-tier pricing structure across EPA-registered premium formulations, standard chlorhexidine alternatives, and private-label economy tiers separates validated log-reduction claims from commodity offerings. Pricing pressure stems from CMS reimbursement compression and dual-formulation pipeline maintenance costs under FDA monograph uncertainty. Long-term care facilities exhibit highest price sensitivity due to Medicaid reimbursement constraints, while neonatal intensive care units prioritize biocompatibility certification over unit cost.
Supply Chain Analysis
Polypropylene staple fiber supply rests on petrochemical complexes in the United States, Saudi Arabia, and South Korea, with hydroentanglement nonwoven production concentrated in North Carolina, South Carolina, and Guangdong province. Silver ion chemistry inputs draw from Australian and Peruvian mining operations refined through Japanese and German specialty chemical processors. Single-source vulnerability in EPA-registered active ingredient supply creates qualification bottlenecks for new market entrants. Distribution runs through Medline Industries and McKesson medical-surgical divisions for institutional accounts, while Amazon Business and direct manufacturer portals serve home health agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA-regulated United States formulations and REACH-compliant European alternatives exploits divergent biocidal authorization timelines, with ECHA's chlorhexidine scrutiny accelerating silver-ion adoption ahead of American regulatory alignment.
For Market Incumbents: Deepen backward integration into hydroentanglement nonwoven production to defend margins against petrochemical volatility and polyester price squeezes. Secure captive EPA-registered active ingredient supply through toll manufacturing agreements with specialty chemical processors. Fortify GPO sole-source relationships with clinical validation investments that raise switching costs for hospital procurement committees. For New Entrants and Emerging Players: Enter via Medicare-certified home health agency direct-ship channels, where standardized infection prevention supply chains remain underpenetrated relative to acute care benchmarks. Target biodegradable lyocell substrate development for California and Washington state hospital sustainability procurement criteria. Pursue white-label manufacturing partnerships with regional distributors lacking in-house antimicrobial textile capabilities. For Investors and Strategic Acquirers: Specialized antimicrobial chemistry developers with patented release systems and validated EPA registrations represent the most active acquirer category in this space, with medical device conglomerates seeking differentiated infection prevention portfolios. Long-term viability hinges on regulatory arbitrage capabilities across FDA, EPA, and ECHA jurisdictions. Watch ECHA's Biocidal Products Committee chlorhexidine reauthorization timeline as inflection indicator for silver-ion substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Acceleration | Expedited antimicrobial active substance approval unlocks hospital procurement eligibility before competitors complete dossier submissions. |
| Direct Hospital System Contracting | Bypassing GPO markups through Ascension and HCA Healthcare supply chain subsidiaries captures price protection commitment. |
| Biodegradable Substrate Development | Lyocell fiber innovation with bio-based quaternary ammonium compounds satisfies California hospital sustainability tender requirements. |
| Home Health Channel Penetration | Medicare-certified agency direct-ship bathing systems exploit unstandardized infection prevention supply infrastructure. |
| Silver-Ion Chemistry Scale-Up | Metal-ion technology investment hedges FDA chlorhexidine reclassification risk while capturing pediatric and burn center demand. |
Study Parameters
Direct dialogue with hospital infection prevention officers, GPO contracts managers, antimicrobial textile R&D directors, and EPA registration consultants grounded qualitative insights in procurement workflow realities. Secondary validation drew from FDA Tentative Final Monograph filings, EPA antimicrobial pesticide registration databases, CMS Hospital-Acquired Condition penalty program documentation, and ECHA biocidal product authorization status reports. Bottom-up unit volume modeling across care settings triangulated against top-down market size estimates from trade flow analysis.
Top-down macroeconomic drivers and bottom-up segment-specific demand patterns converged across the projection horizon. Segmentation dimensions modeled include product format (disposable versus reusable), active ingredient chemistry (chlorhexidine, silver-ion, chlorine dioxide, quaternary ammonium), fabric composition (polyester, cotton, lyocell), and end-use setting (acute care, long-term care, home health, consumer). CAGRs derived from log-linear regression of historical procurement volume trends adjusted for regulatory event impacts. CMS reimbursement penalty expansion and REACH authorization timelines served as key forecast sensitivity inputs.
The model holds under stable FDA monograph timelines and ECHA authorization continuity; deviation in chlorhexidine reclassification severity or petrochemical price volatility spikes would shift volume trajectories. Forecasts reflect documented assumptions regarding hospital infection control protocol persistence and GPO consolidation momentum. A small set of named triggers—EPA registration backlog clearance, ECHA chlorhexidine environmental fate ruling, and CMS condition-specific penalty expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Surgical Drapes Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Europe Adult Diaper Market