
 Intestinal Wash Bags Market | 2026-2036
Intestinal Wash Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Intestinal Wash Bags Market Analytics
Home care patients are reorganizing procurement patterns for intestinal wash bags, shifting volume away from acute facilities toward direct-to-patient channels. Coloplast anchors Nordic and North European markets through specialized ostomy care portfolios. Medtronic leverages its surgical ecosystem to secure hospital contract access. Flexicare Medical competes on manufacturing scale across PVC and silicone product lines.
Intestinal wash bags are closed-collection pouches, typically fabricated from medical-grade polyethylene, PVC, or silicone, designed to receive effluent from colostomy or ileostomy stomas via secure flange attachment; they incorporate odor-barrier films and drainable or closed-tail configurations for hygienic management. Disposable bags dominate hospital procurement due to infection control protocols, while reusable silicone variants capture margin pools in home care where long-term cost efficiency matters. Material selection increasingly favors latex-free formulations as allergen sensitivity reshapes clinical purchasing criteria across rehabilitation centers and clinics.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for manufacturers seeking multi-jurisdiction placement. ISO 10993 biocompatibility testing and REACH chemical compliance add layer costs that favor mid-cap specialists with established regulatory infrastructure. Stakeholders must monitor reimbursement code consolidation in Medicare and national health systems, as payment policy directly determines patient out-of-pocket exposure and category growth velocity.
Market Dynamics
Home care patients are reorganizing procurement patterns for intestinal wash bags, shifting volume away from acute facilities toward direct-to-patient channels. Coloplast anchors Nordic and North European markets through specialized ostomy care portfolios. Medtronic leverages its surgical ecosystem to secure hospital contract access. Flexicare Medical competes on manufacturing scale across PVC and silicone product lines.
Growth Catalysts
- FDA 510(k) clearance requirements:These regulatory pathways are streamlining biocompatibility documentation for polyethylene and silicone formulations, accelerating market access for compliant manufacturers in the United States.
- Home care adoption:Elderly patients managing colostomy and ileostomy routines are driving demand for reusable silicone variants with odor-barrier films and drainable configurations.
- EU MDR technical documentation:Stricter sterility assurance obligations are favoring mid-cap specialists with established ISO 10993 testing infrastructure across Germany and France.
Market Restraints
- REACH chemical compliance costs:Layered testing expenditures for PVC and latex-free formulations are compressing margins for smaller manufacturers without captive laboratory capacity.
- Reimbursement code consolidation:Medicare payment policy revisions are directly determining patient out-of-pocket exposure in the United States, creating demand volatility.
- Input material concentration:Medical-grade polyethylene supply chains cluster among specialized polymer producers in Germany and Japan, exposing converters to price pass-through risk.
Strategic Opportunities
- Japan's aging demographic:Established reimbursement pathways and expanding elderly populations create sustained clinical utilization potential for closed-collection pouch systems.
- Direct-to-patient channel innovation:E-commerce platforms and subscription models are capturing home care volume previously routed through hospital discharge coordinators.
- ISO 10993 biocompatibility convergence:Harmonized testing standards across FDA and EU MDR jurisdictions are enabling single-documentation multi-market placement for prepared manufacturers.
Industry Challenges
- Regulatory talent scarcity:Qualified professionals capable of navigating simultaneous FDA 510(k) and EU MDR technical file preparation command premium compensation, constraining mid-tier firm expansion.
- Legacy system integration:Hospital procurement departments require EDI connectivity and inventory management interoperability that smaller manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intestinal Wash Bags Market |
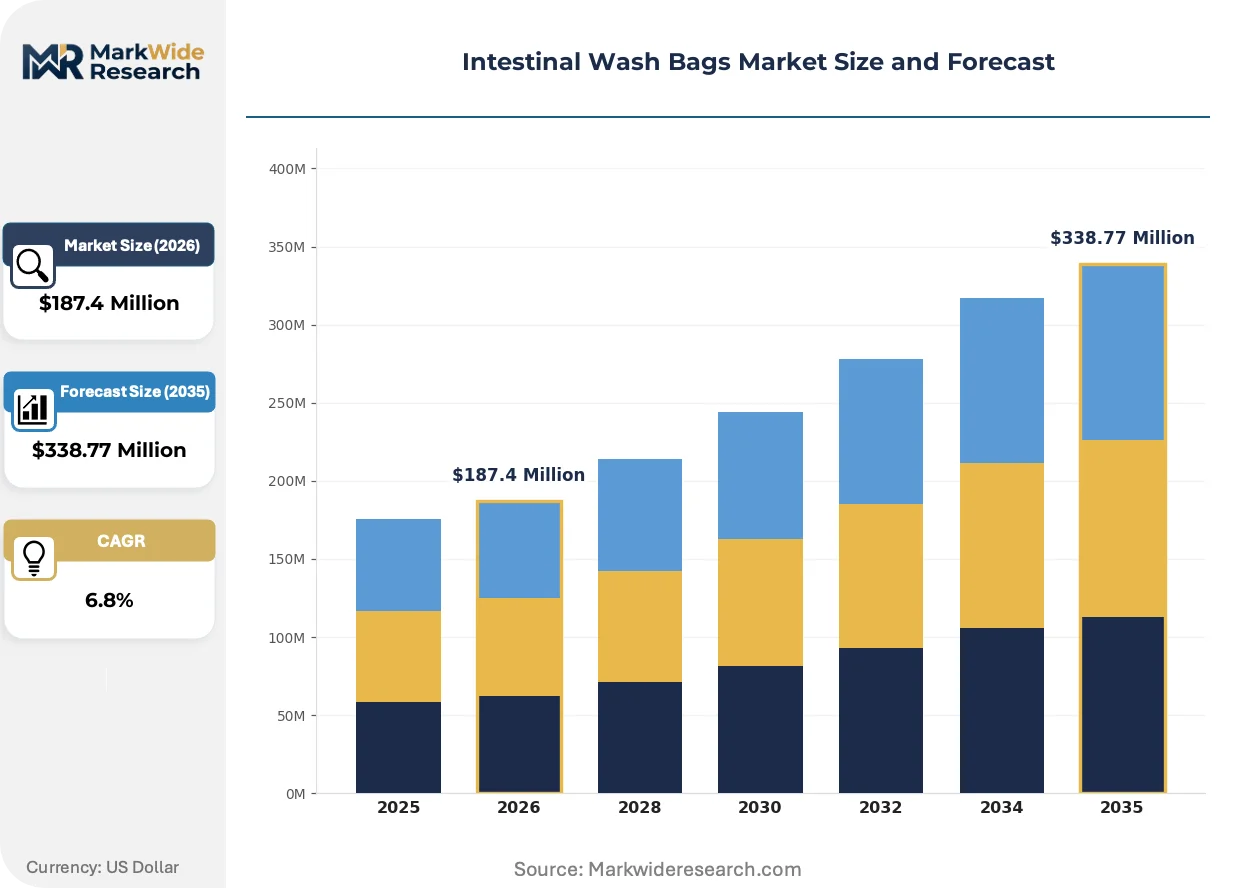
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Bags, Reusable Bags, Sterilized Bags, Customized Bags Material: Polyethylene, PVC, Silicone, Latex End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesalers |
| Companies Covered | Medtronic, Medline, Flexicare Medical, Coloplast, Trustin Medical, Microbar, Seeking Health, Atilim Saglik, Jshuatai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intestinal Wash Bags Market Evolving Landscape
Material science advances and regulatory harmonization efforts are compressing product development timelines while fragmenting competitive positioning across disposable and reusable segments. Three developments warrant particular attention.
Silicone elastomer formulations with integrated activated carbon odor-barrier layers are bifurcating the home care segment. Rehabilitation centers and long-term care facilities in Germany and Japan are adopting these premium variants for 30-day reuse cycles. This technology is bifurcating price architecture between acute-care disposable procurement and chronic-care capital-equipment models.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports for all Class I sterile devices including intestinal wash bags. Manufacturers must demonstrate biological safety through ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization testing. Nordic and North European markets are responding fastest, with Danish and Swedish notified bodies processing submissions at accelerated rates.
Patient self-management education programs are shortening replacement cycles for flange attachment systems. Ostomy nurses in United States home health agencies are training beneficiaries on earlier pouch replacement to prevent peristomal complications. This behavioral shift is most visible in Medicare Advantage populations where capitated payments align provider incentives with prevention.
Intestinal Wash Bags Market Segmentation
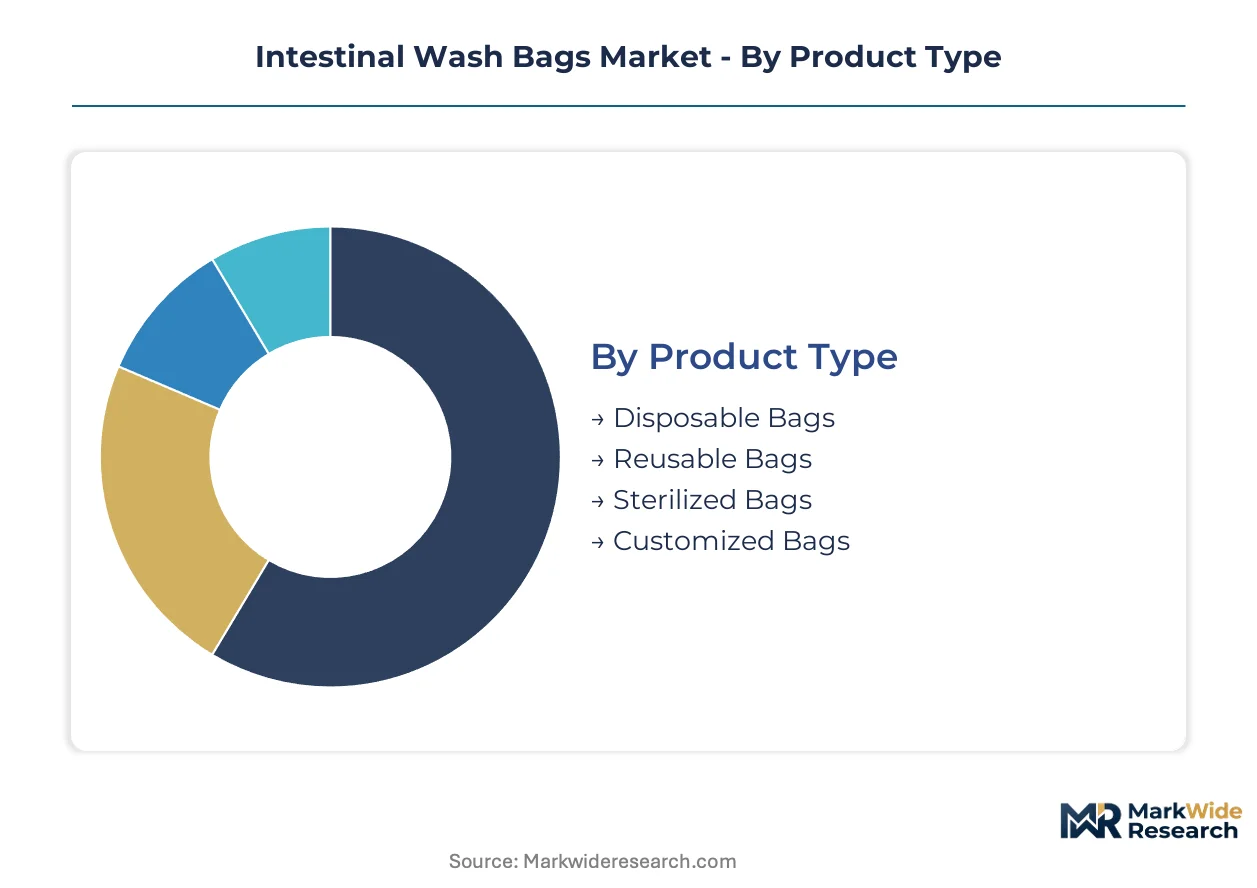
Intestinal wash bag procurement splits across clinical and consumer channels with divergent material specifications and sterility requirements. Each segment carries distinct regulatory documentation burdens and reimbursement eligibility criteria that reshape competitive positioning.
Product Type:
FDA 510(k) clearance pathways and EU MDR technical documentation obligations create tiered market access barriers across product categories, with sterile variants demanding clinical evaluation reports while non-sterile formats navigate lighter conformity routes.
- Disposable Bags:Single-use polyethylene or PVC pouches with integrated odor-barrier films dominate acute care procurement. Hospital infection control protocols in the United States and Germany mandate disposability, with Medicare reimbursement codes favoring bulk purchase arrangements through medical supply distributors.
- Reusable Bags:Medical-grade silicone elastomer formulations withstand 30-day cleaning cycles and appeal to home care patients managing long-term colostomy routines. German rehabilitation centers and Japanese elderly care facilities are expanding adoption of these premium variants despite higher upfront capital requirements.
- Sterilized Bags:Gamma-irradiated or ethylene oxide-sterilized units carry ISO 11135 or ISO 11137 validation documentation for surgical theater deployment.
- Customized Bags:Patient-specific flange geometries and stoma aperture sizing serve pediatric or post-surgical anatomical variations.
Established volume favors Disposable Bags; emerging adoption favors Reusable Bags.
Material:
REACH chemical compliance costs and ISO 10993 biocompatibility testing expenditures stratify manufacturer capabilities across polymer categories.
- Polyethylene:Low-density and linear low-density formulations provide cost-efficient moisture barriers for high-volume disposable production. German polymer converters supply medical-grade resin to contract manufacturers serving NHS England and French hospital procurement consortiums.
- PVC:Plasticized polyvinyl chloride offers weldability and transparency for drainable tail configurations. Supply chain concentration among specialized European compounders exposes converters to diethylhexyl phthalate regulatory restrictions under REACH Annex XVII.
- Silicone:Platinum-cured elastomers deliver biocompatibility and thermal stability for extended reuse cycles.
- Latex:Natural rubber formulations persist in emerging market price-sensitive segments despite allergen labeling requirements.
Polyethylene captures the highest shipment volumes; Silicone climbs the fastest on home care premiumization.
End User:
Reimbursement pathway maturity and patient acuity levels determine product specification intensity across care settings.
- Hospitals:Acute surgical wards and oncology units demand sterile, closed-collection systems with EDI-enabled inventory tracking. German DRG-based payment systems and Japanese diagnosis-procedure combination frameworks standardize procurement around disposable polyethylene formats.
- Home Care:Elderly ostomy patients and family caregivers prioritize odor control and discreet portability over clinical feature density. United States Medicare Advantage capitation models align provider incentives with preventive pouch replacement education.
- Clinics:Outpatient wound care and stoma therapy centers balance infection protocols with patient throughput efficiency.
- Rehabilitation Centers:Post-acute skilled nursing facilities manage transition from hospital-supplied disposables to patient-owned reusable systems.
Hospitals retain procurement volume leadership; Home Care gains share fastest on aging demographic expansion.
Distribution Channel:
Channel margin structures and patient data privacy requirements fragment route-to-market strategies.
- Direct Sales:Manufacturer field representatives secure multi-year hospital system contracts with integrated EDI and consignment inventory management. Medtronic and Coloplast deploy dedicated ostomy care specialists to United States integrated delivery networks and German Klinikverbünde.
- Online Retail:E-commerce platforms and subscription services capture home care patients seeking discretion and auto-replenishment convenience. HIPAA-compliant patient portals enable direct billing to Medicare Advantage plans.
- Medical Supply Stores:Brick-and-mortar durable medical equipment dealers serve walk-in ostomy patients with immediate fitting needs.
- Wholesalers:Regional distributors aggregate fragmented clinic and nursing home demand.
Direct Sales commands institutional contract value; Online Retail expands most quickly on patient self-management trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polyethylene converters cluster among specialized polymer producers in Germany and Japan, exposing downstream manufacturers to concentrated input pricing power across North America, Europe, and Asia-Pacific demand centers.
United States
Medicare Advantage capitation models and aging ostomy patient populations sustain clinical utilization of closed-collection pouch systems. FDA 510(k) clearance pathways streamline biocompatibility documentation for silicone and polyethylene formulations entering hospital procurement channels. Greater Boston and Pacific Northwest medical device clusters host contract manufacturers serving integrated delivery networks with EDI-enabled inventory systems.
Germany
DRG-based hospital payment systems and expanding rehabilitation center networks standardize procurement around disposable formats for acute care transitions. EU MDR Article 10 technical documentation mandates ISO 10993-5 cytotoxicity validation for all Class I sterile devices entering German Klinikverbünde. Bavaria and North Rhine-Westphalia polymer converters supply medical-grade resin to NHS England and French hospital consortiums.
Japan
Diagnosis-procedure combination reimbursement frameworks and elderly care facility expansion create sustained demand for premium reusable silicone variants. PMDA consultation procedures align with METI industrial standards for platinum-cured elastomer biocompatibility. Kanto and Kansai manufacturing belts concentrate medical device production for domestic consumption and Southeast Asian export.
United Kingdom
NHS England bulk purchase arrangements and stoma therapy nursing programs drive volume through medical supply distributors. REACH Annex XVII phthalate restrictions shape PVC formulation specifications for drainable tail configurations. Midlands and North England industrial zones host converters serving clinic and nursing home procurement through regional wholesaler networks.
Intestinal Wash Bags Market Competitive Landscape
Concentration sits with diversified medical device conglomerates anchoring hospital contract access alongside specialized ostomy care portfolios. Mid-cap silicone fabricators compete on manufacturing scale and regulatory infrastructure depth. Three archetypes dominate: surgical ecosystem integrators leveraging procedure volume relationships; dedicated ostomy care specialists with direct-to-patient channel expertise; and polymer converters competing on material science differentiation. M&A activity targets ISO 10993 testing capabilities and EDI connectivity infrastructure. Geographic expansion into Japanese and German reimbursement markets represents the primary competitive move.
Within the surgical ecosystem tier, Medtronic exemplifies hospital contract leverage through integrated delivery network relationships. Coloplast and Flexicare Medical occupy positions spanning specialized ostomy portfolios and manufacturing scale across PVC and silicone product lines. These three entities represent divergent strategic anchors: procedure-driven institutional access, dedicated chronic care expertise, and polymer conversion scale.
| Leading Market Players |
|---|
| Medtronic |
| Medline |
| Flexicare Medical |
| Coloplast |
| Trustin Medical |
| Microbar |
| Seeking Health |
| Atilim Saglik |
| Jshuatai |
| Others |
Value Network & Pricing Analysis
Silicone elastomer substitution for PVC in premium reusable pouches simultaneously redraws procurement geography toward German and Japanese polymer converters and compresses margin structures for legacy polyethylene-dependent manufacturers serving acute-care contracts. This material transition concentrates pricing power among platinum-cured elastomer specialists while exposing PVC-dependent competitors to REACH Annex XVII phthalate compliance cost pass-throughs.
Pricing Analysis
Volume-discount tiering structures separate hospital system GPO contracts from home care direct-to-patient subscriptions, with acute-care disposable polyethylene formats commanding lowest per-unit pricing at scale and silicone reusable variants sustaining premium positioning through 30-day lifecycle economics. Price differentiation rests on ISO 10993 biocompatibility certification tier and odor-barrier film integration density. Cost compression in standard disposable tiers intensifies as Medicare reimbursement code consolidation squeezes distributor margins. Home care patients exhibit highest price sensitivity to upfront capital outlay, while hospital procurement committees prioritize total cost of ownership and infection control compliance over per-unit expenditure.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement through EDI-enabled consignment arrangements, whereas home care channels favor strategic stockpile behavior via subscription auto-replenishment to mitigate stoma supply anxiety. Geographic supply concentration centers on Germany, Japan, and the United States for medical-grade polyethylene resin, platinum-cured silicone elastomers, and activated carbon odor-barrier films. Raw material dependencies draw from specialized polymer producers, medical-grade adhesive compounders, and gamma-irradiation sterilization facilities. Single-source vulnerability runs through German Klinikverbünde supply contracts anchored to Bavarian resin converters. Distribution runs through medical supply distributors for institutional volume and HIPAA-compliant e-commerce platforms for direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intestinal wash bags market sits in early-cycle expansion as home care adoption among aging ostomy patients outpaces acute-care volume displacement, with direct-to-patient channel innovation representing the primary penetration tailwind.
For Market Incumbents: Shield hospital contract positions by deepening ISO 10993-5 cytotoxicity documentation capabilities and securing multi-year GPO agreements before EU MDR Article 10 technical file requirements fully phase in. Threats from mid-cap silicone specialists with established regulatory infrastructure demand backward integration into platinum-cured elastomer production or captive supply arrangements with German and Japanese polymer converters. Channel control through EDI connectivity investment remains essential to defend against e-commerce platform disintermediation. For New Entrants and Emerging Players: Anchor in Japan's elderly care facility expansion and United States Medicare Advantage capitation markets where reimbursement pathway maturity reduces patient out-of-pocket friction. The most penetrable segment comprises reusable silicone variants for 30-day home care cycles, currently underserved by incumbent disposable-focused portfolios. A direct-to-patient subscription go-to-market angle bypasses hospital procurement gatekeepers and captures lifetime value through auto-replenishment retention economics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with captive ISO 10993 testing infrastructure and established FDA 510(k) clearance track records. Long-term viability over the next decade hinges on regulatory documentation depth rather than manufacturing scale alone. Acquisition target archetypes include silicone elastomer fabricators with EU MDR notified body relationships and e-commerce platforms with HIPAA-compliant patient billing systems. The signal to watch is Medicare reimbursement code consolidation velocity in the United States, which would accelerate margin compression and trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | ISO 10993-5 cytotoxicity validation accelerates German and French notified body submissions. |
| Direct-to-Patient Subscription Launch | HIPAA-compliant auto-replenishment captures home care volume from hospital discharge coordinators. |
| Silicone Elastomer Backward Integration | In-house platinum-cured production secures margin against German polymer converter pricing power. |
| Hospital System EDI Partnership | Consignment inventory interoperability locks in multi-year GPO contract renewals. |
| Japan PMDA Consultation Pathway | METI-aligned biocompatibility standards open reimbursement-eligible elderly care facility procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ostomy care nurses, hospital GPO contracts managers, biomedical engineers, home health agency administrators, and medical supply distributors. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, CMS Medicare reimbursement code filings, and hospital procurement consortium contract disclosures. Bottom-up shipment estimates by product type and material were triangulated against top-down spending flows by end-user channel.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning product type (disposable, reusable, sterilized, customized), material (polyethylene, PVC, silicone, latex), end user (hospitals, home care, clinics, rehabilitation centers), and distribution channel (direct sales, online retail, medical supply stores, wholesalers). CAGRs were derived from regression-adjusted trend extrapolation incorporating reimbursement policy elasticity and demographic aging curves. Industry-specific forecast inputs included stoma surgery incidence rates and Medicare Advantage enrollment penetration.
Decision-makers should treat outputs as directional under stable reimbursement pathway assumptions; material deviation would warrant model refresh. Specific risk factors include REACH chemical compliance cost escalation, FDA 510(k) clearance timeline extension, and polymer supply concentration disruptions. Revision becomes warranted when Medicare payment policy volatility crosses threshold uncertainty bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Absorbent Mats Market