
 Global Digital Identity Solutions Market | 2026-2036
Global Digital Identity Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Identity Solutions Market Foresight
Channel architecture for enterprise identity software is fragmenting as direct sales, systems integrators, and cloud marketplaces compete for procurement budgets. Thales Group leverages its smart card and biometrics heritage to anchor high-assurance government contracts across Europe and the Middle East. IBM Corporation competes through Red Hat OpenShift integrations that extend hybrid identity governance into regulated financial workflows. Microsoft Corporation dominates consumer and enterprise segments through Azure Active Directory's embedded position within Office 365 ecosystems.
Digital identity solutions encompass hardware, software, and services that validate, authenticate, and manage individual or entity credentials across networked environments, typically processing verification through cryptographic protocols, biometric templates, or federated trust frameworks with latency requirements under 500 milliseconds for real-time transactions. Biometric Authentication leads solution type revenue due to fingerprint and facial recognition deployments in mobile banking, while Identity Verification grows fastest among application layers as remote onboarding mandates expand. Cloud-Based deployment captures the largest margin pool among delivery modes, though Hybrid architectures sustain premium pricing in defense and critical infrastructure sectors where data residency rules apply.
The EU AI Act classifies biometric identification as high-risk, forcing providers to maintain conformity assessments and human oversight protocols before market access. India's UIDAI governs Aadhaar authentication APIs, China's SAMR enforces national cryptography standards for citizen identity systems, and the US NIST Digital Identity Guidelines shape federal procurement specifications through SP 800-63 revision cycles. Stakeholders must monitor divergence between regional trust frameworks and interoperability certifications to avoid architectural lock-in that fragments addressable market segments.
Market Dynamics
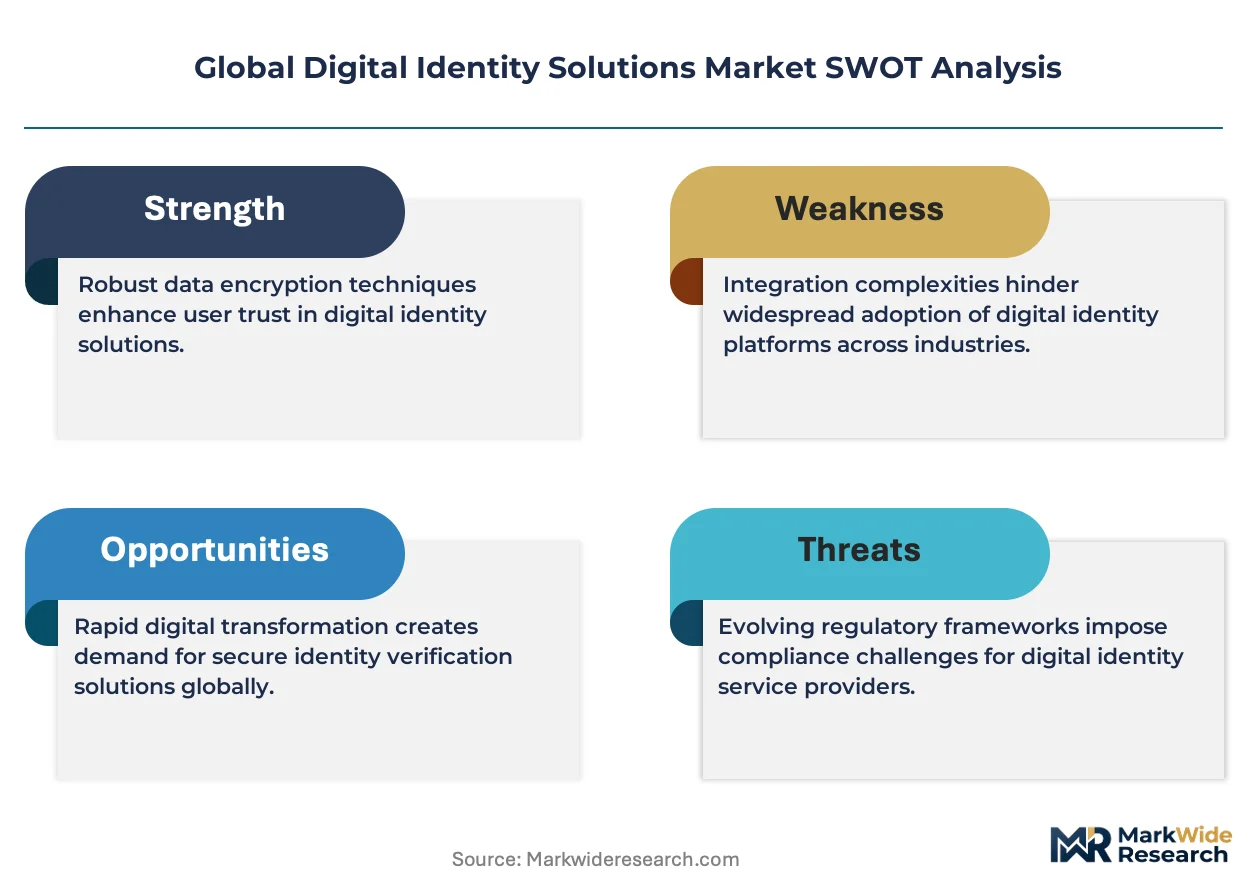
The EU AI Act's high-risk classification for biometric identification is forcing architectural redesigns across identity infrastructure, compressing deployment timelines while elevating compliance costs for real-time authentication systems.
Growth Catalysts
- Remote onboarding mandates:Financial regulators in Singapore, India, and Brazil now require video-KYC protocols for digital account opening, expanding identity verification API volumes in mobile banking infrastructure.
- eIDAS 2.0 framework:The European Union's revised electronic identification standards mandate cross-border wallet interoperability, creating procurement pull for qualified trust service providers.
- Biometric template protection:Fingerprint liveness detection and facial anti-spoofing algorithms are hardening mobile payment rails against synthetic identity fraud.
Market Restraints
- Specialized silicon shortages:Secure element manufacturing capacity for smart cards concentrates in East Asian foundries, creating 18-24 month lead times for high-assurance credential batches.
- Data residency fragmentation:Sovereign cloud mandates in Germany, France, and Saudi Arabia prevent unified identity architectures, forcing redundant infrastructure deployments.
- Algorithmic bias liability:The EU AI Act's conformity assessment requirements for demographic performance parity add 12-18 months to facial recognition product certification cycles.
Strategic Opportunities
- Decentralized identity convergence:Verifiable credentials and mobile driver's licenses are merging with blockchain-based self-sovereign identity pilots in Canada and Estonia.
- Voice biometrics in contact centers:Passive authentication during customer service calls remains underdeployed in healthcare and insurance verticals outside North America.
- Edge AI inference:On-device facial matching without cloud transmission is opening defense and critical infrastructure segments previously blocked by air-gap requirements.
Industry Challenges
- Legacy directory migration:Financial institutions running 15-20 year-old LDAP architectures face 3-5 year modernization timelines to support passwordless FIDO2 standards.
- Cross-border trust framework negotiation:Bilateral mutual recognition agreements between national eID schemes require 24-36 month diplomatic and technical alignment processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Identity Solutions Market |
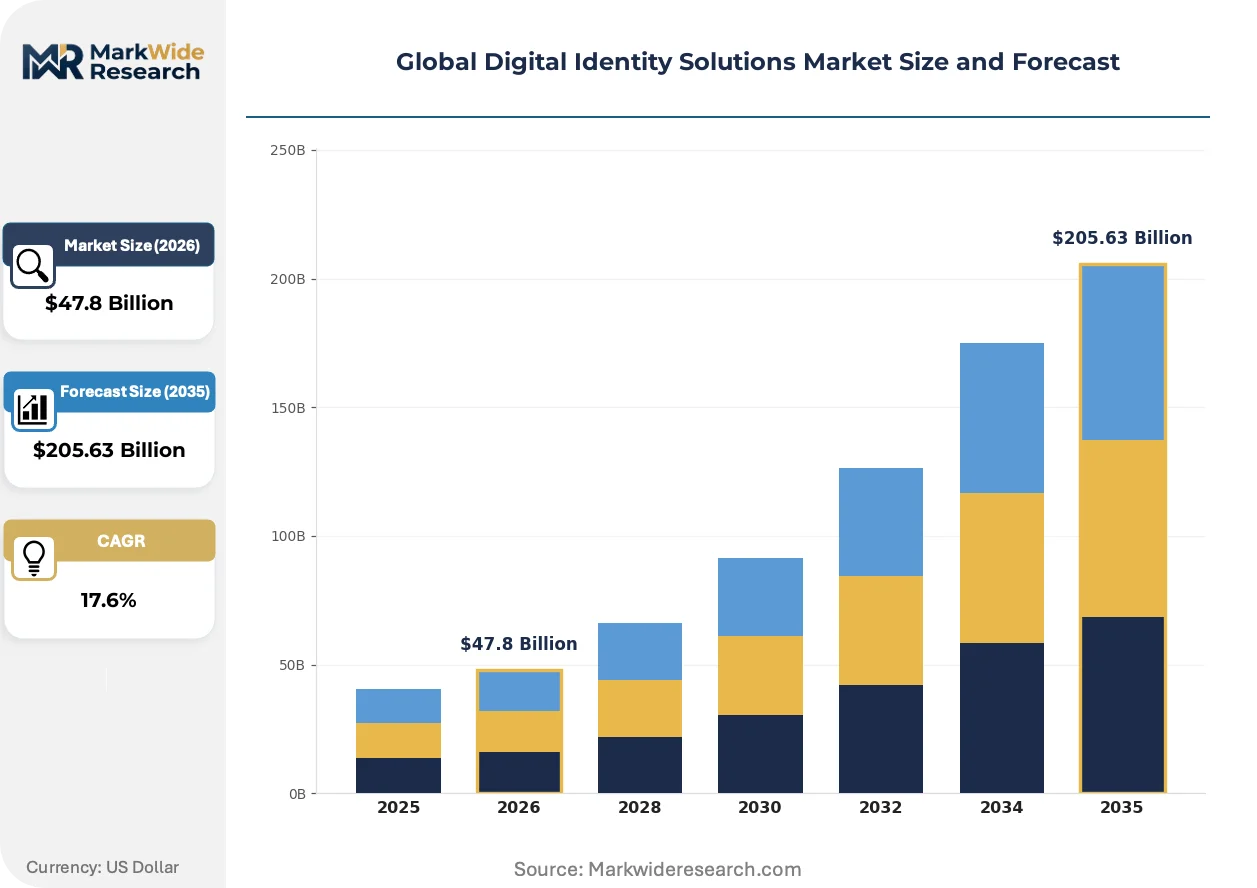
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $205.63 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Biometric Authentication, Multi-Factor Authentication, Identity Verification, Access Management, Identity Governance Application: E-Government, Financial Services, Telecommunications, E-Commerce, Travel & Hospitality End User Industry: Banking, Insurance, Retailers, Education, Public Safety Deployment Mode: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services |
| Companies Covered | Thales Group, NEC Corporation, IDEMIA, Samsung SDS, IBM Corporation, Microsoft Corporation, ForgeRock, Experian plc, TELUS Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Identity Solutions Market Shifts & Advancements
Identity infrastructure is decoupling from hardware-bound roots, with cryptographic verification moving toward portable credentials and continuous authentication models that reduce friction in high-velocity transaction environments.
Software-based secure enclaves are virtualizing hardware trust anchors previously embedded in dedicated smart cards and TPM modules. Cloud providers and handset OEMs are integrating these capabilities at silicon level, enabling FIDO2 and passkey deployments without separate security hardware purchases. This is virtualizing the traditional smart card supply chain, compressing manufacturing value capture toward semiconductor IP licensors.
The EU AI Act's high-risk system classification is mandating human-in-the-loop oversight for biometric identification in public spaces. Law enforcement and border control procurement specifications now require explainable AI documentation and demographic performance testing. European integrators are responding by segmenting product lines between regulated high-assurance tiers and consumer-grade offerings with reduced capability claims.
Enterprise buyers are consolidating identity vendor relationships from point solutions toward platform contracts spanning workforce, customer, and machine identities. Systems integrators in Germany and Australia are capturing margin by bundling implementation services with multi-year SaaS commitments. This vendor consolidation pattern is most visible in healthcare and energy verticals where cyber insurance underwriters now mandate unified identity governance coverage.
Global Digital Identity Solutions Market Segmentation
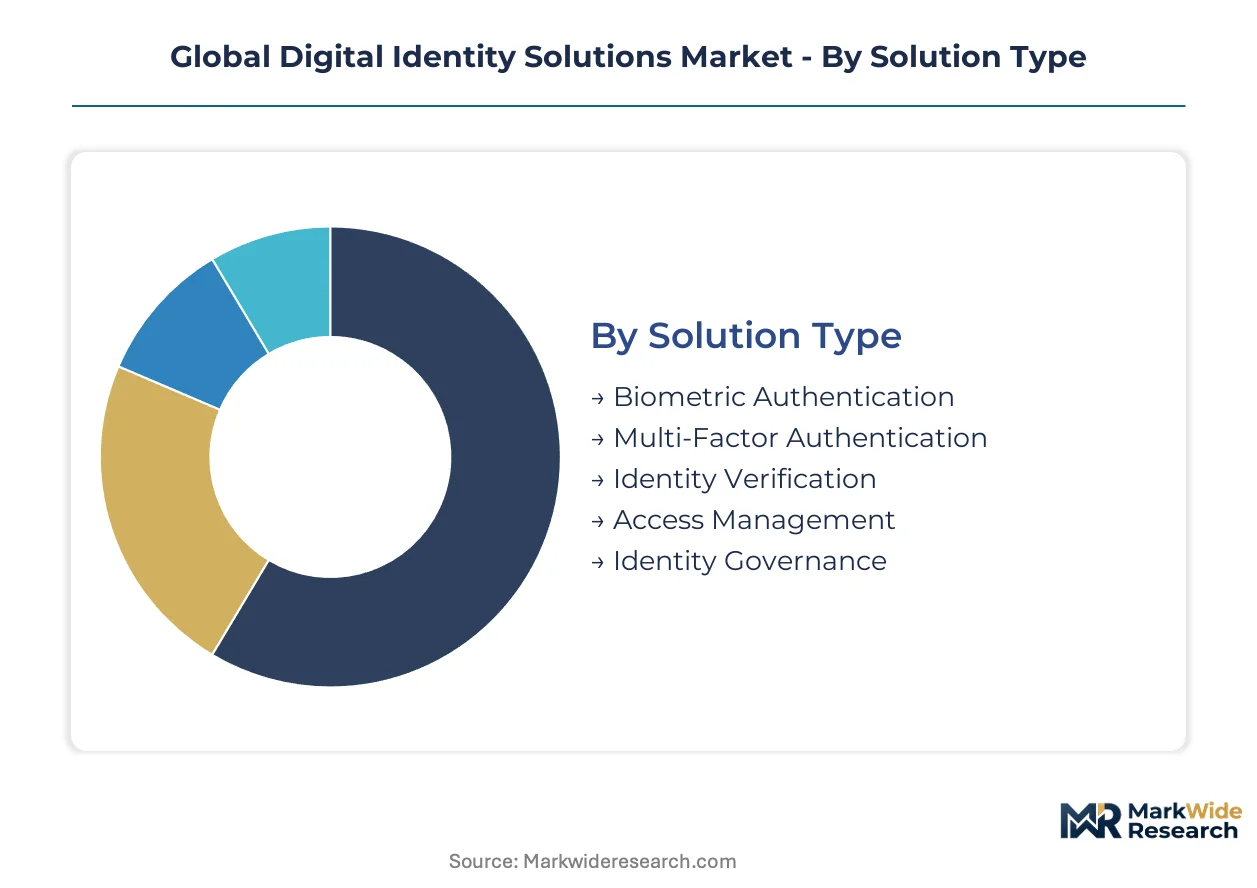
Architectural choices in digital identity infrastructure create divergent investment cycles across solution layers, with biometric hardware requiring multi-year refresh schedules while cloud-native verification APIs iterate quarterly. Procurement patterns fragment between regulated sectors demanding air-gapped deployments and consumer-facing platforms optimizing for frictionless onboarding velocity.
Solution Type:
Biometric Authentication and Identity Verification turn over fastest as algorithm vendors release liveness detection updates every 90-120 days, while Identity Governance platforms lock enterprises into 5-7 year implementation roadmaps.
- Biometric Authentication:Fingerprint, facial, and iris recognition systems process verification through encrypted template matching with sub-500 millisecond latency requirements. India's UIDAI mandates drive Aadhaar-linked fingerprint deployments across rural banking correspondent networks, while EU AI Act conformity assessments slow facial recognition rollouts in public infrastructure.
- Identity Verification:Document-centric and biometric liveness checks anchor remote customer onboarding workflows for mobile banking and digital lending. Brazil's Central Bank video-KYC requirements and Singapore MAS guidelines are expanding API call volumes in Southeast Asian neobank infrastructure.
- Multi-Factor Authentication:Combines possession, knowledge, and inherence factors through FIDO2, TOTP, and push notification protocols. FIDO Alliance certification programs standardize interoperability across handset OEMs and enterprise identity providers.
- Access Management:Session control, privilege elevation, and adaptive risk engines govern workforce and machine identity interactions. Zero-trust architecture mandates from US federal agencies and German BSI specifications are accelerating cloud-native policy engine procurement.
- Identity Governance:Lifecycle management, access certification, and compliance reporting platforms integrate with HR systems and SIEM tools. SOX, GDPR, and sectoral banking regulations enforce quarterly attestation cycles that sustain multi-year platform contracts.
Biometric Authentication dominates installed base. Identity Verification is where expansion concentrates.
Application:
Financial Services and E-Government absorb premium pricing for high-assurance credentials, while E-Commerce and Travel & Hospitality prioritize conversion-optimized friction reduction.
- E-Government:National identity wallets, digital driver's licenses, and tax authentication portals require qualified trust service provider certification under eIDAS 2.0. Estonia's X-Road interoperability layer and India's DigiLocker ecosystem demonstrate divergent architectural approaches to citizen credential federation.
- Financial Services:KYC/AML compliance, account opening, and transaction authentication anchor the highest identity verification spend per customer. Brazil's PIX instant payment rails and India's UPI stack embed biometric verification at transaction initiation, compressing fraud windows.
- Telecommunications:SIM registration, device activation, and fraud prevention for mobile money services. Pakistan's PTA biometric SIM verification mandate and Nigeria's NCC regulations demonstrate subscriber identity enforcement patterns in emerging markets.
- E-Commerce:Account takeover prevention, age verification, and buyer-seller trust scoring. PSD2 Strong Customer Authentication requirements in Europe and emerging open banking frameworks in Australia shape checkout friction tradeoffs.
- Travel & Hospitality:Biometric boarding, hotel check-in, and loyalty program authentication. IATA One ID pilots at Singapore Changi and Dubai International anchor cross-border facial recognition corridor development.
E-Government commands the longest procurement cycles. Financial Services delivers the steepest expansion trajectory.
End User Industry:
Banking and Insurance concentrate high-assurance biometric deployments, while Retailers and Education lag in passwordless migration due to fragmented IT ownership.
- Banking:Video-KYC, behavioral biometrics, and transaction signing dominate technology refresh budgets. RBI guidelines in India, MAS notices in Singapore, and OCC guidance in the US create overlapping compliance layers for cross-border institutions.
- Insurance:Claims verification, policyholder authentication, and agent onboarding drive voice and facial recognition pilots. Health insurance exchanges in Germany and life insurers in Japan are expanding passive biometric authentication in contact center environments.
- Retailers:Loyalty program protection, employee access, and age-restricted purchase verification. Point-of-sale biometric payment trials in Brazil and Saudi Arabia remain limited by consumer privacy hesitation and terminal upgrade costs.
- Education:Campus access, examination proctoring, and student service authentication. Remote learning platforms in North America and examination boards in India deploy browser-based identity verification with limited hardware integration.
- Public Safety:Law enforcement identification, border control, and emergency responder credentialing. EU AI Act high-risk system classifications and NIST FRVT testing requirements constrain facial recognition procurement timelines for police and immigration agencies.
Banking dominates installed base. Insurance is where expansion concentrates.
Deployment Mode:
Cloud-Based and SaaS offerings iterate fastest with monthly feature releases, while On-Premises and Hybrid architectures lock into 3-5 year infrastructure amortization cycles.
- Cloud-Based:Multi-tenant identity platforms with elastic scaling and regional data residency options. AWS, Azure, and Google Cloud availability zone configurations enable GDPR, LGPD, and PIPL compliance through geo-fenced tenant isolation.
- SaaS:Pre-configured workforce and customer identity workflows with API-first integration models. Okta, Ping Identity, and ForgeRock compete through connector ecosystems spanning 5,000+ enterprise applications.
- Hybrid:Split architectures with sensitive credential processing on-premises and policy management in cloud control planes. German KrITIS sector operators and Saudi Arabian critical infrastructure providers mandate this topology for air-gapped credential vaults.
- On-Premises:Dedicated hardware and software stacks for classified government and defense environments. NATO and Five Eyes alliance procurement specifications enforce Common Criteria EAL4+ certification for directory services and cryptographic modules.
- Managed Services:Outsourced identity operations including help desk, certification authority management, and fraud monitoring. Australian federal agencies and Canadian provincial health networks contract SIEMENS and IBM for multi-year identity operations outsourcing.
On-Premises dominates installed base in defense and classified sectors. Cloud-Based is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and France runs 40-50% above Southeast Asian markets due to eIDAS 2.0 compliance premiums and sovereign cloud mandates. India's Aadhaar-linked infrastructure delivers the steepest volume expansion, though at compressed per-transaction economics.
United States
NIST SP 800-63 revision cycles shape federal procurement specifications for zero-trust identity architectures. The Department of Defense mandates Common Criteria EAL4+ certification for directory services in classified environments. Washington DC and Northern Virginia host concentrated defense contractor identity integration clusters serving federal agencies.
Germany
KrITIS sector operators require air-gapped credential vaults under BSI specifications for critical infrastructure protection. The EU AI Act's high-risk classification for biometric identification forces 12-18 month conformity assessment extensions. Munich and Frankfurt anchor qualified trust service provider ecosystems for cross-border wallet interoperability.
India
UIDAI governs Aadhaar authentication APIs driving rural banking correspondent network deployments. RBI guidelines mandate video-KYC protocols for digital account opening in mobile banking infrastructure. Mumbai and Bangalore concentrate neobank identity verification API development centers.
Singapore
MAS guidelines require biometric liveness checks for remote customer onboarding in digital lending workflows. The country's national digital identity regulator enforces Singpass integration standards for government service authentication. The city-state functions as Southeast Asia's regional hub for financial services identity platform deployment.
Brazil
Central Bank video-KYC requirements expand identity verification volumes for PIX instant payment rails. ANVISA and the national telecommunications regulator enforce subscriber identity verification for mobile money services. São Paulo anchors biometric payment terminal pilot programs in retail point-of-sale infrastructure.
Global Digital Identity Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cryptographic modules and biometric sensors. The vendor base stratifies between consolidated cloud-native platforms and fragmented hardware credential manufacturers. Three archetypes dominate: aerospace-defense conglomerates with smart card heritage, enterprise software vendors extending hybrid cloud governance, and pure-play SaaS identity providers. Competitive moves concentrate on vertical integration into secure element manufacturing and strategic partnerships with systems integrators for regulated sector deployment.
Among French aerospace-defense conglomerates, Thales Group exemplifies the high-assurance government contract archetype through its biometrics and smart card heritage. NEC Corporation and IDEMIA represent specialized component tier positions in facial recognition algorithms and secure credential manufacturing respectively. IBM Corporation anchors the enterprise platform segment through Red Hat OpenShift integrations extending hybrid identity governance into financial workflows.
| Leading Market Players |
|---|
| Thales Group |
| NEC Corporation |
| IDEMIA |
| Samsung SDS |
| IBM Corporation |
| Microsoft Corporation |
| ForgeRock |
| Experian plc |
| TELUS Communications |
| Others |
Supply & Pricing Matrix
Secure element foundry undercapacity in Taiwan and South Korea is forcing 18-24 month allocation queues for high-assurance smart card batches, compressing supplier margins while elevating premium pricing for qualified trust service providers serving EU eIDAS 2.0 mandates. This utilization squeeze propagates through identity infrastructure procurement, with biometric hardware vendors absorbing cost escalation while cloud-native verification API providers capture margin expansion through software-based secure enclave virtualization.
Pricing Analysis
Configured-to-order pricing for air-gapped hybrid deployments runs 40-50% above standard cloud-native SaaS tiers, reflecting sovereign cloud compliance premiums and Common Criteria EAL4+ certification costs. Three-tier pricing structure across premium, standard, and economy levels separates qualified trust service providers from consumer-grade biometric offerings and basic document verification APIs. Cost compression in consumer onboarding tiers is intensifying because neobanks and digital lenders prioritize friction reduction over assurance depth. Financial services procurement committees exhibit lowest price sensitivity, while education and retail verticals drive hardest bargain for passwordless workforce authentication.
Supply Chain Analysis
Extended payment terms from German and French critical infrastructure operators are squeezing working capital for biometric sensor manufacturers and cryptographic module suppliers. Geographic supply concentration centers on Taiwan and South Korea for secure element foundry capacity, China for fingerprint sensor assembly, and France for qualified electronic signature HSM production. Raw material dependencies span silicon wafers, rare-earth magnets for iris recognition motors, and specialized optical glass for facial recognition cameras. Single-source vulnerability in East Asian foundry networks threatens credential batch delivery timelines. Distribution runs through systems integrators in Munich, Singapore, and São Paulo who bundle implementation services with multi-year platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Identity Solutions Market is approaching a platform-economics inflection where eIDAS 2.0 wallet interoperability and India's Aadhaar-linked DPI ecosystem are consolidating procurement around vertically integrated trust frameworks rather than point solutions.
For Market Incumbents: Insulate high-assurance government contract positions through captive secure element manufacturing investments in France and Germany, while accelerating FIDO2 passkey integration into handset OEM silicon to defend against cloud-native verification API displacement. The EU AI Act's conformity assessment timeline compression threatens facial recognition product margins unless incumbents pre-certify algorithmic fairness documentation. For New Entrants and Emerging Players: Voice biometrics penetration gaps in European healthcare contact centers offer white-space expansion with lower competitive density than saturated facial recognition markets. Brazil's PIX instant payment rail expansion and Nigeria's mobile money subscriber verification mandates present penetrable geographies where local systems integrator partnerships anchor faster procurement access than direct enterprise sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS identity governance platforms with HR system and SIEM tool integrations, positioning these archetypes for sustained cash flow quality across a multi-year horizon. Acquisition targets should demonstrate qualified trust service provider certification progress under eIDAS 2.0. The signal to watch as inflection indicator is cross-border mutual recognition agreement momentum between national eID schemes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Active Directory's Office 365 embedding demonstrates ecosystem lock-in through productivity suite bundling. |
| Acquisition of Specialist Firm | Biometric algorithm vendors with NIST FRVT top-tier performance attract defense and border control procurement pull. |
| Strategic Partnership | Red Hat OpenShift integrations extend hybrid identity governance into regulated financial workflows. |
| Geographic Expansion | Qualified trust service provider certification in Munich and Frankfurt anchors EU cross-border wallet interoperability. |
| Product Launch | Edge AI facial matching without cloud transmission opens defense segments previously blocked by air-gap requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with identity governance platform engineers, financial services IT procurement officers, biometric algorithm R&D directors, and systems integrator partners in Germany and Singapore. Secondary validation drew from NIST SP 800-63 revision documentation, EU AI Act conformity assessment guidance, UIDAI API specification releases, and SEC filings from publicly traded identity software vendors. Bottom-up transaction volume modeling and top-down regulatory mandate sizing were triangulated against cloud provider capex disclosures and hyperscaler identity service revenue segmentations.
Calibration against historical biometric deployment trajectories in India's Aadhaar ecosystem and Estonia's X-Road interoperability layer anchored growth rate derivation across the analysis window. Segmentation dimensions modeled span solution type, deployment mode, end-user industry, and regional regulatory framework cluster. CAGRs were derived from algorithmic liveness detection update cycles, eIDAS 2.0 procurement timeline assumptions, and sovereign cloud mandate diffusion patterns. Industry-specific inputs include video-KYC regulatory mandate expansion rates and FIDO Alliance certification program adoption curves.
Practitioners should monitor EU AI Act enforcement variance, Aadhaar authentication API volume trajectories, and cross-border eID mutual recognition agreement momentum for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
VPN Software Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Information Rights Management Market
Security Software
Global Consumer IAM Market
Security Software
Smartphone Security Market
Security Software
Secure Digital Card Market
Security Software
Identity Governance and Administration Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
Home Webcam Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Next-Generation Intrusion Prevention System (NGIPS) Market
Security Software
Passwordless Authentication Market
Security Software
Security Testing Market
Security Software
Digital Risk Protection Platform Market