
 North America Artificial Intelligence in Healthcare Market | 2026-2036
North America Artificial Intelligence in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
North America Artificial Intelligence in Healthcare Market Insights
The FDA's software-as-a-medical-device framework is repositioning compliance costs and validation timelines for AI healthcare entrants across North America. Microsoft Corporation leverages its cloud infrastructure to anchor enterprise health AI deployments at scale. NVIDIA Corporation dominates specialized silicon supply for medical imaging inference workloads. IBM Corporation navigates regulatory complexity through dedicated healthcare compliance divisions.
Artificial intelligence in healthcare encompasses algorithmic systems that process clinical, genomic, or operational data to augment diagnostic accuracy, optimize treatment protocols, or automate administrative workflows, typically requiring GPU-accelerated computing clusters and federated learning architectures to preserve patient privacy. Machine learning applications in diagnostic imaging command the largest installed base and near-term revenue pools across the technology dimension. Natural language processing tools for clinical documentation represent the fastest-expanding segment as health systems confront physician burnout and coding backlogs. Software platforms capture disproportionate margin compared to hardware owing to recurring licensing models and lower incremental delivery costs.
FDA premarket review pathways, HIPAA privacy safeguards, and Health Canada regulatory standards collectively determine which AI models achieve commercial deployment in North American clinical settings. These frameworks elevate barriers for unvalidated algorithms while creating protected market access for compliant vendors. Stakeholders must monitor evolving FDA guidance on adaptive AI systems and provincial health authority procurement criteria in Canada to anticipate reimbursement and adoption trajectories.
Market Dynamics
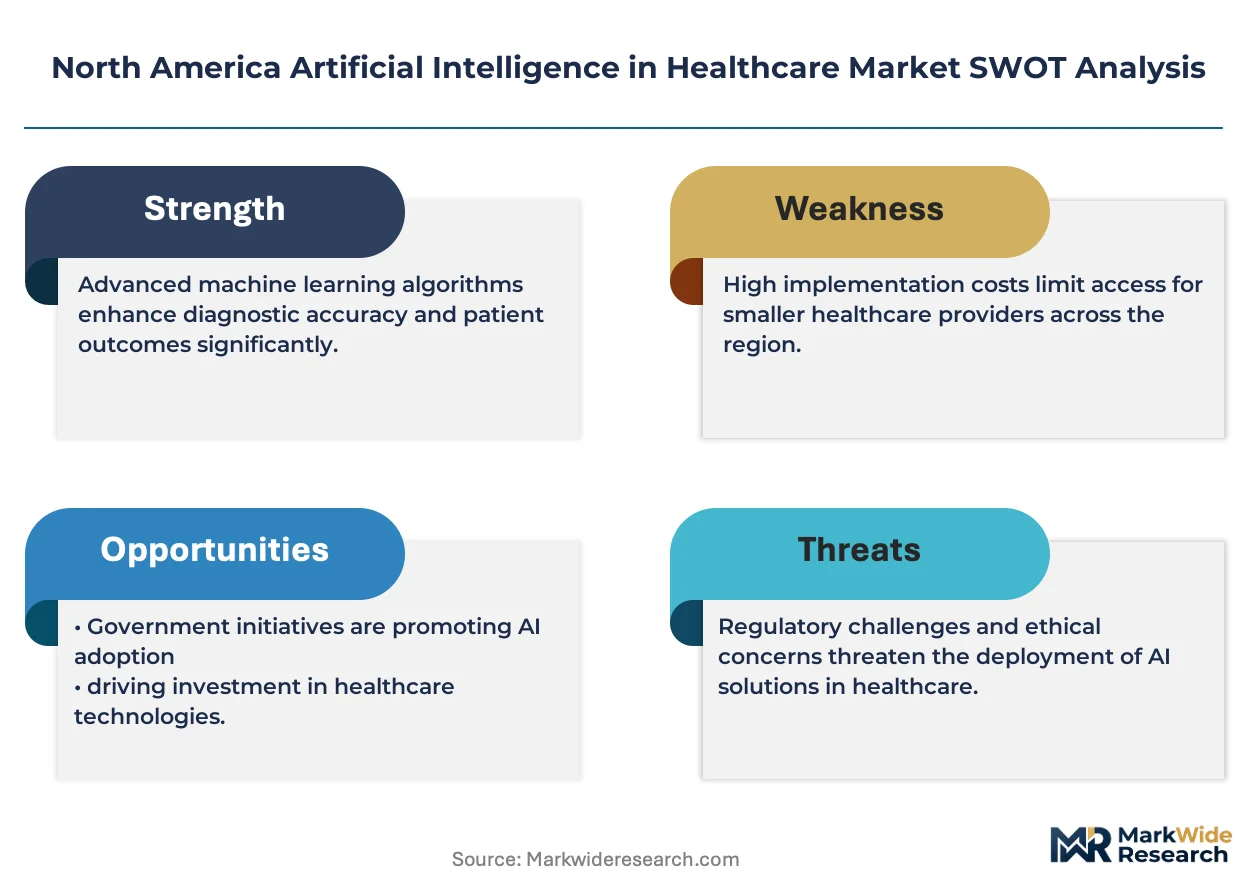
FDA premarket review pathways are compressing validation timelines for adaptive AI systems while hospital procurement committees demand real-world evidence packages that exceed traditional software validation standards.
Growth Catalysts
- Software-as-a-Medical-Device Framework:The FDA's evolving SaMD classification is creating clear commercialization pathways for algorithm developers seeking 510(k) clearance.
- Physician Burnout Crisis:Clinical documentation backlogs across Massachusetts General Brigham and NYU Langone are accelerating NLP tool procurement cycles.
- Federated Learning Architectures:Privacy-preserving computation is unblocking multi-site training datasets that were previously inaccessible under HIPAA constraints.
Market Restraints
- GPU Supply Concentration:NVIDIA's dominance in medical imaging inference silicon creates single-source vulnerability for algorithm deployment at scale.
- Premarket Validation Costs:FDA 510(k) submissions for AI diagnostic tools require prospective clinical studies that consume eighteen to thirty-six months.
- Interoperability Friction:Legacy EHR systems from Epic and Cerner demand custom API integration that fragments deployment economics.
Strategic Opportunities
- Canadian Provincial Procurement:Ontario Health and Alberta Health Services are consolidating AI purchasing through centralized tender frameworks that favor enterprise-scale vendors.
- Genomic-Clinical Convergence:Integration of whole-genome sequencing with diagnostic imaging algorithms is opening oncology precision medicine workflows.
- CMS Reimbursement Tailwinds:New Technology Add-on Payment pathways are creating covered indications for AI-assisted stroke detection and diabetic retinopathy screening.
Industry Challenges
- Clinical-AI Talent Scarcity:Health systems compete for data scientists with dual competency in machine learning and clinical domain knowledge.
- Algorithm Drift Management:Continuous learning systems require post-market surveillance infrastructure that most hospitals have not built.
- Cloud Migration Complexity:Hybrid architectures spanning on-premise PHI storage and AWS/Azure compute layers multiply security audit surfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Artificial Intelligence in Healthcare Market |
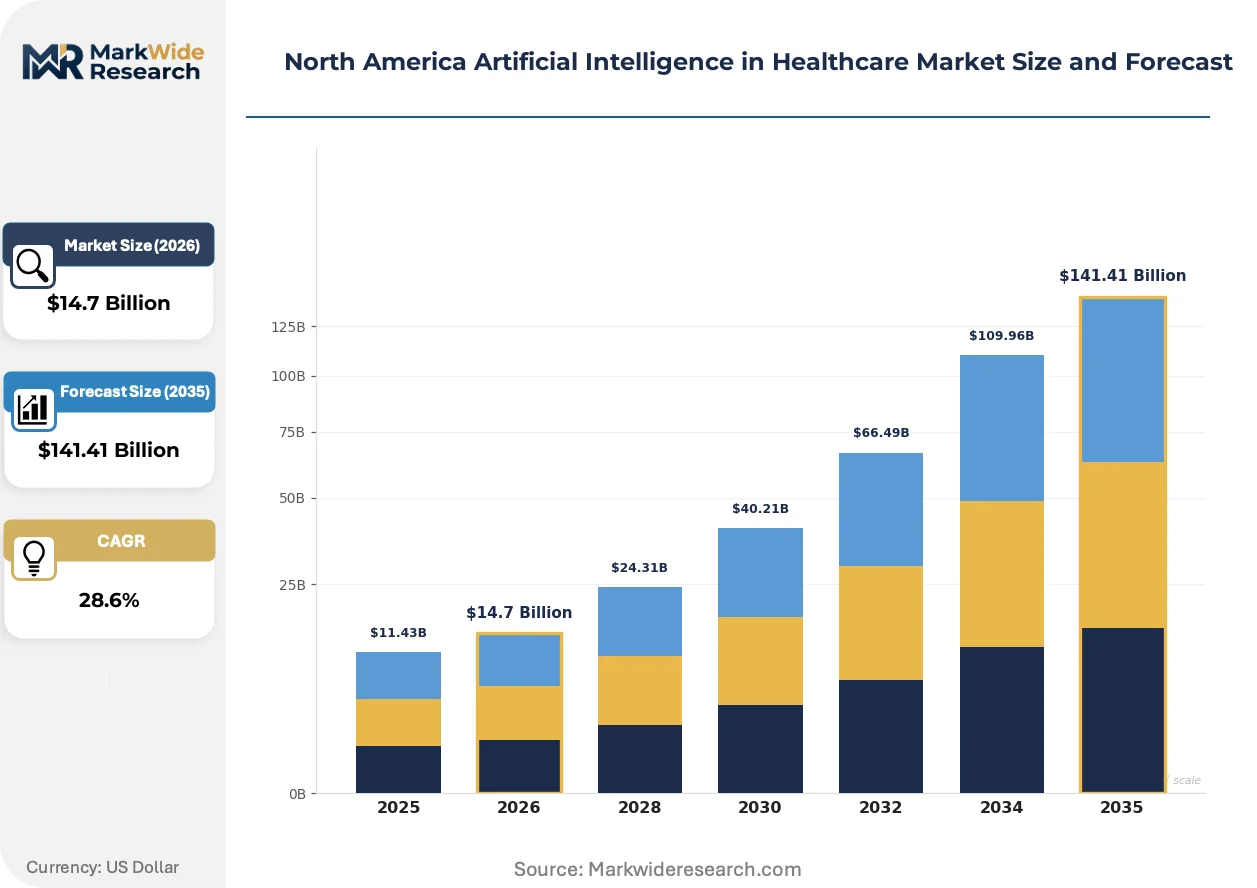
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $141.41 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Application: Diagnostic Imaging, Patient Monitoring, Drug Discovery, Personalized Medicine End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies Technology: Machine Learning, Natural Language Processing, Robotics, Deep Learning |
| Companies Covered | Microsoft Corporation, IBM Corporation, Amazon Web Services, Inc., NVIDIA Corporation, Google LLC, Oracle Corporation, GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Artificial Intelligence in Healthcare Market Trends and Innovations
Foundation models trained on multimodal clinical data are displacing narrow task-specific algorithms across diagnostic and operational workflows. This architectural shift is compressing development cycles while raising new questions about validation scope and liability allocation.
Multimodal foundation models are unifying diagnostic imaging, pathology slides, and clinical notes into single inference architectures. Radiology departments at Stanford Medicine and Memorial Sloan Kettering are piloting these systems for oncology staging. The technology is unifying previously siloed subspecialty workflows into integrated diagnostic pipelines that compress report turnaround times.
Health Canada's Interim Order for Medical Devices with Machine Learning is mandating predetermined change control plans for adaptive algorithms. Manufacturers must submit modification protocols upfront rather than seeking approval for each update. Cardiovascular AI vendors targeting the Canadian market are restructuring quality management systems to accommodate this proactive governance model.
Hospital procurement committees are consolidating AI purchasing through single-vendor enterprise agreements rather than point solutions. Integrated delivery networks in Texas and Florida are demanding platform breadth that spans imaging, documentation, and operational analytics. This concentration is visible most acutely in the southeastern United States where HCA Healthcare and Tenet Health are standardizing vendor rosters.
North America Artificial Intelligence in Healthcare Market Segmentation
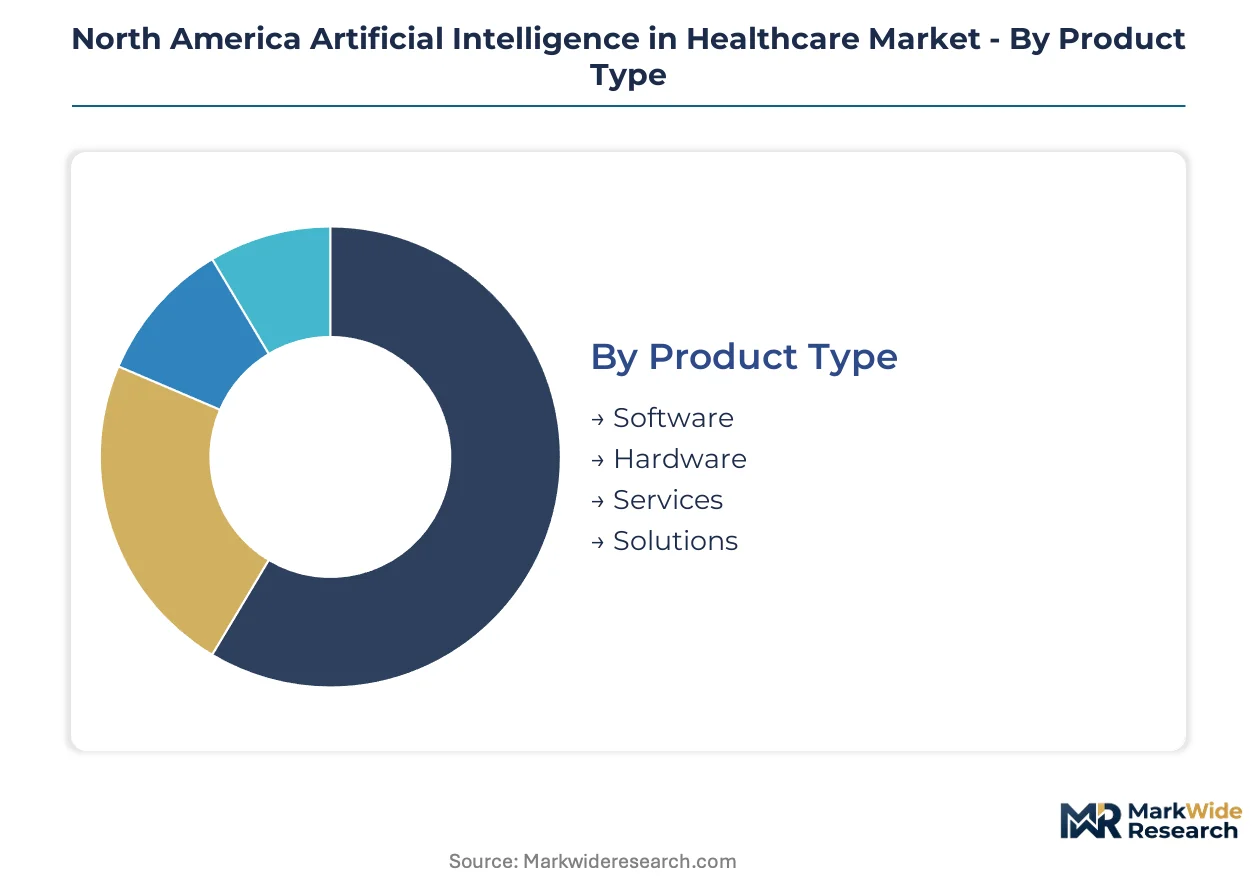
Segmentation in the North America AI healthcare market reveals divergent procurement patterns across clinical settings. Hospital systems prioritize integrated platforms while research institutions favor modular, experimental toolkits. Understanding these buyer archetypes shapes product positioning and pricing architecture.
Product Type:
Cost tier separates enterprise commitments from experimental deployments across buyer categories.
- Software:Algorithmic platforms for diagnostic inference and clinical decision support run on recurring licensing models. Massachusetts General Brigham and NYU Langone negotiate enterprise-wide NLP documentation tools to address physician burnout. Software commands disproportionate margin through SaaS delivery and lower incremental deployment costs.
- Hardware:GPU-accelerated compute clusters and specialized inference processors power real-time medical imaging workloads. NVIDIA silicon dominates hospital data center procurement in the northeastern United States corridor. Supply concentration creates single-source vulnerability for scaled algorithm deployment.
- Services:Implementation consulting and integration support for legacy EHR systems.
- Solutions:Bundled offerings combining software, hardware, and managed services for turnkey deployment.
Software leads volumes today; hardware is gaining share fastest through cloud-adjacent infrastructure refresh cycles.
Application:
Maturity gradient separates FDA-cleared pathways from emerging experimental domains.
- Diagnostic Imaging:Radiological AI for oncology staging, stroke detection, and diabetic retinopathy screening commands the largest installed base. Memorial Sloan Kettering and Stanford Medicine pilot multimodal foundation models unifying imaging with pathology. CMS New Technology Add-on Payment pathways now cover specific AI-assisted indications.
- Drug Discovery:Generative models accelerate molecular design and clinical trial patient matching. Pharmaceutical companies deploy these tools for target identification in the Boston metropolitan cluster. Federated learning architectures preserve competitive data silos while enabling multi-site training.
- Patient Monitoring:Continuous vital sign analysis and early warning systems for ICU settings.
- Personalized Medicine:Genomic-clinical convergence tools for precision oncology protocols.
Diagnostic imaging anchors current revenue; drug discovery is climbing the fastest as biopharma R&D budgets reallocate.
End User:
Volume scale distinguishes procurement authority and integration complexity requirements.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate AI purchasing through single-vendor enterprise agreements. HCA Healthcare and Tenet Health standardize vendor rosters across imaging, documentation, and operational analytics. These buyers demand platform breadth and real-world evidence packages exceeding traditional software validation.
- Research Institutions:Academic medical centers pilot experimental algorithms before commercial translation. Stanford Medicine and Memorial Sloan Kettering host multimodal foundation model trials. Publication incentives and grant funding drive early adoption of unvalidated architectures.
- Clinics:Smaller outpatient settings seeking point solutions for specific diagnostic tasks.
- Pharmaceutical Companies:R&D divisions deploying AI for compound screening and clinical operations.
Hospitals dominate procurement value; research institutions are expanding most quickly through federal funding infusions.
Technology:
Supply concentration in specialized silicon shapes deployment economics and vendor lock-in risk.
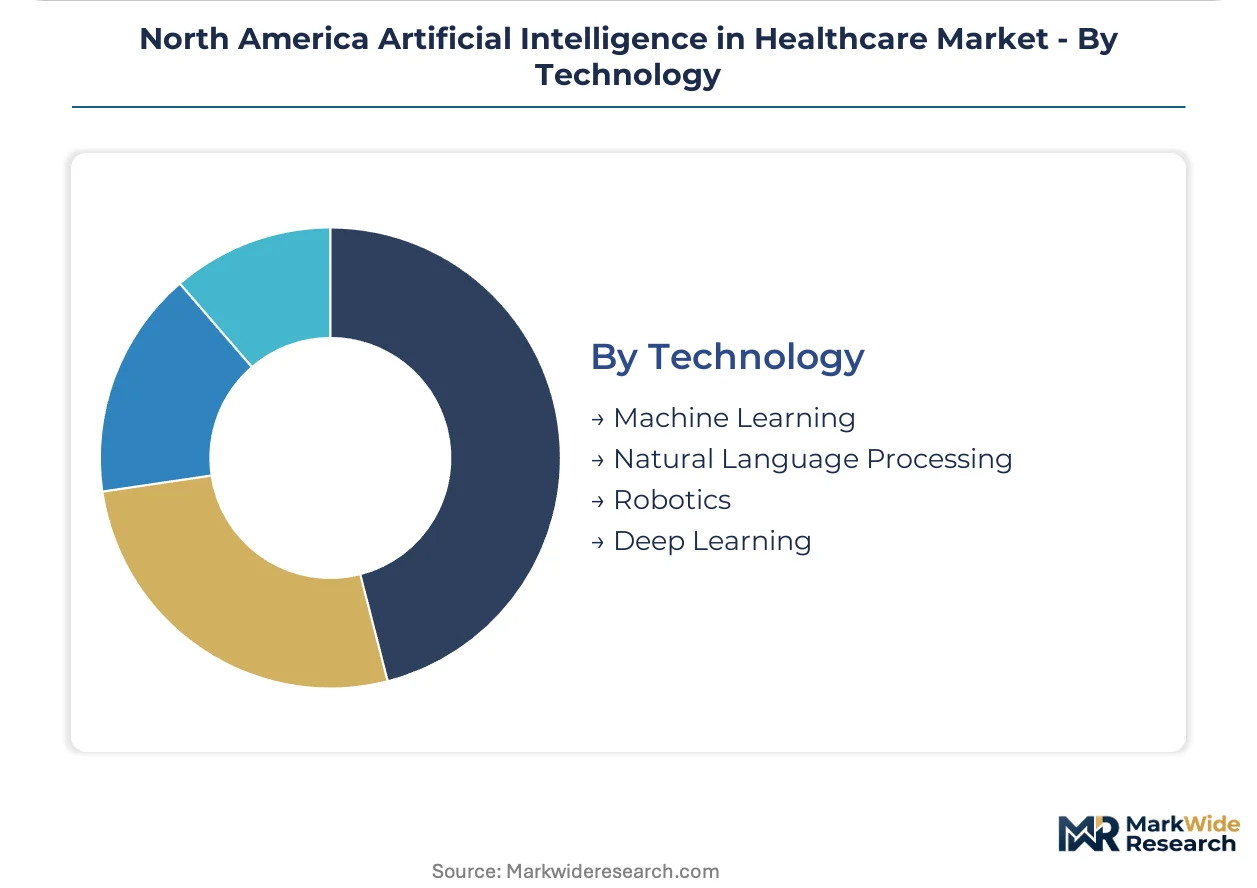
- Machine Learning:Supervised and unsupervised algorithms for structured clinical data analysis represent established deployment. Supervised learning for diagnostic imaging commands near-term revenue concentration. Health Canada's Interim Order mandates predetermined change control plans for adaptive ML systems.
- Natural Language Processing:Clinical documentation automation and coding assistance tools address physician burnout crises. Massachusetts General Brigham accelerates procurement cycles for ambient listening and automated note generation. This segment expands most quickly as health systems confront administrative workforce gaps.
- Deep Learning:Neural architectures for complex pattern recognition in unstructured medical data.
- Robotics:Surgical assistance and rehabilitation automation systems with AI-guided motion planning.
Machine learning holds installed base leadership; natural language processing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical AI talent concentrates in the northeastern United States corridor and southern Ontario, where academic medical centers and technology clusters overlap. Hospital procurement committees in these zones demand real-world evidence packages that exceed traditional software validation standards. Federal and provincial regulators are compressing approval timelines while elevating post-market surveillance requirements.
United States
Massachusetts General Brigham and NYU Langone accelerate procurement cycles for NLP documentation tools to address physician burnout. FDA premarket review pathways for software-as-a-medical-device are compressing validation timelines for adaptive AI systems. The Boston-New York metropolitan clinical networks anchor demand concentration for diagnostic imaging platforms.
Canada
Ontario Health and Alberta Health Services consolidate AI purchasing through centralized tender frameworks favoring enterprise-scale vendors. Health Canada's Interim Order for Medical Devices with Machine Learning mandates predetermined change control plans for adaptive algorithms. Toronto's University Health Network pilots multimodal foundation models for oncology staging workflows.
Mexico
Private hospital chains in Mexico City Metro expand telemedicine infrastructure requiring AI-powered diagnostic assistance tools. The national pharmaceutical regulator evaluates alignment with FDA premarket review standards for cross-border algorithm deployment. Guadalajara's technology corridor attracts nearshore development centers for clinical NLP tools.
California
Stanford Medicine and Memorial Sloan Kettering satellite facilities pilot multimodal foundation models unifying imaging with pathology data. HIPAA privacy safeguards and CMS reimbursement pathways shape commercial deployment feasibility. The San Francisco Bay Area hosts venture concentration for genomic-clinical convergence startups.
Texas
HCA Healthcare and Tenet Health standardize vendor rosters across imaging, documentation, and operational analytics through single-vendor enterprise agreements. Federated learning architectures unblock multi-site training datasets previously inaccessible under privacy constraints. The Dallas-Houston corridor anchors southeastern United States procurement volume for hospital AI systems.
North America Artificial Intelligence in Healthcare Market Competitive Landscape
The competitive structure tilts toward cloud infrastructure providers and specialized silicon manufacturers. Technology conglomerates with existing healthcare compliance divisions hold structural advantages in navigating FDA validation requirements. Two strategic archetypes dominate: horizontal platform vendors leveraging enterprise cloud relationships, and vertical health AI specialists with regulatory-cleared diagnostic algorithms. Competitive moves concentrate on strategic partnerships with integrated delivery networks and portfolio diversification into adjacent clinical workflows.
Among cloud infrastructure providers, Microsoft Corporation anchors enterprise health AI deployments through existing Azure relationships with hospital systems. NVIDIA Corporation exemplifies the specialized silicon archetype, supplying GPU-accelerated compute clusters for real-time medical imaging inference. IBM Corporation occupies a position bridging both categories, navigating regulatory complexity through dedicated healthcare compliance divisions while maintaining on-premise infrastructure partnerships. These three entities represent the dominant competitive anchors shaping procurement committee vendor selection criteria.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services, Inc. |
| NVIDIA Corporation |
| Google LLC |
| Oracle Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committee consolidation across HCA Healthcare and Tenet Health networks is compressing vendor margins and forcing algorithm developers toward bundled platform economics rather than point-solution pricing. This buyer concentration elevates enterprise-scale vendors while fragmenting pricing power among specialized diagnostic toolmakers.
Pricing Analysis
Bundled enterprise agreements versus unbundled point solutions define the pricing architecture across North American health systems. SaaS-tiered subscription models dominate software licensing, with price differentiation resting on FDA clearance tier and integration complexity with Epic or Cerner EHR environments. Pricing pressure intensifies in the hardware tier as NVIDIA's silicon monopoly limits negotiation leverage for hospital data centers. Research institutions show least price sensitivity owing to grant-funded procurement, while community hospital networks face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced GPU fabrication, while specialized medical imaging processors concentrate in the United States and China. The supply chain draws from rare earth elements for semiconductor substrates, high-purity silicon wafers, and precision optical components for imaging systems. Tariff exposure on Chinese-manufactured hardware components elevates cost uncertainty for algorithm deployment at scale. Distribution runs through hyperscaler cloud marketplaces and direct OEM relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA software-as-a-medical-device framework evolution continuously elevates compliance barriers and entrenches cleared incumbents.
For Market Incumbents: Cement platform breadth across imaging, documentation, and operational analytics to match HCA Healthcare and Tenet Health enterprise procurement demands. Deepen backward integration into cloud infrastructure partnerships to defend against Microsoft and Amazon margin compression. Prioritize Health Canada predetermined change control plan certification to capture Ontario Health and Alberta Health Services centralized tenders. For New Entrants and Emerging Players: Community hospital networks in the southeastern United States represent an underserved buyer archetype bypassed by enterprise-focused vendors. Federated learning toolkits for multi-site research consortia offer lower regulatory barriers than diagnostic imaging clearance pathways. A go-to-market angle anchored on ambient clinical documentation for physician burnout relief bypasses crowded radiology AI competition. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical health AI specialists possessing FDA-cleared algorithms but lacking cloud infrastructure scale. Long-term viability favors entities bridging regulatory compliance depth with platform integration breadth. Watch Health Canada adaptive algorithm guidance evolution as the signal indicating Canadian market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses validation timelines for adaptive AI systems seeking software-as-a-medical-device clearance. |
| Hospital System Partnership | Secures real-world evidence generation through Massachusetts General Brigham or NYU Langone deployment. |
| Cloud Infrastructure Integration | Aligns with Azure and AWS procurement preferences dominating integrated delivery network RFPs. |
| Reimbursement Strategy Development | Captures CMS New Technology Add-on Payment pathways for stroke detection and retinopathy screening. |
| Genomic-Clinical Convergence Platform | Opens precision oncology workflows through Memorial Sloan Kettering and Stanford Medicine pilot networks. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at algorithm developers. Secondary validation draws from FDA 510(k) clearance databases, Health Canada medical device listings, CMS reimbursement code decisions, and hospital procurement contract disclosures. Bottom-up installed base estimates triangulate against top-down market sizing from cloud infrastructure spending and GPU shipment data.
Granularity-level modeling disaggregates revenue across software, hardware, services, and solutions product types; diagnostic imaging, drug discovery, patient monitoring, and personalized medicine applications; machine learning, natural language processing, deep learning, and robotics technologies; and hospitals, research institutions, clinics, and pharmaceutical company end users. CAGRs derive from regression analysis of historical procurement cycles and regulatory approval velocity. Forecast inputs include FDA premarket review timeline compression rates and Canadian provincial tender consolidation patterns.
Underlying measurement precision varies by segment; software licensing revenue carries tighter precision than experimental hardware deployment estimates. Forecasts reflect assumptions about regulatory pathway stability and hospital capital expenditure continuity. Algorithm drift management capability gaps and cloud migration complexity represent specific risk factors that could revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Vocal Biomarkers Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Laboratory Informatics Market
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
EHR EMR Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market