
 Aliphatic Solvents Market | 2026-2036
Aliphatic Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Aliphatic Solvents Market Analysis
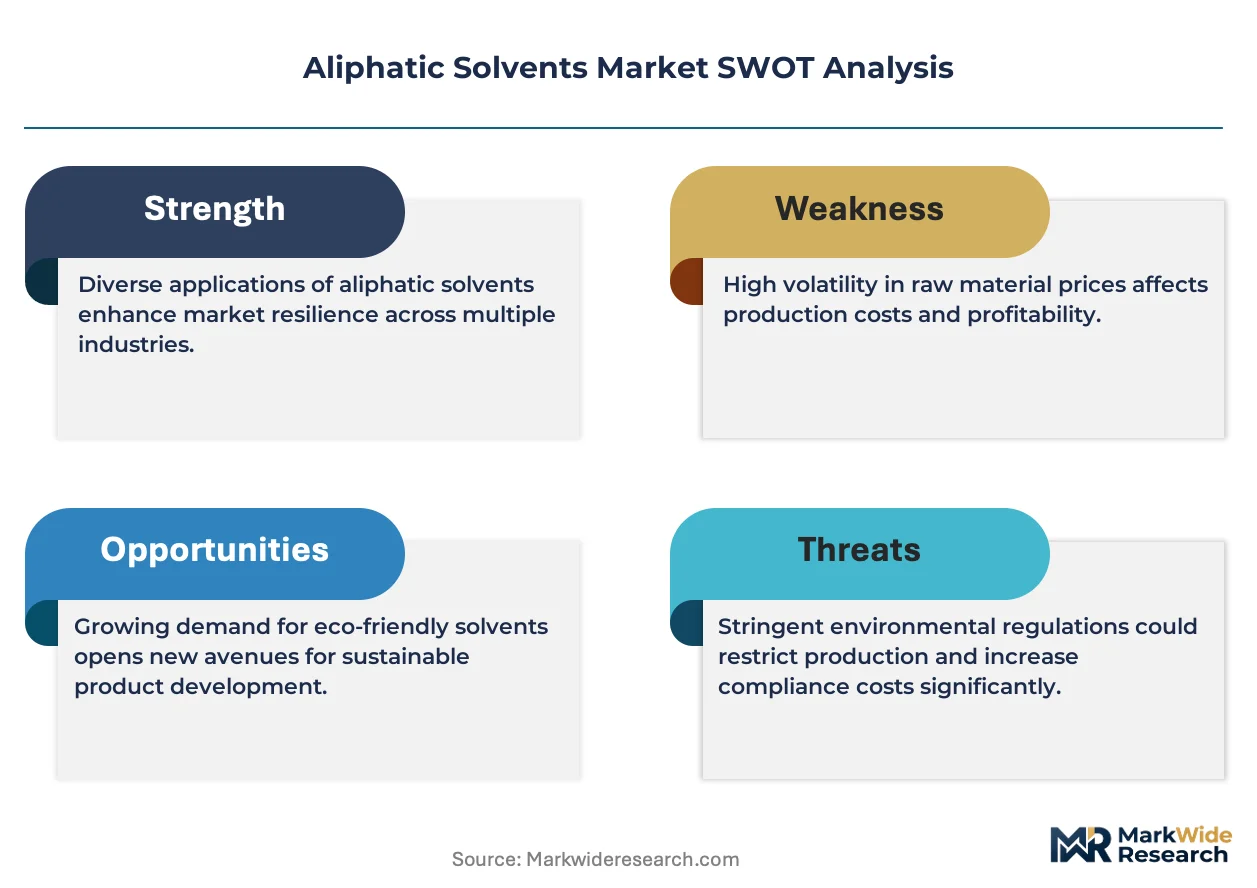
Pharmaceutical-grade purity specifications are bifurcating the Aliphatic Solvents Market into premium-certified and commodity-industrial tiers. Exxon Mobil Corporation leverages its integrated refinery-petrochemical footprint to sustain cost leadership in high-volume hexane production. Shell plc differentiates through controlled supply chains for food-grade mineral spirits across European pharmaceutical packaging applications.
Aliphatic solvents are saturated hydrocarbon-based liquids, typically C5–C12 paraffinic or naphthenic structures, refined to achieve specific boiling ranges between 30°C and 300°C for dissolution, extraction, or carrier functions in industrial processes. Mineral spirits dominates volume demand from paints and coatings end users, where architectural recovery in North American housing construction anchors steady offtake. Pharmaceutical-grade heptane is recording the fastest expansion trajectory, driven by crystallization and chromatography applications in generic drug manufacturing across India and Southeast Asia.
EPA regulations under the Clean Air Act constrain permissible benzene content in commercial aliphatic blends, while REACH mandates full substance registration and hazard communication across European supply chains. India's BIS certification requirements for solvent purity in food-contact and pharmaceutical applications are tightening import specifications and redirecting procurement toward domestic producers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as solvent producers face downstream pressure to certify fluorine-free status in cleaning and coating formulations.
Market Dynamics
Pharmaceutical-grade purity mandates are compressing commodity margins while rewarding certified producers with pricing power and supply chain lock-in across drug formulation value chains.
Growth Catalysts
- India's PLI scheme for active pharmaceutical ingredients:Domestic solvent consumption is accelerating as API manufacturers localize production to capture fiscal incentives and reduce import dependency.
- REACH substance registration requirements:European pharmaceutical packaging demand for fully traceable, hazard-documented mineral spirits is filtering non-compliant suppliers from approved vendor lists.
- Crystallization-grade heptane:Generic drug manufacturers in Southeast Asia are standardizing on high-purity heptane for chromatography applications, creating dedicated solvent specification tiers.
Market Restraints
- Crude oil price volatility:Naphtha feedstock costs swing with Brent crude benchmarks, compressing margin predictability for non-integrated refiners.
- EPA benzene content limits:The Clean Air Act's aromatic impurity caps force additional hydrotreating investment, raising fixed costs for commercial blend producers.
- Aqueous cleaning systems:Water-based degreasing technologies are capturing surface preparation applications in automotive assembly, displacing mineral spirits in select process steps.
Strategic Opportunities
- Food-contact certification expansion:BIS requirements for solvent purity in Indian food packaging are redirecting procurement toward domestic producers with verified contaminant testing.
- Fluorine-free formulation demand:Per- and polyfluoroalkyl substance restrictions are opening certified solvent positions in electronics cleaning where fluorinated chemistries previously dominated.
- Digital inventory platforms:Specialty chemical distributors are deploying just-in-time solvent delivery systems to reduce pharmaceutical manufacturer working capital requirements.
Industry Challenges
- Pharmaceutical-grade certification timelines:CDSCO and FDA dual-filing requirements for excipient-grade solvents extend approval cycles beyond eighteen months.
- Legacy tank farm infrastructure:Dedicated storage for segregated purity grades demands capital retrofitting at port terminals and inland distribution hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aliphatic Solvents Market |
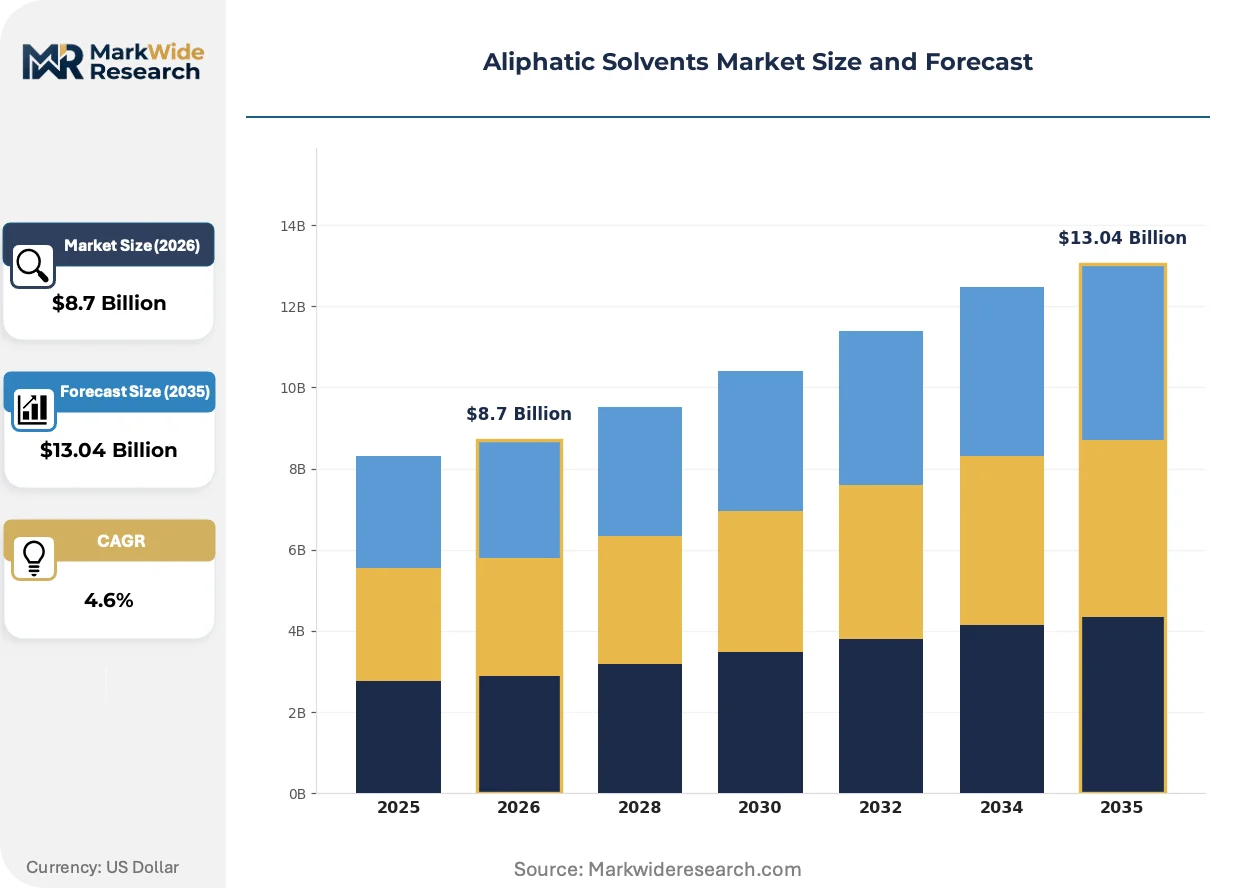
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Hexane, Mineral Spirits, Heptane Grade: Industrial Grade, Pharmaceutical Grade, Food Grade, Technical Grade Packaging Type: Drums, Containers, Bottles, IBC Totes End User: Paints & Coatings, Adhesives, Pharmaceuticals, Cleaning Agents |
| Companies Covered | Exxon Mobil Corporation, Shell plc, TotalEnergies SE, Chevron Phillips Chemical Company, BASF SE, SK Geocentric Co., Ltd., Calumet Specialty Products Partners, Idemitsu Kosan Co., Ltd., LyondellBasell Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aliphatic Solvents Market Emerging Trajectories
Bio-based hydrocarbon refining and closed-loop solvent recovery systems are redrawing competitive boundaries between petrochemical majors and specialty chemical innovators.
Supercritical fluid extraction using modified aliphatic blends is decomposing traditional hexane-based oilseed extraction in European food processing. Archer Daniels Midland and Bunge facilities in Germany and the Netherlands have retrofitted plants to handle densified propane-isobutane mixtures. This technology is decomposing the volume premium historically commanded by n-hexane in edible oil markets.
REACH's 2024 update to restriction entries for polycyclic aromatic hydrocarbons is forcing reformulation of rubber process oils and extender oils across EU tire manufacturing. ECHA's enforcement guidance now requires analytical certification below 0.001% for eight specified PAH compounds. German and Italian compounders are qualifying alternative naphthenic cuts with hydrotreated aromatic saturation below detection limits.
Consolidated procurement through pharmaceutical contract manufacturing organizations is compressing supplier counts and extending master service agreement durations. Indian CMOs like Divi's Laboratories and Laurus Labs are negotiating three-year solvent supply contracts with fixed purity specifications and penalty clauses for batch-to-batch variation. This concentration is most visible in Hyderabad and Visakhapatnam API manufacturing clusters where solvent consumption per facility exceeds ten thousand metric tons annually.
Aliphatic Solvents Market Segmentation
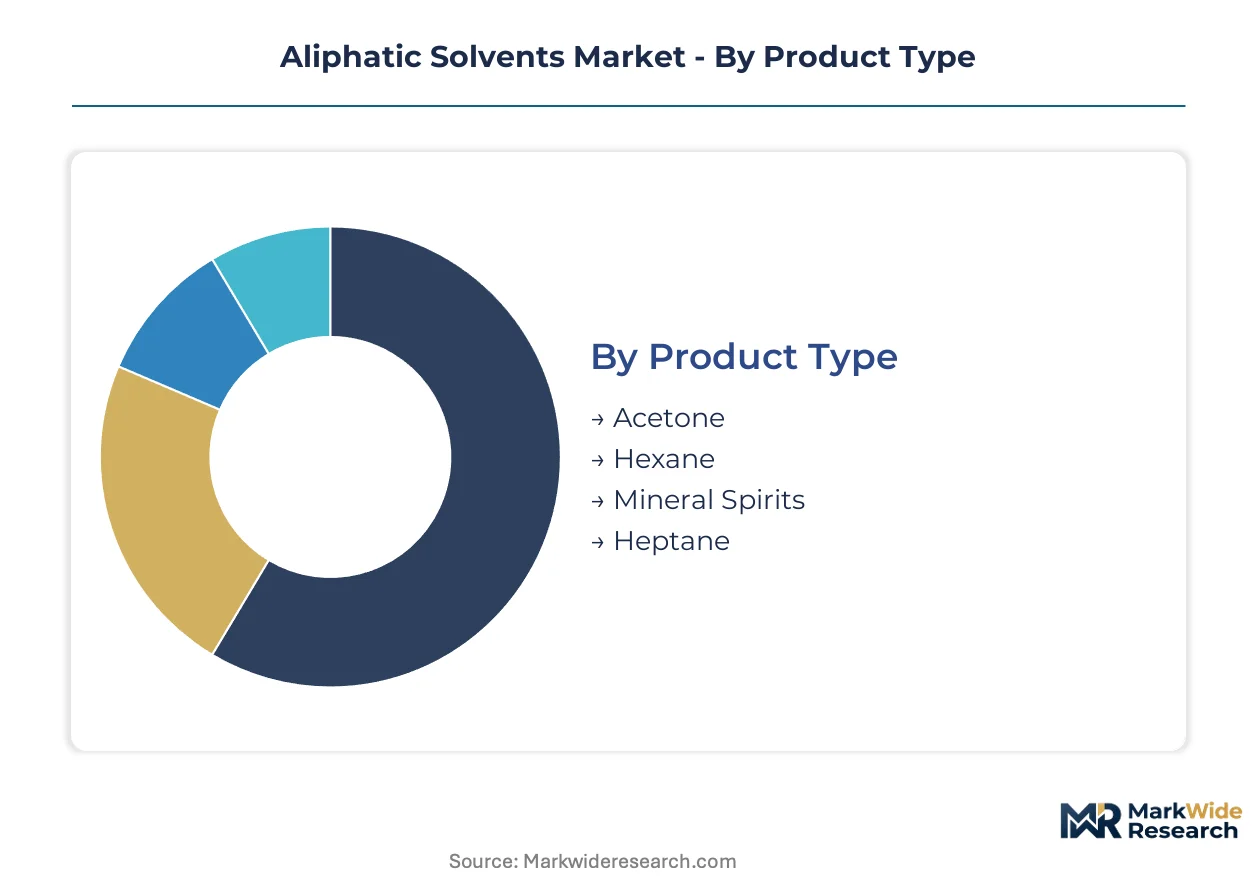
Purity specifications and container integrity requirements fragment the Aliphatic Solvents Market into distinct commercial tiers. Each segmentation dimension carries divergent margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Margin pools concentrate in high-purity solvents where hydrotreating investments create supply scarcity and pricing power.
- Hexane:A C6 paraffinic hydrocarbon refined to narrow boiling ranges between 68°C and 70°C for oilseed extraction and polymerization processes. Edible oil processors in India and Southeast Asia consume volume lots exceeding fifty thousand metric tons annually at individual facilities, with BIS and FSSAI purity mandates tightening import specifications.
- Heptane:A C7 saturated hydrocarbon with controlled aromatic content below 0.1% for crystallization and chromatography applications. Pharmaceutical manufacturers in Hyderabad and Visakhapatnam API clusters are standardizing on heptane for generic drug purification, with CDSCO filing requirements extending qualification timelines beyond eighteen months.
- Mineral Spirits:A C9–C12 aliphatic blend serving paint thinning and degreasing applications where architectural construction cycles drive offtake volatility.
- Acetone:A ketone solvent with miscibility in water and organic systems, consumed in adhesive formulations and chemical synthesis where co-solvent properties matter.
Hexane holds installed capacity at integrated refinery-petrochemical complexes. Heptane is rotating up the share rankings on pharmaceutical-grade demand.
Grade:
Certification tiers separate commodity producers from specialty suppliers capable of sustained margin capture.
- Pharmaceutical Grade:Solvents meeting USP, EP, and JP monograph specifications with residual solvent limits defined by ICH Q3C guidelines. CDSCO and FDA dual-filing requirements for excipient-grade certification extend approval cycles, locking qualified suppliers into multi-year contracts with Indian CMOs like Divi's Laboratories.
- Industrial Grade:Commercial blends with broader boiling ranges and higher aromatic tolerance for paint manufacturing and metal cleaning where cost minimization dominates procurement.
- Food Grade:Refined cuts meeting FSSAI and FDA food-contact specifications for edible oil extraction and packaging applications where contaminant testing is mandatory.
- Technical Grade:Unspecified-purity solvents for research and analytical applications where batch consistency matters less than unit cost.
Industrial Grade holds installed capacity across merchant refinery streams. Pharmaceutical Grade is climbing the fastest on tightening formulation standards.
Packaging Type:
Container specifications align with customer scale and contamination risk thresholds.
- Drums:Standard 200-liter steel containers for mid-volume pharmaceutical and coatings manufacturers with dedicated solvent storage infrastructure.
- IBC Totes:Intermediate bulk containers of 1000-liter capacity for high-throughput API facilities where tanker delivery is impractical and drum handling costs are prohibitive.
- Containers:Flexible intermediate bulk and lined tank options for food-grade mineral spirits where transport hygiene protocols apply.
- Bottles:Laboratory-scale packaging for analytical reagent and R&D applications requiring sealed amber glass to prevent photodegradation.
Drums hold installed capacity across legacy distribution networks. IBC Totes is rotating up the share rankings on pharmaceutical CMO consolidation.
End User:
Application-specific purity requirements create divergent procurement behaviors across consuming industries.
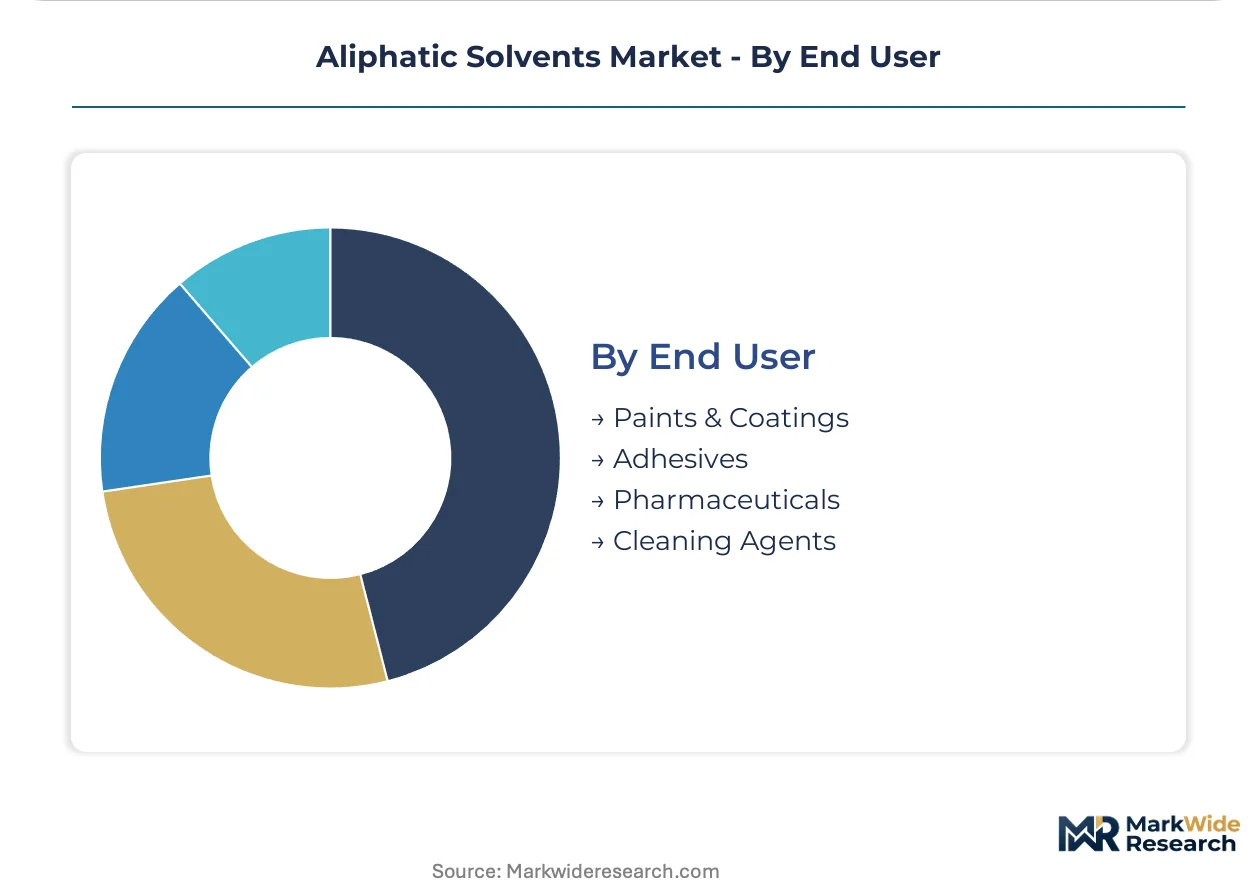
- Pharmaceuticals:Crystallization, chromatography, and tablet coating applications demanding ICH Q3C-compliant residual solvent profiles. Indian API manufacturers under the PLI scheme are localizing solvent procurement to capture fiscal incentives and reduce import dependency on European suppliers.
- Paints & Coatings:Architectural and industrial formulations where mineral spirits serve as viscosity reducers and flow agents. North American housing construction recovery is anchoring steady offtake from regional blenders.
- Adhesives:Solvent-borne systems for packaging and construction where acetone and hexane blends control drying rates and open times.
- Cleaning Agents:Degreasing formulations for metal fabrication and electronics where aqueous systems are displacing mineral spirits in select automotive assembly steps.
Paints & Coatings holds installed capacity on construction-linked demand cycles. Pharmaceuticals is rotating up the share rankings on API localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports pharmaceutical-grade heptane to European generic drug manufacturers while importing mineral spirits feedstock from Middle Eastern refiners. This trade corridor reflects divergent regional specialization across upstream refining and downstream formulation.
United States
EPA benzene content limits under the Clean Air Act constrain aromatic impurity levels in commercial aliphatic blends. Houston-Galveston petrochemical complexes maintain hydrotreating capacity for hexane production serving domestic edible oil processors. North American housing construction recovery sustains mineral spirits demand from architectural coatings manufacturers.
Germany
ECHA enforcement of REACH restriction entries for polycyclic aromatic hydrocarbons forces reformulation of rubber process oils. Ruhr industrial clusters host specialty refiners qualifying alternative naphthenic cuts with hydrotreated aromatic saturation below detection limits. German compounders supply tire manufacturers with certified low-PAH extender oils.
India
CDSCO filing requirements for excipient-grade solvents extend pharmaceutical certification timelines beyond eighteen months. Hyderabad and Visakhapatnam API manufacturing clusters negotiate three-year supply contracts with fixed purity specifications. The PLI scheme for active pharmaceutical ingredients accelerates domestic solvent consumption as manufacturers localize production.
Japan
METI standards for chemical substance management align with ICH Q3C residual solvent guidelines. Osaka-Kobe industrial corridors maintain dedicated storage infrastructure for segregated pharmaceutical-grade purity tiers. Japanese pharmaceutical packaging demand requires fully traceable mineral spirits with documented hazard communication.
South Korea
MFDS pharmaceutical excipient regulations mirror USP and EP monograph specifications. Ulsan petrochemical complexes leverage integrated refinery-petrochemical footprints for cost-competitive hexane production. Korean CMOs consolidate procurement through master service agreements with penalty clauses for batch-to-batch variation.
Aliphatic Solvents Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base separates into integrated petrochemical majors, merchant refinery operators, and regional specialty blenders. Three archetypes dominate: scale-driven refiners with captive feedstock, certification-focused specialists serving pharmaceutical CMOs, and regional distributors with tank farm infrastructure. Competitive moves concentrate on M&A for terminal assets and strategic partnerships for pharmaceutical-grade certification.
Within the integrated petrochemical tier, Exxon Mobil Corporation and Shell plc occupy positions exemplifying scale-driven production with refinery-petrochemical integration. Among merchant operators, Calumet Specialty Products Partners represents the specialty refiner archetype with focused capacity in narrow-cut aliphatic production. SK Geocentric Co., Ltd. anchors the Asia-Pacific regional specialist position, reflecting Korean petrochemical industry consolidation patterns.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell plc |
| TotalEnergies SE |
| Chevron Phillips Chemical Company |
| BASF SE |
| SK Geocentric Co., Ltd. |
| Calumet Specialty Products Partners |
| Idemitsu Kosan Co., Ltd. |
| LyondellBasell Industries N.V. |
| Others |
Supply Flow & Price Mechanics
Integrated refinery-petrochemical scale economies at Houston-Galveston and Ulsan complexes compress unit costs for hexane producers, concentrating supply-side pricing power among hydrotreating-capable operators while establishing cost floors that merchant refiners struggle to match. This scale asymmetry bifurcates the market into captive-feedstock price-setters and naphtha-dependent price-takers, with certification burdens further widening the spread between pharmaceutical-grade premiums and commodity-industrial benchmarks.
Pricing Analysis
Current-generation hydrotreating technology commands a 15-20% premium over prior-generation aromatic-tolerant processing, while next-generation bio-based hydrocarbon refining remains pre-commercial and unpriced. Three-tier pricing structure across pharmaceutical, food-contact, and industrial grades dominates, with CDSCO/FDA dual-filing certification and BIS contaminant testing as the primary differentiation drivers. Cost compression in industrial-grade mineral spirits is intensifying because aqueous cleaning systems displace solvent-borne degreasing in automotive assembly. Paint and coatings manufacturers exhibit the highest price sensitivity due to cyclical construction demand, while Indian CMOs under PLI incentives accept premium pharmaceutical-grade pricing for supply security.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade heptane extend beyond eighteen months due to CDSCO excipient certification cycles, constraining spot market liquidity and forcing long-term contract structures. Supply concentrates in the United States, South Korea, and India, with naphtha feedstock, hydrotreating catalysts, and specialized tank farm infrastructure as critical input dependencies. Single-source vulnerability around FDA-audited manufacturing sites for high-purity grades exposes buyers to regulatory inspection delays. Distribution runs through specialty chemical distributors with dedicated solvent storage terminals at Hyderabad and Visakhapatnam API clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aliphatic Solvents Market tracks a cyclical recovery anchored to North American housing construction rebounds and Indian API localization under PLI fiscal incentives. Stakeholders should position for sustained pharmaceutical-grade demand premiums while managing feedstock volatility exposure.
For Market Incumbents: Consolidate hydrotreating capacity at integrated refinery-petrochemical complexes to defend against naphtha price volatility eroding merchant refiner margins. Lock in three-year master service agreements with Indian CMOs like Divi's Laboratories and Laurus Labs, embedding penalty clauses for batch-to-batch variation to secure pharmaceutical-grade offtake. Prioritize backward integration into naphtha supply or captive feedstock production to reduce Brent crude benchmark exposure. For New Entrants and Emerging Players: CDSCO fast-track certification for excipient-grade solvents opens white-space entry for domestic Indian producers serving Hyderabad and Visakhapatnam API clusters. Target food-contact mineral spirits for Indian packaging applications where BIS purity mandates redirect procurement from imports. Pursue joint venture structures with established distributors possessing dedicated tank farm infrastructure to bypass capital-intensive terminal retrofits. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty refiners with hydrotreating capability and pharmaceutical-grade certification infrastructure over commodity naphtha blenders. Long-term viability across the projection horizon hinges on fluorine-free formulation positioning as PFAS restrictions expand in electronics cleaning. Watch ECHA enforcement guidance on polycyclic aromatic hydrocarbon limits as the signal for accelerated low-PAH extender oil qualification demand in EU tire manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Supply | Captive feedstock access at Houston-Galveston complexes insulates margin from Brent crude volatility. |
| Pharmaceutical-Grade Certification Investment | CDSCO/FDA dual-filing capability locks multi-year contracts with Indian PLI-scheme API manufacturers. |
| Fluorine-Free Formulation Development | PFAS-free solvent certification captures electronics cleaning applications previously dominated by fluorinated chemistries. |
| Dedicated Tank Farm Infrastructure Expansion | Segregated storage for purity grades at port terminals enables just-in-time delivery to pharmaceutical CMOs. |
| Long-Term Supply Agreement with Indian CMOs | Fixed-price contracts with Divi's Laboratories and Laurus Labs secure volume offtake above ten thousand metric tons annually. |
Methodological Framework
Operator-level perspectives from refinery operations managers, pharmaceutical procurement leads at Indian CMOs, specialty chemical distribution channel partners, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from customs/trade data, SEC 10-K filings of integrated petrochemical majors, CDSCO excipient registration databases, and Cefic solvent market reports. Bottom-up capacity modeling across hydrotreating units and top-down demand triangulation through end-use industry consumption patterns ensured cross-verified outputs.
Sensitivity analysis tested forecast robustness across crude oil price scenarios, PLI scheme continuation assumptions, and REACH restriction enforcement intensities. Segmentation dimensions modeled include purity grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from compound growth trajectory analysis incorporating capacity utilization rates, import substitution elasticities, and pharmaceutical formulation standard evolution. Industry-specific inputs encompassed naphtha-to-solvent yield ratios and certification timeline distributions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued PLI scheme funding assumptions; material deviation would warrant model refresh. Specific risks include abrupt REACH restriction expansion, aqueous cleaning technology acceleration, or crude oil supply disruption revising feedstock cost structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Butane Market
Solvents
Xylene Market
Solvents
Tetraethyl Benzene Market
Solvents
Japan Acetonitrile Market
Solvents
North America Toluene Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Diethanolamide Market
Solvents
Methyl Acetate Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Coating Solvents Market
Solvents
Oxygenated Solvents Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Diethyl Ether Market
Solvents
Mesitylene Market
Solvents
Monochlorobenzene Market
Solvents
Ethyl Pyruvate Market