
 Spirulina Market | 2026-2036
Spirulina Market Size, Share, and Industry Trends Forecast 2026-2036
Spirulina Market Analysis
Phycocyanin extraction expertise is bifurcating the competitive landscape into technology leaders and commodity suppliers. Cyanotech Corporation leverages its Hawaiian cultivation infrastructure to sustain premium positioning in natural astaxanthin and spirulina co-production. DIC Corporation anchors Japanese market access through its integrated microalgae biotechnology platform. Earthrise Nutritionals LLC dominates North American bulk supply through its California-based open-pond systems.
Spirulina denotes a filamentous cyanobacterium (Arthrospira platensis and Arthrospira maxima) containing protein concentrations of 60-70% dry weight, phycocyanin pigments, and gamma-linolenic acid, cultivated through open-pond or closed photobioreactor systems for nutritional and colorant applications. Powder formulations occupy the largest volume share due to manufacturing scalability and blending flexibility across food matrices. Dietary supplements represent the fastest-expanding application segment as athletes and health-conscious consumers prioritize plant-based protein alternatives. Organic sourcing commands premium positioning, though conventional cultivation sustains cost-competitive supply for animal feed integration.
FDA dietary supplement cGMPs, EU Novel Food Catalogue listings, and USDA National Organic Program standards collectively govern spirulina product claims, purity thresholds, and import eligibility across major consumption markets. India's FSSAI and CDSCO are tightening nutraceutical labeling requirements while expanding PLI scheme incentives for domestic microalgae production capacity. Stakeholders must monitor evolving novel food approvals and organic certification reciprocity agreements to secure sustained market access.
Market Dynamics
Phycocyanin extraction technology is bifurcating competitive positioning, separating technology leaders with advanced bioreactor capabilities from commodity suppliers reliant on conventional open-pond cultivation. This structural divide is reshaping margin distribution and procurement relationships across nutritional and colorant applications.
Growth Catalysts
- EU Novel Food Catalogue expansion:Streamlined approval pathways for spirulina-derived ingredients are accelerating functional food launches across member states, with EFSA safety assessments reducing time-to-market for new formulations.
- Plant-based protein substitution:Sports nutrition and clean-label beverage manufacturers are reformulating with spirulina protein concentrates to meet athlete demand for allergen-free, complete amino acid profiles.
- India PLI scheme incentives:Domestic microalgae production capacity is expanding through government production-linked incentives targeting nutraceutical self-sufficiency and ayurvedic product integration.
Market Restraints
- Arthrospira cultivation concentration:Premium spirulina supply clusters in specific climatic zones with consistent solar exposure, creating geographic vulnerability to weather disruption and transport cost volatility.
- Phycocyanin stability limitations:Natural blue pigment degradation under thermal processing and acidic pH conditions restricts application breadth in heat-treated beverages and low-pH formulations.
- EU organic import reciprocity gaps:Non-EU cultivation facilities face certification recognition barriers that complicate premium positioning for USDA Organic and equivalent third-country suppliers.
Strategic Opportunities
- India domestic consumption expansion:Underpenetrated Tier-2 and Tier-3 cities present whitespace for spirulina tablet and powder distribution through pharmacy and ayurvedic retail networks.
- Precision fermentation convergence:Hybrid production models combining photobioreactor cultivation with metabolic engineering are opening recombinant phycocyanin pathways for pharmaceutical-grade applications.
- FSSAI nutraceutical labeling clarity:India's tightening regulatory framework for health claims is creating first-mover advantage for compliant domestic manufacturers with established quality documentation.
Industry Challenges
- Photobioreactor engineering talent scarcity:Specialized expertise in closed-system algae cultivation, harvesting automation, and contamination control remains concentrated among limited technical training programs.
- Dual certification timeline compression:Simultaneous pursuit of EU Novel Food approval and USDA Organic certification demands parallel documentation streams that strain smaller cultivation operations.
- Contamination detection integration:Real-time monitoring for heavy metals, microcystins, and bacterial pathogens requires capital-intensive analytical infrastructure that raises operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirulina Market |
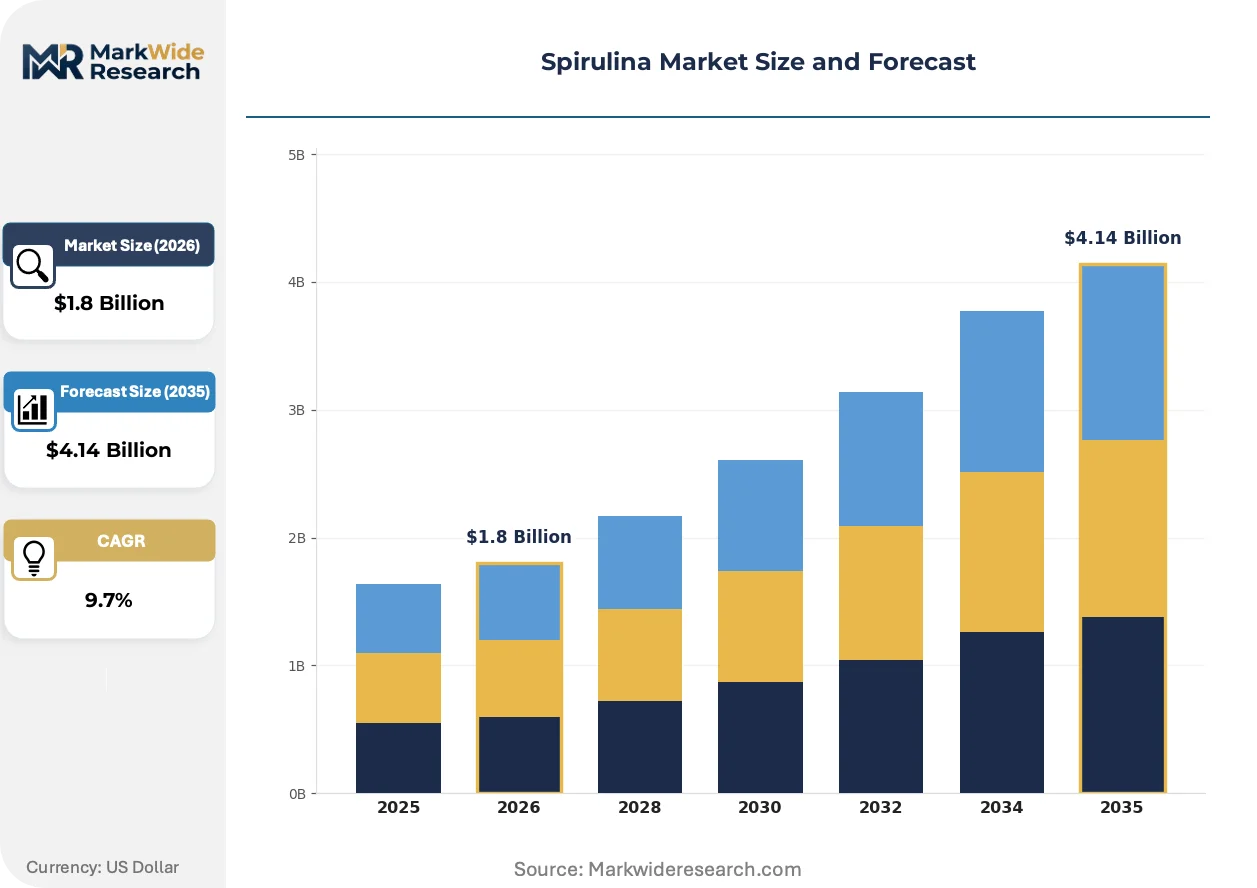
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablets, Flakes, Extracts Application: Dietary Supplements, Food & Beverages, Animal Feed, Cosmetics Source: Organic, Conventional, Blue-Green Algae, Others End User: Health-conscious Consumers, Athletes, Healthcare Facilities, Food Manufacturers |
| Companies Covered | Cyanotech Corporation, DIC Corporation, Chr. Hansen Holding A/S, Fuqing King Dnarmsa Spirulina Co., Ltd., Sensient Technologies Corp., Earthrise Nutritionals LLC, Parry Nutraceuticals Limited, Prolgae Spirulina Supplies Pvt. Ltd., Dohler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirulina Market Emerging Trajectories
Bioprocessing infrastructure is fragmenting along cultivation-system lines, with closed photobioreactors gaining traction in pharmaceutical-grade applications while open-pond systems defend commodity feed and bulk nutraceutical supply. This technological divergence is creating distinct competitive ecosystems with incompatible scale economics.
Closed photobioreactor technology is fragmenting the traditional open-pond dominance in high-value spirulina segments. Pharmaceutical and cosmetic formulators are adopting these systems for contaminant-controlled phycocyanin supply. The technology is fragmenting procurement patterns, with premium buyers now requiring batch-level traceability that open-pond operators cannot economically provide.
REACH and EU Green Deal sustainability reporting requirements are tightening carbon footprint disclosure for imported spirulina ingredients. European food manufacturers now demand cultivation energy intensity documentation and water usage certifications from non-EU suppliers. Organic and natural colorant segments are responding by investing in lifecycle assessment capabilities and renewable-powered production facilities.
Direct-to-brand sourcing is displacing traditional ingredient distributor intermediation in North American and European spirulina procurement. Large food and supplement manufacturers are establishing direct relationships with cultivation operations to secure volume commitments and co-development partnerships. This pattern is most visible in sports nutrition and functional beverage verticals where formulation specificity demands technical collaboration.
Spirulina Market Segmentation
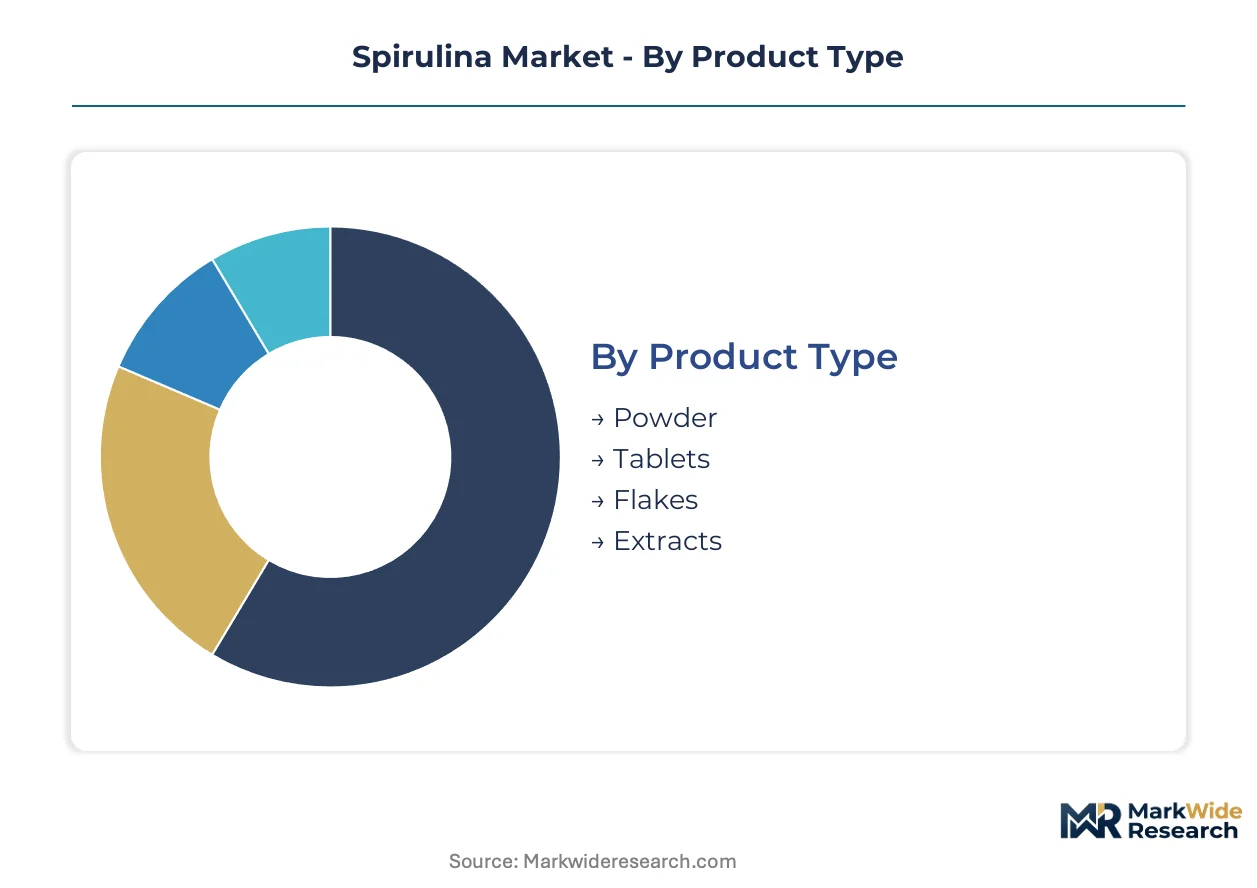
Spirulina procurement patterns diverge sharply across formulation types and end-use specifications. Manufacturers must align cultivation system investments with segment-specific purity thresholds and certification requirements.
Product Type:
Powder substitutes threaten tablet and flake formats most acutely in bulk nutraceutical applications, where blending flexibility outweighs convenience positioning.
- Powder:Dry-milled biomass with 60-70% protein concentration enables seamless integration across beverage, bakery, and supplement matrices. Health-conscious consumers in India and Germany drive bulk procurement for home formulation and ayurvedic compounding.
- Tablets:Compressed dosing units standardize intake for athletes and clinical protocols. Sports nutrition brands in the US and Japan specify disintegration rates and excipient-free binding to secure cGMP and PMDA compliance.
- Flakes:Dehydrated whole-cell fragments serve as visual texture elements in premium snack and salad categories.
- Extracts:Phycocyanin-concentrated liquid and powder isolates target natural colorant applications with EFSA Novel Food clearance.
Powder retains volume leadership; Extracts hold the steepest expansion curve.
Application:
Cost tier stratification separates premium human-grade segments from commodity animal feed supply chains with incompatible margin structures.
- Dietary Supplements:Encapsulated and tablet formats deliver standardized phycocyanin and protein dosing for athletic recovery and immune support. Athletes in Australia and South Korea prioritize third-party tested, contaminant-screened products with TGA and MFDS registration.
- Food & Beverages:Natural blue colorant demand from clean-label beverage formulators accelerates phycocyanin extract incorporation. EU manufacturers navigate EFSA usage limits and thermal stability constraints in heat-treated applications.
- Animal Feed:Bulk biomass supply for aquaculture and poultry protein fortification operates on conventional cultivation cost structures.
- Cosmetics:Antioxidant and pigment properties support topical serum and mask formulations with dermatological testing requirements.
Dietary Supplements command the highest margin tier; Food & Beverages is climbing fastest on colorant substitution.
Source:
Volume concentration in conventional cultivation creates supply vulnerability for organic-certified finished goods.
- Organic:USDA National Organic Program and EU 2018/848 compliance mandates open-pond or photobioreactor systems with prohibited substance exclusion. German and French retailers demand full chain-of-custody documentation for premium positioning.
- Conventional:Standard cultivation without synthetic input restrictions supplies cost-sensitive feed and bulk nutraceutical markets.
- Blue-Green Algae:Arthrospira and Aphanizomenon species differentiation matters for toxin screening protocols.
- Others:Mixed microalgae biomass and experimental strains occupy niche research and specialty feed applications.
Conventional dominates tonnage; Organic posts the sharpest value-per-kilogram gains.
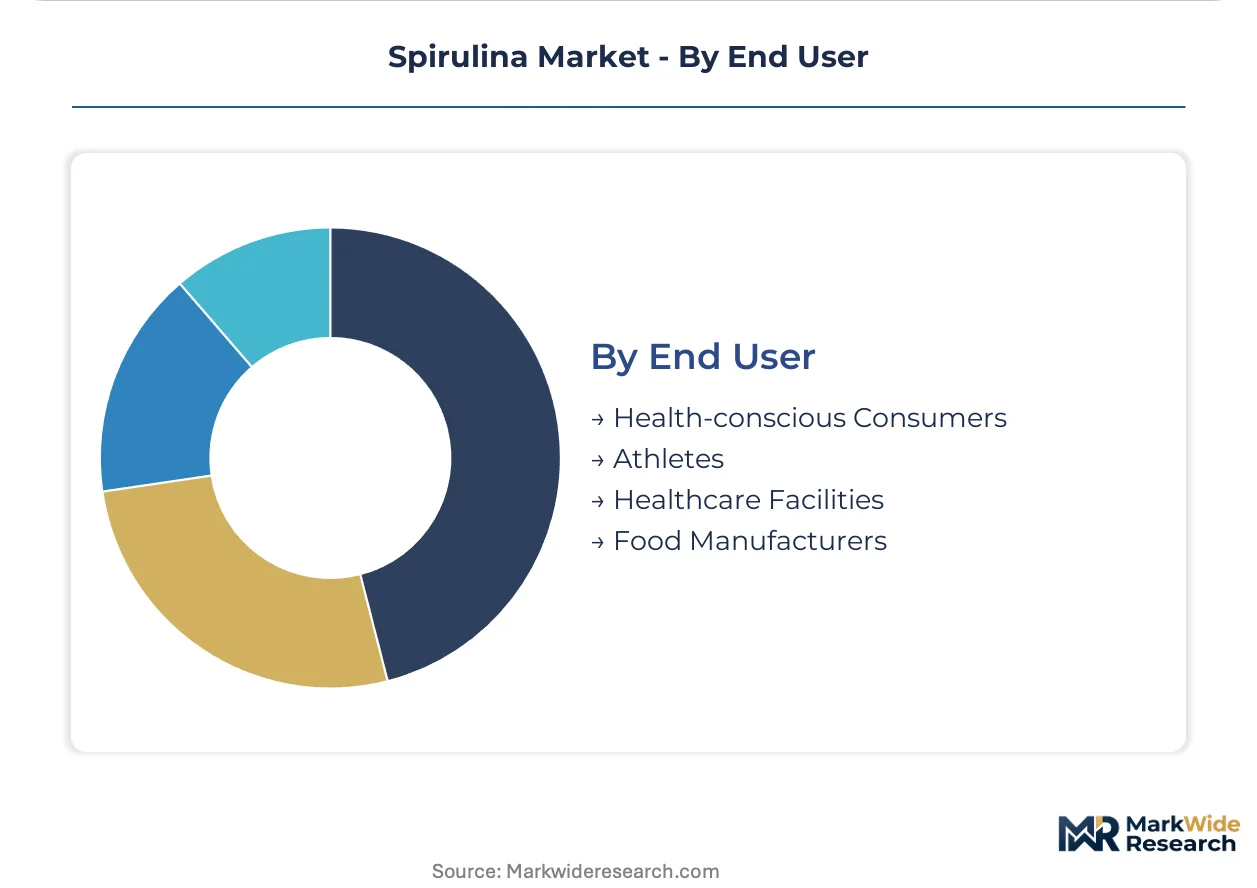
End User:
Customer type fragmentation splits procurement between direct-to-consumer wellness channels and industrial ingredient supply.
- Health-conscious Consumers:Direct retail purchasers prioritize organic certification, origin transparency, and convenient dosing formats. Pharmacy and ayurvedic retail networks in India target Tier-2 and Tier-3 city expansion.
- Athletes:Performance-oriented buyers demand batch-tested protein content, heavy metal screening, and banned substance certification from NSF or Informed Sport programs.
- Healthcare Facilities:Clinical nutrition and integrative medicine protocols require pharmaceutical-grade documentation and stability data.
- Food Manufacturers:Industrial buyers specify color consistency, solubility profiles, and scalable volume commitments for reformulation projects.
Health-conscious Consumers anchor retail volume; Athletes generate the most rapid specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes spirulina predominantly through ayurvedic pharmacy channels and traditional medicine compounding, while Germany and the United States prioritize sports nutrition powders and clean-label beverage colorants. This consumption-mix differential shapes divergent regulatory compliance burdens and distribution infrastructure investments across major markets.
United States
Athletes and functional beverage formulators drive powder and tablet procurement through direct-to-brand relationships with California cultivation operations. FDA dietary supplement cGMPs and NSF Certified for Sport programs enforce batch-level contaminant screening and banned substance verification. The Imperial Valley and Mojave Desert host open-pond facilities supplying bulk biomass to sports nutrition brands in Utah and Colorado.
Germany
Clean-label food manufacturers and organic retailers command phycocyanin extracts with full EU 2018/848 organic chain-of-custody documentation. EFSA Novel Food approvals and REACH sustainability reporting requirements govern import eligibility and carbon footprint disclosure. Bavaria and Baden-Württemberg concentrate natural colorant formulation labs serving pan-European beverage clients.
India
Domestic nutraceutical consumption and ayurvedic product integration expand through Tier-2 and Tier-3 pharmacy networks in Tamil Nadu and Gujarat. FSSAI nutraceutical labeling requirements and CDSCO quality standards tighten while PLI scheme incentives accelerate domestic microalgae production capacity. Chennai and Ahmedabad host tablet manufacturing clusters serving ayurvedic distribution channels.
Japan
Health-conscious consumers and aging demographics sustain premium spirulina tablet demand through pharmacy and convenience retail channels. PMDA and Ministry of Health, Labour and Welfare standards govern functional food claims and import purity thresholds. The Chubu region around Nagoya concentrates supplement formulation operations with technical collaboration from domestic biotechnology platforms.
Australia
Athletes and wellness consumers prioritize third-party tested products with TGA registration and heavy metal screening certifications. Sports nutrition brands in Sydney and Melbourne specify disintegration rates and excipient-free binding for clinical protocol alignment. Queensland and Western Australia host cultivation operations leveraging consistent solar exposure for biomass production.
Spirulina Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cultivation-system capabilities and certification breadth determining competitive positioning. Technology leaders with closed photobioreactor infrastructure command pharmaceutical-grade phycocyanin premiums, while commodity suppliers defend bulk nutraceutical and animal feed supply through open-pond scale economics. Two strategic archetypes dominate: integrated biotechnology platforms with multi-product microalgae portfolios, and regionally anchored cultivation specialists with direct-to-brand distribution relationships. Capacity expansion in India and certification reciprocity negotiations in Europe represent the dominant competitive moves reshaping procurement patterns.
Within the integrated biotechnology tier, Cyanotech Corporation and DIC Corporation exemplify cultivation infrastructure leveraged across natural astaxanthin and spirulina co-production. Earthrise Nutritionals LLC occupies a position among North American bulk supply specialists with California-based open-pond operations. Sensient Technologies Corp. and Chr. Hansen Holding A/S represent natural colorant and ingredient technology platforms with formulation expertise serving food and beverage manufacturers. Fuqing King Dnarmsa Spirulina Co., Ltd. anchors Chinese supply capacity, while Parry Nutraceuticals Limited and Prolgae Spirulina Supplies Pvt. Ltd. exemplify India-based specialists targeting domestic nutraceutical and ayurvedic integration channels.
| Leading Market Players |
|---|
| Cyanotech Corporation |
| DIC Corporation |
| Chr. Hansen Holding A/S |
| Fuqing King Dnarmsa Spirulina Co., Ltd. |
| Sensient Technologies Corp. |
| Earthrise Nutritionals LLC |
| Parry Nutraceuticals Limited |
| Prolgae Spirulina Supplies Pvt. Ltd. |
| Dohler Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between California cultivation operations and North American sports nutrition brands lock in biomass supply visibility while insulating premium-grade spirulina from spot-market volatility in conventional feed-grade channels. These contractual structures anchor price predictability for buyers seeking cGMP-compliant, batch-traceable powder while leaving commodity suppliers exposed to open-pond yield fluctuations.
Pricing Analysis
Contract-based long-term offtake dominates premium human-grade supply, with three-tier pricing structure across organic-certified, conventional food-grade, and feed-grade levels. Price differentiation rests on phycocyanin concentration thresholds and dual certification status, with EU Novel Food and USDA Organic compliance commanding substantial premiums. Cost compression in conventional feed-grade biomass is intensifying because Indian domestic capacity expansion under PLI incentives floods commodity channels. Animal feed integrators exhibit highest price sensitivity, while pharmaceutical-grade phycocyanin extract buyers prioritize batch consistency over unit cost.
Supply Chain Analysis
India and the United States anchor spirulina biomass production, with China supplying downstream processing equipment and phycocyanin extraction technology. Raw material dependencies center on sodium bicarbonate culture media, magnesium sulfate nutrients, and polyethylene photobioreactor sheeting. Single-source vulnerability concentrates in Hawaiian open-pond operations serving premium natural colorant demand. Distribution runs through direct-to-brand procurement relationships displacing traditional ingredient distributors in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed photobioreactor engineering expertise and contamination control protocols represent acute capability gaps constraining pharmaceutical-grade supply expansion. Cultivation operations with proven batch-level traceability systems command disproportionate procurement leverage as formulation specificity demands escalate.
For Market Incumbents: Secure backward integration into photobioreactor manufacturing to reduce capital intensity barriers for capacity expansion. Defend margin position by accelerating EU Novel Food approval timelines ahead of reciprocity agreement shifts that could disadvantage non-EU organic suppliers. Prioritize cultivation automation investments to offset engineering talent scarcity in closed-system operations. For New Entrants and Emerging Players: Differentiate on precision fermentation convergence for recombinant phycocyanin pathways targeting pharmaceutical applications. Target Tier-2 and Tier-3 pharmacy networks in India where ayurvedic product integration remains underpenetrated and FSSAI labeling clarity creates first-mover advantage for compliant domestic manufacturers. Pursue technical collaboration partnerships with established biotechnology platforms rather than greenfield cultivation investments. For Investors and Strategic Acquirers: Regional cultivation specialists with direct-to-brand distribution relationships and established quality documentation represent the most defensible acquisition archetype. Long-term viability hinges on certification breadth rather than volume scale, with dual EU-USDA organic compliance serving as the critical moat. Watch for FSSAI enforcement actions against non-compliant labeling as an inflection indicator for domestic Indian manufacturer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Enables contaminant-controlled phycocyanin supply for pharmaceutical-grade applications with batch traceability. |
| Dual Certification Investment | Secures EU Novel Food and USDA Organic compliance to defend premium positioning against reciprocity barriers. |
| Direct-to-Brand Sourcing Relationships | Displaces distributor intermediation through technical collaboration on formulation specificity with sports nutrition manufacturers. |
| Precision Fermentation Convergence | Opens recombinant phycocyanin pathways for heat-stable, low-pH applications beyond natural pigment limitations. |
| India PLI Scheme Utilization | Captures government production-linked incentives targeting nutraceutical self-sufficiency and ayurvedic integration channels. |
Methodological Framework
A standing panel of cultivation operations managers, sports nutrition procurement directors, regulatory affairs specialists at nutraceutical firms, and ayurvedic pharmacy chain buyers provided ongoing calibration across primary fieldwork phases. Secondary validation drew from FDA cGMP inspection databases, EFSA Novel Food approval registers, FSSAI labeling compliance notices, USDA organic certification records, and CDSCO quality standard circulars. Bottom-up volume estimates from cultivation facility capacity were triangulated against top-down demand projections from end-use segment consumption patterns.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation modeling incorporated product type, application category, certification source, and end-user archetype dimensions. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and regulatory approval timelines. Forecast inputs included PLI scheme disbursement schedules, EU organic import reciprocity negotiation status, and photobioreactor installation pipeline data.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement, EU Novel Food approval pathways, and FSSAI nutraceutical labeling regimes; material policy shifts would require re-modeling of import eligibility and premium positioning assumptions. Recalibration cycles align with material shifts in novel food approval timelines, organic certification reciprocity agreements, and domestic production incentive disbursements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Gluten Replacer Market