
 Global AI in Banking Market | 2026-2036
Global AI in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI in Banking Market Foresight
Consolidation among tier-one retail banks is recalibrating procurement patterns for enterprise AI platforms. JPMorgan Chase & Co. leverages its proprietary data infrastructure to anchor in-house model development. NVIDIA Corporation competes through specialized silicon architectures optimized for financial workload acceleration. Amazon Web Services, Inc. controls cloud distribution channels that dominate deployment preferences among mid-sized institutions.
Global AI in banking encompasses machine learning systems, natural language processing engines, and robotic process automation tools that ingest transactional data, generate predictive insights, and execute decisions with minimal human intervention. These technologies process millions of data points in milliseconds to detect anomalies, assess creditworthiness, and automate customer interactions. Fraud detection and risk management applications command the largest current revenue pools, while customer service automation represents the fastest-expanding segment as conversational interfaces displace traditional call center operations. Cloud-based deployment is displacing on-premises infrastructure among institutions seeking elastic compute capacity without capital-intensive hardware commitments.
The EU AI Act imposes strict transparency and human oversight requirements on credit-scoring algorithms, compelling European banks to redesign model governance frameworks. In the United States, the SEC and banking regulators scrutinize AI-driven trading and advisory systems for fiduciary compliance and systemic risk. India's RBI has issued draft guidelines on algorithmic transparency for digital lenders, reflecting broader emerging-market regulatory momentum. Stakeholders must monitor divergence between prescriptive European rules and principles-based American oversight when architecting cross-border AI strategies.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for AI infrastructure across retail and investment banking, forcing institutions to choose between capital-intensive in-house development and vendor-dependent subscription models.
Growth Catalysts
- EU AI Act compliance mandates:European banks must implement explainable credit-scoring systems, creating immediate procurement demand for model governance platforms and audit-ready documentation tools.
- Real-time payment networks:FedNow and equivalent instant settlement systems in Brazil, India, and Singapore generate transaction volumes requiring AI-powered anomaly detection at millisecond latency.
- Neuromorphic silicon:Specialized inference chips reduce energy consumption for branch-level fraud detection, enabling deployment in markets with unreliable grid infrastructure.
Market Restraints
- GPU supply concentration:Taiwan Semiconductor Manufacturing Company fabricates over 90 percent of advanced AI accelerators, exposing banks to geopolitical disruption in the Taiwan Strait.
- Data localization requirements:China's Cybersecurity Law and Russia's data sovereignty rules prevent cross-border model training, fragmenting R&D economies of scale.
- Interpretability trade-offs:Deep learning architectures for anti-money laundering sacrifice explainability for accuracy, conflicting with supervisory expectations for algorithmic transparency.
Strategic Opportunities
- Embedded finance in Indonesia:Super-app platforms Gojek and Grab partner with rural banks to deploy lightweight AI credit models for unbanked micro-merchants.
- Quantum-resistant cryptography:NIST post-quantum standards drive replacement cycles for encryption key management, opening adjacent AI security procurement.
- Conversational AI + biometric fusion:Voice authentication layered with natural language understanding reduces call center fraud while compressing customer verification times.
Industry Challenges
- MLOps talent scarcity:Production deployment of banking AI requires engineers fluent in both financial risk modeling and Kubernetes orchestration, a combination rare outside London, New York, and Singapore.
- Core banking integration:COBOL-era transaction engines resist API connectivity, forcing middleware investments that delay AI ROI realization by 18-24 months.
- Model drift monitoring:Shifting consumer behavior during economic stress invalidates training data distributions, requiring continuous revalidation pipelines most institutions lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI in Banking Market |
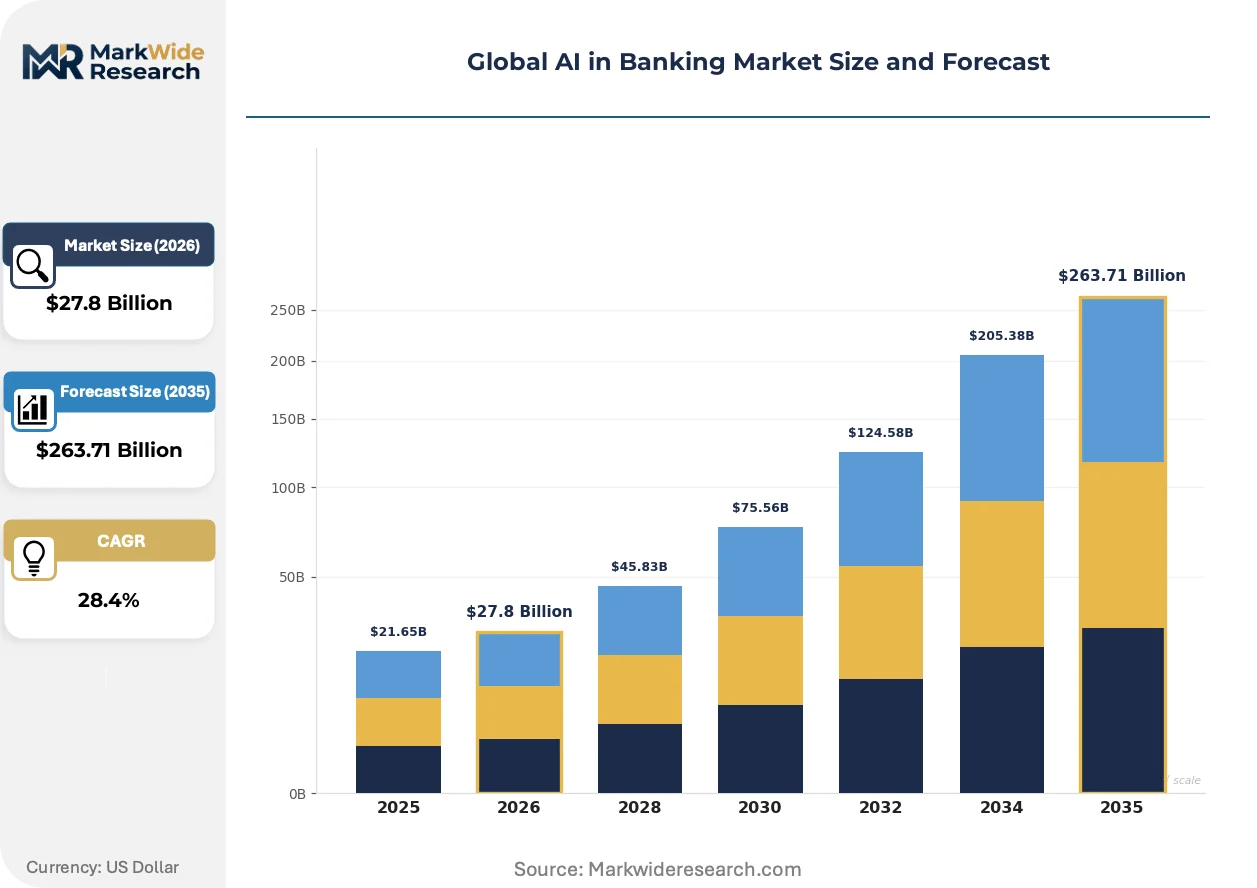
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $263.71 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Credit Scoring, Customer Service Automation, Risk Management Technology: Machine Learning, Natural Language Processing, Robotic Process Automation, Cognitive Computing Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Retail Banks, Investment Firms, Credit Unions, Payment Processors |
| Companies Covered | JPMorgan Chase & Co., Capital One, Goldman Sachs, International Business Machines Corporation, Amazon Web Services, Inc., NVIDIA Corporation, SAP SE, FAIR ISAAC CORPORATION, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI in Banking Market Shifts & Advancements
Foundation models trained on synthetic financial data are compressing the cost of domain-specific AI development, while regulatory sandboxes in multiple jurisdictions accelerate deployment of experimental algorithms.
Large language models fine-tuned on regulatory filings and earnings transcripts are expanding into investment research and compliance documentation workflows. Tier-one asset managers deploy these systems to generate first-draft analyst reports and flag disclosure inconsistencies. The technology is expanding into retail robo-advisory, compressing the cost of personalized portfolio commentary.
The EU AI Act's risk-based classification system imposes mandatory conformity assessments on credit-scoring and insurance pricing algorithms. European banks must maintain technical documentation, human oversight protocols, and accuracy metrics subject to market authority audit. Mid-sized institutions in Germany and France are responding by consolidating vendor relationships to reduce compliance fragmentation.
Buyers now demand consumption-based pricing for AI infrastructure rather than perpetual licenses or capital-intensive hardware purchases. Cloud service providers displace traditional enterprise software vendors in procurement evaluations for fraud detection and customer analytics. This shift is most visible among regional banks in the United States seeking to avoid data center expansion costs.
Global AI in Banking Market Segmentation
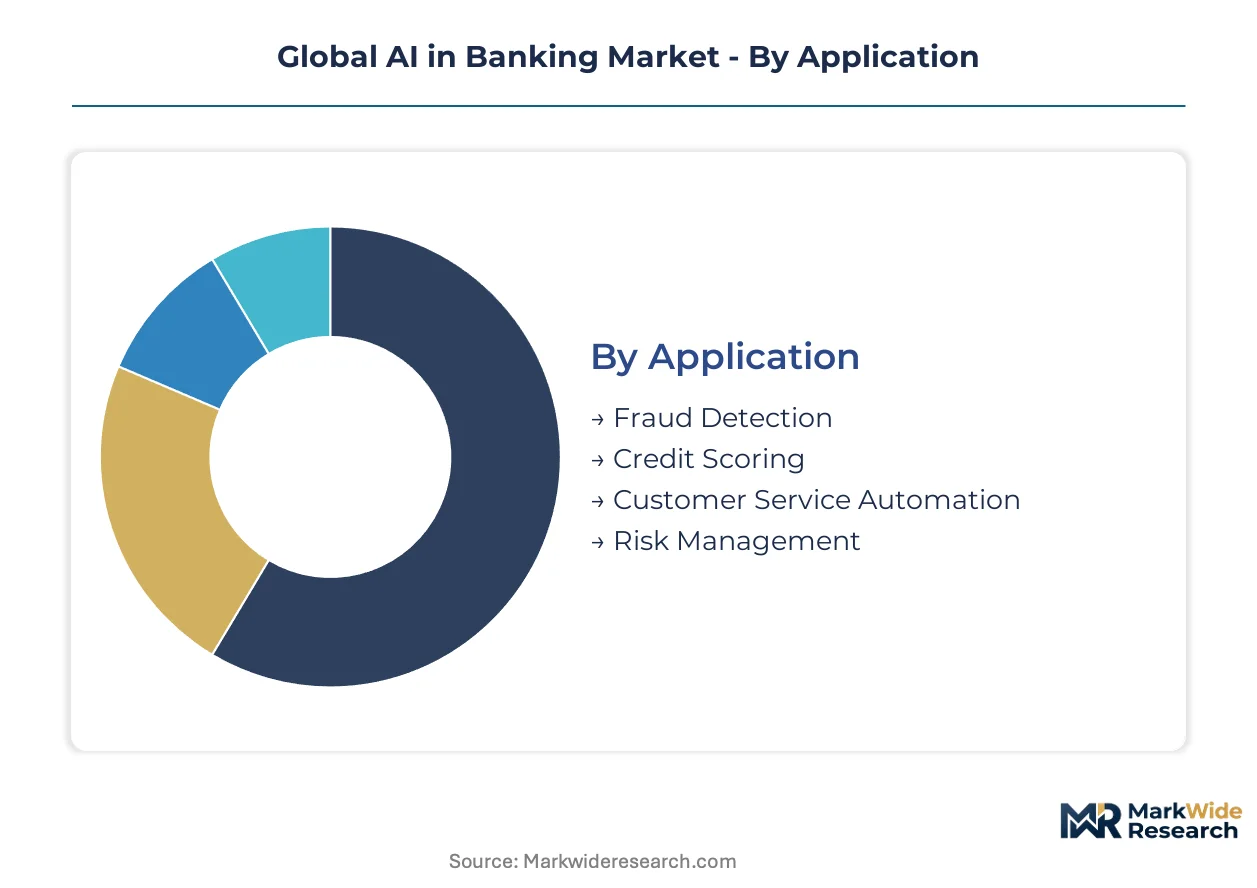
Banking AI deployments vary dramatically in architectural depth, from standalone point solutions to deeply embedded transaction engines. Understanding these integration patterns reveals where procurement budgets concentrate and which vendors capture recurring revenue versus one-time implementation fees.
Application:
Standalone modules dominate initial deployments, while embedded systems require core banking overhauls that stretch timelines by 18-24 months.
- Fraud Detection:Real-time transaction monitoring systems ingest millions of payment events per second, flagging anomalies through pattern recognition algorithms. JPMorgan Chase deploys proprietary models across its retail network, while mid-sized institutions license cloud-native alternatives from AWS and Google Cloud. Volume placements concentrate in fraud detection; the faster expansion belongs to customer service automation.
- Credit Scoring:Alternative data ingestion engines assess borrower risk beyond traditional FICO metrics, incorporating utility payments, rental history, and behavioral biometrics. European banks redesign these systems under EU AI Act transparency mandates, creating immediate procurement demand for explainable AI platforms. Demand concentrates among digital lenders in Indonesia and Brazil seeking to underwrite unbanked populations.
- Customer Service Automation:Conversational interfaces displace call center operations through voice and chatbot deployment.
- Risk Management:Portfolio stress-testing and market risk calculation engines automate regulatory capital reporting.
Procurement cycles for fraud detection compress to 6-9 months; credit scoring implementations stretch to 24 months due to model governance requirements.
Technology:
Cost tiers separate capital-intensive model training infrastructure from lightweight inference deployment at branch level.
- Machine Learning:Supervised and unsupervised learning frameworks power predictive analytics across lending, trading, and operations. Gradient-boosted decision trees dominate credit scoring for interpretability, while deep neural networks handle unstructured document processing. Tier-one banks maintain dedicated ML engineering teams exceeding 500 personnel.
- Natural Language Processing:Transformer architectures fine-tuned on financial corpora extract entities from regulatory filings, earnings transcripts, and customer communications. NVIDIA's NeMo framework accelerates deployment for institutions lacking in-house NLP expertise. Demand concentrates in asset management for research automation and compliance documentation.
- Robotic Process Automation:Rule-based bots automate repetitive back-office workflows without machine learning complexity.
- Cognitive Computing:Hybrid symbolic-neural systems attempt structured reasoning over financial knowledge graphs.
Machine learning claims the largest current spend; NLP is climbing the fastest as large language models penetrate investment research workflows.
Deployment:
Customer type dictates infrastructure choice — global systemically important banks favor hybrid architectures while regional institutions skip straight to cloud.
- Cloud-Based:Elastic compute consumption eliminates data center capital expenditure, with pay-per-inference pricing attractive to sub-$50 billion asset institutions. AWS, Azure, and Google Cloud compete aggressively through specialized financial services compliance certifications. Regional banks in the United States and Germany dominate current migrations.
- Hybrid:Sensitive model training occurs on-premises while inference scales through cloud burst capacity. This architecture satisfies data residency requirements in India and Saudi Arabia while capturing elasticity benefits. Tier-one institutions in London and Singapore lead hybrid adoption.
- On-Premises:Legacy mainframe environments persist at institutions with decades-old core banking investments.
- Edge Computing:Branch-level inference enables real-time fraud decisions without network latency to central data centers.
Hybrid deployments dominate among the twenty largest global banks; cloud-native expansion is steepest among mid-tier institutions seeking to avoid infrastructure technical debt.
End User:
Margin structures vary sharply — investment firms pay premium pricing for latency-sensitive execution algorithms while credit unions seek standardized SaaS packages.
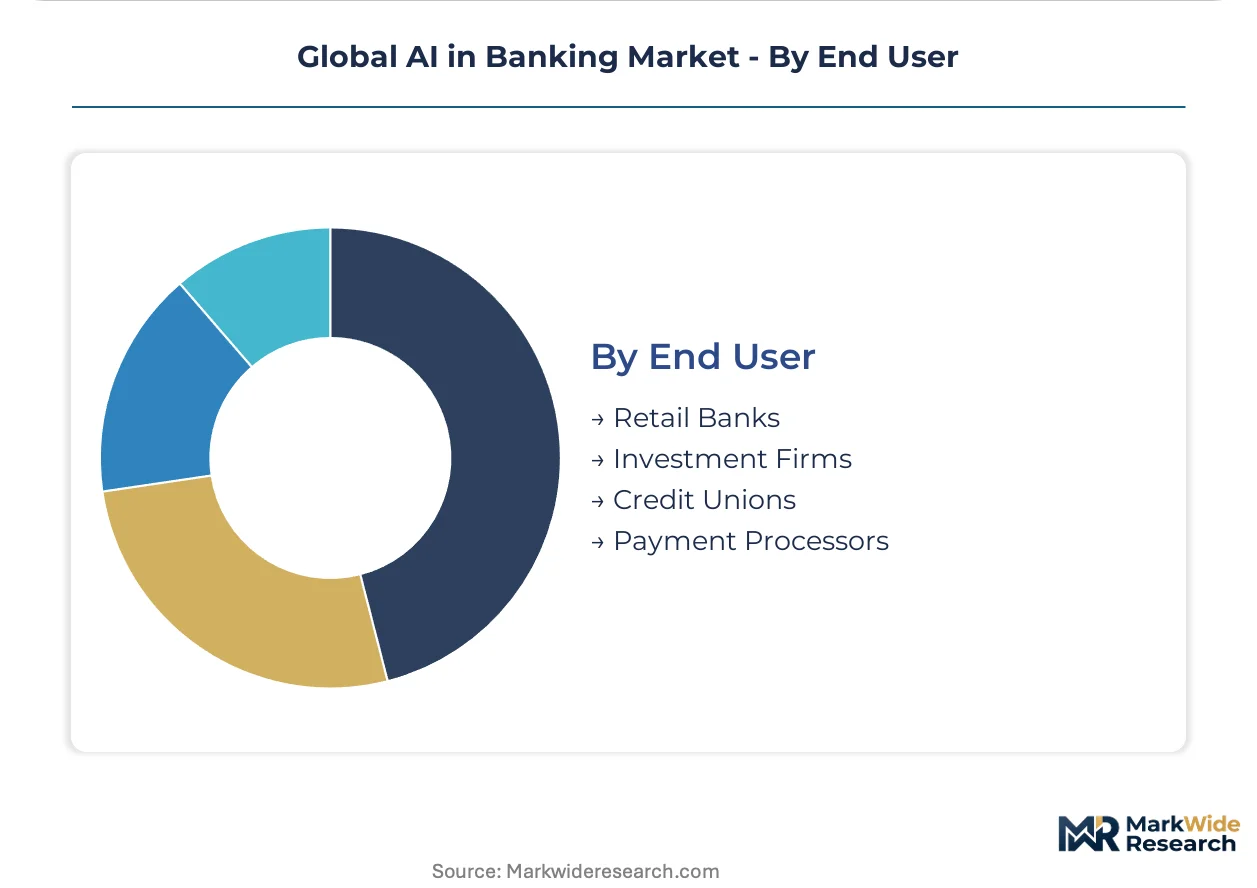
- Retail Banks:Consumer-facing institutions deploy AI across the full application spectrum, from chatbots to mortgage underwriting. Scale advantages concentrate among the largest institutions: JPMorgan Chase processes over 350 million AI-powered risk decisions annually. Procurement budgets exceed $100 million annually at tier-one institutions.
- Investment Firms:Hedge funds and asset managers prioritize alpha generation through alternative data ingestion and execution optimization. Quantitative strategies at Two Sigma and Citadel drive demand for specialized hardware accelerators and low-latency data feeds.
- Credit Unions:Member-owned institutions adopt pre-configured AI modules through core banking vendor partnerships.
- Payment Processors:Visa and Mastercard deploy network-level fraud detection across billions of transactions.
Retail banks generate the largest absolute AI spend; investment firms show the fastest budget growth as generative AI penetrates research and advisory functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States institutions command the largest procurement budgets for enterprise AI infrastructure, with venture capital availability and cloud hyperscaler presence concentrating development activity in New York and San Francisco.
United States
FedNow instant payment networks and real-time settlement infrastructure drive demand for millisecond-latency fraud detection systems. SEC scrutiny of AI-driven advisory platforms compels fiduciary compliance investments across registered investment advisers. New York's financial district anchors deployment of proprietary risk models at JPMorgan Chase, while San Francisco Bay Area fintechs license cloud-native alternatives from AWS and Google Cloud.
Germany
EU AI Act transparency mandates force redesign of credit-scoring algorithms across Sparkasse and Volksbanken networks. BaFin supervisory expectations require human-in-the-loop protocols for automated lending decisions. Frankfurt's banking cluster concentrates procurement of explainable AI platforms, with Commerzbank and Deutsche Bank consolidating vendor relationships to reduce compliance fragmentation.
United Kingdom
Open Banking API proliferation generates transactional data volumes requiring AI-powered customer analytics. Bank of England prudential guidance scrutinizes algorithmic trading systems for systemic risk contribution. London's Square Mile hosts specialized MLOps talent pools exceeding 500 engineers at tier-one institutions, drawing fintech entrants from Berlin and Paris.
Singapore
Cross-border payment corridors linking ASEAN markets demand network-level fraud detection across Visa and Mastercard processing volumes. Monetary Authority of Singapore regulatory sandboxes accelerate deployment of experimental credit models for unbanked micro-merchants. The city-state's technology district anchors hybrid cloud architectures for regional banks seeking data residency compliance without sacrificing elasticity.
India
Digital lending expansion among PhonePe and Paytm drives alternative data ingestion for credit scoring beyond traditional bureau metrics. RBI draft guidelines on algorithmic transparency compel documentation investments among non-banking financial companies. Mumbai's financial district and Bangalore's technology corridor split AI development between core banking integration and cloud-native inference deployment.
Global AI in Banking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized inference acceleration and vertical SaaS delivery. Tier-one retail banks maintain in-house model development teams exceeding 500 personnel, while mid-sized institutions depend on vendor subscriptions. Three archetypes dominate: proprietary data infrastructure operators, specialized silicon architects, and cloud distribution channel controllers. Consolidation through strategic vendor reduction and M&A activity accelerates as compliance costs rise.
Among United States-based institutions, JPMorgan Chase & Co. exemplifies the proprietary development archetype through captive data infrastructure investment. NVIDIA Corporation occupies a position as specialized silicon architect for financial workload acceleration. Amazon Web Services, Inc. anchors cloud distribution dominance among regional banks seeking consumption-based pricing without capital expenditure commitment.
| Leading Market Players |
|---|
| JPMorgan Chase & Co. |
| Capital One |
| Goldman Sachs |
| International Business Machines Corporation |
| Amazon Web Services, Inc. |
| NVIDIA Corporation |
| SAP SE |
| FAIR ISAAC CORPORATION |
| Cisco Systems, Inc. |
| Others |
Supply & Pricing Matrix
Cloud hyperscaler dominance in AI infrastructure delivery has compressed pricing discipline across the banking sector, as AWS, Microsoft Azure, and Google Cloud leverage scale economics to displace capital-intensive on-premises deployments with consumption-based subscription models.
Pricing Analysis
Volume placements in fraud detection and customer service automation run on per-transaction SaaS tiers, while bespoke credit-scoring implementations command project-based professional services fees. Price differentiation rests on data residency certification levels—EU AI Act-compliant explainable AI platforms extract premiums over black-box alternatives. Pricing pressure stems from GPU supply concentration at Taiwan Semiconductor Manufacturing Company, which constrains inference cost reductions. Regional banks in the United States exhibit acute price sensitivity, whereas tier-one institutions prioritize latency performance over unit economics.
Supply Chain Analysis
Certification gating through FedRAMP, PCI-DSS, and EU AI Act conformity assessments restricts viable silicon and cloud suppliers to a qualified vendor pool. Advanced AI accelerator fabrication concentrates in Taiwan, South Korea, and the United States, with NVIDIA designs dominating financial workload optimization. Supply chains draw from cobalt-intensive memory modules, specialized photolithography equipment, and rare-earth magnet components. Single-source vulnerability at TSMC's advanced node production exposes procurement timelines to geopolitical disruption. Distribution runs through direct hyperscaler contracts for cloud-native institutions and systems integrators for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The banking AI sector occupies a transition phase where cloud-native architectures displace COBOL-era core systems, with generative AI compression of development timelines accelerating procurement cycles for model governance and inference infrastructure.
For Market Incumbents: Lock in proprietary data infrastructure advantages through captive MLOps talent pools exceeding 500 engineers, while consolidating vendor relationships to reduce EU AI Act compliance fragmentation. Defensive moves must address neuromorphic silicon entrants threatening latency advantages in branch-level fraud detection, and cloud hyperscalers eroding margins through consumption-based pricing. Vertical integration into synthetic financial data generation preserves model training autonomy. For New Entrants and Emerging Players: The mid-market pricing gap between JPMorgan-scale proprietary development and regional bank SaaS subscriptions offers white-space entry for vertical AI specialists. Target credit unions and community banks in Germany and the United States seeking pre-configured explainable credit-scoring modules. Indonesia's unbanked micro-merchant segment presents the most penetrable geography for lightweight edge inference deployment. Go-to-market traction requires FedRAMP authorization as table stakes. For Investors and Strategic Acquirers: Distressed-cycle entries favor MLOps tooling specialists with EU regulatory sandbox exposure in Frankfurt and Singapore. Long-term viability across the projection horizon hinges on quantum-resistant cryptography adjacencies and conversational AI-biometric fusion capabilities. Acquisition screening should prioritize firms with active BaFin or MAS sandbox approvals. The signal to watch is NIST post-quantum standard adoption velocity triggering encryption replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | BaFin and ECB scrutiny forces German banks to redesign credit-scoring governance frameworks. |
| Neuromorphic Silicon Partnership | Branch-level inference deployment enables real-time fraud decisions in grid-unreliable markets. |
| Synthetic Financial Data Platform | Foundation model training cost compression accelerates domain-specific AI development cycles. |
| Quantum-Resistant Cryptography Integration | NIST post-quantum standards drive adjacent AI security procurement from tier-one institutions. |
| Conversational AI-Biometric Fusion | Voice authentication layered with NLP reduces call center fraud at JPMorgan-scale deployments. |
Research Methodology
SEC 10-K filings, EU regulatory sandbox disclosures, and hyperscaler financial services capex reports formed the secondary backbone. Primary interviews with chief data officers at tier-one retail banks, MLOps engineering leads at cloud-native fintechs, and procurement directors at regional German Sparkassen validated quantitative assumptions. Bottom-up triangulation against top-down macroeconomic indicators anchored segmentation-level estimates across application, technology, deployment, and end-user dimensions.
Bottom-up modeling of transaction volumes, inference pricing tiers, and professional services attach rates generated value estimates across the projection horizon. Segmentation dimensions included fraud detection versus credit scoring application split, cloud versus hybrid deployment architecture, and retail bank versus investment firm end-user margin structures. CAGRs derived from historical penetration curves adjusted for EU AI Act compliance acceleration and FedNow real-time payment network expansion.
Underlying measurement precision varies by segment; cloud deployment and fraud detection applications carry tighter precision than emerging quantum-resistant cryptography adjacencies. Forecasts reflect assumptions around GPU supply continuity, regulatory sandbox approval velocities, and core banking API modernization timelines. A model refresh is warranted upon material change in Taiwan Strait geopolitical stability or NIST post-quantum standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Bank Kiosk Market
Banking
Russia Data Analytics in Banking Market
Banking
GCC Mobile Banking Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Banking Maintenance Support and Services Market
Banking
Middle East and Africa Neobanking Market
Banking
Third-Party Banking Software Market
Banking
North America Bank Kiosk Market
Banking
Video Banking Service Market
Banking
Germany Banking As a Service Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Bank Guarantee Market
Banking
ATM Market
Banking
Banking Software Market
Banking
Open Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market