
 Banking Software Market | 2026-2036
Banking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Software Market Insights
Cloud distribution channels for banking software is tilting toward SaaS-first partnerships over perpetual license resellers. Fiserv leverages its merchant acquiring network to bundle core banking with payment acceptance tools. Temenos anchors its growth in European and Asia-Pacific markets through API-native architecture. Oracle FLEXCUBE competes aggressively in emerging markets with localized regulatory compliance modules.
Banking software comprises integrated application suites that automate ledger management, transaction processing, risk calculation, and customer-facing digital interfaces through modular microservices or monolithic core architectures. These systems process real-time payment authorization, maintain immutable audit trails, and enforce role-based access controls across branch, mobile, and API endpoints. Core banking platforms still command the largest installed base, yet cloud-based deployment models are capturing the fastest expansion as banks retire mainframe infrastructure. Payment processing modules sit at the center of margin concentration because transaction volume scales directly with SaaS revenue recognition.
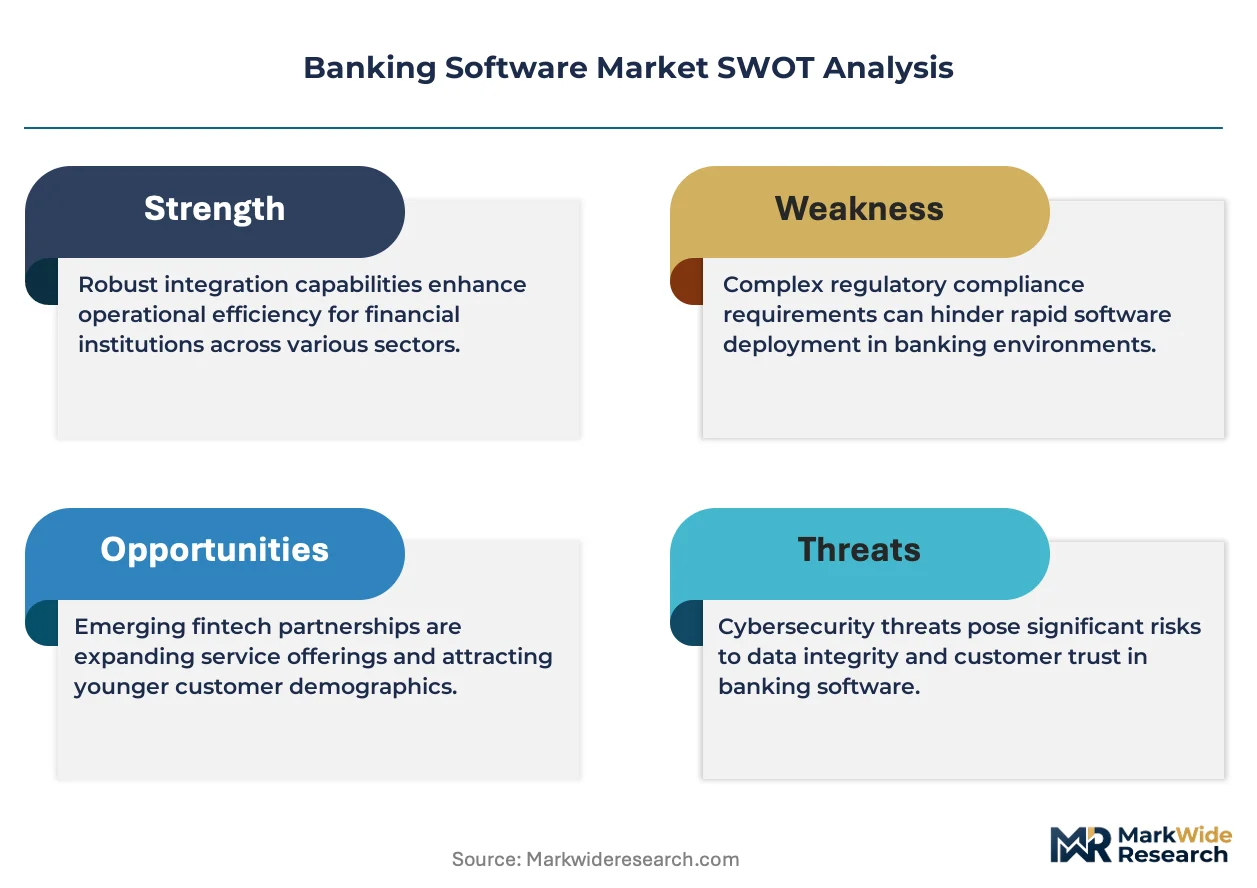
The European Banking Authority enforces stringent operational resilience requirements under DORA, while the RBI mandates granular data localization for payment systems in India. The US OCC and Federal Reserve jointly supervise third-party risk management, forcing banks to vet software vendor cyber controls before contract execution. Stakeholders must weigh regulatory fragmentation against platform consolidation bets as jurisdictions diverge on cloud sovereignty rules and AI governance standards.
Market Dynamics
Cloud-native core banking platforms are collapsing the traditional mainframe-to-branch infrastructure model, forcing incumbent vendors to rearchitect around API-first microservices or cede share to SaaS-native challengers. This structural shift redistributes value from perpetual license maintenance toward transaction-scaled revenue recognition.
Growth Catalysts
- PSD2 Compliance Mandates:European open banking regulations compel banks to expose customer data through standardized APIs, accelerating procurement of middleware and consent management layers.
- UPI Infrastructure Scale:India's real-time payment rail processes billions of monthly transactions, creating mandatory upgrade cycles for core systems handling instant settlement.
- Container Orchestration:Kubernetes-based deployment models slash provisioning costs for regional banks, collapsing barriers to multi-tenant cloud migration.
Market Restraints
- Data Localization Requirements:RBI mandates in India and comparable rules in Indonesia force vendors to establish in-country cloud regions, fragmenting infrastructure economics.
- Mainframe Skill Scarcity:COBOL and assembler expertise concentrates among aging workforces in the United States and Germany, constraining migration timelines.
- Cyber Insurance Collapse:Premium spikes for financial institutions' cyber coverage are compressing software procurement budgets, particularly among mid-tier banks.
Strategic Opportunities
- Embedded Finance Convergence:Banking-as-a-Service APIs enable non-bank platforms to offer regulated financial products, opening distribution through e-commerce and logistics software.
- DORA Operational Resilience:European Banking Authority requirements create mandatory investment windows for business continuity and incident response tooling.
- Rural Cooperative Digitization:India's regional rural banks remain underpenetrated by cloud cores, presenting white-space for localized language and low-bandwidth solutions.
Industry Challenges
- API Version Fragmentation:Banks maintain decades of legacy integrations, forcing vendors to support parallel protocol stacks that dilute engineering resources.
- Certification Timeline Compression:Regulatory sandbox approvals in Singapore and the UK compress validation cycles, straining quality assurance bandwidth.
- Talent Poaching Intensity:Cloud architecture and DevSecOps skills command premium compensation, inflating vendor delivery costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Software Market |
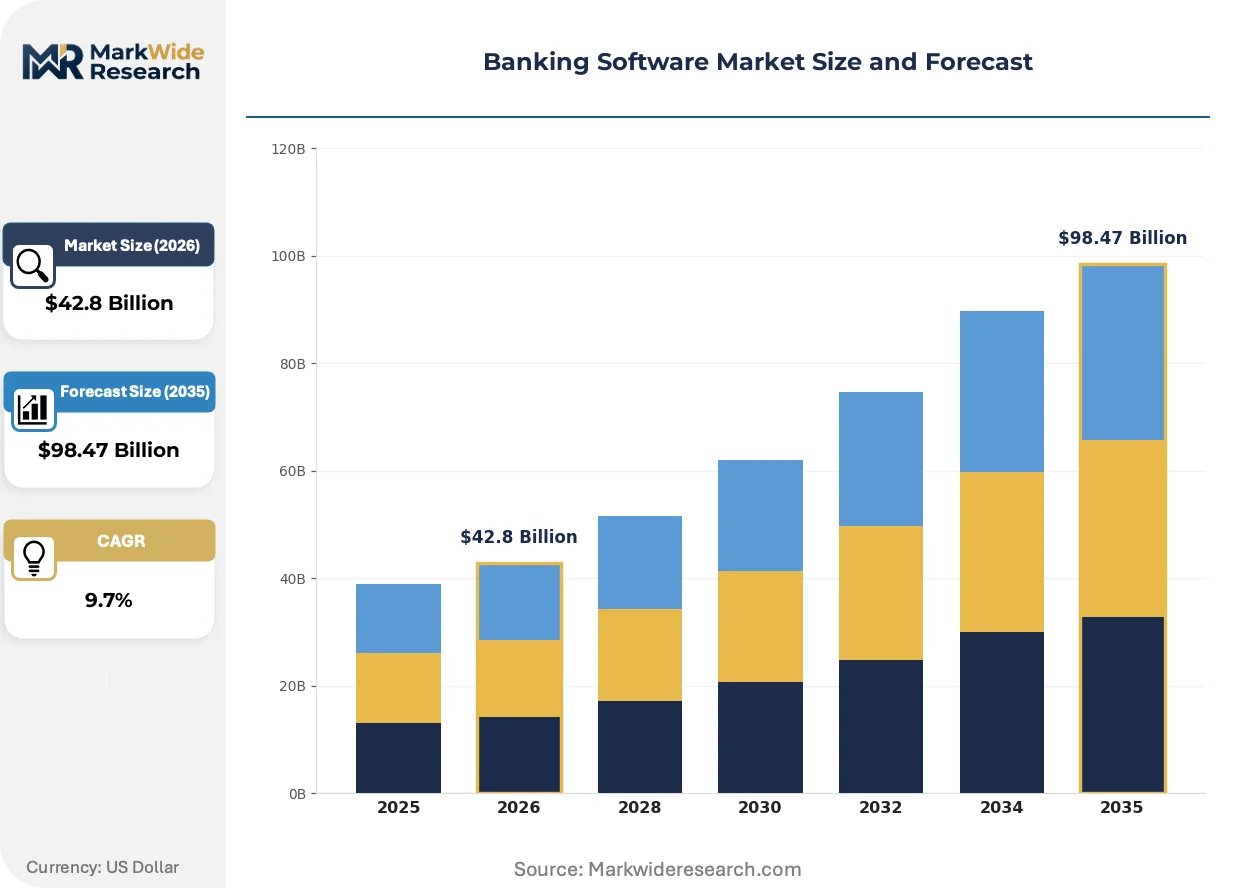
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $98.47 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Core Banking, Risk Management, Customer Relationship Management, Loan Origination, Payment Processing Deployment Model: On-Premise, Cloud-Based, Hybrid Cloud, Private Cloud, SaaS Application: Retail Banking, Corporate Banking, Wealth Management, Digital Payments, Trade Finance End User: Commercial Banks, Credit Unions, Microfinance Institutions, Investment Firms, Savings Institutions |
| Companies Covered | TCS BaNCS, Fiserv, Temenos, Sopra, Mambu, FIS, Finastra, InfrasoftTech, Oracle FLEXCUBE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Software Market Trends and Innovations
Event-driven architecture and generative AI are converging to reshape how banking software processes transactions, detects anomalies, and interfaces with customers. Vendors that integrate these capabilities into unified platforms capture disproportionate RFP win rates.
Event streaming platforms are collapsing the batch-processing paradigm that dominated core banking for decades. Apache Kafka and cloud-native alternatives enable real-time ledger reconciliation and instant fraud scoring. Tier-two banks in Brazil and Mexico are adopting these architectures fastest, leapfroging legacy modernization cycles. The structural consequence is collapsing time-to-market for new product launches from quarters to weeks.
DORA operational resilience requirements enforce mandatory business continuity testing and third-party risk documentation across European financial institutions. Vendors must now certify sub-24-hour recovery capabilities and provide granular dependency mapping. Payment processors and core banking providers face the steepest compliance burden, driving consolidation toward vendors with pre-certified infrastructure.
Subscription-based pricing is displacing perpetual licenses as the dominant procurement model for mid-market banks. Finance teams prefer operational expenditure treatment and usage-scaled commitments over upfront capital allocation. This shift is most visible in the United States, where regional banks under $50 billion in assets have pivoted procurement evaluation criteria toward total cost of ownership over five-year horizons rather than initial license fees.
Banking Software Market Segmentation
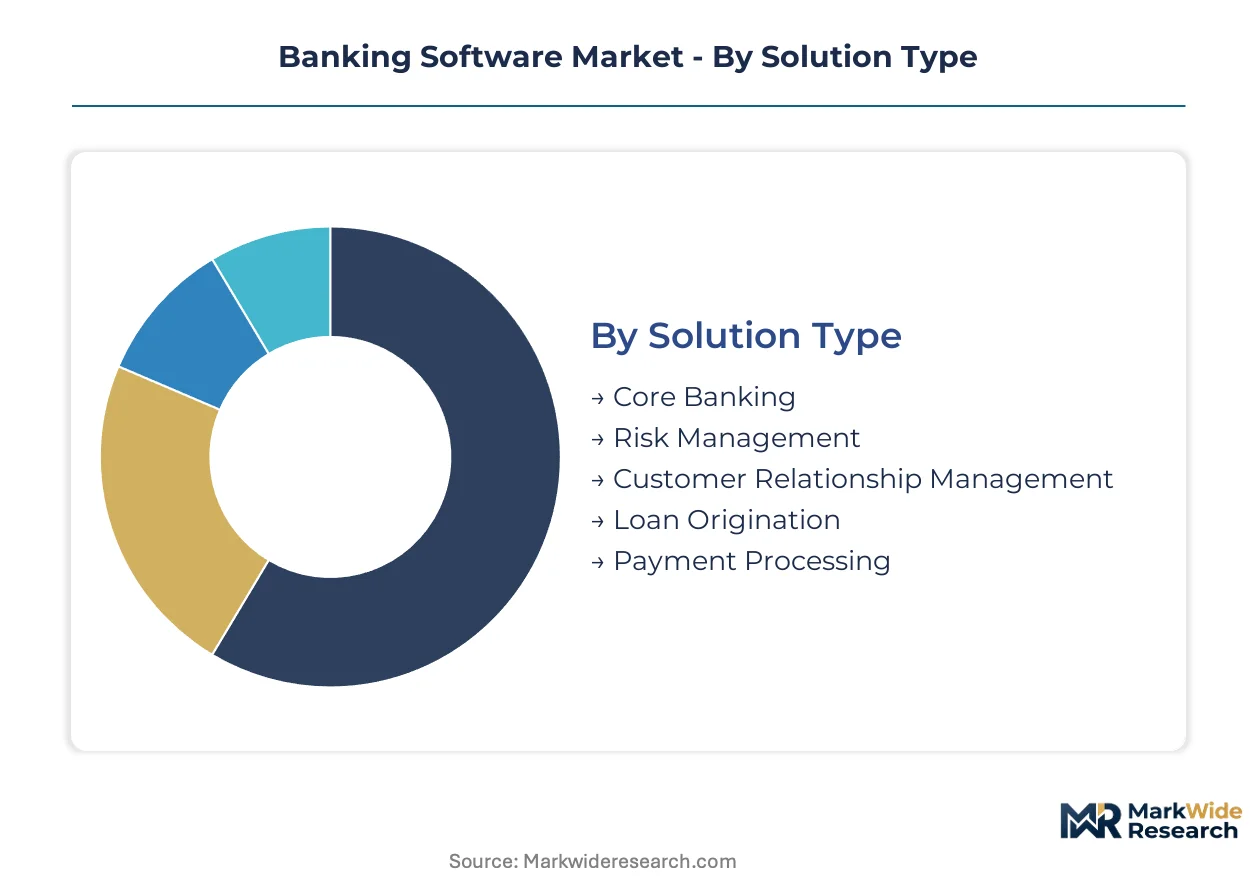
Banking software procurement patterns diverge sharply across institution size, regulatory jurisdiction, and technical maturity. Segment-level analysis reveals where cloud-native architectures are displacing legacy cores versus where mainframe retention persists.
Solution Type:
Cost tier determines vendor selection criteria and contract structure across solution categories.
- Core Banking:Monolithic ledger systems process deposit accounts, loans, and general ledger operations through batch or real-time settlement engines. Indian regional banks and German Sparkassen dominate replacement demand as RBI data localization rules and ECB climate risk reporting force infrastructure refresh cycles.
- Payment Processing:Transaction-scaled SaaS modules handle authorization, clearing, and settlement across card networks, ACH rails, and instant payment schemes. Brazilian neobanks and Southeast Asian super-apps drive fastest adoption as UPI and Pix volumes force real-time architecture upgrades.
- Risk Management:Calculation engines for credit, market, and operational risk with Basel III/IV compliance reporting.
- Customer Relationship Management:Unified customer data platforms with campaign orchestration and lifetime value analytics.
- Loan Origination:Digital application processing with automated underwriting and document verification workflows.
Core Banking holds installed capacity. Payment Processing is rotating up the share rankings.
Deployment Model:
Application architecture constraints dictate which deployment topology banks can adopt without core replacement.
- SaaS:Multi-tenant cloud delivery with vendor-managed infrastructure and automatic security patching. United States community banks under $10 billion in assets prefer this model for operational expenditure treatment and rapid feature deployment.
- Cloud-Based:Single-tenant public cloud instances with bank-controlled configuration and update scheduling. Australian and Singaporean mid-tier banks favor this for regulatory sandbox participation and geographic redundancy requirements.
- On-Premise:Bank-owned data center deployment with full hardware and software stack control.
- Hybrid Cloud:Split workload architecture with sensitive data on-premise and customer-facing layers in cloud.
- Private Cloud:Dedicated cloud infrastructure with single-tenant isolation and custom compliance certifications.
On-Premise retains regulatory-mandated share. SaaS is climbing the fastest among deployment options.
Application:
Customer type and transaction velocity shape functional requirements across banking verticals.
- Digital Payments:Real-time payment interfaces, wallet infrastructure, and merchant acquiring technology stacks. Indian fintechs and Nigerian mobile money operators concentrate procurement here as central bank digital currency pilots and QR-code national standards force platform investments.
- Retail Banking:Consumer deposit, lending, and card products with branch and mobile channel integration. Japanese regional banks and Italian cooperative banks drive modernization as negative interest rate policies compress net interest margins and force cost reduction.
- Corporate Banking:Treasury management, cash pooling, and working capital solutions for enterprise clients.
- Wealth Management:Portfolio accounting, rebalancing engines, and advisor workstation platforms.
- Trade Finance:Letter of credit processing, supply chain finance, and documentary collection workflows.
Retail Banking anchors current revenue. Digital Payments is gaining share fastest as real-time rails proliferate.
End User:
Institution charter and regulatory classification determine procurement authority and technical sophistication.
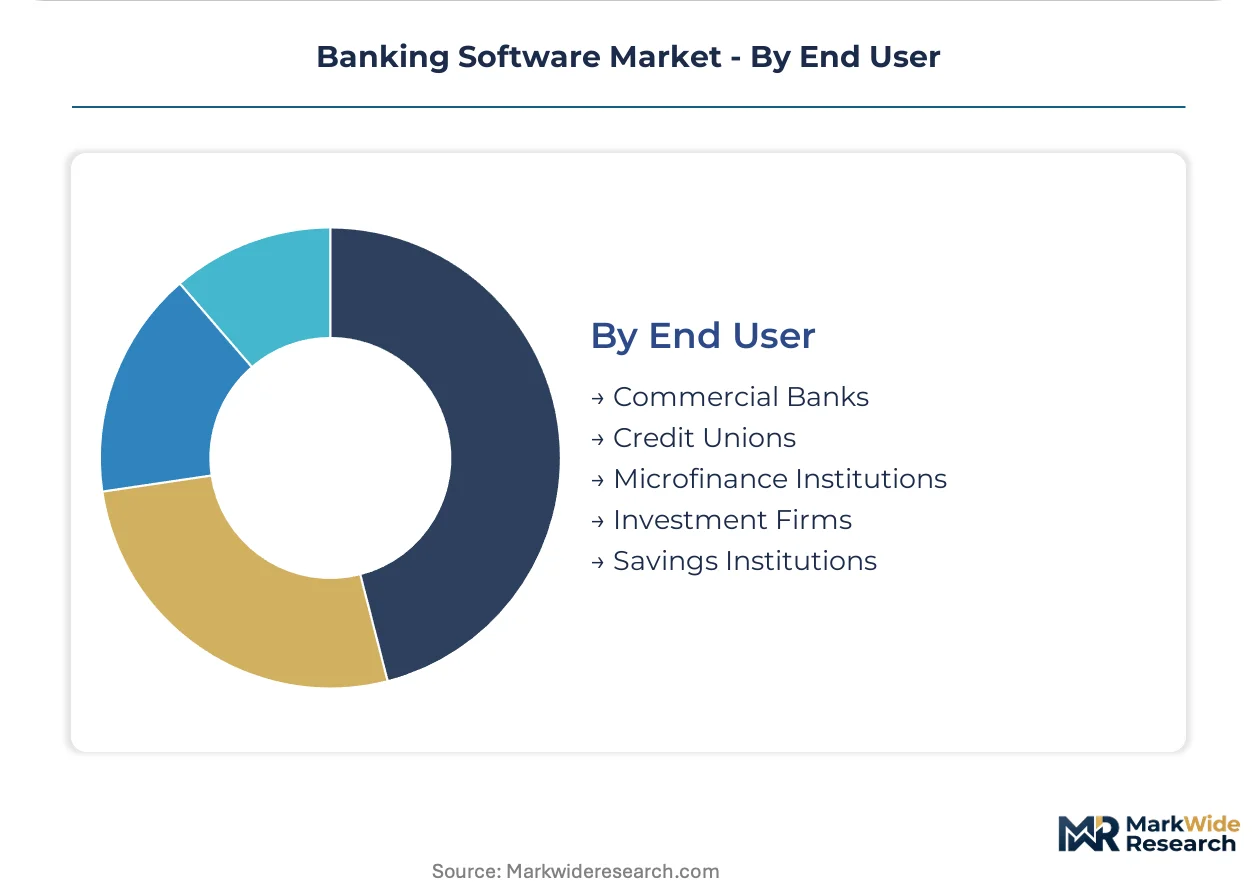
- Commercial Banks:Full-service deposit-taking institutions with national or regional charters. United States regional banks between $10-50 billion in assets and Canadian Schedule I banks dominate enterprise software spending as Dodd-Frank stress testing and OSFI capital requirements force platform consolidation.
- Credit Unions:Member-owned cooperatives with tax-exempt status and community-focused lending mandates. Australian customer-owned banking sector and Canadian credit union networks drive demand for cloud-native cores with shared service economics.
- Microfinance Institutions:Small-balance lenders serving unbanked populations with group lending methodologies.
- Investment Firms:Broker-dealers and asset managers requiring custody and trading infrastructure.
- Savings Institutions:Thrift charters focused on mortgage lending and deposit gathering.
Commercial Banks command procurement volume. Credit Unions are rotating up the share rankings through cooperative purchasing consortia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UPI payment rail underwrites India's central position in banking software procurement, processing billions of monthly transactions that mandate core system upgrades. Cloud-native architecture investments concentrate where real-time settlement infrastructure scales fastest.
United States
Community banks under $10 billion in assets drive SaaS-first procurement for operational expenditure treatment. The OCC and Federal Reserve jointly supervise third-party risk management, forcing vendor cyber control vetting before contract execution. Dallas and Charlotte banking clusters concentrate core platform replacement demand as regional institutions retire mainframe infrastructure.
Germany
Sparkassen and cooperative banks dominate replacement demand as ECB climate risk reporting forces infrastructure refresh cycles. DORA operational resilience requirements enforce mandatory business continuity testing across European financial institutions. Frankfurt's fintech corridor anchors API-native architecture adoption among mid-tier institutions seeking sandbox participation.
India
RBI data localization rules and UPI infrastructure expansion create mandatory upgrade cycles for core systems handling instant settlement. The central bank mandates granular data localization for payment systems, forcing vendors to establish in-country cloud regions. Mumbai and Bangalore banking technology clusters concentrate procurement authority for cloud-native core platforms.
Brazil
Pix real-time payment volumes force architecture upgrades among tier-two banks and neobanks. The central bank's instant payment rail adoption collapses time-to-market for new product launches from quarters to weeks. São Paulo's financial district anchors event-streaming platform deployment as institutions leapfrog legacy modernization cycles.
United Kingdom
Open banking regulations compel institutions to expose customer data through standardized APIs, accelerating middleware procurement. The Financial Conduct Authority's regulatory sandbox compresses validation cycles for cloud-native entrants. London's Square Mile concentrates consent management layer investments as incumbent banks rearchitect around microservices.
Banking Software Market Competitive Landscape
On the supply side, the industry is tiered between incumbent core banking vendors with installed mainframe bases and SaaS-native challengers capturing cloud migration cycles. Strategic archetypes include API-first platform specialists, merchant-acquiring bundlers, and regulatory compliance module providers. Dominant competitive moves encompass SaaS partnership restructuring and geographic expansion through pre-certified infrastructure.
Among established platform vendors, Fiserv exemplifies the merchant-acquiring bundler archetype through payment acceptance tool integration. Temenos occupies a position within the API-native architecture tier, anchoring growth in European and Asia-Pacific markets. Oracle FLEXCUBE represents the emerging-market compliance specialist archetype, with localized regulatory modules as its positioning anchor.
| Leading Market Players |
|---|
| TCS BaNCS |
| Fiserv |
| Temenos |
| Sopra |
| Mambu |
| FIS |
| Finastra |
| InfrasoftTech |
| Oracle FLEXCUBE |
| Others |
Pricing and Supply Chain Analysis
Bangalore's cloud engineering talent density anchors global SaaS delivery capacity, concentrating vendor development centers and compressing deployment cost curves for downstream banking clients. This geographic concentration of technical labor pools directly shapes pricing power across subscription tiers, as vendors compete for finite DevSecOps and Kubernetes architecture expertise.
Pricing Analysis
Volume-discount tiering structures dominate banking software procurement, with three-tier pricing separating enterprise multi-year commitments from standard mid-market subscriptions and economy-tier community bank packages. Price differentiation rests on customization depth and regulatory certification grade, with DORA-compliant European deployments commanding premiums over baseline SaaS offerings. Cost compression in the economy tier is intensifying because Kubernetes-based container orchestration slashes provisioning overhead for regional banks. Community banks under $10 billion in assets exhibit highest price sensitivity, while tier-one commercial banks prioritize total cost of ownership over initial license fees.
Supply Chain Analysis
Contract manufacturing concentration among hyperscale cloud providers—Amazon Web Services, Microsoft Azure, and Google Cloud Platform—holds infrastructure capacity for banking software delivery. Geographic supply concentrates in the United States, Ireland, and Singapore, where financial services-certified data centers feed from specialized hardware components including HSM security modules and low-latency networking equipment. Single-source vulnerability in cloud region availability presents structural risk, particularly where RBI data localization rules mandate in-country infrastructure. Distribution runs through direct vendor sales teams and systems integrator partnerships for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The banking software market rewards vendors possessing scarce mainframe-to-cloud migration expertise, as COBOL skill attrition outpaces replacement pipeline development. Institutions face capability gaps in real-time event streaming architecture and DORA operational resilience certification.
For Market Incumbents: Insulate core revenue streams by accelerating API-native rearchitecture around microservices before SaaS-native challengers capture cloud migration cycles. Invest in vertical integration into managed security services to defend against specialized cybersecurity vendors. Prioritize certification investment for European DORA compliance to maintain incumbent positioning against emerging entrants. For New Entrants and Emerging Players: India's regional rural banks represent the most penetrable entry point, given underpenetration by cloud-native cores and RBI-mandated infrastructure refresh cycles. Target embedded finance convergence through Banking-as-a-Service APIs for e-commerce and logistics platforms seeking regulated financial product distribution. Pursue regulatory sandbox participation in Singapore and the United Kingdom as primary go-to-market validation pathway. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because API-first platform specialists with pre-certified DORA infrastructure will capture disproportionate European procurement volume as operational resilience mandates compress vendor shortlists. Acquisition target archetype: SaaS-native challengers with Kubernetes-based deployment models and established RBI data localization compliance. Monitor central bank instant payment rail expansion—UPI, Pix, FedNow adoption velocity serves as inflection indicator for core system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Integration | Temenos and Mambu capture European open banking procurement through standardized middleware layers. |
| Regulatory Pre-Certification Investment | DORA-compliant vendors secure mandatory European financial institution upgrade cycles ahead of competitors. |
| Geographic Expansion Through Local Cloud Regions | RBI data localization rules force infrastructure establishment in Mumbai and Bangalore banking clusters. |
| Embedded Finance Partnership Development | Fiserv bundles merchant acquiring with core banking to penetrate e-commerce platform distribution channels. |
| Legacy Modernization Service Acquisition | COBOL-to-cloud migration expertise commands premium valuations amid aging workforce attrition. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers, IT procurement officers at commercial banks, platform engineers, and channel partners and refined through secondary validation. Primary fieldwork drew from SEC filings of publicly traded vendors, hyperscaler capex disclosures, and central bank regulatory sandbox documentation. Bottom-up triangulation across deployment model adoption rates and top-down validation against aggregate banking technology spending produced convergent estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions including deployment model, institution asset tier, regulatory jurisdiction cluster, and integration complexity. CAGRs were derived from curve-fitting historical replacement cycles against projected real-time payment infrastructure expansion. Forecast inputs incorporated UPI transaction velocity trajectories and DORA compliance deadline clustering.
Macroeconomic conditions sit as an overlay; deviation in central bank interest rate policy and regional bank merger activity would shift the trajectory of core system replacement demand. Forecasts reflect assumptions regarding regulatory sandbox approval timelines and cloud region certification pacing. Quarterly review of instant payment rail transaction volumes and vendor earnings call commentary on backlog duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Europe Neobanking Market
Banking
Singapore Neobanking Market
Banking
UK Banking as a Service Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Brazil Retail Banking Market
Banking
Data Analytics in Banking Market
Banking
Global Neobanking Market
Banking
Europe Machine Learning in Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Banking As a Service (BAAS) Market
Banking
Performance Bank Guarantee Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Cloud Billing in Banking Market
Banking
Cloud Computing Banking Market
Banking
AI and Automation in Banking Market
Banking
UK Retail Banking Market