
 AI and Automation in Banking Market | 2026-2036
AI and Automation in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
AI and Automation in Banking Market Insights
ISO 20022 certification is unwinding competitive access across wholesale banking networks, forcing vendors to recalibrate messaging protocols. IBM Corporation leverages its mainframe-to-cloud integration stack to anchor institutional clients in hybrid deployment architectures. Capgemini SE competes through embedded consulting models that combine process redesign with automation implementation. DataRobot Inc. differentiates via governed AI pipelines that sustain compliance audit trails for regulated lending decisions.
AI and automation in banking encompasses machine learning algorithms, robotic process automation engines, and natural language processing systems that execute transactional workflows, detect anomalous patterns, and generate predictive risk scores with sub-second latency. These technologies primarily reduce operational cost density while tightening regulatory conformance across high-volume payment and credit operations. Robotic Process Automation solutions occupy mature margin pools in back-office reconciliation, while Fraud Detection Systems capture accelerated investment as real-time transaction monitoring becomes mandatory. Cloud-Based deployment modes lead growth trajectories as banks exit legacy data center commitments, though Hybrid architectures retain dominance among tier-one institutions with sovereign data requirements.
The EU AI Act classifies automated credit scoring as high-risk, compelling algorithmic transparency documentation that shapes procurement specifications across European retail banking. The Federal Reserve's guidance on model risk management, paired with SEC disclosure rules for AI-driven advisory tools, creates layered compliance obligations for US institutions. Stakeholders must monitor divergence between emerging national AI frameworks and existing financial regulations to anticipate where compliance costs will concentrate.
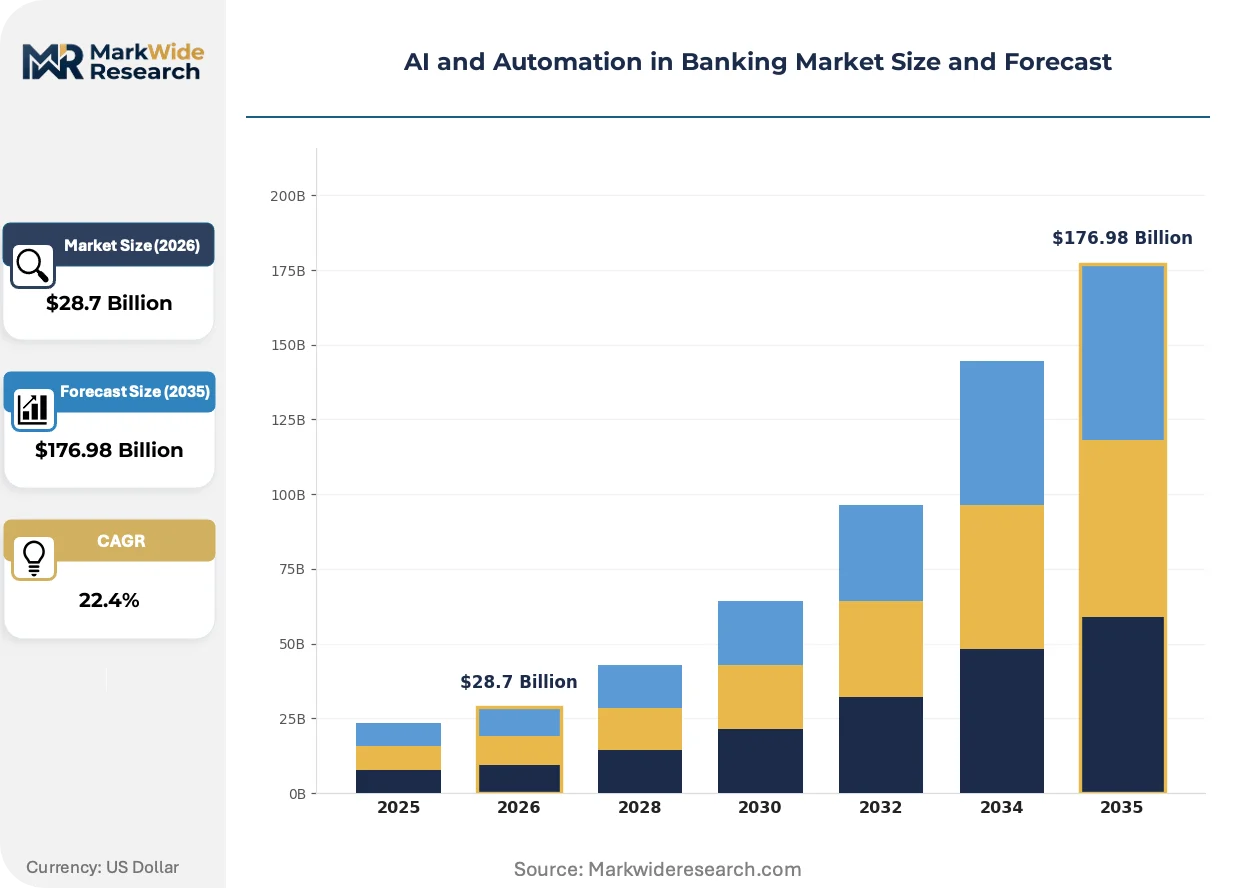
Market Dynamics
The EU AI Act's high-risk classification for automated credit decisions is forcing banks to rebuild algorithmic governance frameworks, creating procurement urgency for explainable AI systems that document decision pathways for regulatory audit.
Growth Catalysts
- EU AI Act risk mandates:Automated credit scoring regulations in Europe require transparent algorithmic documentation, driving demand for interpretable machine learning platforms in retail banking.
- Real-time transaction monitoring:Payment networks across Singapore, Germany, and the United Kingdom now mandate sub-second fraud detection, accelerating cloud infrastructure investment.
- Core banking modernization:Legacy system replacement cycles in wholesale banking are converging with ISO 20022 migration timelines, creating bundled procurement opportunities.
Market Restraints
- Specialized talent scarcity:Machine learning engineers with financial services domain expertise command premium compensation, compressing vendor margins on implementation services.
- Sovereign data requirements:Tier-one institutions in France and Switzerland maintain hybrid architectures despite cloud cost advantages, fragmenting deployment standardization.
- Algorithmic audit complexity:The Federal Reserve's model risk management guidance demands continuous validation documentation, extending sales cycles for AI vendors.
Strategic Opportunities
- Embedded finance convergence:Retail banking AI stacks are integrating with non-bank payment platforms, opening distribution through e-commerce and logistics ecosystems.
- Climate risk modeling:The EU Green Deal's stress-testing requirements for loan portfolios create demand for predictive analytics that incorporate environmental data.
- Small-business lending automation:Underpenetrated credit decisioning in India's regional banking cooperatives offers whitespace for cloud-native workflow platforms.
Industry Challenges
- Legacy system integration:Mainframe-to-cloud data pipeline construction requires specialized middleware expertise that sits outside most AI vendors' core capabilities.
- Cross-border compliance fragmentation:Divergent national AI frameworks between the SEC's disclosure rules and emerging Asian regulations force product localization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI and Automation in Banking Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $176.98 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Robotic Process Automation, Fraud Detection Systems, Customer Analytics, Chatbots, Credit Scoring Tools Deployment Mode: On-Premises, Cloud-Based, Hybrid, Private Cloud Use Case: Risk Management, Loan Processing, Personal Finance Advisory, Compliance Monitoring, Customer Service Customer Type: Retail Banking, Corporate Banking, Wealth Management, Payment Service Providers |
| Companies Covered | Automation Anywhere, Inc., Pegasystems Inc., Capgemini SE, Sutherland, Nintex, C3.AI Inc., DataRobot Inc., IBM Corporation, Synechron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI and Automation in Banking Market Trends and Innovations
Generative AI capabilities are penetrating banking operations through distinct pathways—customer-facing interfaces, code generation for legacy modernization, and synthetic data creation for model training—each carrying different risk profiles and deployment timelines.
Large language model deployment is bifurcating across two operational tracks. Conservative institutions restrict generative AI to internal documentation and code assistance, while aggressive adopters deploy customer-facing conversational agents. Retail banks in the United Kingdom and Singapore lead external deployment, compressing traditional call center operating models. This divergence is creating parallel vendor ecosystems with incompatible security certifications.
The EU AI Act's enforcement timeline is reshaping procurement specifications for algorithmic credit decisions. Retail banks must now maintain technical documentation proving human oversight mechanisms, model performance metrics, and bias testing protocols. German and French institutions are consolidating vendor relationships to reduce compliance audit fragmentation, favoring platforms with pre-built governance modules.
Subscription-based pricing for AI infrastructure is displacing perpetual licensing in mid-tier banking procurement. Chief information officers in North American regional banks now prioritize operational expenditure flexibility over capital-intensive ownership, particularly for fraud detection systems with volatile transaction volumes. This shift rewards vendors with metered cloud architectures and penalizes legacy on-premise specialists.
AI and Automation in Banking Market Segmentation
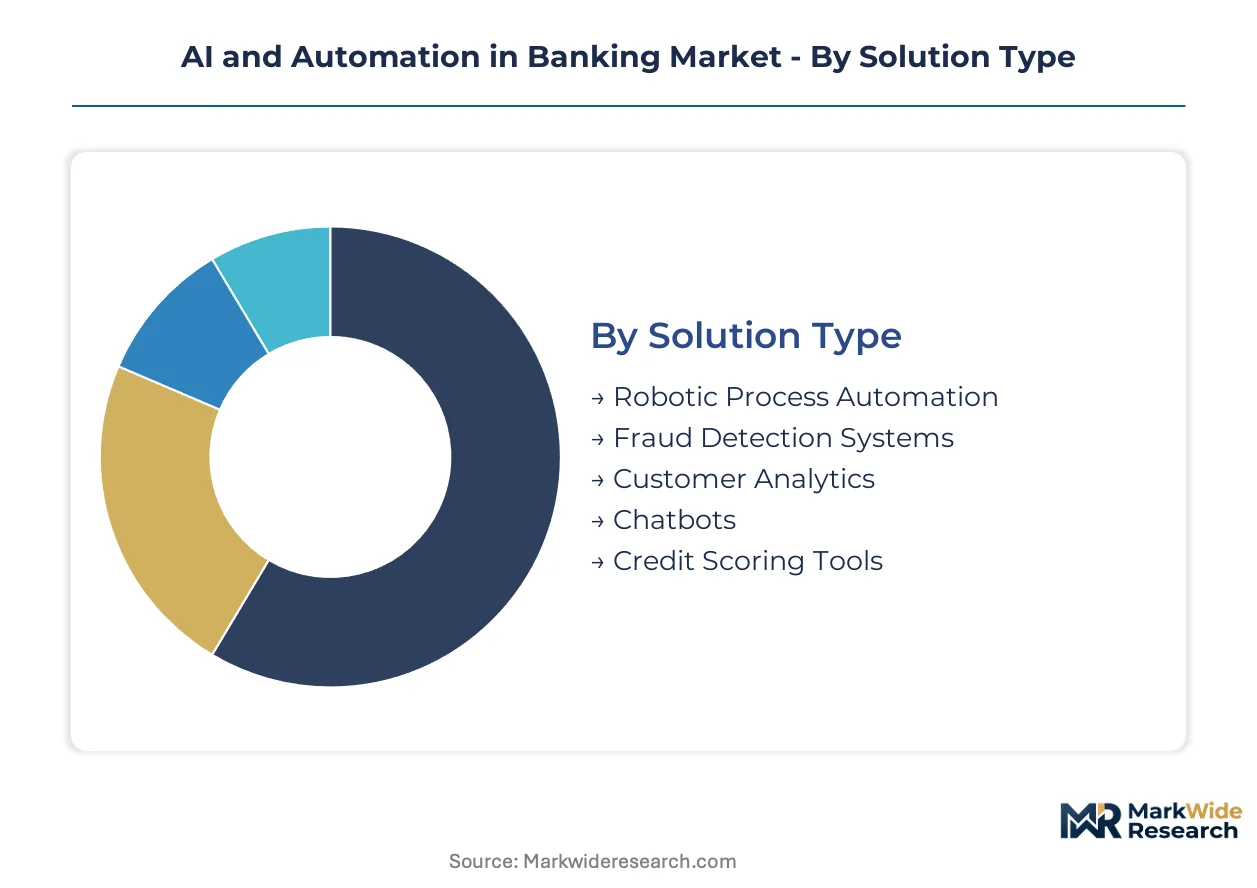
Segmentation in banking AI reveals how procurement priorities diverge across risk tolerance, infrastructure legacy, and regulatory exposure. Institutions select solution architectures based on where automation delivers compliance leverage versus operational efficiency.
Solution Type:
Robotic Process Automation faces substitution pressure from generative AI coding assistants that replicate back-office workflows without legacy bot infrastructure.
- Robotic Process Automation:Rule-based software bots execute repetitive reconciliation, data entry, and report generation tasks across core banking systems. German retail banks deploy these for ISO 20022 message conversion during legacy modernization, though generative AI threatens this segment's maintenance-heavy operating model.
- Fraud Detection Systems:Real-time machine learning models score transaction risk using behavioral biometrics, device fingerprints, and velocity patterns. Singapore's payment networks mandate sub-second detection latency, driving cloud-native architecture procurement for these systems.
- Customer Analytics:Predictive segmentation engines cluster depositors by propensity, lifetime value, and channel preference for targeted product offers.
- Chatbots:Natural language interfaces handle routine balance inquiries, branch locators, and password resets through conversational workflows.
- Credit Scoring Tools:Algorithmic underwriting platforms assess borrower default probability using alternative data streams and traditional bureau files.
Fraud Detection Systems anchor the volume base while Credit Scoring Tools gain share at the steepest rate under EU AI Act compliance mandates.
Deployment Mode:
Cost tier stratification separates sovereign-data institutions from mid-tier banks seeking operational expenditure flexibility.
- On-Premises:Dedicated hardware installations within bank-owned data centers retain full data custody and network isolation. Swiss wealth managers and French systemic institutions maintain these configurations despite higher total cost of ownership.
- Cloud-Based:Multi-tenant public cloud services deliver elastic compute for variable transaction volumes without capital commitment. United Kingdom regional banks prioritize this mode for fraud detection systems with seasonal demand spikes.
- Hybrid:Split architectures place sensitive workloads on-premise while bursting non-critical processing to public cloud. Tier-one institutions in Germany and Singapore adopt this for sovereign data compliance combined with scalability.
- Private Cloud:Single-tenant cloud infrastructure dedicated to one institution within a service provider's facility.
Cloud-Based deployments capture the fastest expansion trajectory among mid-tier banks, while Hybrid architectures retain dominance at systemic institutions.
Use Case:
Application maturity varies sharply, with some use cases delivering measurable ROI and others trapped in pilot phases.
- Risk Management:Integrated platforms for market, credit, and operational risk calculation with automated regulatory reporting. United States institutions deploy these under Federal Reserve model risk management guidance requiring continuous validation documentation.
- Loan Processing:End-to-end automation of application intake, document verification, and approval workflow for consumer and commercial credit. Indian regional banking cooperatives represent whitespace for these platforms in underpenetrated markets.
- Personal Finance Advisory:Algorithmic recommendation engines for budgeting, savings optimization, and investment allocation.
- Compliance Monitoring:Surveillance systems detecting market abuse, anti-money laundering patterns, and conduct violations across trading and communications data.
- Customer Service:Unified agent desktops and automated interaction handling across voice, chat, and email channels.
Risk Management commands the largest implementation spend while Loan Processing demonstrates the steepest growth curve in emerging banking markets.
Customer Type:
Customer sophistication determines whether procurement emphasizes governance depth or speed-to-deployment.
- Retail Banking:High-volume, standardized transaction processing for individual depositors and borrowers. United Kingdom and Singapore institutions lead external generative AI deployment for customer-facing conversational agents in this segment.
- Corporate Banking:Complex, relationship-driven services for mid-market and large enterprises including treasury, trade finance, and lending. These clients demand explainable AI documentation for automated credit decisions under EU AI Act requirements.
- Wealth Management:High-net-worth and ultra-high-net-worth advisory with customized portfolio construction and tax optimization.
- Payment Service Providers:Non-bank processors and fintechs requiring real-time authorization, settlement, and reconciliation infrastructure.
Retail Banking generates the highest solution volume while Payment Service Providers expand most quickly through embedded finance distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-London financial corridor anchors European AI banking infrastructure, while Singapore's submarine cable landing stations connect Asia-Pacific cloud nodes to global payment networks.
United States
Commercial banks in New York and Chicago deploy real-time fraud detection at scale, driven by Federal Reserve model risk management guidance. The SEC's disclosure rules for AI-driven advisory tools create layered compliance obligations. Silicon Valley clusters concentrate generative AI development for code modernization and synthetic data generation.
Germany
Frankfurt-based systemic banks rebuild algorithmic governance frameworks under EU AI Act high-risk classification mandates for automated credit decisions. The Bundesbank's oversight of payment systems accelerates ISO 20022 migration timelines. Bavarian technology clusters supply explainable AI platforms with pre-built compliance modules.
United Kingdom
London retail banks lead external generative AI deployment for customer-facing conversational agents, compressing traditional call center models. The Financial Conduct Authority's operational resilience requirements shape cloud procurement specifications. Edinburgh and Manchester regional banking centers prioritize subscription-based fraud detection pricing.
Singapore
The Monetary Authority of Singapore mandates sub-second transaction monitoring latency across payment networks, driving cloud-native architecture investment. Sovereign data requirements sustain hybrid deployment dominance among tier-one institutions. The city's submarine cable infrastructure anchors Asia-Pacific cloud banking nodes.
India
Mumbai-based private sector banks automate small-business lending workflows, targeting underpenetrated regional banking cooperatives. The Reserve Bank of India's digital payment push accelerates core modernization cycles. Bangalore technology clusters supply cloud-native workflow platforms for emerging market deployment.
AI and Automation in Banking Market Competitive Landscape
Listed leaders compete with private specialists across governance depth and deployment speed dimensions. The vendor base stratifies into three tiers: global systems integrators with embedded consulting arms, pure-play AI platform vendors with governed pipeline architectures, and automation specialists with mature RPA maintenance networks. Dominant competitive moves include bundling ISO 20022 migration services with core modernization contracts, and consolidating vendor relationships to reduce compliance audit fragmentation.
Within the governance-focused tier, DataRobot Inc. and IBM Corporation occupy positions emphasizing algorithmic transparency documentation. Capgemini SE exemplifies the embedded consulting model combining process redesign with implementation delivery. These three anchors span distinct archetypes: governed AI pipelines, hybrid cloud integration stacks, and end-to-end transformation services.
| Leading Market Players |
|---|
| Automation Anywhere, Inc. |
| Pegasystems Inc. |
| Capgemini SE |
| Sutherland |
| Nintex |
| C3.AI Inc. |
| DataRobot Inc. |
| IBM Corporation |
| Synechron |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure scale economies in fraud detection and credit scoring systems concentrate procurement power among hyperscale platform operators, compressing price floors for mid-tier vendors while elevating switching costs for institutional buyers locked into ISO 20022-compliant integration stacks.
Pricing Analysis
Volume-discount tiering structures separate enterprise banking clients committing to multi-year SaaS contracts from regional institutions purchasing metered consumption. Pricing stratifies across premium governance modules, standard automation suites, and economy RPA maintenance tiers, with EU AI Act compliance certification commanding substantial premiums. Cost compression in standard-tier RPA is intensifying because generative AI coding assistants replicate back-office workflows without legacy bot infrastructure. Payment service providers exhibit the highest price sensitivity due to thin transaction margins, while Swiss wealth managers accept premium pricing for sovereign data custody guarantees.
Supply Chain Analysis
Submarine cable landing stations in Singapore and the Netherlands create chokepoints for Asia-Pacific cloud banking nodes connecting to Frankfurt-London financial corridors. Software development concentrates in the United States, Germany, and India, with specialized GPU clusters for model training drawing from Taiwan and South Korea. Single-source vulnerability in explainable AI governance modules threatens vendor diversification strategies. Distribution runs through embedded consulting partnerships at Capgemini SE and systems integrator channels rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one institutions consolidating vendor relationships to reduce EU AI Act compliance audit fragmentation, fragmenting pricing leverage for mid-tier automation specialists.
For Market Incumbents: Fortify algorithmic governance module offerings with pre-built EU AI Act documentation templates to defend against pure-play AI platform vendors. Deepen vertical integration into hybrid cloud infrastructure through mainframe-to-cloud middleware development, countering the threat of generative AI coding assistants displacing RPA maintenance revenue. Prioritize certification investment in ISO 20022 migration bundling to anchor institutional clients in long-term service contracts. For New Entrants and Emerging Players: EU AI Act compliance fast-tracks for automated credit scoring tools open white-space in French and German retail banking procurement. India's regional banking cooperatives represent the most penetrable geography for cloud-native loan processing workflows. A channel partnership strategy with Mumbai-based system integrators accelerates deployment velocity without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors offering metered fraud detection architectures with seasonal transaction volume elasticity. Long-term viability in the five-to-ten-year window favors platforms combining governed AI pipelines with embedded consulting capabilities rather than pure automation tool vendors. Monitor divergence between emerging national AI frameworks and existing financial regulations as the inflection signal for compliance cost concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | IBM Corporation's mainframe-to-cloud stacks anchor hybrid deployment architectures for sovereign data requirements. |
| Regulatory Certification Pathway | Pre-built EU AI Act governance modules reduce procurement friction for German and French retail banks. |
| Geographic Expansion | Cloud-native workflow platforms target underpenetrated Indian regional banking cooperatives for small-business lending. |
| Strategic Partnership | Embedded finance convergence with Singapore payment networks accelerates distribution through e-commerce ecosystems. |
| Acquisition of Specialist Firm | Consolidating explainable AI vendors reduces compliance audit fragmentation for tier-one institutions. |
Research Methodology
A spread of perspectives from chief information officers at tier-one banks, AI platform engineering leads, regulatory compliance officers, and procurement directors at payment service providers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of listed automation vendors, EU AI Act implementation guidance documents, Federal Reserve model risk management bulletins, and Monetary Authority of Singapore payment system circulars. Bottom-up deployment mode sizing and top-down solution type demand aggregation were triangulated to converge on market estimates.
Segmentation dimensions modeled span solution type, deployment mode, use case, and customer type across the projection horizon. CAGRs were derived from weighted growth trajectories within each segment, with particular sensitivity to cloud-based deployment elasticity and fraud detection system procurement cycles. Industry-specific forecast inputs included ISO 20022 migration timelines and EU AI Act enforcement readiness assessments among European retail banks.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement timelines and stable cloud infrastructure pricing; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as divergence between emerging national AI frameworks and existing financial regulations evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Smart Banking Solutions Market
Banking
Middle East Data Analytics in Banking Market
Banking
Japan Trade Finance Market
Banking
Banking Software Market
Banking
GCC Mobile Banking Market
Banking
US Banking-As-A-Service Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Banking CRM Software Market
Banking
US Commercial Banking Market
Banking
Brazil Retail Banking Market
Banking
Video Banking Service Market
Banking
Saudi Arabia Retail Banking Market
Banking
Cybersecurity in Banking Market
Banking
API Banking Market
Banking
Cloud Billing in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market