
 Middle-East and Africa Banking-As-A-Service Market | 2026-2036
Middle-East and Africa Banking-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Banking-As-A-Service Market Foresight
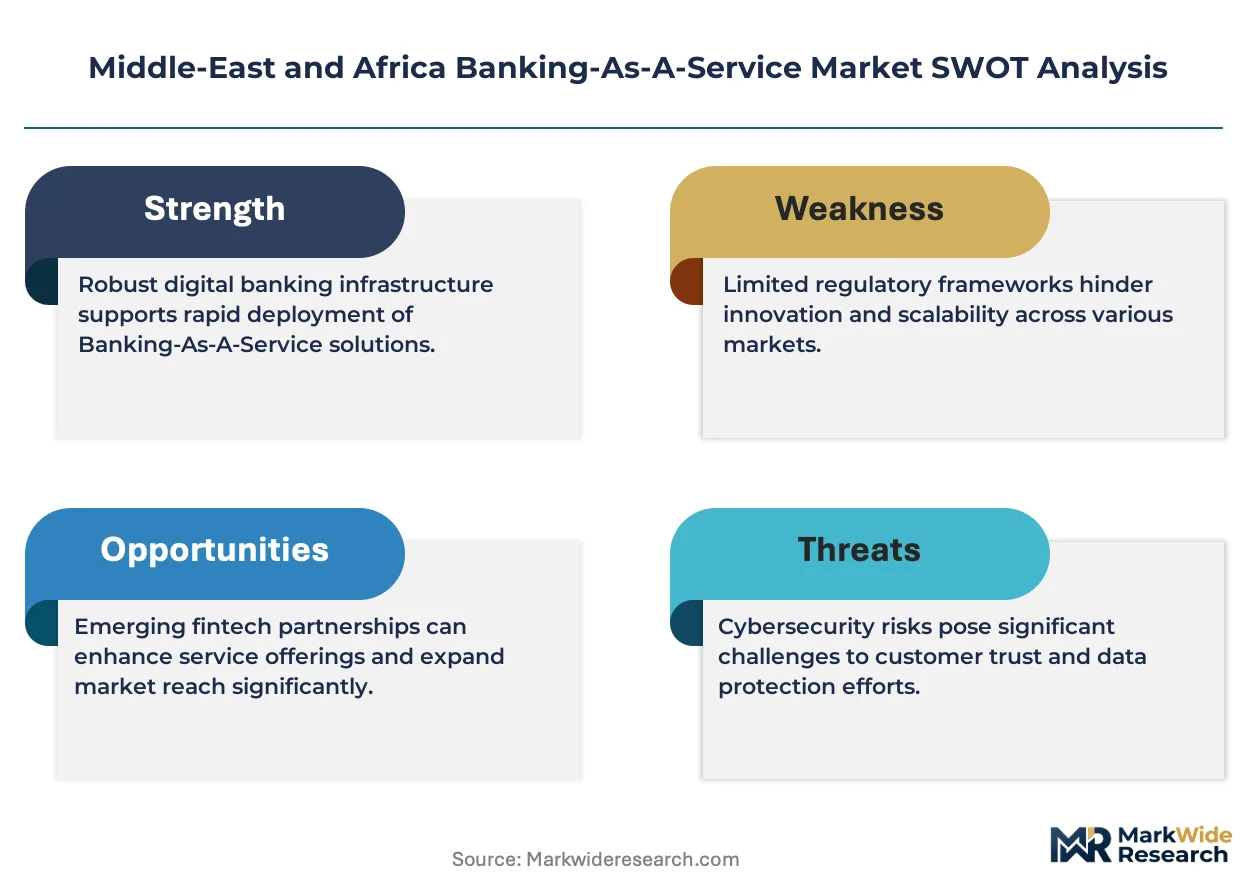
A shortage of API-native engineering talent is collapsing implementation timelines for BaaS rollouts across the Middle-East and Africa. MFS Africa anchors its competitive stance through proprietary cross-border payment rails connecting mobile money wallets. NymCard leverages localized card-issuing infrastructure to dominate the UAE and Saudi Arabian markets. Flutterwave competes aggressively by extending its developer ecosystem into Egyptian and Kenyan merchant segments.
Banking-as-a-Service denotes a licensed banking infrastructure delivered through application programming interfaces, enabling non-bank entities to embed financial products without obtaining charters. The architecture typically relies on RESTful APIs with OAuth authentication, real-time webhooks, and sandbox environments for pre-production testing. Public cloud deployment leads among fintech startups seeking elastic compute for transaction spikes, while private cloud configurations sustain traditional banks managing sensitive customer data under stricter residency requirements. API integration technology anchors current implementations, though artificial intelligence is emerging as the fastest-growing segment for fraud detection and credit scoring automation.
The Saudi Arabian Monetary Authority's open banking framework and the Central Bank of the UAE's sandbox licensing regime are compressing time-to-market for new entrants. South Africa's Financial Sector Conduct Authority and National Payment System Act impose capital and interoperability standards that shape product architecture for regional providers. Stakeholders must monitor how biometric authentication mandates evolve across Gulf and East African jurisdictions, as compliance costs will determine which technology layers absorb margin compression.
Market Dynamics
Open banking mandates from the Saudi Arabian Monetary Authority and the Central Bank of the UAE are compressing API standardization timelines and forcing infrastructure consolidation among regional providers.
Growth Catalysts
- Agent banking network density:Nigeria's last-mile distribution infrastructure creates embedded finance penetration points for non-bank distributors seeking wallet and credit APIs.
- SAMA Open Banking Framework:Mandatory data-sharing protocols accelerate third-party provider onboarding and reduce compliance friction for new entrants.
- Mobile money interoperability:East African wallet-to-wallet rails enable cross-border BaaS product bundling previously blocked by closed-loop systems.
Market Restraints
- Cloud data residency mandates:Gulf Cooperation Council jurisdictions require sovereign server deployment, inflating infrastructure costs for foreign platform providers.
- API-native engineering scarcity:Regional universities produce insufficient OAuth and webhook architecture specialists, elongating implementation cycles.
- Capital adequacy thresholds:South Africa's National Payment System Act imposes reserve requirements that constrain balance-sheet-light BaaS models.
Strategic Opportunities
- Egyptian merchant ecosystem:Underbanked SME segments present white space for embedded lending products delivered through POS-integrated APIs.
- Biometric authentication convergence:Fingerprint and facial recognition APIs enable compliance with evolving KYC mandates across Gulf and East African markets.
- Cross-border remittance corridors:Gulf-to-East Africa payment flows create demand for multi-currency wallet infrastructure with real-time settlement.
Industry Challenges
- Core banking integration complexity:Legacy COBOL and mainframe systems at incumbent banks resist RESTful API layering, requiring middleware investment.
- Sandbox exit timelines:Central Bank of the UAE's graduated licensing extends time-to-revenue for pre-revenue fintechs burning runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Banking-As-A-Service Market |
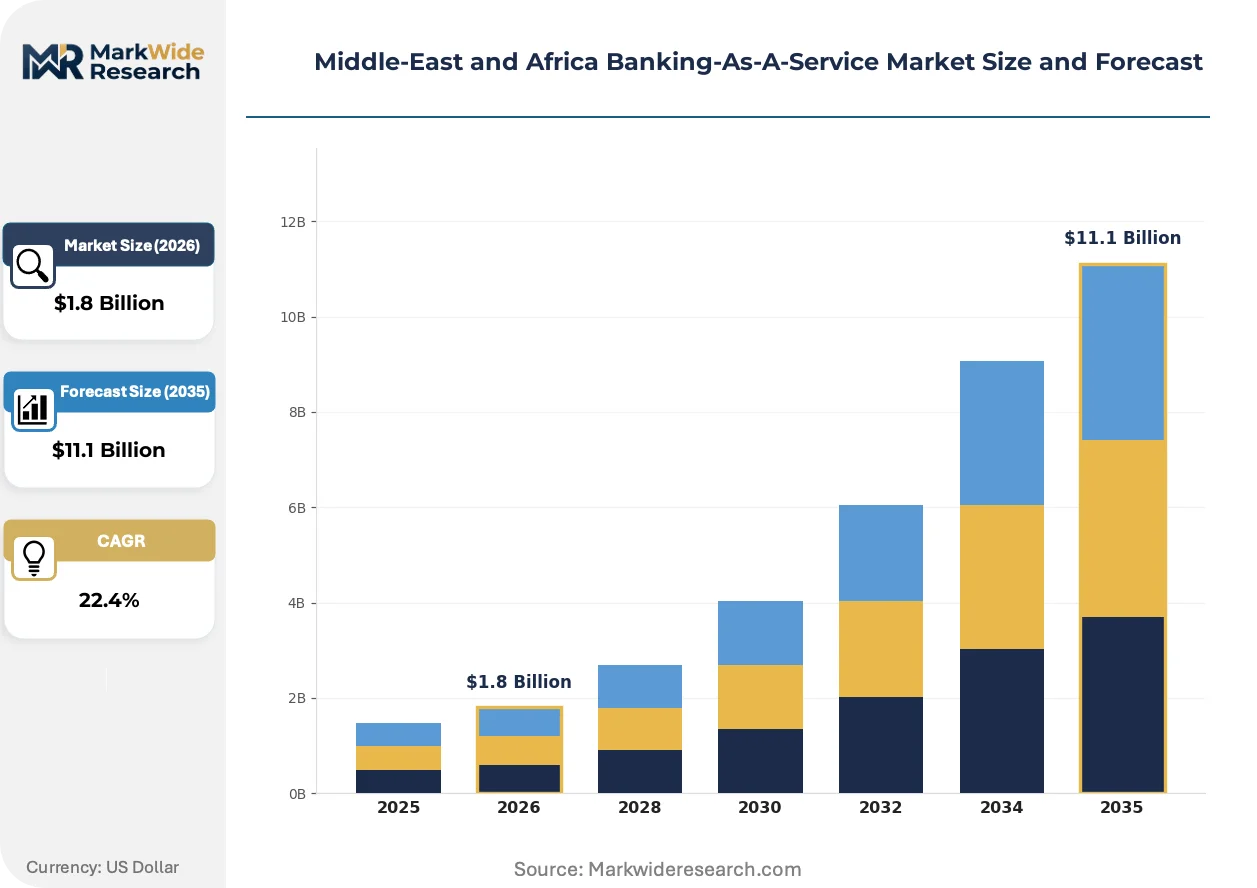
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Payment Processing, Compliance Solutions, Data Analytics Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Customer Type: Fintech Startups, Traditional Banks, Credit Unions, Retailers Technology: API Integration, Blockchain, Artificial Intelligence, Biometric Authentication |
| Companies Covered | NymCard, PayTabs, Flutterwave, Fawry, MFS Africa, Tarabut Gateway, Lean Technologies, JUMO, Mashreq Bank, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Banking-As-A-Service Market Shifts & Advancements
Artificial intelligence is penetrating fraud detection and credit scoring layers, while regulatory sandboxes compress product validation cycles across Gulf and African jurisdictions.
RESTful API architectures with OAuth 2.0 authentication are fragmenting monolithic banking cores into modular microservices. Fintech startups adopt these interfaces to embed payments and lending into non-financial apps without charter acquisition. The structural consequence is collapsing time-to-market for new financial products from years to quarters.
The Central Bank of the UAE's sandbox licensing regime permits live testing with limited customer cohorts before full authorization. This reduces regulatory risk for pre-revenue entrants and accelerates product-market fit validation. B2B infrastructure providers leverage this pathway to pilot treasury management APIs with corporate treasurers.
Merchant acquisition models are pivoting from standalone payment terminals to integrated software platforms with embedded finance. Kenyan and Egyptian POS providers bundle working capital advances with transaction processing, displacing traditional invoice factoring. This convergence is most visible in Nairobi's retail corridors and Cairo's informal trade clusters.
Middle-East and Africa Banking-As-A-Service Market Segmentation
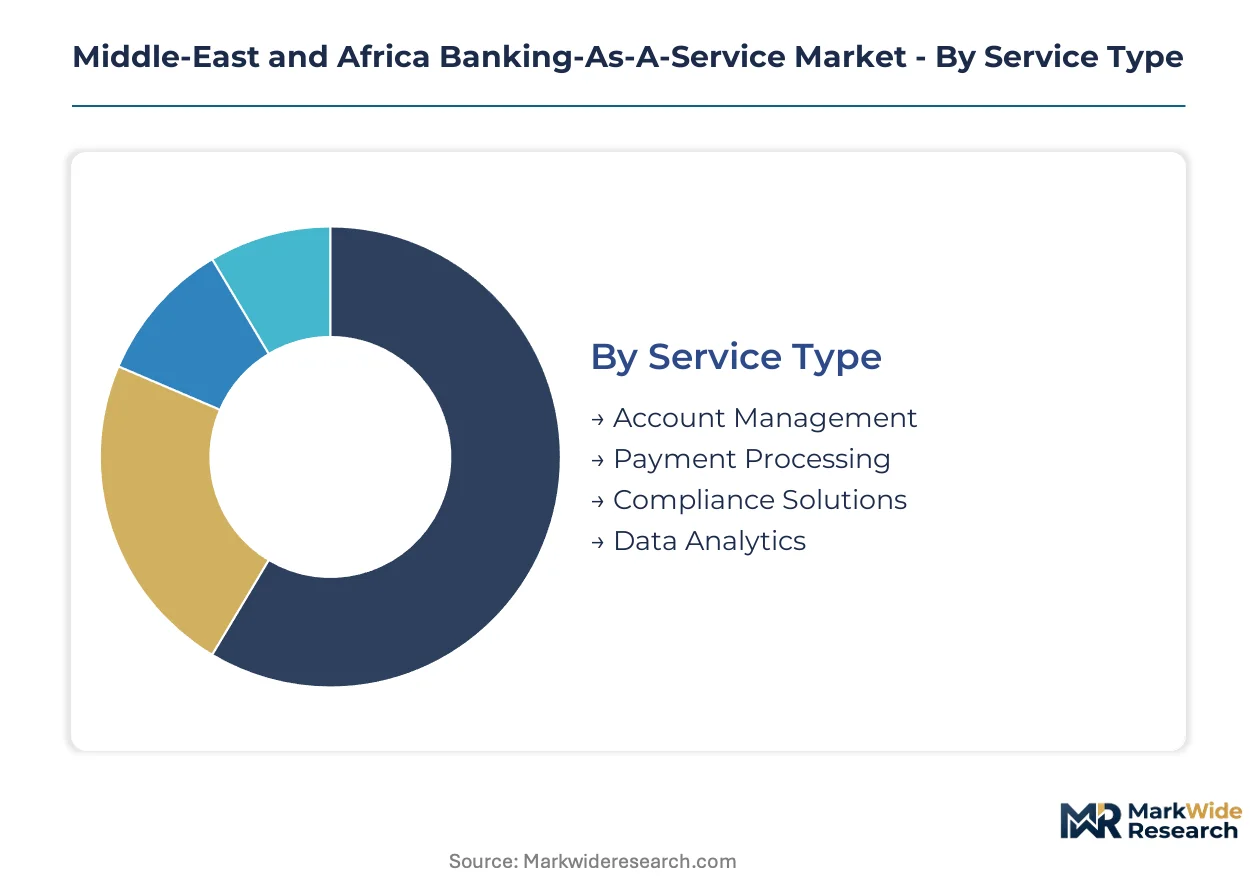
BaaS segmentation reveals where infrastructure investments concentrate and which service layers face displacement from adjacent fintech models. Understanding these divisions clarifies why certain deployment configurations dominate specific regulatory environments.
Service Type:
Payment Processing faces the most acute substitution pressure from specialized remittance providers and wallet operators building proprietary rails.
- Account Management:Core ledger services enabling virtual account creation, balance tracking, and transaction history through RESTful APIs. Nigerian agent banking networks and Egyptian SME aggregators drive demand for lightweight, KYC-embedded account infrastructure that bypasses traditional branch onboarding.
- Payment Processing:Real-time transaction routing across card networks, ACH equivalents, and mobile money rails. Concentrated in East African corridors where M-Pesa interoperability and cross-border wallet settlement create dense volume for API-based orchestration layers.
- Compliance Solutions:Automated AML screening, sanctions list monitoring, and regulatory reporting modules that reduce manual overhead for licensed BaaS providers operating across multiple Gulf and African jurisdictions.
- Data Analytics:Transaction pattern recognition and merchant behavior scoring that feeds credit decisioning engines for embedded lending products.
Payment Processing retains volume leadership; Data Analytics holds the steepest expansion curve.
Deployment Model:
Cost tiering separates elastic compute options from sovereign infrastructure investments required by Gulf data residency mandates.
- Public Cloud:AWS, Azure, and GCP-hosted environments delivering auto-scaling compute for transaction spikes. Fintech startups across Kenya and Nigeria favor this model for minimal capital deployment and rapid geographic expansion.
- Private Cloud:Dedicated server instances satisfying Saudi Arabian Monetary Authority and Central Bank of the UAE data localization requirements. Incumbent banks managing sensitive customer records absorb higher infrastructure costs for regulatory compliance.
- Hybrid Cloud:Split architectures placing transactional workloads in public environments while reserving core ledger data in private instances. South African providers leverage this configuration to balance agility against National Payment System Act residency rules.
- On-Premises:Legacy mainframe and COBOL-based systems at established banks resisting API layering without substantial middleware investment.
Public Cloud captures the greatest deployment share; Hybrid Cloud is climbing the fastest as compliance boundaries harden.
Customer Type:
Application intensity varies sharply between charter-seeking entrants and established institutions modernizing distribution.
- Fintech Startups:Pre-revenue and early-stage entities leveraging sandbox licensing to pilot embedded finance without full banking authorization. Concentrated in Dubai and Lagos where regulatory pathways compress time-to-market.
- Traditional Banks:Incumbent institutions outsourcing infrastructure to reduce core system modernization costs while preserving customer relationships. Egyptian and Saudi banks dominate this segment as they respond to open banking mandates.
- Credit Unions:Member-owned cooperatives seeking white-label digital channels to compete against mobile money penetration in East African markets.
- Retailers:Supermarket chains, fuel stations, and telecom agents embedding wallet and credit products at point-of-sale across Nigerian and Kenyan retail corridors.
Fintech Startups drive API consumption volume; Retailers are gaining share fastest as POS-integrated finance proliferates.
Technology:
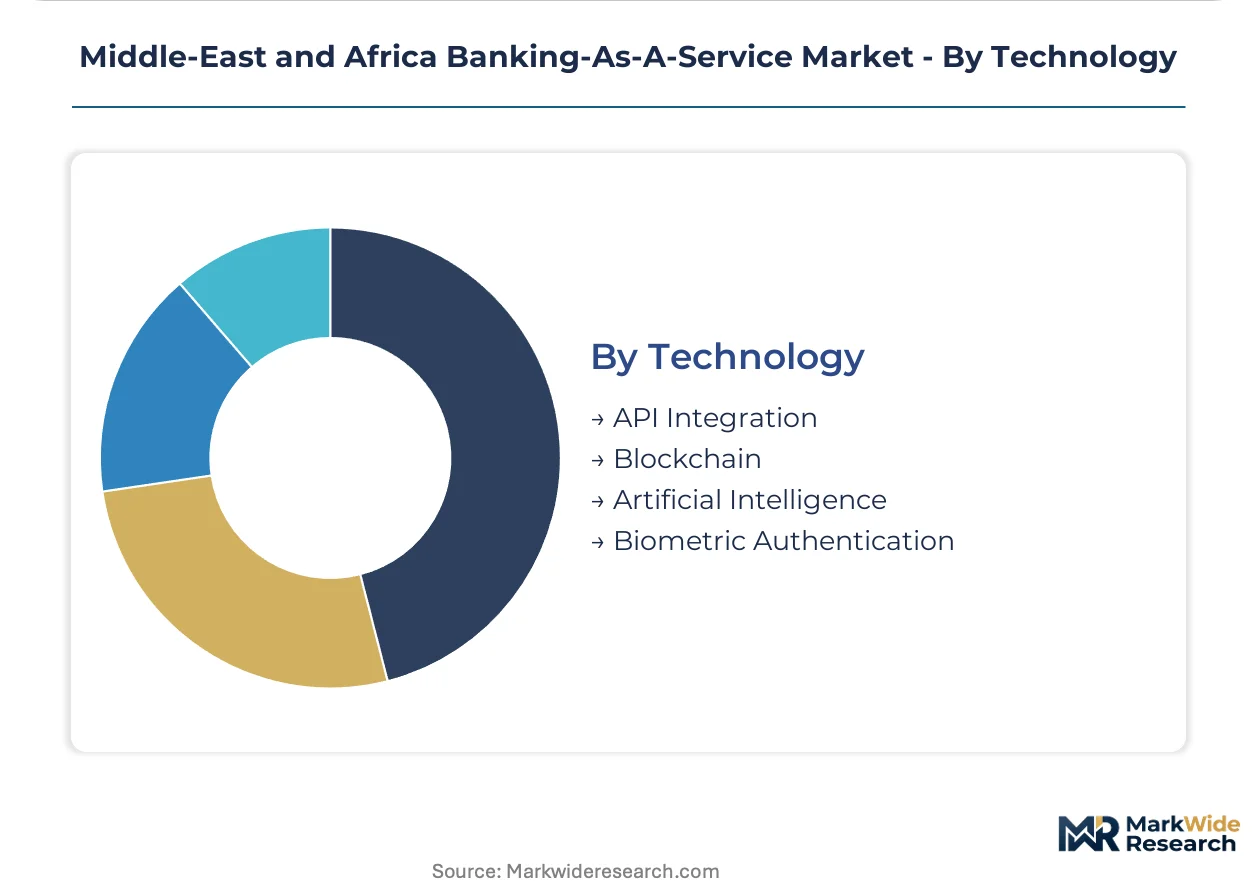
Maturity gaps separate proven integration layers from emerging authentication and distributed ledger approaches still seeking product-market fit.
- API Integration:OAuth 2.0-secured RESTful interfaces with webhook event streaming and sandbox environments for pre-production testing. Anchors current implementations across all Gulf and African BaaS deployments.
- Biometric Authentication:Fingerprint and facial recognition APIs enabling compliance with evolving KYC mandates. Saudi and UAE regulators are driving adoption through explicit authentication requirements for digital onboarding.
- Artificial Intelligence:Machine learning models for real-time fraud detection and alternative credit scoring using transaction history rather than traditional bureau data.
- Blockchain:Distributed ledger pilots for cross-border settlement and programmable money, though regulatory clarity remains limited across most Middle-East and Africa jurisdictions.
API Integration sustains technology leadership; Biometric Authentication follows the steepest adoption trajectory as compliance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi Arabian Monetary Authority anchors the dominant geography through its open banking framework, which mandates API standardization and data-sharing protocols. This regulatory architecture compresses time-to-market for new entrants and forces infrastructure consolidation among regional providers.
United Arab Emirates
Dubai's fintech cluster and Abu Dhabi's sovereign wealth deployment drive embedded finance demand across merchant segments. The Central Bank of the UAE operates a graduated sandbox licensing regime that permits live testing with limited customer cohorts before full authorization. Dubai International Financial Centre concentrates B2B infrastructure providers piloting treasury management APIs with corporate treasurers.
Saudi Arabia
Riyadh's Vision 2030 diversification and Jeddah's commercial banking corridors create dense distribution infrastructure for BaaS providers. SAMA's mandatory data-sharing protocols accelerate third-party provider onboarding and reduce compliance friction. King Abdullah Financial District hosts the densest concentration of API-native engineering talent in the Gulf region.
Nigeria
Lagos-based agent banking networks and mobile money interoperability create embedded finance penetration points for non-bank distributors. The Central Bank of Nigeria's licensing frameworks shape capital requirements for balance-sheet-light BaaS models. Lagos Island and Victoria Island clusters dominate API consumption volume for wallet and credit products.
South Africa
Johannesburg's corporate treasury demand and Cape Town's fintech startup density sustain hybrid cloud deployment configurations. The Financial Sector Conduct Authority and National Payment System Act impose capital and interoperability standards that shape product architecture. Sandton's financial district anchors traditional bank modernization initiatives responding to open banking mandates.
Egypt
Cairo's informal trade clusters and Alexandria's port commerce generate underbanked SME demand for POS-integrated lending products. The Central Bank of Egypt's regulatory evolution determines compliance costs for biometric authentication layers. Cairo's retail corridors witness the fastest proliferation of merchant acquisition models pivoting from standalone terminals to embedded finance platforms.
Middle-East and Africa Banking-As-A-Service Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cross-border payment rail operators and localized card issuers occupying distinct competitive positions. The market structure fragments across API infrastructure providers, mobile money aggregators, and legacy banks modernizing through partnership models. Three archetypes dominate: proprietary rail builders, sandbox-licensed fintechs, and incumbent banks outsourcing core infrastructure. Competitive moves concentrate on middleware investment for legacy system integration and sandbox exit acceleration to compress time-to-revenue.
Within the cross-border infrastructure tier, MFS Africa anchors proprietary mobile money connectivity across East African corridors. NymCard occupies a position among localized card-issuing specialists serving UAE and Saudi Arabian market requirements. Flutterwave exemplifies the developer ecosystem archetype, extending API infrastructure into Egyptian and Kenyan merchant segments. These three entities represent distinct strategic postures: rail ownership, geographic specialization, and platform expansion.
| Leading Market Players |
|---|
| NymCard |
| PayTabs |
| Flutterwave |
| Fawry |
| MFS Africa |
| Tarabut Gateway |
| Lean Technologies |
| JUMO |
| Mashreq Bank |
| Others |
Supply & Pricing Matrix
Long-term API capacity reservation contracts dominate BaaS procurement between fintech startups and cloud infrastructure providers, locking in compute access and cost predictability across multi-year deployment horizons in Saudi Arabia and the UAE.
Pricing Analysis
Geographic price spreads between Gulf Cooperation Council jurisdictions and East African markets reflect divergent data residency compliance burdens. SaaS-tiered subscription models anchor BaaS pricing, with differentiation driven by API call volume tiers and biometric authentication module inclusion. Pricing pressure stems from open banking mandate compliance costs, particularly for foreign platform providers facing sovereign server deployment requirements. Fintech startups exhibit highest price sensitivity, while traditional banks absorbing private cloud infrastructure costs show greater tolerance.
Supply Chain Analysis
Just-in-time compute provisioning prevails among Kenyan and Nigerian fintech startups leveraging public cloud elasticity, whereas strategic infrastructure stockpiling characterizes Saudi and UAE incumbent banks satisfying SAMA and Central Bank of the UAE data localization mandates. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore, with regional sovereign deployment expanding in Riyadh and Dubai. Raw material dependencies span server hardware components, cryptographic security modules, and biometric sensor arrays. Single-source vulnerability runs through hyperscaler concentration for API gateway services. Distribution feeds from cloud provider marketplaces into direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory sandbox pathways and mobile money interoperability standards creates niche entry points for specialized infrastructure providers serving underbanked merchant segments.
For Market Incumbents: Compound API-native engineering capabilities through targeted acquisition of OAuth and webhook architecture specialists in King Abdullah Financial District. Expand middleware investment for legacy COBOL system integration to defend against fintech disintermediation. Prioritize sandbox exit acceleration to compress time-to-revenue before runway exhaustion erodes competitive position. For New Entrants and Emerging Players: Compliance-as-a-service layers represent the most acute incumbent underservice, particularly automated AML screening modules spanning multiple Gulf and African jurisdictions. Egyptian SME aggregators and Nigerian agent banking networks offer the most penetrable demand pools. Pursue graduated licensing pathways through Central Bank of the UAE sandbox regimes to validate product-market fit before full authorization investment. For Investors and Strategic Acquirers: Capital is best deployed toward proprietary cross-border payment rail operators with established mobile money wallet connectivity across East African corridors. Long-term viability hinges on regulatory sandbox exit velocity and core banking integration completion rates. Watch biometric authentication mandate expansion across Gulf jurisdictions as the primary inflection signal for compliance solution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sandbox Licensing Completion | Accelerates time-to-revenue for pre-revenue fintechs burning runway under Central Bank of the UAE graduated regimes. |
| API-Native Engineering Acquisition | Addresses regional scarcity of OAuth and webhook specialists collapsing BaaS implementation timelines. |
| Biometric Authentication Module Development | Aligns product roadmaps with evolving KYC mandates from Saudi Arabian Monetary Authority and East African regulators. |
| Cross-Border Rail Partnership | Enables real-time settlement across Gulf-to-East Africa remittance corridors through M-Pesa interoperability. |
| Legacy Core Modernization | Reduces middleware investment burden for Egyptian and Saudi banks responding to open banking mandates. |
Research Methodology
The analysis maps API infrastructure providers, mobile money aggregators, and legacy bank partnership models, each validated through primary interviews with BaaS platform engineers, regulatory affairs leads at central banks, fintech CTOs, and merchant acquisition heads. Secondary sources include SAMA open banking framework documentation, Central Bank of the UAE sandbox licensing records, and National Payment System Act regulatory filings. Bottom-up transaction volume estimates triangulate against top-down market sizing from cloud infrastructure deployment disclosures.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon. Segmentation dimensions modeled span service type, deployment model, customer archetype, and technology layer. CAGRs derive from API consumption velocity curves and sandbox exit rate assumptions. Industry-specific inputs include mobile money interoperability expansion timelines and biometric authentication mandate adoption rates.
Material uncertainties — regulatory sandbox timeline extensions, sovereign data residency requirement tightening, and core banking integration failure rates — sit outside the modeled envelope. Forecasts reflect assumptions about open banking framework stability and API standardization convergence. Revision becomes warranted when biometric authentication mandate adoption crosses implementation cost thresholds that trigger provider margin compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Asia-Pacific Islamic Finance Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Payment Bank Solutions Market
Banking
Retail Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Africa Data Analytics in Banking Market
Banking
Banking Credit Analytics Market
Banking
Singapore Data Analytics in Banking Market
Banking
Cloud Computing Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Europe Neobanking Market
Banking
Smart Banking Solutions Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Credit Intermediation Market
Banking
South Korea Data Analytics in Banking Market
Banking
Virtual Teller Machine (VTM) Market