
 High-End Performance Packaging Market | 2026-2036
High-End Performance Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Performance Packaging Market Foresight
ISO 15378 certification for medicinal product packaging is bifurcating the supplier base into qualified pharmaceutical-grade providers and general industrial converters. Taiwan Semiconductor Manufacturing Company leverages cleanroom-compatible packaging protocols to protect wafer shipments across Asia-Pacific logistics lanes. Amkor Technology anchors its competitive position through proprietary anti-static tray designs for advanced semiconductor device transport. Samsung Electronics differentiates via vertically integrated material science capabilities spanning polymer formulation to finished barrier films.
High-end performance packaging denotes engineered containment systems designed to maintain specified environmental conditions including moisture vapor transmission rates below 0.1 g/m²/day, oxygen permeability under 0.01 cc/m²/day, and temperature stability across −80°C to +60°C ranges for sensitive product protection. Composite material laminates incorporating aluminum oxide vapor-deposited films command premium positioning due to superior barrier properties against gas and light ingress. Smart packaging segments integrating time-temperature indicators and NFC authentication tags represent the fastest-expanding innovation category, while vacuum packaging retains mature volume leadership in food preservation applications.
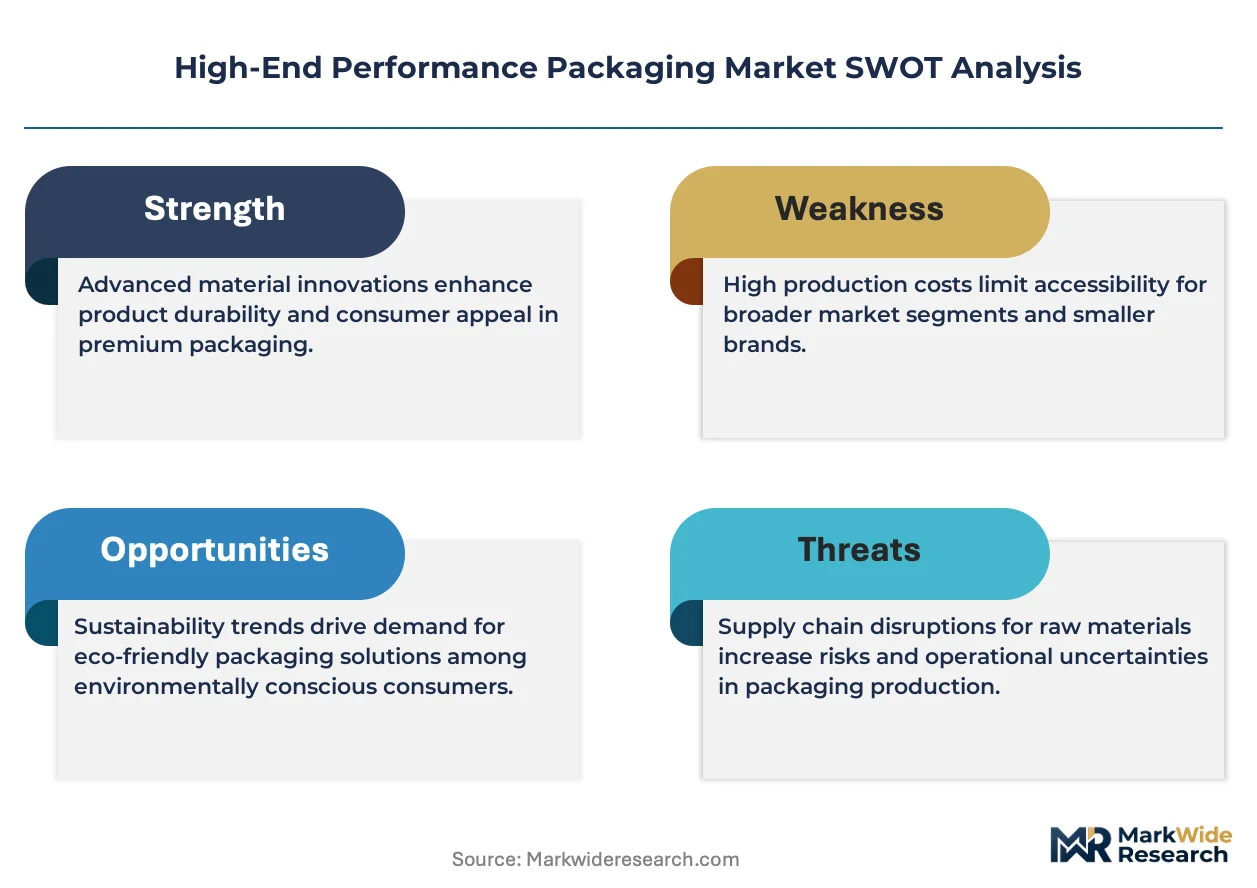
The US FDA enforces strict container closure integrity requirements under 21 CFR Part 211, compelling pharmaceutical packaging suppliers to validate seal performance against microbial ingress. The EU Green Deal's packaging waste reduction targets are forcing substrate transitions toward mono-material recyclable structures that maintain barrier equivalence. Japan's METI circular economy guidelines for plastic resource efficiency add compliance layers for exporters serving East Asian electronics supply chains. Stakeholders must monitor evolving Extended Producer Responsibility frameworks to anticipate material substitution timelines and capital allocation for compliant production assets.
Market Dynamics
Material science convergence with digital traceability systems is restructuring competitive advantage in high-end performance packaging, as pharmaceutical and semiconductor end-users demand validated environmental control plus real-time shipment visibility.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recovery mandates above 70% for plastic packaging are accelerating substrate innovation toward mono-material barrier laminates that maintain oxygen permeability thresholds under 0.01 cc/m²/day.
- Pharmaceutical cold-chain expansion:Biologics distribution networks spanning Frankfurt, Ludwigshafen, and Singapore require validated thermal packaging for −80°C to +60°C stability corridors.
- Aluminum oxide vapor deposition:This thin-film barrier technology enables flexible packaging formats previously constrained by metalized film rigidity.
Market Restraints
- Specialty polymer feedstock concentration:Cyclic olefin copolymer supply concentrates among three Japanese and German chemical producers, creating input cost volatility for pharmaceutical-grade containers.
- ISO 15378 certification timeline:The 12-18 month qualification process for medicinal product packaging creates regulatory friction that locks out general industrial converters from pharmaceutical contracts.
- Recyclable barrier performance gap:Mono-material structures struggle to match multi-layer laminates for moisture vapor transmission rates below 0.1 g/m²/day.
Strategic Opportunities
- Smart packaging convergence:NFC authentication tags integrated with time-temperature indicators are penetrating semiconductor logistics lanes where Samsung Electronics and Taiwan Semiconductor Manufacturing Company operate.
- US FDA container closure integrity:21 CFR Part 211 validation requirements for microbial ingress resistance create premium service opportunities for qualified suppliers.
- Japan METI circular economy guidelines:Plastic resource efficiency mandates are driving substrate transitions in electronics supply chains serving East Asian manufacturing clusters.
Industry Challenges
- Cleanroom-compatible production capacity:Wafer-grade packaging protocols require ISO Class 5-7 manufacturing environments that demand specialized HVAC and personnel gowning infrastructure.
- Extended Producer Responsibility alignment:Divergent national frameworks for material recovery are forcing packaging designers to engineer for multiple compliance endpoints simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Performance Packaging Market |
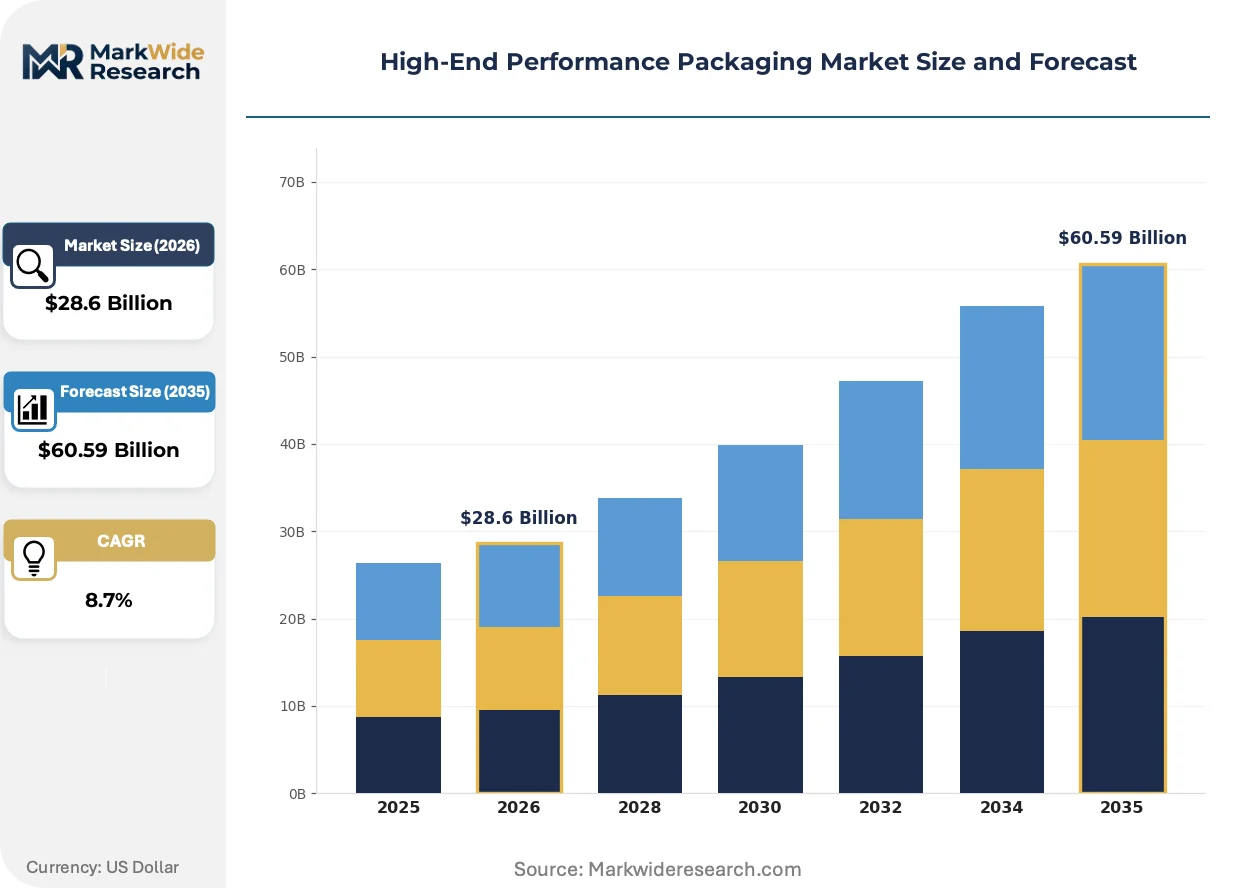
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Glass, Paper, Composite Form Factor: Box, Bottle, Pouch, Tray End User: Food & Beverage, Cosmetics, Pharmaceuticals, Electronics Innovation Type: Smart Packaging, Eco-Friendly Packaging, Vacuum Packaging, Modified Atmosphere Packaging |
| Companies Covered | Samsung Electronics, JCET Group, Intel Corporation, Analog Devices, Tongfu Microelectronics, Taiwan Semiconductor Manufacturing Company, Amkor Technology, Advanced Micro Devices, Advanced Semiconductor Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Performance Packaging Market Shifts & Advancements
Digital authentication layers are merging with passive barrier technologies, creating intelligent packaging systems that verify both environmental integrity and product provenance across complex multi-modal supply chains.
Active barrier systems incorporating oxygen scavengers and desiccant films are decomposing the traditional separation between primary packaging and controlled-atmosphere warehousing. Pharmaceutical distributors in Germany's Rhine-Main corridor are adopting these integrated formats for temperature-sensitive biologics. The technology is decomposing capital allocation patterns as logistics providers redirect warehouse investment toward last-mile conditioning rather than bulk storage infrastructure.
REACH restrictions on per- and polyfluoroalkyl substances are compelling fluoropolymer alternatives in high-barrier applications. The European Chemicals Agency substance evaluation process is accelerating substrate transitions toward silicon oxide and aluminum oxide vapor-deposited films. Medical device packaging for implantable products faces the most acute compliance pressure, with manufacturers qualifying new laminates ahead of 2025 restriction deadlines.
Consolidated procurement by semiconductor foundries is compressing supplier qualification cycles from 24 months to 14 months for cleanroom-compatible transport media. Taiwan and South Korean electronics manufacturers are unbundling packaging specification from logistics execution, creating direct contracting opportunities for specialized barrier film producers. This pattern is most visible in Asia-Pacific wafer shipment corridors where anti-static and particle-free requirements dominate vendor selection criteria.
High-End Performance Packaging Market Segmentation
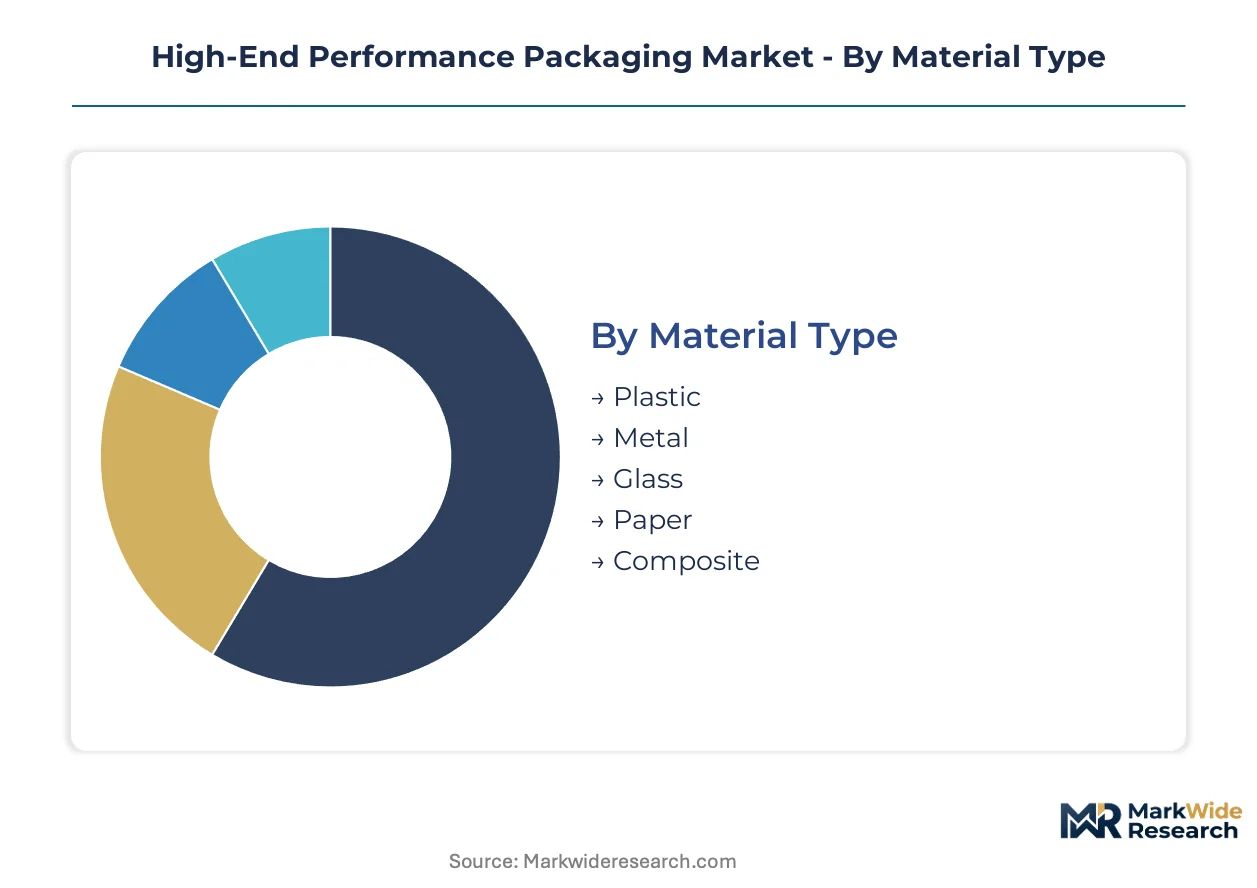
Engineered containment systems for sensitive products require precise material-form combinations validated against end-use environmental thresholds. Segmentation reveals where substrate substitution pressures intersect with regulatory compliance burdens and where smart functionality creates pricing power.
Material Type:
Composite laminates face the most acute substitution pressure as REACH restrictions on fluoropolymers force transitions to silicon oxide and aluminum oxide vapor-deposited alternatives.
- Composite:Multi-layer structures incorporating aluminum oxide vapor-deposited films achieve moisture vapor transmission rates below 0.1 g/m²/day. Pharmaceutical manufacturers in Germany's Rhine-Main corridor specify these laminates for biologics requiring −80°C to +60°C stability corridors.
- Plastic:Cyclic olefin copolymer dominates pharmaceutical-grade containers under ISO 15378 protocols. Supply concentrates among Japanese and German chemical producers, creating input cost volatility for medicinal product packaging converters.
- Metal:Aluminum barrier systems serve mature food preservation applications where oxygen permeability requirements exceed 0.01 cc/m²/day thresholds.
- Glass:Borosilicate and treated soda-lime formats retain preference for parenteral drug containment where inert surface properties outweigh fragility constraints.
- Paper:Fiber-based substrates with barrier coatings penetrate cosmetic and limited pharmaceutical applications where moisture sensitivity is moderate.
Plastic anchors the volume base while composite gains share at the steepest rate.
Form Factor:
Tray configurations command margin premiums in semiconductor logistics where anti-static and particle-free specifications dominate vendor selection.
- Tray:Proprietary anti-static designs protect wafer shipments across Asia-Pacific lanes. Taiwan Semiconductor Manufacturing Company and Samsung Electronics specify cleanroom-compatible protocols requiring ISO Class 5-7 manufacturing environments.
- Pouch:Flexible barrier formats incorporate time-temperature indicators and NFC authentication tags for pharmaceutical cold-chain validation. These smart-enabled configurations expand fastest in biologics distribution networks.
- Box:Rigid containment systems serve electronics and pharmaceutical bulk shipments where structural protection supersedes barrier performance.
- Bottle:Blow-molded and injection-stretch formats dominate liquid pharmaceutical and cosmetic applications requiring precise dosing interfaces.
Box formats retain the largest installed base while pouch configurations climb the fastest.
End User:
Pharmaceutical procurement concentrates specification authority among qualified suppliers, bifurcating the vendor base from general industrial converters.
- Pharmaceuticals:Container closure integrity requirements under US FDA 21 CFR Part 211 compel seal validation against microbial ingress. Biologics expansion drives demand for validated thermal packaging across Frankfurt, Ludwigshafen, and Singapore distribution nodes.
- Electronics:Semiconductor foundries compress supplier qualification cycles from 24 months to 14 months for cleanroom-compatible transport media. Anti-static tray designs anchor competitive positioning for advanced device protection.
- Food & Beverage:Vacuum packaging retains mature volume leadership where cost minimization outweighs smart functionality requirements.
- Cosmetics:Premium positioning drives mono-material recyclable structures under EU Green Deal packaging waste reduction targets.
Food and beverage provides the broadest volume foundation while electronics shows the steepest expansion trajectory.
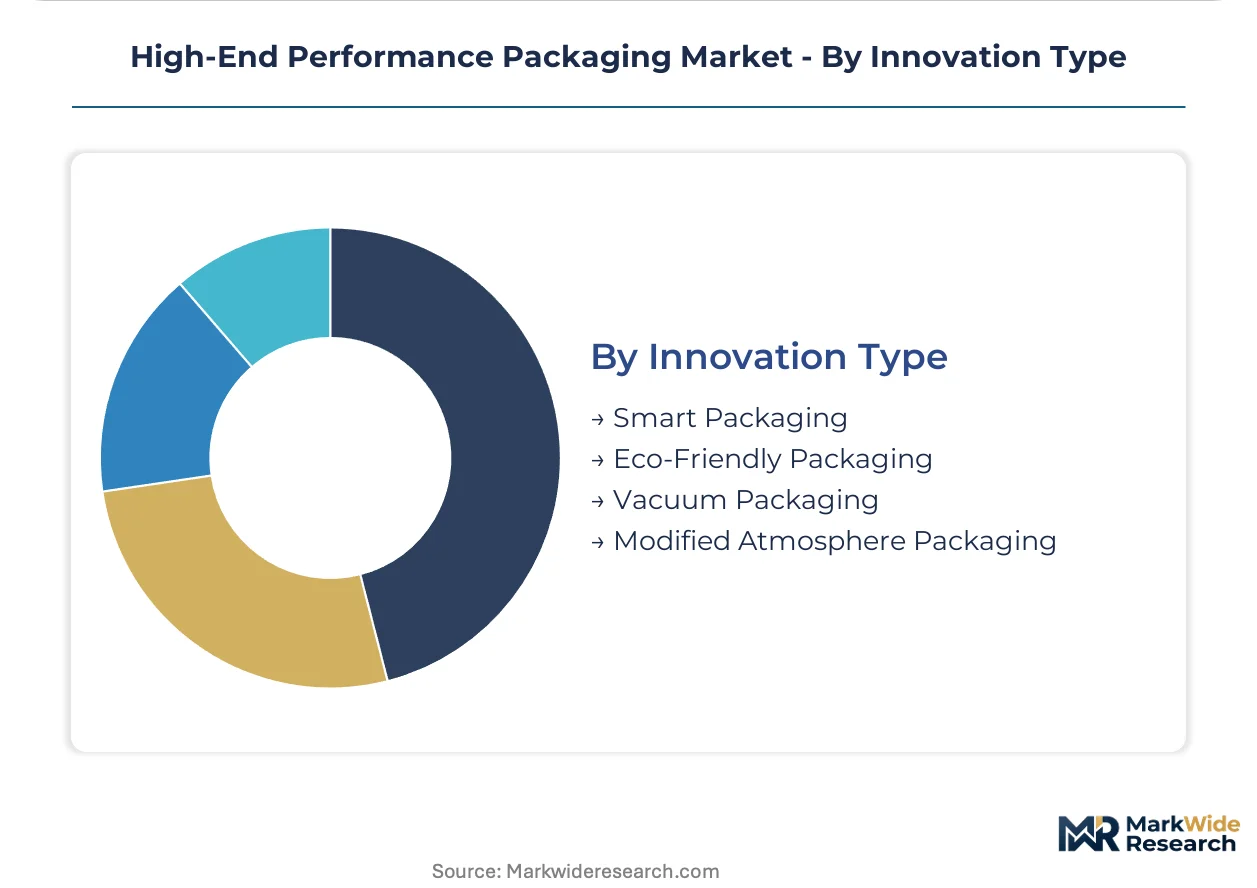
Innovation Type:
Eco-friendly substrate development absorbs the largest R&D allocation as Extended Producer Responsibility frameworks force material transitions.
- Smart Packaging:NFC authentication tags integrated with time-temperature indicators verify environmental integrity and product provenance. These systems penetrate semiconductor logistics lanes and pharmaceutical cold chains where real-time visibility commands premium pricing.
- Eco-Friendly Packaging:Mono-material recyclable structures struggle to match multi-layer laminates for barrier performance. EU Packaging and Packaging Waste Regulation mandates above 70% plastic recovery accelerate substrate innovation toward compliant formats.
- Vacuum Packaging:Mature passive barrier technology dominates food preservation where oxygen exclusion suffices without active monitoring.
- Modified Atmosphere Packaging:Active gas composition control extends shelf life for fresh produce and prepared foods in retail distribution.
Vacuum packaging holds the largest revenue base while smart packaging demonstrates the fastest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main logistics corridor connects Frankfurt Airport's pharmaceutical cold-chain infrastructure to Ludwigshafen's chemical manufacturing cluster, underwriting Germany's central role in temperature-validated barrier distribution.
Germany
Biologics manufacturers along the Rhine-Main corridor drive demand for validated thermal packaging spanning −80°C to +60°C stability ranges. The EU Packaging and Packaging Waste Regulation mandates recovery rates above 70% for plastic packaging, accelerating substrate transitions toward mono-material barrier laminates. Production concentrates in Hesse and Rhineland-Palatinate, where cleanroom-compatible facilities serve pharmaceutical export markets.
United States
Semiconductor foundries and pharmaceutical distributors require container closure integrity validation under US FDA 21 CFR Part 211 for microbial ingress resistance. The EPA oversees per- and polyfluoroalkyl substance restrictions that parallel REACH constraints, forcing fluoropolymer alternatives in high-barrier medical device applications. Boston and San Francisco Bay Area clusters anchor biologics packaging specification authority.
South Korea
Samsung Electronics and semiconductor suppliers compress supplier qualification cycles from 24 months to 14 months for cleanroom-compatible transport media. METI circular economy guidelines for plastic resource efficiency influence substrate selection in electronics supply chains serving East Asian manufacturing nodes. Gyeonggi Province hosts the densest concentration of advanced packaging qualification facilities.
Japan
Cyclic olefin copolymer supply concentrates among domestic chemical producers, creating input cost volatility for pharmaceutical-grade container converters. The PMDA enforces stringent quality management system requirements for medicinal product packaging that align with ISO 15378 protocols. Osaka and Tokyo metropolitan areas concentrate demand from medical device manufacturers qualifying implantable product laminates.
Singapore
Pharmaceutical cold-chain logistics hubs connect European biologics production to Asia-Pacific distribution networks, requiring validated thermal packaging for temperature-sensitive shipments. The city-state's national environmental agency advances extended producer responsibility frameworks that anticipate EU packaging waste reduction trajectories. Tuas biomedical park anchors regional demand for barrier film specification and qualification services.
High-End Performance Packaging Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with the supplier base bifurcating between ISO 15378-qualified pharmaceutical-grade providers and general industrial converters locked out by 12-18 month qualification timelines. Three strategic archetypes dominate: vertically integrated material science operators controlling polymer formulation through finished barrier film production; cleanroom-specialized fabricators maintaining ISO Class 5-7 manufacturing environments for wafer-grade protocols; and smart packaging integrators combining passive barrier technologies with NFC authentication and time-temperature indicator systems. Competitive moves concentrate on strategic partnerships for digital traceability integration and capacity expansion in aluminum oxide vapor-deposited film production.
Among Asia-Pacific semiconductor packaging specialists, Taiwan Semiconductor Manufacturing Company, Amkor Technology, and Samsung Electronics exemplify the vertical integration archetype. Taiwan Semiconductor Manufacturing Company anchors demand specification for cleanroom-compatible protocols across Asia-Pacific logistics lanes. Amkor Technology occupies a position within the anti-static transport media tier, with proprietary tray designs serving advanced semiconductor device protection requirements. Samsung Electronics represents the material science convergence model, with capabilities spanning polymer formulation through finished barrier film production.
| Leading Market Players |
|---|
| Samsung Electronics |
| JCET Group |
| Intel Corporation |
| Analog Devices |
| Tongfu Microelectronics |
| Taiwan Semiconductor Manufacturing Company |
| Amkor Technology |
| Advanced Micro Devices |
| Advanced Semiconductor Engineering |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for cyclic olefin copolymer resin lock in both supply access and price visibility for pharmaceutical-grade packaging converters serving ISO 15378-qualified markets. These arrangements insulate qualified suppliers from feedstock volatility while embedding cost pass-through mechanisms that preserve margin stability across raw material cycles.
Pricing Analysis
Certification level creates the primary spread between ISO 15378-qualified pharmaceutical-grade suppliers and general industrial converters. Three-tier pricing structure across premium, standard, and economy levels segments the market by barrier performance tier and validation depth. Cost compression in standard-grade laminates is intensifying because mono-material recyclable alternatives struggle to match multi-layer barrier equivalence. Generic industrial converters exhibit highest price sensitivity, while biologics manufacturers prioritize validated thermal performance over unit economics.
Supply Chain Analysis
Inventory buffers for aluminum oxide vapor-deposited films stretch lead times when semiconductor foundries accelerate qualification cycles. Supply concentrates in Japan and Germany for cyclic olefin copolymer resin, with South Korea anchoring cleanroom-compatible tray fabrication. Raw material dependencies span specialty polymer feedstocks, vapor-deposition equipment, and anti-static additive formulations. Single-source vulnerability concentrates among Japanese chemical producers for pharmaceutical-grade resin. Distribution runs through direct contracting with semiconductor foundries and pharmaceutical manufacturers, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cleanroom production capacity represents the scarcest deployable asset, with ISO Class 5-7 manufacturing environments requiring 18-24 month construction timelines that outpace demand acceleration from biologics and semiconductor logistics.
For Market Incumbents: Consolidate backward integration into aluminum oxide vapor-deposition capacity to secure barrier film supply against equipment lead time extension. Deepen certification moats by accelerating ISO 15378 qualification for secondary facilities before regulatory scrutiny tightens under EU Packaging and Packaging Waste Regulation enforcement. For New Entrants and Emerging Players: Lead with smart packaging convergence targeting pharmaceutical cold-chain logistics where real-time visibility commands premium pricing. The most penetrable white space sits in NFC-authenticated pouch formats for biologics distribution, with direct-to-pharma contracting bypassing established converter relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors cleanroom-specialized fabricators with captive vapor-deposition capability. Long-term viability hinges on substrate innovation pipelines capable of bridging recyclable mono-material performance gaps. Watch for REACH restriction acceleration on fluoropolymers as the inflection signal driving aluminum oxide adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vapor-Deposition Films | Aluminum oxide film shortages constrain pharmaceutical and semiconductor packaging output. |
| Backward Integration into Polymer Formulation | Captive cyclic olefin copolymer supply insulates against Japanese producer concentration risk. |
| Smart Packaging Technology Licensing | NFC authentication integration differentiates barrier systems in cold-chain logistics. |
| Joint Venture for Cleanroom Infrastructure | ISO Class 5-7 manufacturing partnerships accelerate qualification for wafer-grade protocols. |
| Long-term Supply Agreement with Foundries | Direct contracting with Taiwan Semiconductor Manufacturing Company locks in volume visibility. |
Research Methodology
A standing panel of pharmaceutical packaging procurement directors, semiconductor logistics managers, cleanroom facility operators, and barrier film R&D directors provided ongoing calibration against market developments. Primary interview data combined with secondary validation from FDA 21 CFR Part 211 guidance documents, ECHA REACH substance evaluations, EU Packaging and Packaging Waste Regulation impact assessments, and SEC filings from listed packaging converters. Bottom-up volume modeling across material type, form factor, and end-use segments triangulated with top-down value estimates derived from industry revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated material type, form factor, end-use industry, and innovation category dimensions. CAGRs were derived from log-linear trend fitting applied to validated baseline and terminal year estimates. Industry-specific forecast inputs included pharmaceutical biologics pipeline expansion rates and semiconductor wafer shipment growth trajectories.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment or accelerated REACH restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and substrate substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market