
 Active Smart and Intelligent Packaging Market | 2026-2036
Active Smart and Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Active Smart and Intelligent Packaging Market Analysis
The packaging tier divergence is pivoting around embedded sensor density versus passive barrier performance. Amcor plc leverages integrated oxygen-scavenging film platforms to anchor premium pharmaceutical contracts. Sealed Air Corporation competes through automated fulfillment-compatible designs that sustain e-commerce channel dominance. BASF SE differentiates via active polymer additives that extend shelf-life claims without refrigeration infrastructure.
Active Smart and Intelligent Packaging encompasses systems incorporating responsive materials, electronic identifiers, and data-capture substrates to monitor, record, or modify conditions within sealed environments. These configurations typically integrate printed sensors with conductive traces on flexible substrates, enabling real-time temperature logging, gas composition adjustment, or authentication verification across distribution networks. Smart Packaging leads current deployment volumes through RFID-enabled inventory visibility, while Intelligent Packaging segments command margin concentration where NFC and sensor fusion enable outcome-based freshness guarantees. Active Packaging segments retain structural importance in oxygen-sensitive food and injectable pharmaceuticals, though growth velocity concentrates where traceability applications intersect pharmaceutical serialization mandates.
FDA track-and-trace requirements under the Drug Supply Chain Security Act, EU MDR serialization provisions, and REACH compliance for electronic substrate materials collectively elevate barrier-to-entry thresholds for packaging converters. The EU AI Act introduces emerging scrutiny on algorithmic decision-making within intelligent packaging data systems. Stakeholders must evaluate whether captive sensor development or component sourcing strategies better align with diverging regulatory enforcement intensity across North American and European compliance regimes.
Market Dynamics
Pharmaceutical serialization mandates are compressing packaging procurement cycles while elevating sensor-embedded formats above passive alternatives, forcing converters to choose between captive electronics development and component sourcing partnerships.
Growth Catalysts
- Temperature-sensitive biologics expansion:Cold-chain logistics for cell therapies and mRNA vaccines requires real-time thermal monitoring through printed sensor substrates, pulling pharmaceutical manufacturers toward intelligent packaging formats.
- EU MDR serialization provisions:The Medical Device Regulation mandates unique device identification across distribution networks, compelling packaging converters to integrate RFID and NFC layers into sterile barrier systems.
- German industrial automation clusters:Concentrated pharmaceutical manufacturing around Frankfurt and Munich creates dense deployment zones for automated packaging lines with integrated track-and-trace verification.
Market Restraints
- Conductive ink cost volatility:Silver nanoparticle prices fluctuate with precious metals markets, squeezing margins on printed sensor substrates and forcing converters toward copper or carbon alternatives with inferior conductivity.
- East Asian electronics concentration:Taiwan and South Korea dominate flexible circuit fabrication, creating single-source vulnerability for European and North American packaging firms seeking integrated sensor modules.
- REACH compliance friction:ECHA restrictions on electronic substrate materials delay product launches as converters reformulate conductive adhesives and barrier films to eliminate restricted substances.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO track-and-trace requirements for export-bound generics create demand for serialized packaging among Mumbai and Hyderabad formulation clusters.
- RFID-NFC convergence:Dual-protocol tags enabling both supply-chain scanning and consumer smartphone authentication open premium positioning in anti-counterfeiting applications.
- E-commerce fulfillment compatibility:Automated warehouse systems favor packaging with machine-readable identifiers and damage-indicating sensors, creating specification advantages for compliant converters.
Industry Challenges
- Embedded systems engineering talent scarcity:Packaging converters face recruitment gaps for firmware developers capable of integrating temperature logging algorithms with flexible substrate manufacturing.
- FDA validation timeline compression:Drug Supply Chain Security Act enforcement phases demand packaging qualification cycles that outpace typical converter development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Smart and Intelligent Packaging Market |
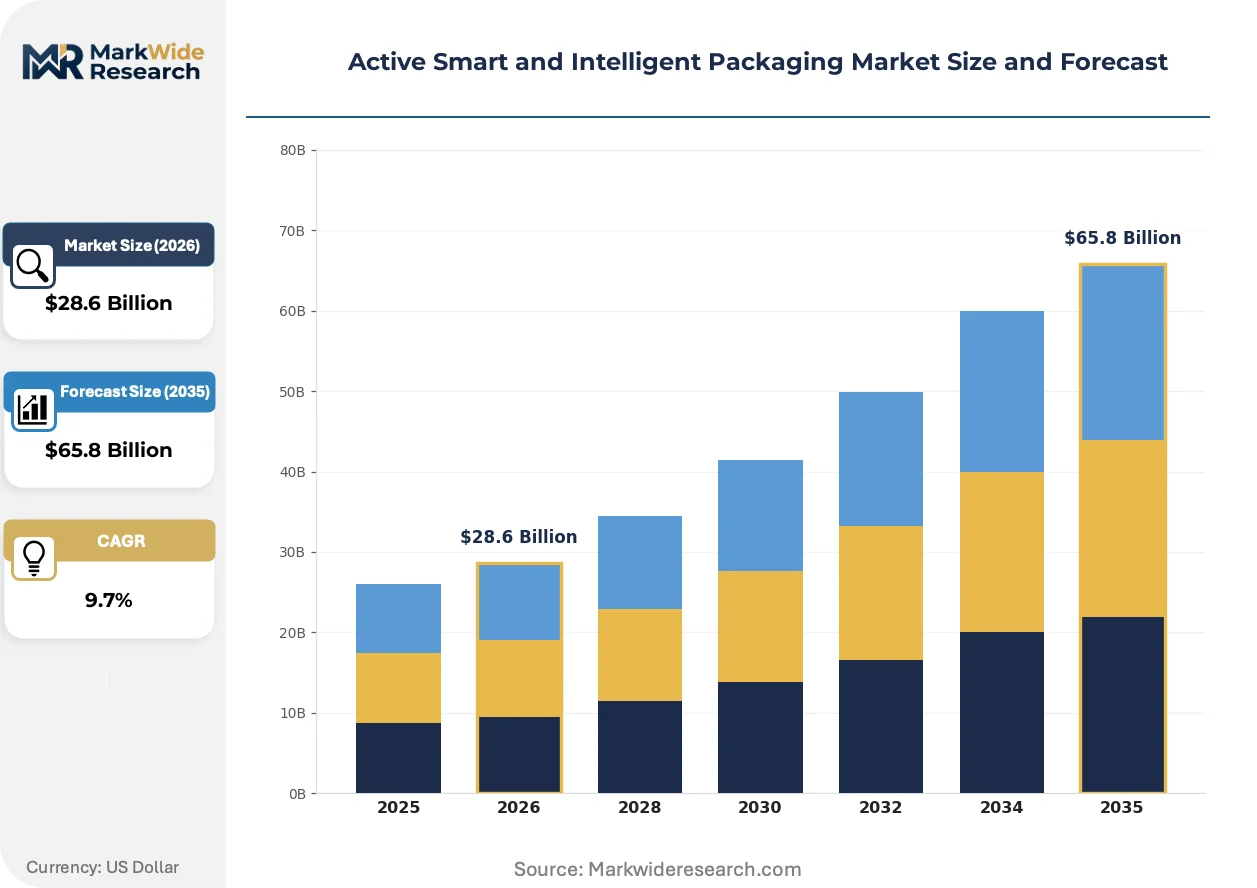
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Smart Packaging, Intelligent Packaging, Hybrid Packaging End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Sensors, RFID, NFC, QR Codes Application: Hermetic Sealing, Temperature Control, Freshness Monitoring, Traceability |
| Companies Covered | Amcor plc, Sealed Air Corporation, Tetra Pak International, Avery Dennison Corporation, Stora Enso, BASF SE, 3M Company, Ball Corporation, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Smart and Intelligent Packaging Market Emerging Trajectories
Sensor fusion architectures are collapsing the distinction between inventory tracking and condition monitoring, enabling packaging to serve simultaneously as logistics node and quality assurance device.
Printed electrochemical sensors on flexible polymer substrates is unifying gas detection and temperature logging within single-layer films. Pharmaceutical cold-chain operators in Germany and Switzerland are adopting these formats for biologics distribution. This convergence is compressing the supplier base toward converters with in-house electronics integration rather than film-only capabilities.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oxygen-scavenging barrier layers across European pharmaceutical packaging. ECHA enforcement timelines are accelerating substitution toward bio-based scavenger chemistries. Injectable drug manufacturers in the Netherlands and Denmark are qualifying alternative active packaging formats ahead of compliance deadlines.
Direct-to-pharmacy distribution models are shortening order cycles and fragmenting batch sizes. Wholesalers in France and Italy are demanding packaging with serialized unit-level identifiers rather than case-level codes. Hospital pharmacy networks in Spain are piloting NFC-enabled inventory systems that bypass traditional distribution tiers entirely.
Active Smart and Intelligent Packaging Market Segmentation
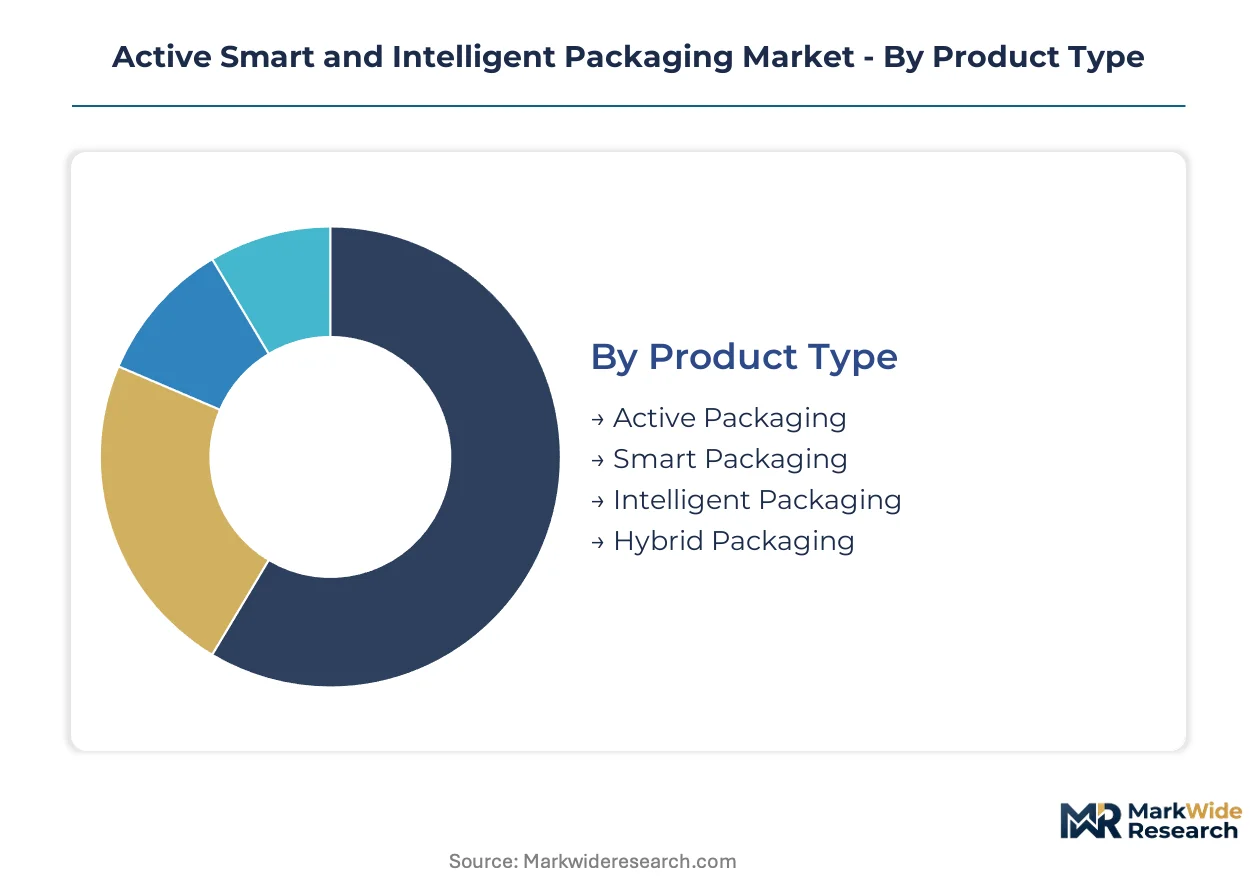
Segmentation in this market tracks diverging certification burdens across pharmaceutical serialization mandates versus food-grade barrier approvals. Each dimension reveals distinct margin structures and converter capability requirements.
Product Type:
Active Packaging formats require FDA validation for oxygen-scavenging claims in sterile barriers, while Intelligent Packaging faces EU AI Act scrutiny on algorithmic freshness scoring.
- Active Packaging:Oxygen-scavenging films and moisture-regulating substrates dominate injectable pharmaceutical applications. Dutch and Danish manufacturers are qualifying alternative scavenger chemistries ahead of ECHA per- and polyfluoroalkyl substance restrictions. Active Packaging sits at the top of the volume ranking, with Hybrid Packaging climbing the fastest.
- Smart Packaging:RFID-enabled inventory visibility systems integrate printed conductive traces on flexible substrates. German pharmaceutical cold-chain operators deploy these formats for biologics distribution where real-time thermal logging is mandatory.
- Intelligent Packaging:NFC and sensor fusion architectures enable outcome-based freshness guarantees with consumer smartphone authentication. Premium positioning in anti-counterfeiting applications drives margin concentration.
- Hybrid Packaging:Combines active barrier performance with electronic traceability layers. French and Italian wholesalers are demanding serialized unit-level identifiers in these formats.
Converters with in-house electronics integration capture premium positioning; film-only suppliers face compression toward commodity oxygen-scavenging volumes.
End User:
Cost tier stratification separates pharmaceutical serialization investments from food-grade sensor deployments.
- Food & Beverage:Printed electrochemical sensors on polymer substrates unify gas detection and temperature logging. Swiss cold-chain operators adopt single-layer films for premium perishables distribution.
- Pharmaceuticals:Temperature-sensitive biologics expansion pulls manufacturers toward intelligent formats with embedded temperature logging algorithms. FDA Drug Supply Chain Security Act enforcement compresses packaging qualification cycles.
- Cosmetics:Anti-counterfeiting NFC layers protect premium fragrance and skincare distribution in direct-to-pharmacy models. Spanish hospital pharmacy networks pilot inventory systems bypassing traditional tiers.
- Electronics:Moisture-indicating sensors protect semiconductor shipments through automated warehouse systems. E-commerce fulfillment compatibility creates specification advantages for compliant converters.
Pharmaceuticals commands the steepest expansion trajectory as serialization mandates harden; Food & Beverage retains structural volume leadership.
Technology:
Application maturity varies from established RFID supply-chain scanning to emerging NFC consumer authentication protocols.
- Sensors:Printed electrochemical and temperature-logging substrates on flexible polymer films. German industrial automation clusters around Frankfurt and Munich create dense deployment zones.
- RFID:UHF and HF protocols dominate warehouse scanning infrastructure. Automated fulfillment systems favor machine-readable identifiers with damage-indicating capabilities.
- NFC:Dual-protocol tags enabling both supply-chain scanning and consumer smartphone interaction. Premium positioning in anti-counterfeiting applications opens margin expansion.
- QR Codes:Low-cost serialization for generic pharmaceutical exports from Indian formulation clusters. CDSCO track-and-trace requirements for export-bound products create specification demand.
RFID maintains volume dominance in logistics applications; NFC gains share fastest where consumer authentication intersects premium brand protection.
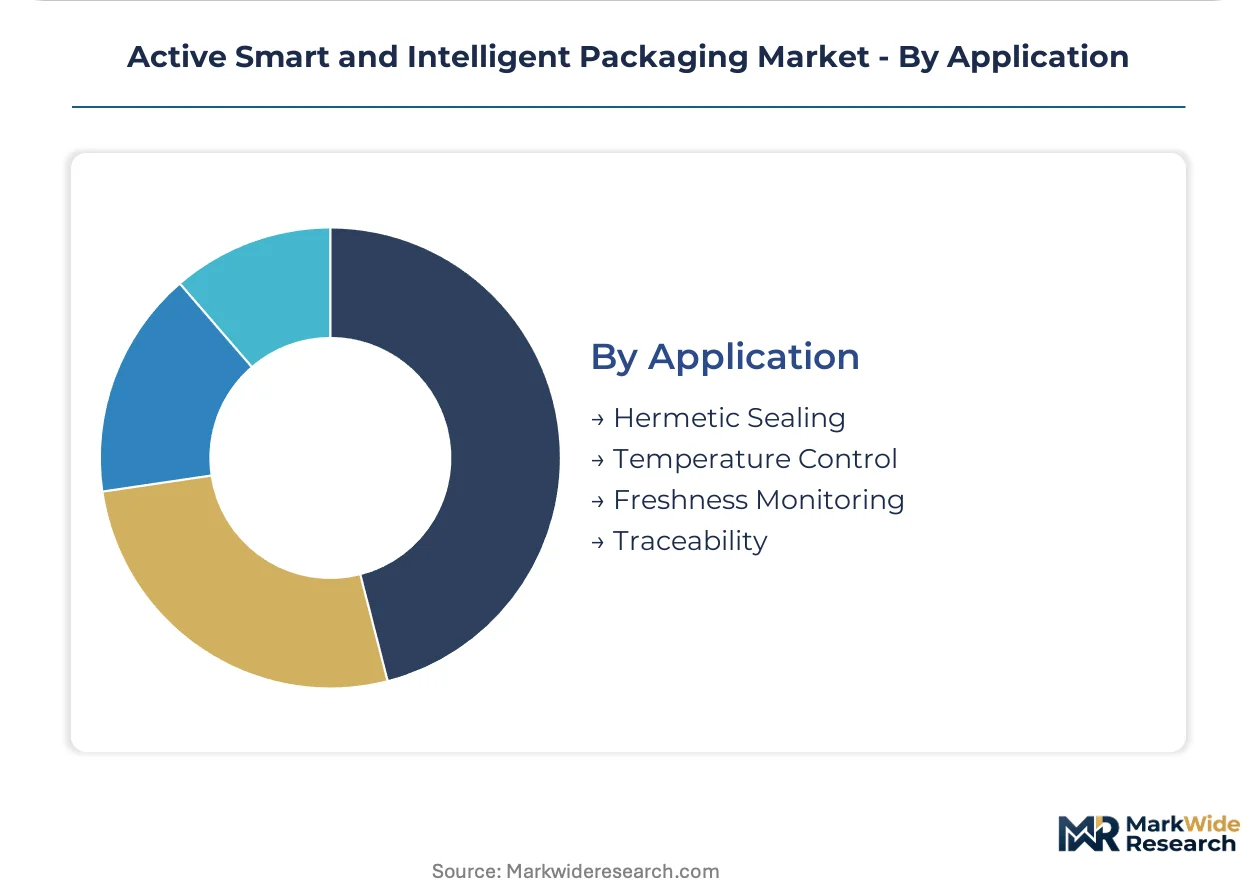
Application:
Customer type differentiation separates sterile barrier manufacturers from cold-chain logistics operators.
- Hermetic Sealing:Oxygen-scavenging barrier layers for injectable pharmaceuticals. REACH compliance friction delays launches as converters reformulate conductive adhesives.
- Temperature Control:Real-time thermal monitoring through printed sensor substrates for cell therapies and mRNA vaccines. Biologics distribution networks in Germany and Switzerland drive adoption.
- Freshness Monitoring:Gas composition adjustment via active polymer additives extending shelf-life claims without refrigeration infrastructure.
- Traceability:Serialized unit-level identifiers replacing case-level codes in French and Italian wholesale distribution. EU MDR unique device identification mandates reshape sterile barrier system design.
Traceability captures the fastest volume growth as serialization mandates expand; Temperature Control holds premium pricing power in biologics cold-chain applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineering talent concentrates in German industrial automation corridors, Swiss precision manufacturing zones, and Indian pharmaceutical formulation clusters. These workforce pools anchor regional specialization patterns that shape converter capabilities and regulatory compliance postures across three continents.
Germany
Frankfurt and Munich pharmaceutical manufacturing density drives intelligent packaging deployment for biologics cold-chain logistics. EU MDR serialization provisions compel sterile barrier converters to integrate RFID and NFC traceability layers. The Baden-Württemberg automation cluster hosts packaging line integrators embedding real-time thermal monitoring systems.
United States
FDA Drug Supply Chain Security Act enforcement compresses packaging qualification cycles for temperature-sensitive cell therapies. Serialization mandates elevate sensor-embedded formats above passive alternatives in domestic biologics distribution. Boston-Cambridge biotech corridor demand pulls converters toward printed electrochemical sensor substrates for mRNA vaccine shipments.
Switzerland
Swissmedic pharmaceutical quality standards anchor premium positioning for intelligent packaging in injectable drug exports. REACH restrictions on per- and polyfluoroalkyl substances accelerate reformulation of oxygen-scavenging barrier layers ahead of ECHA deadlines. Basel pharmaceutical manufacturing concentration creates dense qualification zones for alternative active packaging chemistries.
India
CDSCO track-and-trace requirements for export-bound generics create specification demand among Mumbai and Hyderabad formulation clusters. National pharmaceutical regulator mandates reshape packaging procurement for European and North American market access. Gujarat chemical manufacturing infrastructure supplies bio-based scavenger inputs for reformulated barrier films.
China
NMPA pharmaceutical serialization pilots align with international track-and-trace standards for biologics export certification. Dual carbon goals accelerate substitution toward sustainable active polymer additives in domestic packaging production. Yangtze River Delta electronics fabrication capacity supplies flexible circuit substrates for integrated sensor modules.
Active Smart and Intelligent Packaging Market Vendor Landscape
Top-tier vendors anchor pharmaceutical serialization contracts, while mid-tier converters compete on food-grade barrier performance and e-commerce fulfillment compatibility. The supplier base stratifies between film-only specialists and integrated electronics developers. Three archetypes dominate: diversified materials conglomerates with captive polymer research, packaging-focused converters with strategic electronics partnerships, and precision electronics firms backward integrating into flexible substrates. Competitive moves concentrate on M&A for sensor technology access and capacity expansion in automated packaging line integration.
Within the diversified materials tier, BASF SE and 3M Company exemplify archetypes leveraging polymer additive portfolios and adhesive substrate expertise respectively. Sealed Air Corporation occupies a position representing fulfillment-compatible design specialization. These three anchors illustrate how geographic origin and corporate structure shape strategic positioning: Ludwigshafen-based BASF SE as a European AG, Minnesota-based 3M Company as a US multinational, and North Carolina-rooted Sealed Air Corporation as a packaging-centric incumbent.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Tetra Pak International |
| Avery Dennison Corporation |
| Stora Enso |
| BASF SE |
| 3M Company |
| Ball Corporation |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
Silver nanoparticle conductive inks flow from East Asian refineries through three distinct pricing tiers before reaching pharmaceutical packaging converters in Germany and the United States, with FDA and EU MDR qualification costs determining final landed margins.
Pricing Analysis
The bundled electronics integration versus unbundled film-only service split defines competitive positioning across the supplier base. Three-tier pricing structure across premium, standard, and economy levels separates converters with in-house sensor firmware capabilities from component-sourcing specialists and commodity barrier film producers. Price differentiation hinges on FDA validation tier and volume scale, with serialized pharmaceutical contracts commanding substantial premiums over food-grade oxygen-scavenging volumes. Cost compression in the standard tier is intensifying because REACH reformulation requirements are extending development cycles without commensurate pricing recovery. Generic pharmaceutical exporters in India exhibit the highest price sensitivity, while biologics cold-chain operators in Switzerland demonstrate the least.
Supply Chain Analysis
FDA and EU MDR certification gating restricts qualified converter pools to facilities with validated sterile barrier manufacturing histories, concentrating pharmaceutical-grade supply in Germany, Switzerland, and the United States. Raw material dependencies center on silver nanoparticle inks from Taiwanese refineries, flexible polymer substrates from South Korean extruders, and bio-based scavenger chemistries from Dutch specialty chemical producers. Single-source vulnerability pervades East Asian electronics concentration, where Taiwan and South Korea dominate flexible circuit fabrication. Distribution runs through direct-to-pharmacy channels in France and Italy alongside traditional wholesale networks in Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German automation engineering costs and Indian pharmaceutical formulation labor, with CDSCO track-and-trace mandates creating specification premiums for export-bound packaging that offset domestic margin compression.
For Market Incumbents: Anticipate REACH per- and polyfluoroalkyl substance enforcement compressing oxygen-scavenging chemistry margins by accelerating reformulation timelines. Defensive consolidation through backward integration into flexible circuit substrate manufacturing in Baden-Württemberg automation corridors secures supply continuity. Certification investment in dual-protocol RFID-NFC tag architectures preserves premium positioning against emerging sensor fusion specialists.
For New Entrants and Emerging Players: Enter via CDSCO-mandated serialization contracts for Indian generic pharmaceutical exports, where Mumbai and Hyderabad formulation clusters face urgent compliance deadlines with limited qualified domestic converter capacity. The most penetrable segment lies in QR-code-based low-cost track-and-trace for non-biologic pharmaceuticals. A go-to-market angle anchored in rapid FDA validation timeline compression distinguishes entrants from incumbent development bandwidth constraints.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier converters with captive polymer additive capabilities because EU MDR and FDA serialization mandates are fragmenting procurement toward regionally qualified suppliers with integrated electronics partnerships. The five-to-ten-year viability window favors acquisition targets possessing both sterile barrier validation histories and strategic partnerships with Taiwanese flexible circuit fabricators. The signal to watch is ECHA enforcement intensity on electronic substrate materials, which would accelerate consolidation toward converters with in-house reformulation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flexible Circuit Substrates | Sealed Air Corporation and BASF SE reduce Taiwan single-source exposure through captive polymer extrusion capabilities. |
| Dual-Protocol RFID-NFC Tag Development | Avery Dennison Corporation captures premium anti-counterfeiting positioning in French and Italian pharmaceutical wholesale channels. |
| CDSCO Compliance Partnership | Amcor plc anchors Mumbai and Hyderabad formulation cluster contracts ahead of Indian export serialization deadlines. |
| Bio-Based Scavenger Chemistry Qualification | Stora Enso and Mondi Group secure Dutch and Danish injectable drug manufacturer volumes ahead of ECHA restrictions. |
| Automated Packaging Line Integration | Ball Corporation embeds real-time thermal monitoring systems in Frankfurt and Munich pharmaceutical manufacturing corridors. |
Methodological Framework
Direct dialogue with sterile barrier packaging engineers, pharmaceutical regulatory affairs directors, cold-chain logistics operators, and flexible electronics procurement managers grounded qualitative findings in operational reality. Secondary validation drew from FDA Drug Supply Chain Security Act enforcement documentation, ECHA REACH restriction timelines, CDSCO track-and-trace circulars, and SEC filings from diversified materials conglomerates. Bottom-up and top-down triangulation cross-referenced converter capacity announcements with pharmaceutical serialization mandate implementation schedules.
Bottom-up modeling of unit-level sensor-embedded packaging deployments across pharmaceutical, food and beverage, cosmetics, and electronics end uses converged with top-down macroeconomic drivers including biologics cold-chain expansion and e-commerce fulfillment automation. Segmentation dimensions spanned product type, end user, technology, and application with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves anchored to mandate enforcement phases and qualification cycle durations. Industry-specific forecast inputs incorporated ECHA substance restriction timelines and NMPA serialization pilot progressions.
Inputs from pharmaceutical converter engineering teams and regulatory filing databases were available through the study window; gaps in real-time silver nanoparticle pricing transparency and confidential contract terms between converters and biologics manufacturers introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding ECHA enforcement consistency and FDA validation timeline adherence. A model refresh is warranted upon material change in EU AI Act algorithmic decision-making scrutiny for intelligent packaging data systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market