
 3D Mobile Theater Market | 2026-2036
3D Mobile Theater Market Size, Share, and Industry Trends Forecast 2026-2036
3D Mobile Theater Market Outlook
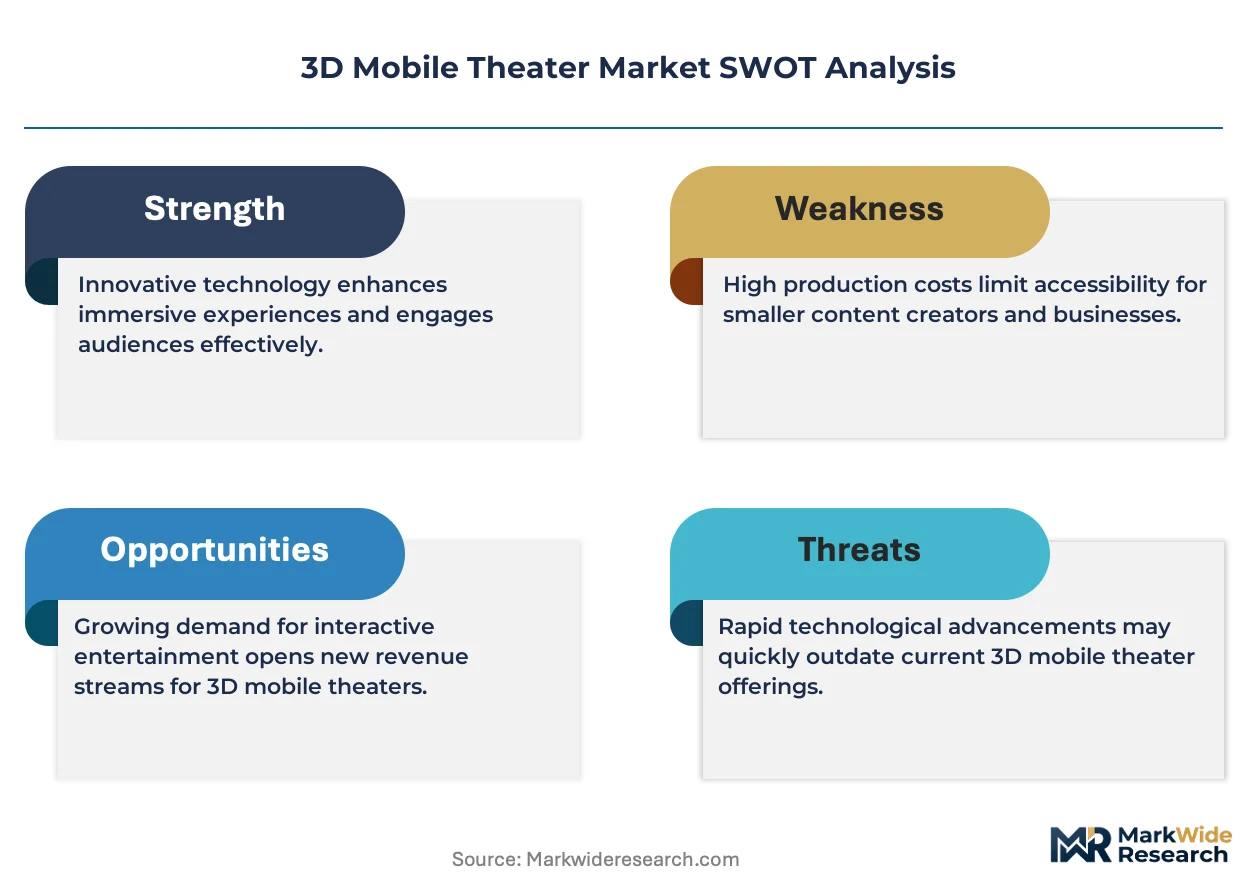
Premium immersive projection is decoupling from commodity portable screening kits in the 3D mobile theater space. Samsung Electronics leverages in-house panel fabrication to sustain its position in active 3D micro-projection. Sony Corporation anchors the high-resolution laser segment through proprietary light-source engineering. Barco N.V. competes in the rental-services channel for live-event deployments.
A 3D mobile theater comprises transportable projection, spatial audio, and stereoscopic display systems engineered for temporary venue installation, typically supporting 120 Hz refresh rates and 4K resolution per eye for immersive depth perception. The technology serves commercial exhibitors requiring rapid deployment without fixed infrastructure. Portable screens and projectors command the hardware revenue pool, while holographic and virtual reality modalities represent the fastest-expanding technology tier. Film screenings dominate application volume, though live events capture disproportionate margin due to premium ticket structures.
FCC equipment authorization and CE marking constrain electromagnetic emissions and optical safety thresholds for mobile projection units entering the US and European markets. ISO display-quality standards further shape product certification for international rental operators. Stakeholders must monitor evolving laser-safety classifications from OSHA and the EU's forthcoming ecodesign requirements for portable electronics.
Market Dynamics
The 3D mobile theater sector is bifurcating around laser-phosphor projection architectures, with rental operators demanding 30,000-lumen brightness thresholds for outdoor daylight viability while budget exhibitors retreat to lamp-based systems. This technical schism is redrawing vendor tiering and service-level expectations across temporary exhibition networks.
Growth Catalysts
- Laser safety reclassification:OSHA's updated Class 3R and 4 laser guidelines for portable emitters have clarified compliance pathways, accelerating venue insurance approvals for high-output mobile units in the United States.
- Outdoor cinema circuits:Germany's municipal summer screening programs have institutionalized mobile 3D deployment, creating predictable seasonal demand that justifies dedicated equipment pools.
- Holographic modulation:Advances in real-time depth-plane rendering are reducing eyewear bulk, enabling faster load-in times for touring live-event productions.
Market Restraints
- Phosphor wheel supply concentration:Japanese and Taiwanese ceramic substrate manufacturers control critical rare-earth coating capacity, exposing projector OEMs to input volatility.
- CE marking optical safety thresholds:The European Union's tightened blue-light hazard limits for temporary public display are extending certification timelines by four to six months.
- VR headset substitution:Standalone virtual reality systems are capturing immersive entertainment budgets from mobile theater operators in education and corporate training verticals.
Strategic Opportunities
- India's untapped exhibition infrastructure:Tier-2 and tier-3 cities lack fixed-screen density, creating white space for rapid-deployment mobile systems ahead of multiplex construction cycles.
- EU Green Deal ecodesign requirements:Upcoming portable electronics efficiency mandates will favor modular, upgradeable projection platforms over sealed-unit competitors.
- Esports live-event convergence:Stereoscopic spectator systems are penetrating gaming tournament circuits, merging broadcast and immersive display workflows.
Industry Challenges
- Projectionist certification gaps:Stereoscopic alignment and laser maintenance skills remain scarce in freelance technical labor pools, forcing rental houses to internalize training costs.
- FCC equipment authorization timelines:Electromagnetic compatibility testing for custom mobile rigs creates deployment bottlenecks for US touring productions.
- Legacy audio format integration:Spatial sound systems must bridge object-based immersive codecs with venue-installed channel-based infrastructure, complicating technical riders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Mobile Theater Market |
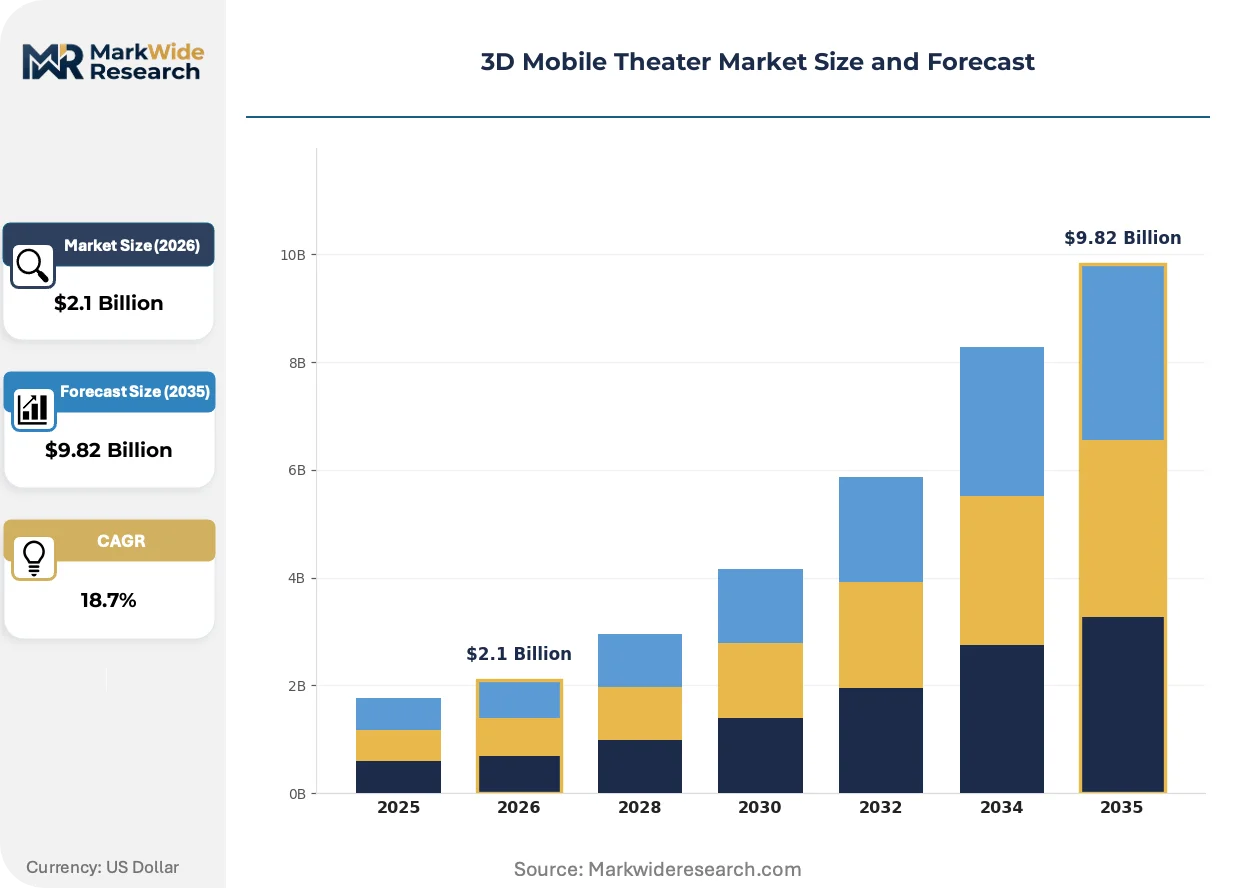
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Screens, Projectors, Audio Systems, Accessories Technology: Active 3D, Passive 3D, Holographic, Virtual Reality End User: Entertainment Venues, Educational Institutions, Event Organizers, Film Festivals Application: Film Screenings, Live Events, Training Sessions, Marketing Promotions |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics Inc., Sony Corporation, Panasonic Corporation, NEC Corporation, Christie Digital Systems USA, Inc., Barco N.V., Epson America, Inc., IMAX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Mobile Theater Market Strategic Shifts
Active modulation of liquid-crystal polarization layers is displacing passive filter systems in mobile 3D projection, enabling brighter perceived images and reduced ghosting artifacts. This shift demands recalibration of screen gain specifications and ambient-light rejection strategies across rental fleets.
Laser-phosphor solid-state illumination is rewriting the economics of high-brightness mobile deployment. Commercial exhibitors operating outdoor summer circuits are retiring mercury-arc lamp inventories two refresh cycles early. The technology is compressing total-cost-of-ownership calculations and enabling same-day redeployment between venues without thermal cycling delays.
CE marking's forthcoming extension to cover temporary outdoor display installations is tightening electromagnetic emissions testing for mobile projection trailers. European rental operators are pre-certifying chassis-integrated systems rather than treating projectors as discrete components. The policy shift most affects touring live-event suppliers serving cross-border festival circuits.
Short-term equipment subscription models are displacing outright purchase for seasonal operators. Germany's outdoor cinema cooperatives and North American film festival circuits are consolidating procurement through specialized AV rental exchanges. This behavioral pivot concentrates bargaining power with fleet-scale providers and compresses switching costs between hardware brands.
3D Mobile Theater Market Segmentation
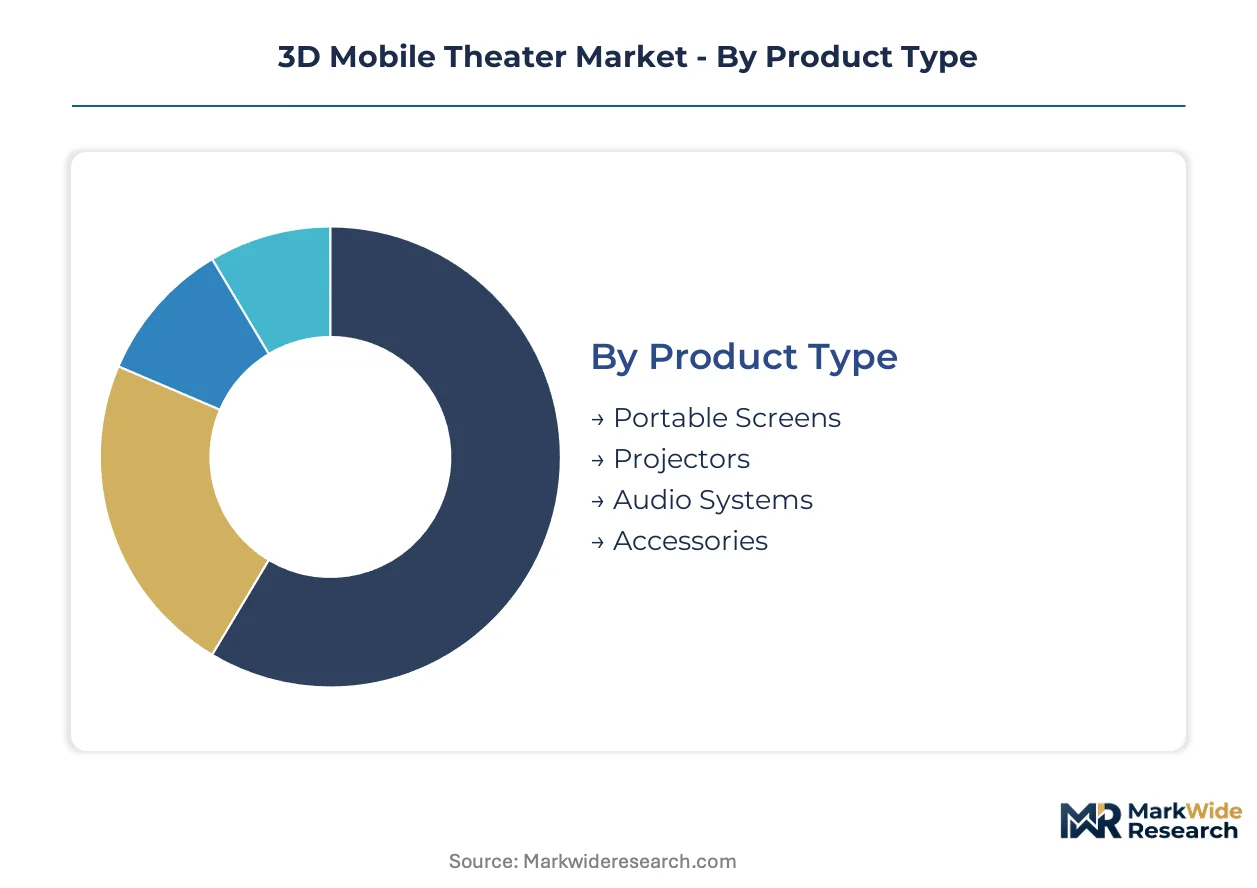
Segmentation in the 3D mobile theater market reveals how procurement priorities diverge between rental operators seeking rapid deployment and fixed-venue exhibitors optimizing for immersive fidelity. Understanding these splits clarifies where hardware margins concentrate versus where service revenues dominate.
Product Type:
Buyers segment procurement decisions around deployment velocity versus image fidelity trade-offs.
- Portable Screens:Tensioned front-projection surfaces with gain coefficients between 1.0 and 2.5 dominate outdoor daylight applications. German municipal summer circuits and North American film festival operators prioritize rapid rigging systems that collapse into standard shipping containers.
- Projectors:Laser-phosphor solid-state illumination units delivering 20,000 to 35,000 lumens anchor high-brightness mobile deployment. Rental houses serving live-event circuits demand sealed optical engines that eliminate filter maintenance during multi-city tours.
- Audio Systems:Object-based spatial arrays with Dante networking backbone integrate with venue-installed infrastructure.
- Accessories:Polarization filters, active shutter eyewear, and rigging hardware complete temporary installation packages.
Volume sits with Projectors; growth tilts toward Portable Screens as outdoor cinema circuits expand.
Technology:
Technology selection hinges on ambient light conditions and eyewear logistics for touring productions.
- Active 3D:Liquid-crystal shutter glasses synchronized to 120 Hz projection deliver full-resolution per-eye imagery without screen silvering requirements. Live-event operators favor active systems for reduced ghosting under mixed lighting.
- Holographic:Real-time depth-plane rendering eliminates eyewear entirely, compressing load-in times for festival deployments. The modality commands premium pricing in corporate marketing activations where guest comfort outweighs hardware cost.
- Passive 3D:Circular polarization through silver screens maintains brightness in fixed-temporary installations.
- Virtual Reality:Standalone headsets capture immersive entertainment budgets in training and education verticals.
Passive 3D carries current volume; holographic systems are climbing the fastest as eyewear logistics burden rental operators.
End User:
Customer type determines service-level expectations and equipment utilization rates.
- Film Festivals:Seasonal operators demand short-term subscription models with guaranteed spare-unit availability during peak programming. North American festival circuits have consolidated procurement through specialized AV rental exchanges.
- Event Organizers:Touring live-event suppliers require cross-border certified chassis-integrated systems that satisfy CE marking for temporary outdoor display across European festival circuits.
- Entertainment Venues:Pop-up cinema operators and outdoor screening cooperatives drive predictable seasonal demand.
- Educational Institutions:Universities and museums deploy mobile systems for STEM outreach and temporary exhibitions.
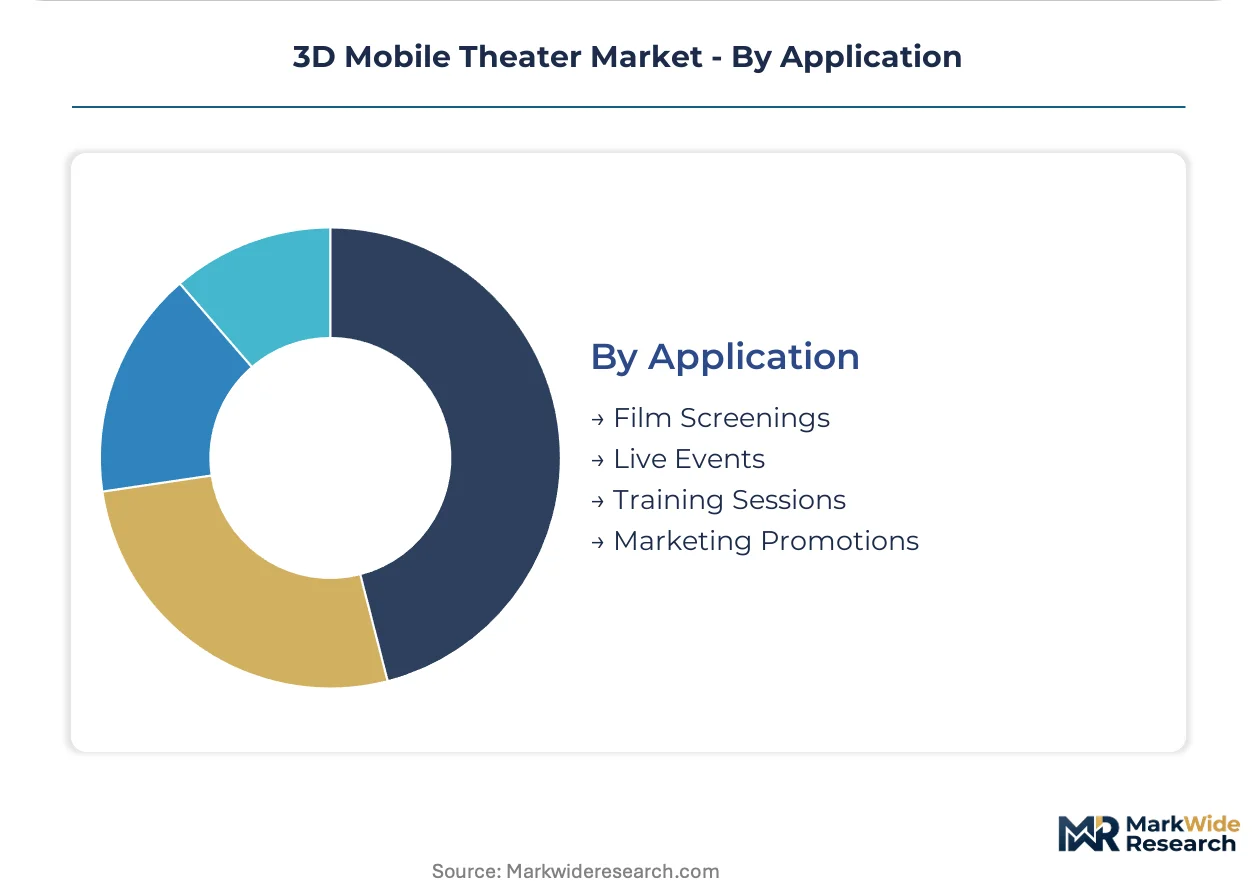
Entertainment Venues dominate installed base; Event Organizers gain share fastest through esports and immersive spectacle convergence.
Application:
Use case shapes the technical specification threshold and pricing architecture.
- Live Events:Stereoscopic spectator systems for gaming tournaments and music festivals merge broadcast and immersive display workflows. Premium ticket structures support 4K-per-eye laser projection with sub-5ms latency requirements.
- Film Screenings:Commercial exhibitors operating outdoor summer circuits prioritize brightness-per-watt efficiency and same-day redeployment capability without thermal cycling delays.
- Training Sessions:Corporate and military simulation applications demand spatial audio alignment with legacy channel-based infrastructure.
- Marketing Promotions:Brand activations favor holographic and VR modalities for viral social media capture.
Film Screenings anchor volume deployment; Live Events capture disproportionate margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the world's most concentrated cluster of mobile 3D rental operators, with Burbank-based technical houses supplying equipment to the festival circuit. FCC equipment authorization requirements for electromagnetic compatibility testing create deployment bottlenecks for US touring productions. OSHA's updated Class 3R and 4 laser guidelines have clarified compliance pathways for high-output mobile units.
United States
Film festivals in Austin, Telluride, and Tribeca drive seasonal procurement through specialized AV rental exchanges. FCC equipment authorization timelines for custom mobile rigs compress lead times for cross-country touring productions. Los Angeles-based technical houses maintain dedicated equipment pools for premium live-event deployments.
Germany
Municipal summer screening programs in Berlin, Munich, and Hamburg institutionalized mobile 3D deployment with predictable seasonal demand. CE marking's tightened blue-light hazard limits for temporary public display extend certification timelines for new equipment introductions. Bavaria's outdoor cinema cooperatives consolidate procurement through fleet-scale subscription models.
China
MIIT certification requirements for portable electronics shape product design for manufacturers targeting domestic exhibition infrastructure. The Yangtze River Delta cluster around Shanghai houses panel fabrication facilities supplying active 3D micro-projection components. Tier-2 cities lacking fixed-screen density create white space for rapid-deployment mobile systems.
Japan
METI efficiency standards for portable display equipment accelerate laser-phosphor adoption in commercial exhibition. Japanese ceramic substrate manufacturers control critical rare-earth coating capacity for phosphor wheel production. Tokyo-based technical operators service the domestic live-event circuit with cross-border certified chassis-integrated systems.
India
PLI scheme incentives for electronics manufacturing attract projector OEMs establishing local assembly operations. BIS certification requirements for imported display equipment create regulatory friction for international rental operators. Maharashtra and Karnataka host emerging clusters of AV rental houses serving tier-2 and tier-3 city exhibition demand.
3D Mobile Theater Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the 3D mobile theater value chain. The vendor base splits between integrated display manufacturers and specialized rental-service operators. Three archetypes dominate: panel fabricators with captive projection technology, pure-play laser-engineering specialists, and fleet-scale rental exchanges. Competitive moves concentrate on M&A to secure phosphor wheel supply and strategic partnerships for cross-border certification.
Within the integrated-manufacturer tier, Samsung Electronics Co., Ltd. and Sony Corporation exemplify divergent technical strategies. Samsung leverages in-house panel fabrication for active 3D micro-projection positioning. Sony anchors the high-resolution laser segment through proprietary light-source engineering. Barco N.V. occupies a distinct position in the rental-services channel for live-event deployments.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Sony Corporation |
| Panasonic Corporation |
| NEC Corporation |
| Christie Digital Systems USA, Inc. |
| Barco N.V. |
| Epson America, Inc. |
| IMAX Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up rental specialists have consolidated Germany's outdoor cinema cooperatives and North American festival circuits, compressing procurement leverage and enforcing subscription-based pricing discipline across mobile 3D deployment networks. This ownership concentration tightens vendor payment terms while amplifying fleet-scale buyers' ability to demand performance-guarantee clauses from projector OEMs.
Pricing Analysis
Uptime-guarantee pricing anchors commercial rental contracts, with German municipal summer circuits and live-event tour operators paying premiums for same-day spare-unit availability during peak deployment windows. Three-tier pricing structure across premium laser-phosphor, standard lamp-based, and economy LED-projection tiers separates brightness-per-watt performance grades. Cost compression in the lamp-based tier is intensifying because mercury-arc lamp inventories face accelerated retirement. Film festival operators exhibit highest price sensitivity due to seasonal utilization constraints, while esports live-event suppliers accept premium positioning for sub-5ms latency specifications.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Burbank, and Hamburg maintain chassis-integrated projection trailers for cross-border festival circuits. Manufacturing draws from Japan and Taiwan for ceramic phosphor wheel substrates, from China for active 3D micro-projection panels, and from Belgium for Barco's laser-engineering components. Single-source vulnerability concentrates in rare-earth coating capacity for phosphor production. Distribution runs through specialized AV rental exchanges that consolidate fleet procurement and compress switching costs between hardware brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are accelerating as projector OEMs pursue captive phosphor wheel supply to insulate margins from Japanese and Taiwanese ceramic substrate volatility. Backward integration into rare-earth coating capacity represents the decisive upstream lever separating tier-one vendors from assembly-dependent competitors.
For Market Incumbents: Deploy laser-phosphor sealed-optical-engine technology to extend maintenance-free tour cycles and defend against standalone VR headset substitution in corporate training verticals. Consolidate phosphor wheel supply through long-term offtake agreements with Japanese ceramic manufacturers before rare-earth coating capacity tightens further. Reinforce CE marking pre-certification capabilities to compress European deployment lead times against emerging chassis-integrated competitors. For New Entrants and Emerging Players: Begin with India's tier-2 and tier-3 cities where fixed-screen underpenetration creates white-space demand ahead of multiplex construction cycles. Target educational institutions with STEM outreach applications where budget constraints favor lamp-based systems over laser-phosphor premiums. Pursue equipment-leasing partnerships with Maharashtra and Karnataka AV rental houses to bypass BIS certification friction for imported display hardware. For Investors and Strategic Acquirers: Distressed-cycle entries favor fleet-scale rental exchanges with cross-border CE marking capabilities in Germany and established festival circuit relationships. Long-term viability hinges on subscription-model conversion rates and spare-unit pooling efficiency rather than hardware depreciation cycles. Watch OSHA laser safety reclassification momentum as inflection indicator for US venue insurance approval velocity and premium live-event deployment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Wheel Supply Agreement | Secures rare-earth coating capacity from Japanese ceramic substrate manufacturers against input volatility. |
| CE Marking Pre-Certification Investment | Compresses European deployment timelines by treating chassis-integrated trailers as unified systems. |
| Short-Term Subscription Platform Launch | Consolidates German outdoor cinema cooperative procurement through fleet-scale rental exchanges. |
| Esports Spectator System Integration | Merges broadcast and immersive display workflows for gaming tournament premium ticket structures. |
| Holographic Modulation R&D Partnership | Eliminates eyewear logistics burden for touring live-event productions seeking faster load-in times. |
Study Parameters
Multi-period observation of laser-phosphor adoption curves, outdoor cinema circuit procurement patterns, and FCC equipment authorization timelines anchored the trend analysis, supplemented by interviews with rental house technical directors, festival programming executives, laser safety compliance officers, and phosphor wheel procurement leads. Secondary validation drew from FCC equipment authorization databases, CE marking notification files, OSHA regulatory dockets, and ISO display-quality certification records. Bottom-up equipment deployment counts across municipal summer circuits triangulated against top-down manufacturer shipment disclosures.
Input-output matrices mapped projector lumen-class demand to phosphor wheel supply capacity, audio system Dante networking penetration, and holographic modulation technology readiness levels across the projection horizon. Segmentation dimensions modeled include product type, technology modality, end-user archetype, and application use case, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from equipment refresh cycle analysis and seasonal utilization rate assumptions, incorporating laser-phosphor total-cost-of-ownership compression and VR headset substitution elasticity as forecast inputs.
Underlying measurement precision varies by segment; laser-phosphor projector shipment data carries tighter precision than holographic modulation prototype deployments. Forecasts reflect documented assumptions regarding OSHA guideline implementation velocity, EU ecodesign mandate timing, and rare-earth supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Online Movie Market
Media and Entertainment
Southeast Asia Gaming Market
Media and Entertainment
Saudi Arabia Webtoons Market
Media and Entertainment
Arcade Games Market
Media and Entertainment
South East Asia Digital Out-Of-Home (Dooh) Market
Media and Entertainment
Germany OOH and DOOH Market
Media and Entertainment
Advertisement Management Solutions Market
Media and Entertainment
ASEAN OOH and DOOH Market
Media and Entertainment
Global Audio Streaming Market
Media and Entertainment
Traditional Music Market
Media and Entertainment
Entertainment Transcription Market
Media and Entertainment
Stock Music Software Market
Media and Entertainment
United Kingdom Marketing Agencies Market
Media and Entertainment
UK Arts Promoter Market
Media and Entertainment
Europe Professional Audio Video (Proav) Market
Media and Entertainment
Europe Programmatic Advertising Market