
 North America OOH and DOOH Market | 2026-2036
North America OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
North America OOH and DOOH Market Insights
The premium-static divide is rebalancing as programmatic digital inventory commands rate premiums while traditional paper-and-vinyl placements retreat to rural routes and secondary markets. Clear Channel Outdoor leverages its urban transit concessions to sustain density in top metropolitan zones. Lamar Advertising Company anchors its position through billboard dominance along interstate corridors. OUTFRONT Media competes via subway and rail assets in dense coastal markets.
Out-of-home and digital out-of-home advertising encompasses physical media assets—billboards, transit panels, street furniture, and place-based screens—designed to deliver brand messages to audiences in public spaces, typically employing LED modules with brightness ratings exceeding 5,000 nits for daylight visibility. Digital billboards within the media type segment lead absolute revenue contribution due to higher effective CPMs and dynamic creative rotation, while programmatic deployment models represent the fastest-expanding margin pool as automated buying reduces sales friction. Retailers among end users command the largest share of direct bookings, whereas automotive brands concentrate spending around auto shows and dealer proximity zones.
The FCC regulates wireless communications infrastructure enabling real-time content updates to connected displays, while municipal zoning boards across the United States and Canada enforce sightline and safety setback ordinances that constrain new permit issuance. The FTC monitors advertising content claims displayed on public screens, creating compliance obligations that favor established operators with legal infrastructure. Stakeholders must weigh capital allocation between retrofitting static assets with LED systems versus acquiring programmatic technology stacks as inventory commoditization pressures spread.
Market Dynamics
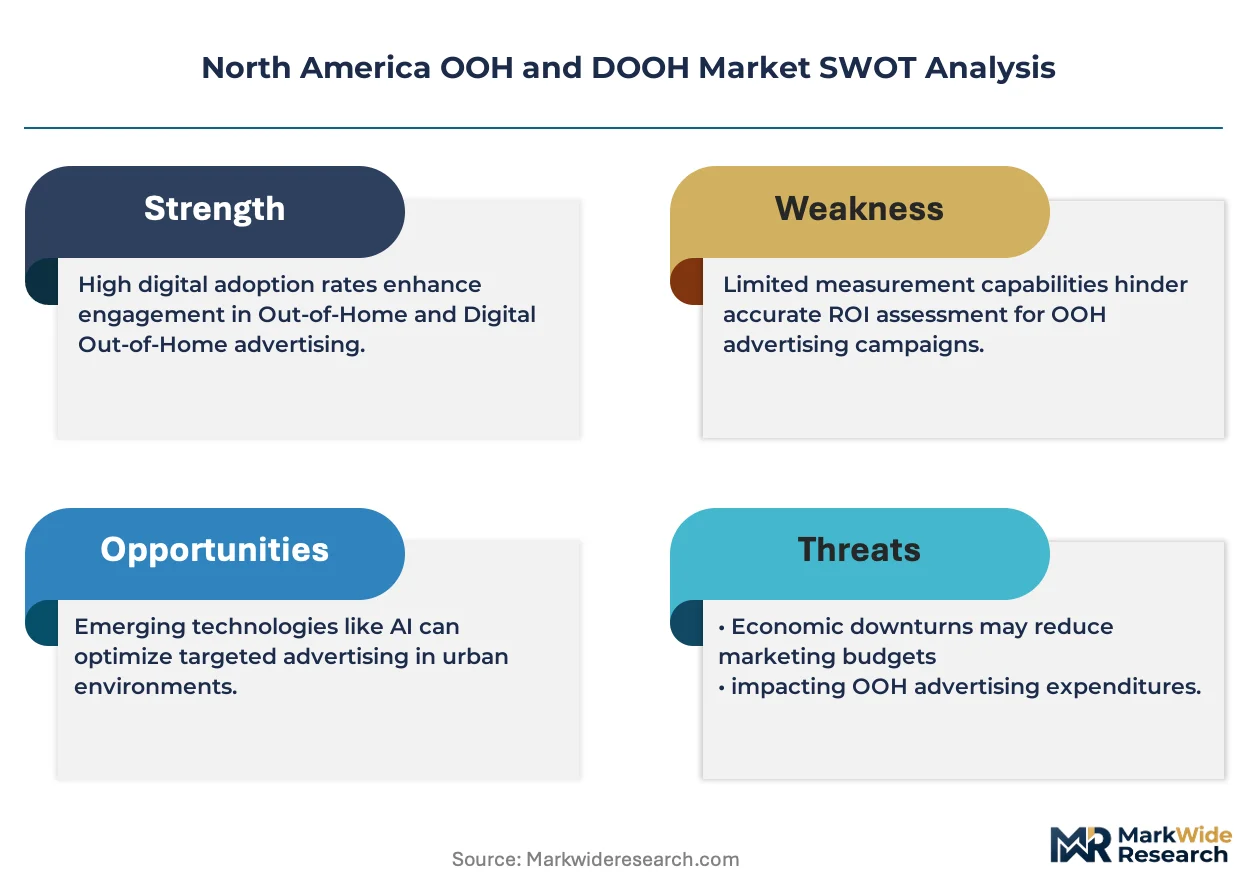
The transition from static vinyl to programmatic digital inventory is compressing sales cycles and fragmenting rate cards across the North America OOH and DOOH Market. Operators now face capital allocation decisions between LED retrofit investments and software platform acquisitions.
Growth Catalysts
- Programmatic Automation:Real-time bidding platforms reduce insertion-order friction for media buyers. Retail brands now execute same-day campaign launches.
- Transit Authority Concessions:Metropolitan transportation agencies in Toronto and Chicago are bundling station assets with street furniture rights. This consolidates inventory access.
- FTC Compliance Infrastructure:Established operators with legal departments capture spend from advertisers avoiding content-claim violations on public screens.
Market Restraints
- Municipal Zoning Friction:Sightline ordinances in Los Angeles and Vancouver constrain new billboard permits. Permit queues extend eighteen months.
- LED Module Supply Concentration:Display component sourcing clusters in East Asian manufacturing hubs. Tariff exposure creates margin volatility.
- Substitution by Connected TV:Addressable streaming platforms capture mobile audience segments. Commuter eyeball time fragments across devices.
Strategic Opportunities
- Secondary Market Penetration:Austin, Nashville, and Calgary exhibit undersupplied digital inventory relative to population growth. Early movers secure concession terms.
- Retail Media Network Convergence:Grocery and pharmacy chains deploy in-store screens with programmatic pipes. DOOH operators supply demand-side platform integration.
- Canadian Spectrum Allocation:Innovation, Science and Economic Development Canada is releasing 3.5 GHz bands for connected display backhaul. This enables rural network expansion.
Industry Challenges
- Programmatic Talent Scarcity:Demand-side platform specialists command premium compensation. Operators compete with ad-tech firms for data science hires.
- Legacy System Integration:Static asset management databases require API bridges to real-time bidding stacks. Technical debt slows automation rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America OOH and DOOH Market |
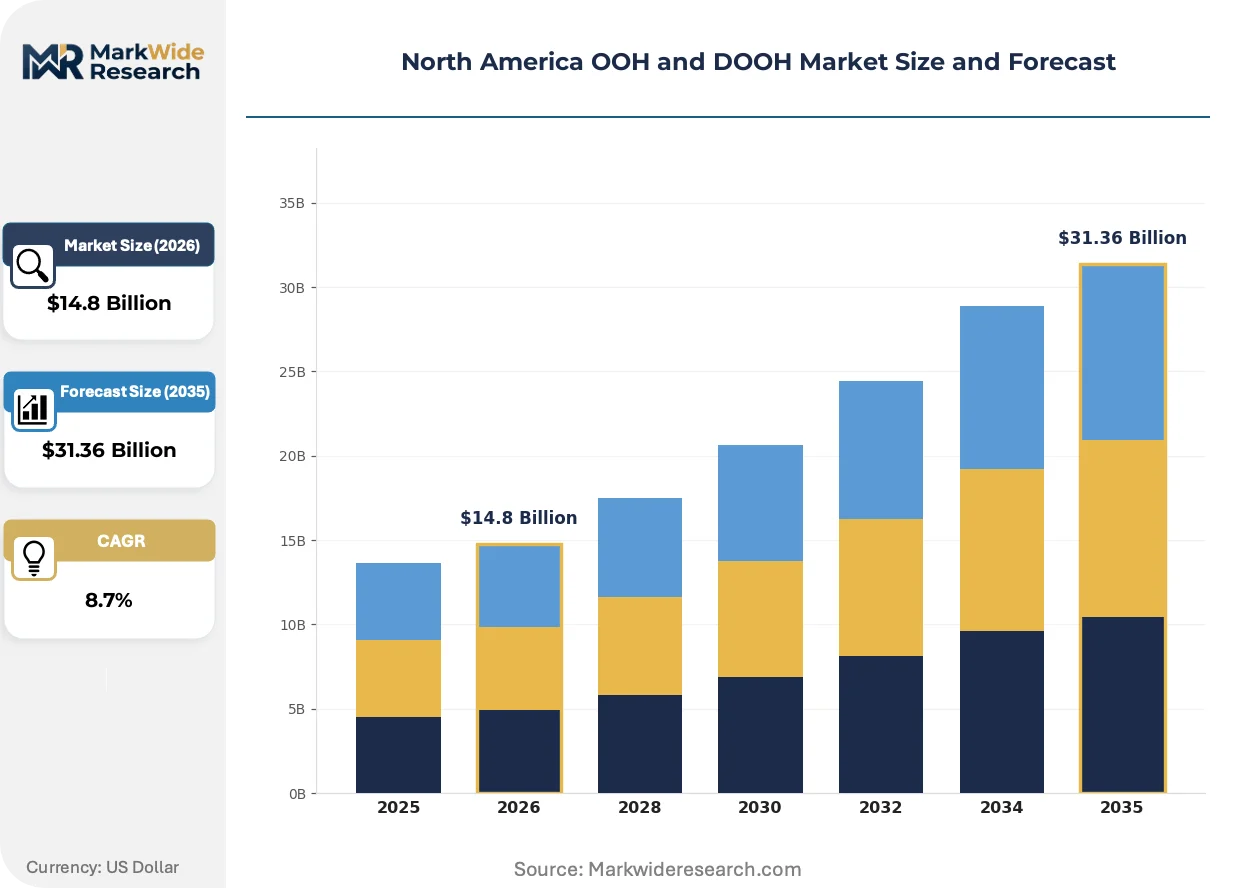
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Digital Billboards, Posters, Transit Displays, Street Furniture End User: Retailers, Automotive Brands, Entertainment, Tourism Deployment Model: Static, Programmatic, Mobile, Interactive Technology: LED, LCD, Projection, Augmented Reality |
| Companies Covered | JCDecaux North America, Clear Channel Outdoor, Lamar Advertising Company, OUTFRONT Media, PATTISON Outdoor Advertising, Daktronics, Intersection, GSTV, Broadsign International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America OOH and DOOH Market Trends and Innovations
Hardware commoditization and software platformization are splitting value capture away from physical asset ownership toward data and automation layers. Three developments define this shift.
LED display hardware is modularizing around standardized cabinet dimensions and driver architectures. Outdoor operators in Texas and Florida now source components from multiple vendors interchangeably. This supplier diversification is compressing capital expenditure timelines and enabling faster network refresh cycles.
The FCC's 2023 spectrum reorganization for unlicensed CBRS bands altered backhaul economics for rural digital billboards. Operators across Montana and Alberta are deploying private LTE networks instead of fiber trenching. This regulatory shift is accelerating coverage in interstate corridors previously deemed uneconomical.
Media buying patterns are fragmenting as direct-response advertisers demand impression-level attribution. Automotive and quick-service restaurant brands now optimize creative rotation by hour and weather condition. This behavioral shift concentrates in the New York-Toronto corridor where data infrastructure density supports real-time optimization.
North America OOH and DOOH Market Segmentation
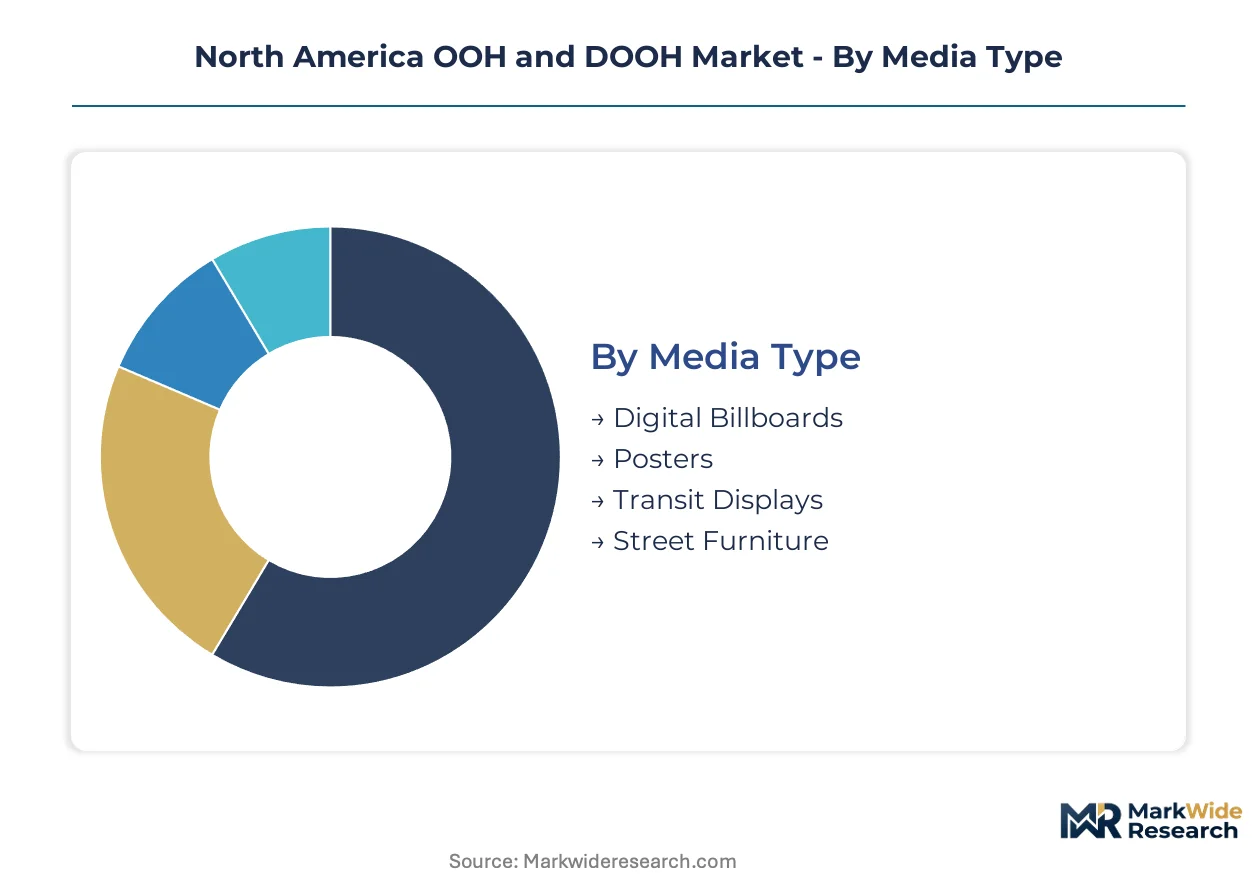
Segmentation in the North America OOH and DOOH Market reveals how capital flows diverge between legacy physical assets and software-enabled inventory. Understanding these splits guides operator decisions on retrofit timing, concession bidding, and technology partnerships.
Media Type:
Standalone roadside installations operate independently of surrounding infrastructure, while embedded transit and street furniture systems integrate with municipal assets and passenger flow patterns.
- Digital Billboards:Large-format LED arrays mounted along interstate corridors and urban arterials, typically exceeding 14 feet in height. Demand concentrates in the Texas Triangle and Florida's I-4 corridor where traffic density supports premium rate cards; operators face eighteen-month permit queues in Los Angeles and Vancouver.
- Transit Displays:Platform-mounted and vehicle-interior screens serving subway, commuter rail, and bus networks. Toronto's TTC and Chicago's CTA are bundling station assets with street furniture rights, consolidating inventory access for concession holders.
- Posters:Standardized vinyl and paper-faced panels in urban corridors and retail proximity zones. These units fill coverage gaps between premium digital placements.
- Street Furniture:Bus shelter panels, newsstand kiosks, and bench-mounted displays. Municipal contracts in Austin and Nashville are undersupplied relative to population growth.
Volume placements concentrate in Posters; the faster expansion belongs to Digital Billboards.
End User:
Customer segmentation by booking behavior shows direct-response advertisers prioritizing impression-level attribution, while brand advertisers emphasize reach and creative flexibility.
- Retailers:Grocery, pharmacy, and big-box chains executing same-day campaign launches through programmatic pipes. Walmart and Target are deploying in-store screens with demand-side platform integration, creating convergence opportunities with DOOH operators.
- Automotive Brands:OEMs and dealer associations concentrating spend around auto shows and dealer proximity zones. Creative rotation optimizes by hour and weather condition in the New York-Toronto corridor.
- Entertainment:Studios and streaming services booking transit and urban digital inventory for tentpole releases. Campaigns cluster in coastal metropolitan zones.
- Tourism:Destination marketing organizations and hospitality brands targeting airport and highway corridor audiences. Seasonal booking patterns align with travel peaks.
Retailers dominate direct bookings by volume; Automotive Brands are climbing the fastest as attribution capabilities mature.
Deployment Model:
Capital intensity varies dramatically across deployment approaches, with static assets requiring heavy upfront installation and programmatic platforms demanding ongoing software investment.
- Programmatic:Real-time bidding platforms enabling automated inventory access and dynamic creative rotation. Media buyers now execute same-day campaign launches; established operators with legal infrastructure capture spend from advertisers avoiding FTC content-claim violations.
- Static:Fixed vinyl and paper placements with predetermined creative runs. These assets retreat to rural routes and secondary markets as rate premiums shift to digital inventory.
- Mobile:Truck-mounted and vehicle-wrapped displays delivering geographic flexibility. Operators target event audiences and temporary construction corridor coverage.
- Interactive:Touch-enabled and gesture-responsive screens deployed in retail and transit environments. Technical debt from legacy system integration slows automation rollout for this segment.
Static deployments retain the largest installed base; Programmatic is gaining share fastest as sales friction diminishes.
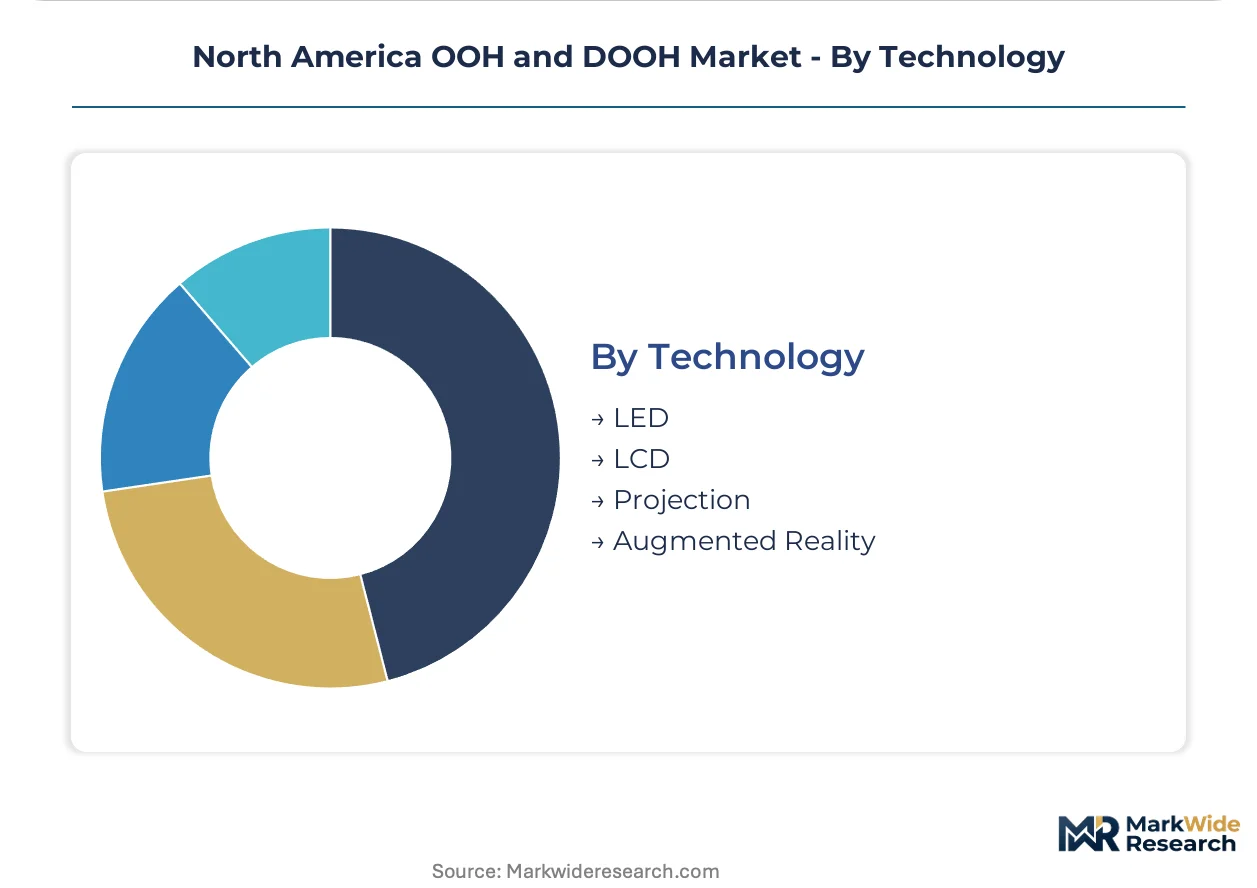
Technology:
Hardware sourcing patterns are splitting between modular LED components and specialized display architectures, with backhaul infrastructure determining rural viability.
- LED:Modular cabinet systems with standardized driver architectures and brightness ratings exceeding 5,000 nits for daylight visibility. Outdoor operators in Texas and Florida source components interchangeably from multiple vendors, compressing capital expenditure timelines.
- LCD:Lower-brightness panels deployed in sheltered transit and retail environments where ambient light control permits reduced specifications.
- Projection:Temporary and event-based installations requiring darkness or controlled lighting conditions. Applications cluster in entertainment and tourism verticals.
- Augmented Reality:Overlay systems integrating mobile device cameras with physical display locations. Early deployments concentrate in the New York-Toronto corridor where data infrastructure density supports real-time rendering.
LED dominates capital deployment by volume; Augmented Reality is expanding most quickly as mobile integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York-Toronto corridor concentrates the highest density of digital inventory deployments, with programmatic trading volumes exceeding all other North American corridors combined. This metropolitan spine anchors revenue generation for transit and street furniture networks.
United States
Transit authority concessions in Chicago and New York bundle station assets with street furniture rights, consolidating inventory access. The FCC governs wireless spectrum allocation for connected displays, enabling real-time content updates. Los Angeles faces eighteen-month permit queues due to sightline ordinance enforcement.
Canada
Toronto's TTC network expansion drives transit display demand alongside Calgary's undersupplied digital inventory relative to population growth. Innovation, Science and Economic Development Canada releases 3.5 GHz spectrum bands for connected display backhaul. Vancouver's municipal zoning boards enforce strict setback requirements constraining new billboard permits.
Mexico
Mexico City Metro's station modernization creates embedded display opportunities for transit operators. The Federal Telecommunications Institute regulates wireless communications infrastructure enabling content distribution. Monterrey's industrial corridor attracts mobile billboard deployments targeting manufacturing workforce traffic.
North America OOH and DOOH Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America OOH and DOOH Market. The vendor base splits between physical asset owners bearing concession obligations and software platform operators capturing margin from automation layers. Three archetypes dominate: urban transit concessionaires, interstate billboard consolidators, and programmatic technology enablers. Capacity expansion through LED retrofit programs and strategic partnerships for demand-side platform integration represent the dominant competitive moves.
Among North American operators, Clear Channel Outdoor and Lamar Advertising Company exemplify contrasting archetypes within the physical asset tier. Clear Channel Outdoor occupies a position emphasizing urban transit density through metropolitan concession holdings. Lamar Advertising Company anchors the interstate corridor strategy with billboard network concentration. OUTFRONT Media sits within the transit-specialist vector, leveraging rail and subway assets in dense coastal markets.
| Leading Market Players |
|---|
| JCDecaux North America |
| Clear Channel Outdoor |
| Lamar Advertising Company |
| OUTFRONT Media |
| PATTISON Outdoor Advertising |
| Daktronics |
| Intersection |
| GSTV |
| Broadsign International |
| Others |
Pricing and Supply Chain Analysis
Programmatic trading specialists in the New York-Toronto corridor command compensation premiums that widen rate-card spreads between automated and manual inventory tiers. Labor-cost differentials between data-science talent pools and legacy sales operations translate directly into pricing-tier stratification across deployment models.
Pricing Analysis
Impression-level attribution anchors value-based pricing for automotive and quick-service restaurant brands optimizing creative rotation by hour and weather condition. Three-tier pricing structure across premium programmatic, standard digital, and economy static levels separates rate cards by automation depth and data integration. Cost compression in static inventory is intensifying because advertisers migrate spend toward measurable digital formats. Retailers exhibit highest price sensitivity due to thin margins on promotional campaigns, while automotive brands accept premium rates for proximity-targeted dealer-zone placements.
Supply Chain Analysis
Direct-to-operator channels handle hyperscale display procurement for Clear Channel Outdoor and Lamar Advertising Company, bypassing distributor markups on LED module volumes. Component sourcing clusters in China, South Korea, and Taiwan for driver architectures and cabinet systems. Display hardware draws from concentrated East Asian manufacturing hubs, exposing operators to tariff volatility on finished assemblies. Distribution runs through specialized AV integrators for smaller regional networks lacking direct procurement scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as programmatic automation advantages force smaller static-only operators toward acquisition or exit. Margin compression from LED hardware commoditization and software platformization favors scaled players with technology infrastructure.
For Market Incumbents: Lock in transit authority concession renewals in Toronto and Chicago before bundling rights expand to new entrants. Acquire demand-side platform capabilities or API bridges to reduce technical debt in legacy asset management systems. Substitution by connected TV for commuter attention threatens rate-card premiums; defend through impression-level attribution partnerships with mobile data providers. For New Entrants and Emerging Players: Capture undersupplied digital inventory positions in Austin, Nashville, and Calgary where population growth outpaces concession deployment. Target retail media network convergence opportunities through grocery and pharmacy chain partnerships for in-store screen integration. Lead with demand-side platform integration expertise rather than physical asset ownership to minimize capital intensity. For Investors and Strategic Acquirers: Re-rating potential sits with programmatic technology enablers given FCC spectrum reorganization expanding rural network viability through private LTE backhaul. Long-term viability favors operators controlling both dense urban transit concessions and interoperable software stacks. Watch Canadian 3.5 GHz spectrum allocation progress as inflection signal for cross-border network expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Program | Converts static roadside inventory to dynamic formats eligible for programmatic rate premiums. |
| Demand-Side Platform Acquisition | Captures margin from automated buying layers as hardware ownership commoditizes. |
| Transit Authority Concession Bundling | Consolidates station assets with street furniture rights in Chicago and Toronto markets. |
| Retail Media Network Partnership | Supplies programmatic pipes for in-store screens at Walmart and Target locations. |
| Private LTE Network Deployment | Leverages FCC CBRS reorganization to extend coverage across Montana and Alberta corridors. |
Research Methodology
Document review covered FCC spectrum allocation records, municipal zoning board permit databases, and transit authority concession agreements, complemented by interviews with DOOH network operations directors, programmatic platform engineers, media buying agency leads, and LED hardware procurement specialists. Secondary validation drew from FTC advertising enforcement actions, Innovation Science and Economic Development Canada spectrum releases, and operator SEC disclosures. Bottom-up inventory counts across metropolitan markets were triangulated against top-down media spend estimates from advertising trade associations.
Historical deployment trajectories were cross-referenced against panel input from network operators and technology vendors to establish growth parameters. Segmentation modeling spanned media type, deployment model, end-user vertical, and technology architecture dimensions across the projection horizon. CAGRs were derived from fitted trend analysis incorporating LED cost decline curves, programmatic adoption S-curves, and transit concession renewal schedules. Forecast inputs included permit queue durations in Los Angeles and Vancouver, and tariff exposure assumptions on East Asian component sourcing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to municipal zoning enforcement intensity and connected TV substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Magazine Advertising Market
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
China OOH and DOOH Market