
 Solar Clamp Meter Market | 2026-2036
Solar Clamp Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Clamp Meter Market Insights
Wireless connectivity integration is fragmenting the traditional handheld instrument architecture into modular, app-enabled ecosystems. Fluke Corporation leverages its established calibration infrastructure to sustain premium positioning across certified solar test workflows. HIOKI anchors its competitive stance through specialized Rogowski coil implementations for high-current PV string diagnostics. GMC Instruments differentiates by concentrating on European grid-code compliance features embedded directly into firmware.
A solar clamp meter is a portable electrical test instrument that measures alternating and direct current without circuit interruption, typically displaying readings through a digital interface with true-RMS resolution down to 0.1 A and safety ratings to CAT IV 600 V. The device serves solar technicians who must verify string performance, detect ground faults, and validate inverter input currents during commissioning and maintenance operations. Digital clamp meters occupy the dominant revenue position due to their precision advantages in variable irradiance conditions, while wireless clamp meters represent the fastest-expanding category as distributed asset management platforms demand real-time data streaming. Hall Effect technology leads the measurement modality mix because of its DC accuracy and temperature stability, though Rogowski coil variants are gaining traction in utility-scale string monitoring where conductor sizing exceeds standard jaw capacities.
NFPA 70E workplace electrical safety standards in the United States and IEC 61010-2-032 international safety specifications collectively mandate arc-flash rated housings and fused input protection, which elevates engineering costs but also creates compliance-based pricing tiers that filter uncertified competitors. The EU AI Act and machinery directives are beginning to influence firmware validation protocols for connected instruments that log performance data to cloud-based analytics platforms. Stakeholders must monitor how evolving grid interconnection codes in target deployment regions redefine the accuracy and reporting specifications that instruments must satisfy to remain specification-compliant.
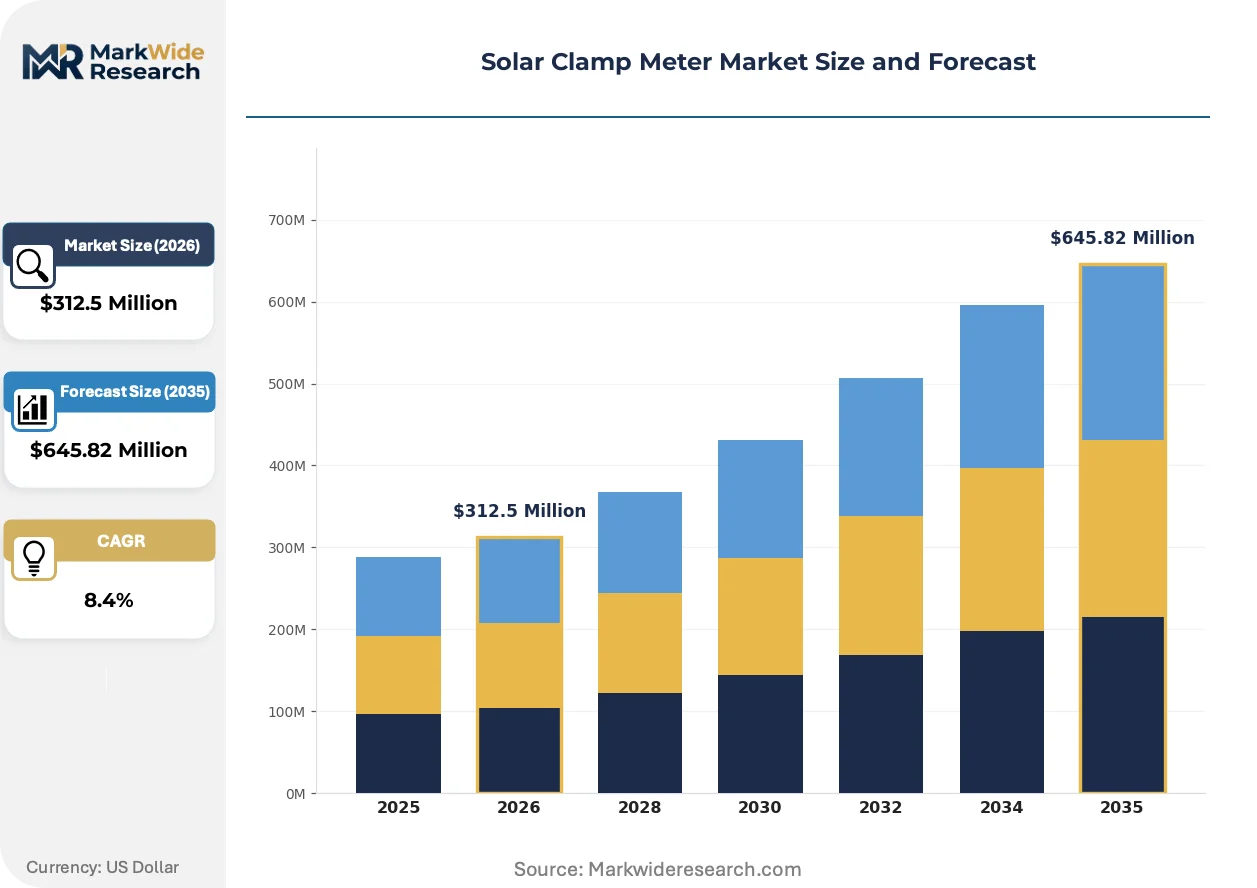
Market Dynamics
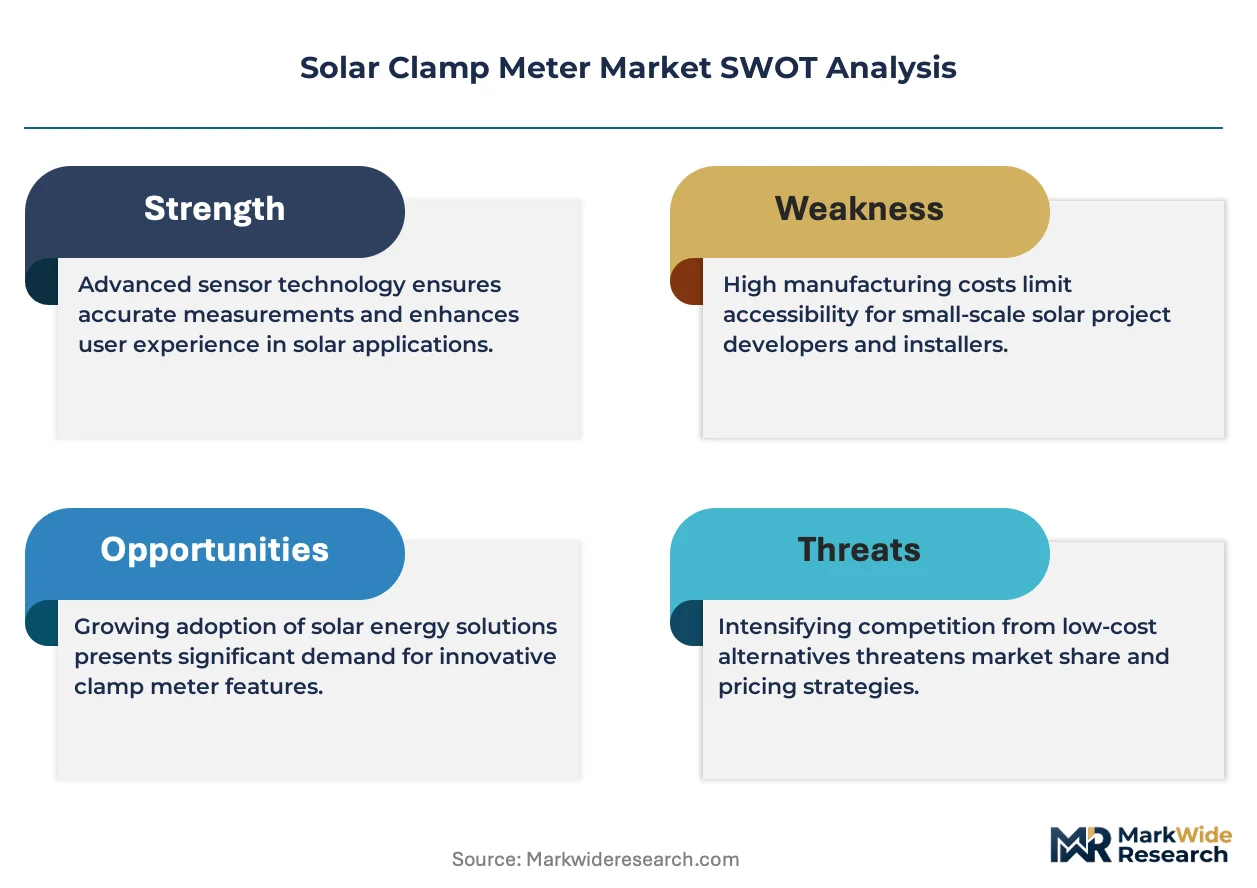
Utility-scale solar deployment is fragmenting demand between precision laboratory-grade instruments and ruggedized field units, compressing the middle tier of general-purpose clamp meters while elevating certification requirements as a primary purchasing filter.
Growth Catalysts
- China grid-scale deployment:Domestic module manufacturing and centralized solar farm construction generate concentrated procurement volumes for high-current diagnostic tools.
- IEC 61010-2-032 safety mandates:International arc-flash protection standards elevate engineering thresholds that filter uncertified competitors from specification-compliant tenders.
- Rogowski coil adoption:Flexible coil technology enables non-invasive measurement of oversized PV string conductors that exceed standard jaw capacities.
Market Restraints
- Semiconductor input volatility:Hall Effect sensor chip supply concentrates among Asian foundries, exposing manufacturers to lead-time fluctuations.
- Calibration infrastructure scarcity:Certified reference laboratories for CAT IV 600 V validation remain geographically sparse outside industrialized markets.
- Wireless protocol fragmentation:Competing IoT standards (Bluetooth, LoRa, proprietary mesh) force redundant firmware development that inflates R&D overhead.
Strategic Opportunities
- India distributed solar:Rooftop PV mandates under CEA regulations create demand for portable, technician-grade instruments at volume price points.
- EU AI Act compliance:Firmware validation requirements for connected instruments that log to cloud analytics platforms favor vendors with embedded cybersecurity capabilities.
- App-enabled ecosystem convergence:Modular hardware paired with diagnostic software opens recurring revenue streams through subscription-based feature unlocks.
Industry Challenges
- True-RMS certification bottlenecks:Variable irradiance testing protocols for accurate AC/DC measurement extend product qualification timelines.
- Legacy inverter integration:Field retrofit of wireless-enabled clamp meters with existing SCADA architectures demands custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Clamp Meter Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Clamp Meters, Analog Clamp Meters, Wireless Clamp Meters, Multimeter Clamp Meters Technology: Hall Effect, Transformer, Rogowski Coil, Optical End User: Electricians, Engineers, Technicians, Solar Installers Application: Solar Power Monitoring, Residential Installations, Commercial Applications, Maintenance Services |
| Companies Covered | Fluke Corporation, HIOKI, GMC Instruments, HT Instruments, Seaward Electronic, Megger, BENNING, HellermannTyton, Metrel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Clamp Meter Market Trends and Innovations
Measurement instrumentation is pivoting from isolated hardware sales toward integrated data services, with connectivity modules and firmware analytics redefining how technicians interact with diagnostic equipment during commissioning workflows.
Rogowski coil technology is digitizing high-current PV string monitoring by replacing rigid magnetic cores with flexible air-core sensors that accommodate irregular conductor geometries. Utility-scale solar farms in the United States and China are standardizing on these variants for string-level diagnostics where conductor sizing exceeds 1000 A. The shift is digitizing maintenance workflows by enabling continuous data logging that feeds predictive analytics platforms.
The EU AI Act is mandating algorithmic transparency for connected instruments that autonomously flag ground fault anomalies. Manufacturers must now document firmware decision trees and maintain audit trails for cloud-transmitted measurement data. European grid operators are responding by embedding compliance verification into procurement specifications, favoring vendors with pre-validated documentation packages.
Service unbundling is compressing traditional distribution channels as solar EPC firms bypass distributors to source instruments directly from manufacturers with embedded calibration certificates. Procurement teams at large installers now specify multi-year calibration service contracts as mandatory bid components. This pattern is most visible in Germany and Australia where asset management platforms demand traceable measurement chains for warranty validation.
Solar Clamp Meter Market Segmentation
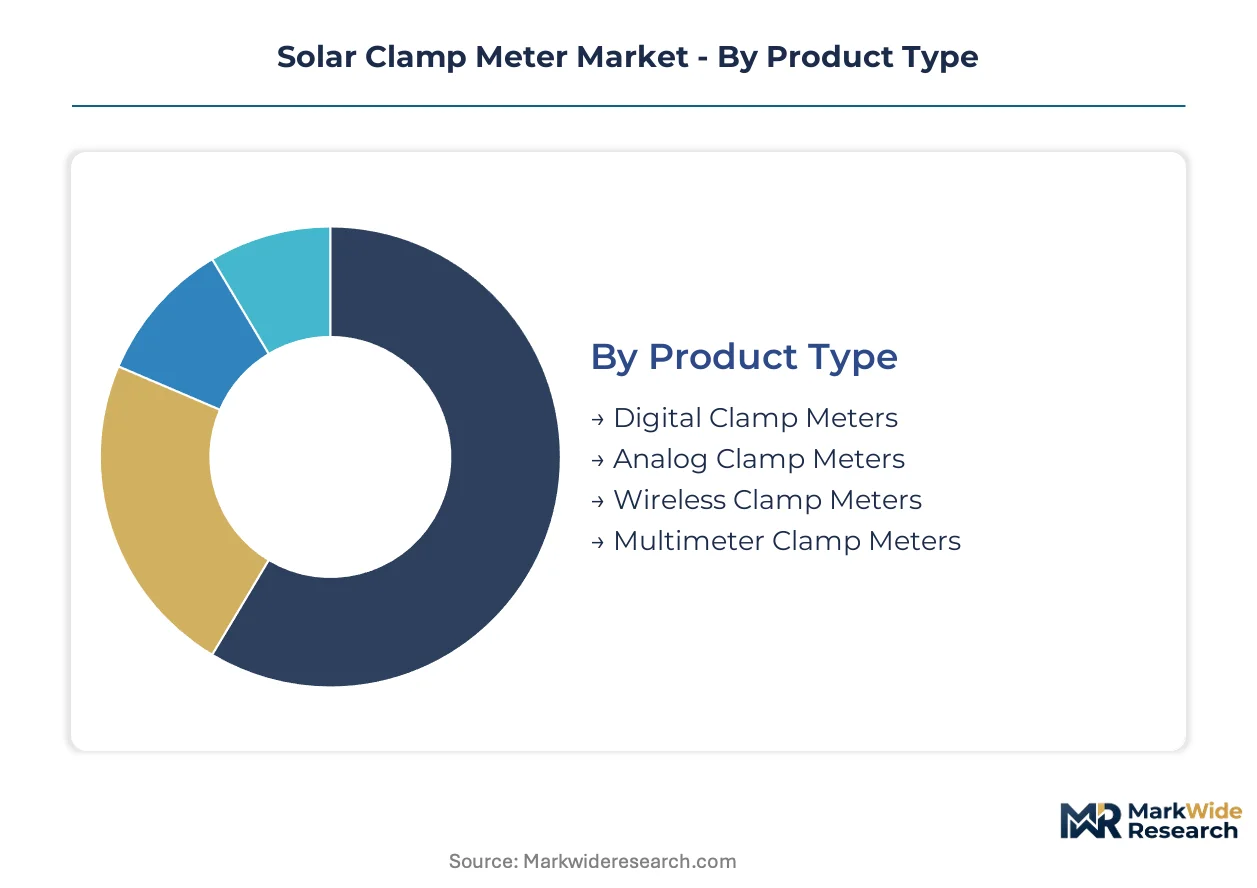
Segmentation in the solar clamp meter market reflects divergent technical requirements across installation scales and measurement modalities. Procurement patterns split sharply between precision instruments for utility commissioning and ruggedized units for distributed rooftop maintenance.
Product Type:
Cost tier differentiation separates laboratory-grade precision instruments from field-deployable units, with connectivity features commanding premium positioning.
- Digital Clamp Meters:These instruments employ true-RMS conversion circuits with 0.1 A resolution and CAT IV 600 V safety ratings, dominating procurement for variable irradiance conditions where waveform fidelity matters. Utility-scale solar farms in China specify these for string-level commissioning where accuracy thresholds filter uncertified alternatives.
- Wireless Clamp Meters:Bluetooth and LoRa-enabled modules stream real-time current data to distributed asset management platforms, expanding most quickly as solar EPC firms adopt predictive maintenance architectures. Firmware subscription models are emerging around these hardware platforms in Germany and Australia.
- Analog Clamp Meters:Electromechanical needle displays persist in price-sensitive technician toolkits across India rooftop markets.
- Multimeter Clamp Meters:Hybrid units combining clamp current measurement with voltage and resistance testing consolidate technician carry loads.
Digital clamp meters hold installed capacity. Wireless variants are rotating up the share rankings.
Technology:
Measurement modality selection tracks conductor geometry constraints and DC accuracy requirements across PV system architectures.
- Hall Effect:Semiconductor-based magnetic field sensing delivers temperature-stable DC measurement with ±1% accuracy, anchoring procurement for inverter input validation where thermal drift would corrupt string performance diagnostics. Hall Effect sensor chip supply concentrates among Asian foundries, exposing manufacturers to lead-time volatility.
- Rogowski Coil:Flexible air-core sensors accommodate irregular conductor geometries exceeding 1000 A in utility-scale string monitoring, gaining traction where rigid jaw capacities fail. United States and Chinese solar farms are standardizing on these variants for oversized conductor diagnostics.
- Transformer:Inductive coupling through iron-core toroids serves AC-only residential applications at lower cost points.
- Optical:Fiber-isolated measurement pathways address extreme electromagnetic interference environments in high-voltage DC collection systems.
Hall Effect dominates current installed capacity. Rogowski coil implementations are rotating up the share rankings.
End User:
Customer type determines feature prioritization, with certification requirements and connectivity needs diverging across professional categories.
- Solar Installers:Field technicians require ruggedized housings with arc-flash ratings and integrated data logging for warranty documentation, driving volume procurement under CEA rooftop mandates in India. These users specify multi-year calibration service contracts as mandatory bid components.
- Engineers:Commissioning specialists demand laboratory-grade precision with documented uncertainty budgets and traceable calibration chains, commanding premium pricing tiers in German and Australian asset management markets.
- Electricians:Generalist contractors prioritize portability and multi-function capability for mixed electrical maintenance workflows.
- Technicians:O&M service providers balance cost constraints against durability requirements for repetitive field deployment.
Solar installers hold installed capacity. Engineers are rotating up the share rankings.
Application:
Volume concentration varies sharply across installation scales, with centralized procurement patterns diverging from fragmented distributed demand.
- Solar Power Monitoring:Continuous string-level current measurement feeds SCADA architectures and predictive analytics platforms, requiring persistent connectivity and cloud integration. EU AI Act algorithmic transparency mandates are reshaping firmware validation for these connected instruments.
- Maintenance Services:Periodic diagnostic workflows prioritize portability and rapid deployment across dispersed asset portfolios, with service unbundling compressing traditional distribution channels as EPC firms source directly from manufacturers.
- Residential Installations:Single-phase rooftop commissioning drives demand for compact, technician-grade units at volume price points.
- Commercial Applications:Three-phase commercial PV systems require higher current ratings and phase balance measurement capabilities.
Solar power monitoring holds installed capacity. Maintenance services are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in solar clamp meters track module manufacturing clusters and utility-scale deployment waves. China exports instruments alongside PV hardware while Germany and the United States import precision units for commissioning workflows. Calibration infrastructure scarcity outside industrialized markets reinforces this pattern.
China
Domestic module production and centralized solar farm construction generate concentrated procurement volumes for high-current diagnostic tools. GB standards and MIIT certification requirements filter uncertified competitors from state-backed tenders. Yangtze River Delta manufacturing clusters supply Hall Effect sensor assemblies to instrument fabricators serving both domestic and export markets.
Germany
Asset management platforms and warranty validation protocols drive demand for traceable calibration chains and laboratory-grade precision. EU AI Act algorithmic transparency mandates reshape firmware validation for connected instruments logging to cloud analytics. Bavaria-based EPC firms specify multi-year calibration service contracts as mandatory bid components.
United States
Utility-scale string monitoring and NFPA 70E arc-flash compliance elevate certification requirements as primary purchasing filters. OSHA workplace electrical safety standards mandate arc-flash rated housings and fused input protection. Southwest solar farm clusters in Arizona and California standardize on Rogowski coil variants for oversized conductor diagnostics exceeding 1000 A.
India
CEA rooftop mandates under distributed solar regulations create demand for portable, technician-grade instruments at volume price points. BIS certification requirements and PLI scheme incentives shape domestic manufacturing investments. Gujarat and Karnataka solar parks concentrate procurement for string-level commissioning where accuracy thresholds matter.
Australia
Service unbundling compresses traditional distribution channels as solar EPC firms bypass distributors to source directly from manufacturers. TGA-equivalent electrical safety standards and grid interconnection codes redefine accuracy specifications for specification-compliant tenders. Queensland and New South Wales asset management platforms demand traceable measurement chains for warranty validation.
Solar Clamp Meter Market Competitive Landscape
On the supply side, the industry is consolidating around calibration infrastructure ownership and certification documentation capabilities. Tiered competitive positioning separates premium vendors with embedded firmware analytics from price-competitive field-unit specialists. Three archetypes dominate: precision laboratory-grade instrument specialists, ruggedized field-unit manufacturers, and modular app-enabled ecosystem providers. Capacity expansion in Asian sensor foundries and strategic partnerships for wireless protocol standardization represent the dominant competitive moves.
Among established precision instrument specialists, Fluke Corporation, HIOKI, and GMC Instruments exemplify distinct competitive anchoring strategies. Fluke Corporation represents the calibration infrastructure archetype, leveraging established service networks to sustain premium positioning. HIOKI occupies a position within specialized measurement modality development, particularly for non-standard conductor geometries. GMC Instruments sits within the regulatory compliance tier, embedding grid-code features directly into firmware for European market access. These three companies illustrate how certification ownership, measurement technology specialization, and regulatory anticipation serve as alternative vectors for competitive differentiation in a market where specification compliance functions as the primary purchasing filter.
| Leading Market Players |
|---|
| Fluke Corporation |
| HIOKI |
| GMC Instruments |
| HT Instruments |
| Seaward Electronic |
| Megger |
| BENNING |
| HellermannTyton |
| Metrel |
| Others |
Pricing and Supply Chain Analysis
Semiconductor input volatility in Hall Effect sensor chip supply determines both pricing tier spreads and supply chain shape, compressing margins on standard-grade units while amplifying premium capture for vendors with captive calibration infrastructure and certified safety ratings.
Pricing Analysis
The current-generation wireless-enabled clamp meter to prior-generation digital handheld to legacy analog needle-display pricing gap spans roughly three performance tiers. Pricing stratifies across CAT IV 600 V certified premium units, standard true-RMS field instruments, and economy-grade technician tools, with certification grade and after-sales calibration bundling as the primary differentiation drivers. Cost compression in the economy tier is intensifying because Indian rooftop mandates concentrate volume procurement at aggressive price points. Solar installers exhibit the highest price sensitivity, while German and Australian asset management platforms prioritize traceable calibration chains over unit cost.
Supply Chain Analysis
Export-control regime restrictions on advanced semiconductor manufacturing equipment constrain Hall Effect sensor chip flows from Taiwanese and South Korean foundries to instrument assemblers. Component sourcing draws from Yangtze River Delta manufacturing clusters for sensor assemblies, Bavaria-based precision calibration laboratories for certified reference standards, and Shenzhen electronics hubs for connectivity modules. Single-source vulnerability concentrates in Asian Hall Effect chip supply, exposing lead-time volatility. Distribution runs through direct manufacturer relationships with solar EPC firms, bypassing traditional industrial instrument distributors in Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated solar EPC firms and utility-scale asset operators, fragmenting procurement across fewer large-volume accounts that mandate multi-year calibration service contracts as mandatory bid components.
For Market Incumbents: Insulate premium positioning by deepening captive calibration infrastructure ownership and accelerating firmware analytics development ahead of EU AI Act algorithmic transparency mandates. The threat of modular app-enabled ecosystem providers displacing hardware-centric revenue models demands embedded cybersecurity capabilities and subscription-based feature unlocks as defensive levers. For New Entrants and Emerging Players: Pursue white-space opportunities in India's distributed rooftop segment under CEA regulations, where technician-grade portable instruments at volume price points remain underpenetrated by established premium vendors. Target wireless protocol standardization partnerships with solar EPC firms seeking predictive maintenance platform integration, using direct manufacturer relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a certification-documentation consolidation phase that favors precision laboratory-grade instrument specialists with established calibration networks and pre-validated regulatory compliance packages. Long-term viability over the next decade hinges on firmware analytics capabilities and cloud-integration infrastructure. Watch for inflection signals in EU AI Act enforcement intensity and wireless protocol convergence patterns among distributed asset management platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | CAT IV 600 V certified reference laboratories in Germany and Australia capture premium positioning through traceable measurement chains. |
| Firmware Analytics Development | EU AI Act algorithmic transparency mandates favor vendors with pre-validated decision-tree documentation and audit-trail capabilities. |
| Wireless Protocol Standardization | Bluetooth and LoRa module convergence reduces redundant R&D overhead and enables subscription-based recurring revenue streams. |
| Rogowski Coil Manufacturing Scale-Up | Flexible air-core sensor production addresses utility-scale string monitoring demand in Arizona and California solar farm clusters. |
| Direct EPC Relationship Building | Service unbundling in Germany and Australia compresses traditional distribution channels and secures multi-year calibration contract visibility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with solar EPC procurement directors, utility asset management officers, and calibration laboratory technical leads; and secondary validation against IEC 61010 certification databases, CEA rooftop mandate implementation records, and Hall Effect sensor trade flow customs data. Bottom-up instrumentation demand modeling triangulated with top-down solar deployment capacity forecasts across the analysis window.
Forecast inputs considered product type segmentation across digital, wireless, analog, and multimeter clamp meter categories; technology modality splits between Hall Effect and Rogowski coil implementations; and end-user differentiation among solar installers, commissioning engineers, and generalist electricians. CAGRs derived from installation volume trajectories, safety standard adoption curves, and connectivity module penetration rates. Variable irradiance testing protocol complexity and semiconductor lead-time volatility served as industry-specific adjustment factors.
Macroeconomic conditions sit as an overlay; deviation in solar module pricing cycles, grid interconnection code revision timing, or Asian foundry capacity utilization would shift the trajectory. Material shifts in IEC 61010-2-032 enforcement intensity or EU AI Act firmware validation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Shock Testing System Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Global Source Measure Unit Market