
 3D Printed Nanocellulose Market | 2026-2036
3D Printed Nanocellulose Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Nanocellulose Market Analytics
Finland is tilting toward nanocellulose commercialization through UPM Biomedicals' sustained pulp-to-biomaterials pipeline. CelluForce leverages Quebec's forestry base to anchor North American nanocellulose supply. CELLINK dominates bioprinting hardware while competing against Sappi's expanding specialty cellulose portfolio.
3D printed nanocellulose denotes additive-manufactured constructs from cellulose nanofibrils or nanocrystals, typically 5-20 nanometers in width and several micrometers in length, processed through aqueous extrusion or photopolymerizable resin systems to yield biocompatible, high-strength-to-weight structures for load-bearing and biological applications. Hydrogels occupy the largest application share as tissue engineering scaffolds, while composites capture expanding margin pools in automotive lightweighting. Fused Deposition Modeling leads technology adoption due to aqueous feedstock compatibility, though Stereolithography advances in microscale biomedical precision.
FDA governs implantable nanocellulose devices through 510(k) and PMA pathways, while EMA's MDR framework mandates biocompatibility documentation for long-term implant materials. ISO 10993 standards shape preclinical testing protocols across both jurisdictions. REACH registration requirements in Europe constrain novel nanomaterial market entry timelines. Stakeholders must monitor regulatory divergence between FDA's risk-based device classification and EMA's stricter substance-level scrutiny as they allocate R&D budgets across geographic markets.
Market Dynamics
EU MDR's tightened biocompatibility documentation requirements are forcing implantable device manufacturers to requalify nanocellulose supply chains, compressing time-to-market windows and privileging pre-certified material sources over novel entrants.
Growth Catalysts
- FDA 510(k) pathway clarity:The FDA's risk-based device classification provides predictable regulatory routes for nanocellulose scaffolds, accelerating orthopedic and wound-care submissions from US-based bioprinting firms.
- Tissue engineering demand:Hydrogel scaffold applications in regenerative medicine are pulling nanocellulose volumes as hospitals seek load-bearing, bioresorbable alternatives to synthetic polymer implants.
- Fraunhofer institute network:Germany's applied research infrastructure bridges pilot-scale nanocellulose production to industrial qualification, reducing technology transfer friction for European medical device partners.
Market Restraints
- Cellulose feedstock concentration:Nordic and Canadian pulp suppliers control high-purity dissolving-grade cellulose inputs, creating geographic supply vulnerability for extrusion-grade nanofibril production.
- REACH registration timelines:ECHA's novel nanomaterial data requirements impose multi-year pre-market dossier preparation, delaying European commercialization against faster US regulatory paths.
- Stereolithography resin cost:Photopolymerizable nanocellulose formulations require specialized acrylate functionalization, elevating per-kilogram material costs above aqueous extrusion alternatives.
Strategic Opportunities
- Automotive lightweighting:Nanocellulose-reinforced composites for interior structural panels offer OEMs a bio-based route to fleet emission targets under EU Green Deal mandates.
- Microscale precision demand:Stereolithography convergence with nanocellulose hydrogels enables vascularized tissue constructs, opening preclinical pharmaceutical testing contracts.
- India PLI scheme:Production-linked incentives for medical device manufacturing create tariff-advantaged assembly capacity for export-oriented nanocellulose implant producers.
Industry Challenges
- ISO 10993-5 cytotoxicity testing backlog:Contract research organizations face capacity constraints for nanocellulose-specific biocompatibility validation, extending preclinical timelines.
- Cross-platform file format standardization:Bioprinting hardware vendors use proprietary G-code dialects, complicating scaffold design portability between FDM and SLA production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Nanocellulose Market |
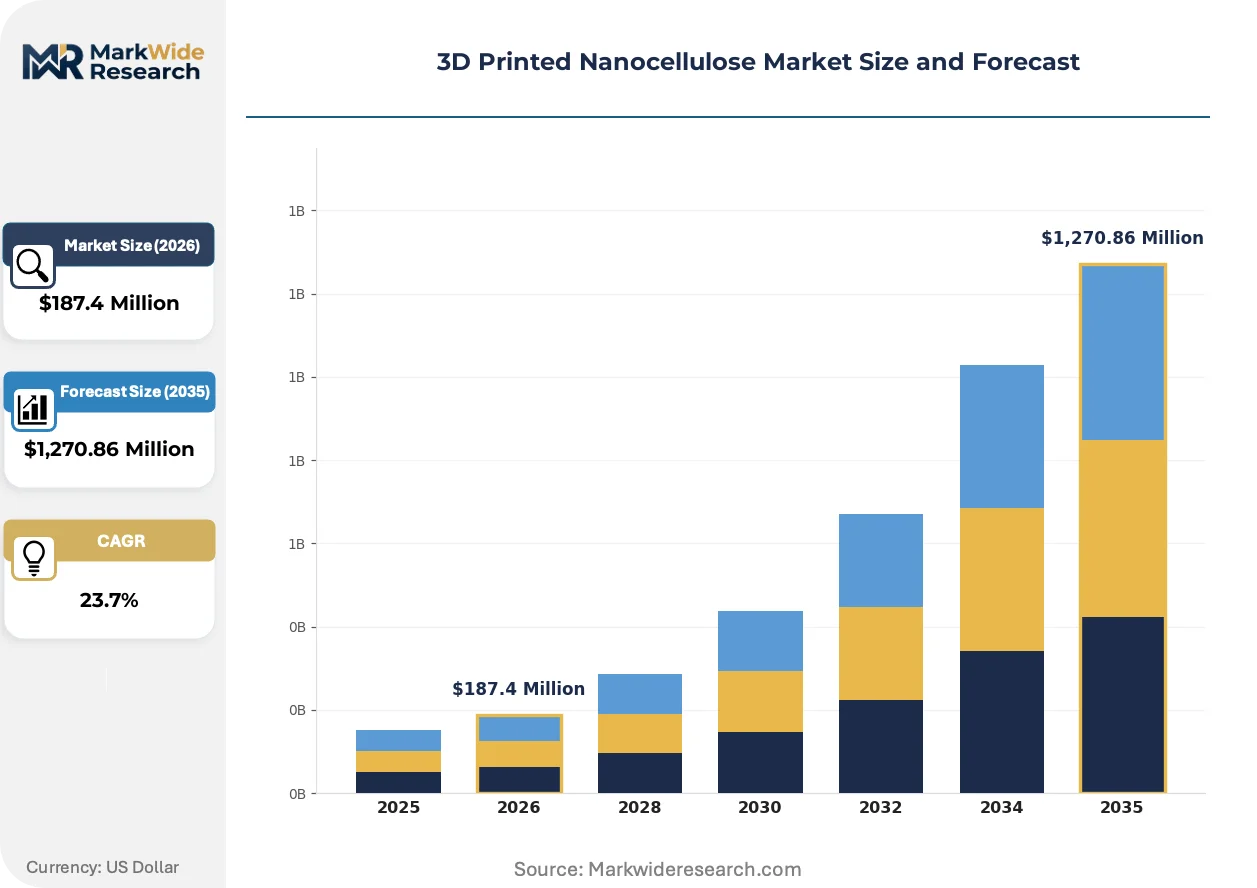
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogels, Composites, Films, Coatings End Use Industry: Automotive, Aerospace, Packaging, Biomedical Application: Structural Supports, Drug Delivery, Tissue Engineering, Filtration Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Others |
| Companies Covered | CELLINK (BICO Group AB), UPM Biomedicals, CelluForce, Sappi, Oji Holdings Corporation, Nippon Paper Industries, American Process Inc., Axcelon Biopolymers Corporation, Nanografi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Nanocellulose Market Evolving Landscape
Aqueous extrusion systems are compressing the cost-performance gap with petroleum-based additive manufacturing, while regulatory frameworks on both sides of the Atlantic diverge in their nanomaterial scrutiny intensity.
Photopolymerizable nanocellulose resin formulations are collapsing the resolution limitations that previously constrained hydrogel scaffolds to millimeter-scale features. Academic medical centers in Boston and Rotterdam are adopting these systems for patient-specific orthopedic implants. The technology is collapsing lead times for vascularized tissue constructs from months to weeks.
EMA's MDR Annex I general safety and performance requirements now mandate traceability documentation for all implantable nanomaterials back to forest source. German notified bodies are interpreting this as requiring chain-of-custody certification from pulp mill through fibrillation. Small-scale nanocellulose producers without integrated forestry operations are exiting the implantable device supply base.
Hospital procurement departments are consolidating bioprinted scaffold suppliers around pre-qualified material platforms, displacing project-by-project custom formulation contracts. Academic medical center purchasing consortiums in the US and Netherlands are driving this consolidation. The shift is most visible in craniomaxillofacial reconstruction, where standardized nanocellulose mesh products are capturing volume from patient-specific titanium alternatives.
3D Printed Nanocellulose Market Segmentation
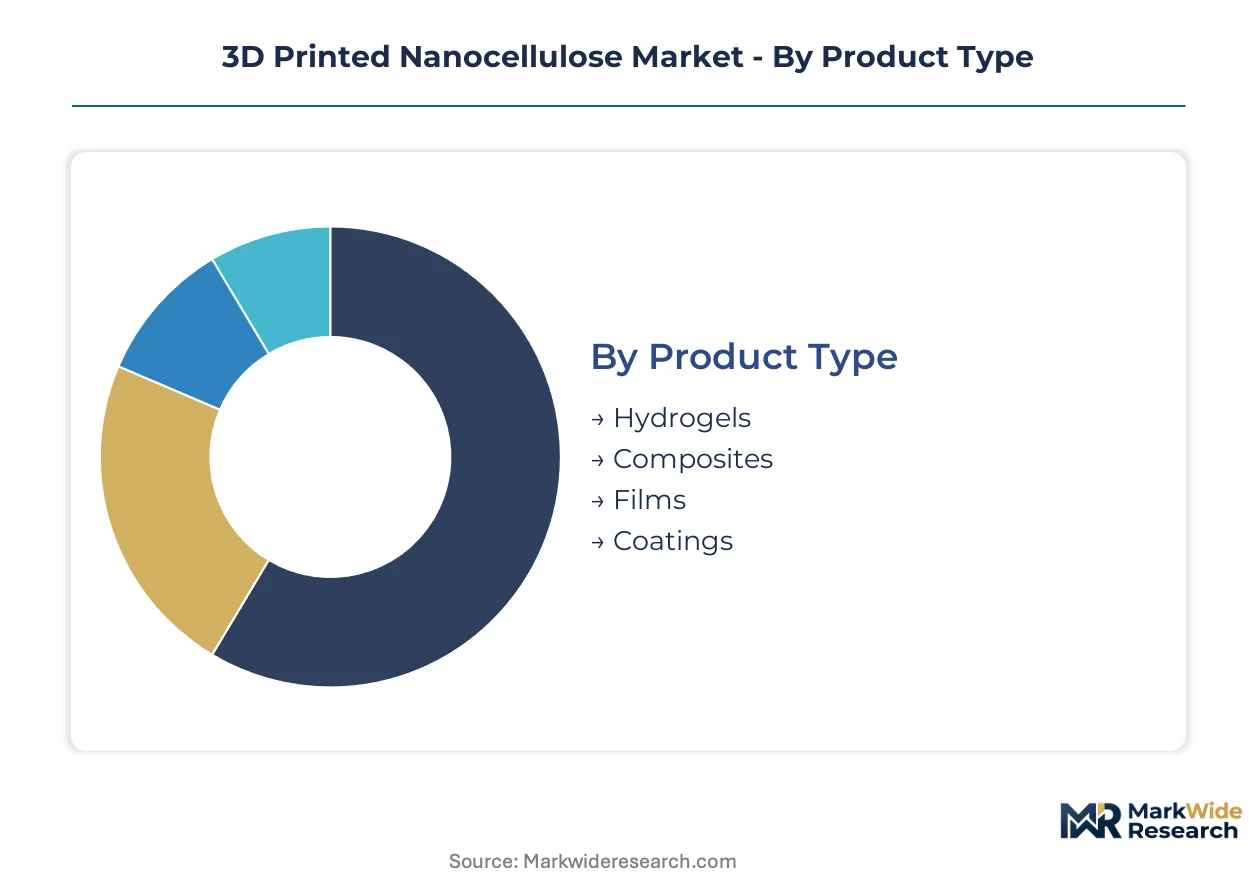
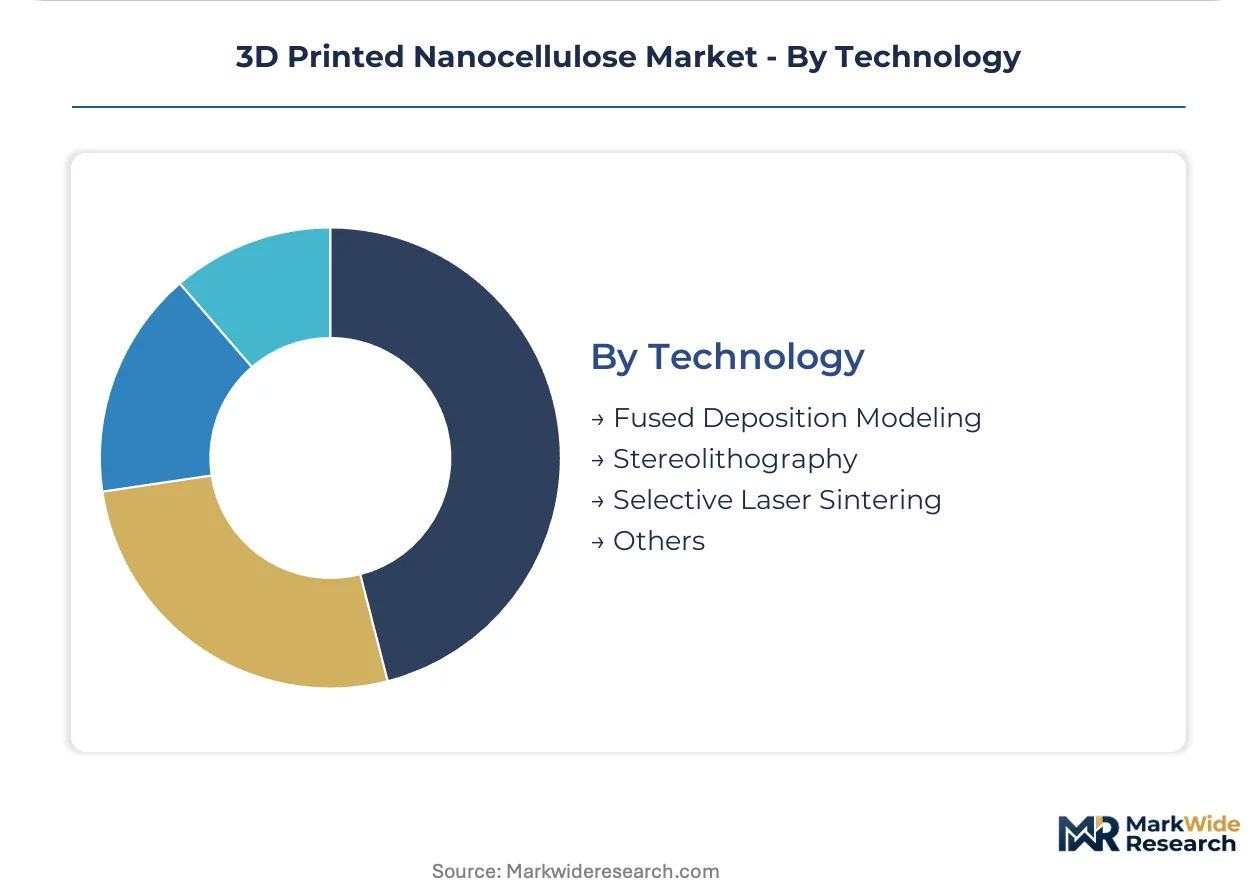
Segmentation in 3D printed nanocellulose reveals how material form, manufacturing process, and end-use requirements create distinct competitive arenas. Each dimension carries different margin profiles, regulatory burdens, and technology maturity levels that shape supplier positioning.
Product Type:
Mature formats dominate current revenue while emerging variants capture R&D investment and pilot contracts.
- Hydrogels:Aqueous nanocellulose networks with tunable porosity and mechanical compliance. Tissue engineering scaffolds in German university hospitals and Dutch regenerative medicine centers drive qualification volumes. FDA 510(k) submissions for wound-care applications are accelerating commercial adoption.
- Composites:Nanocellulose-reinforced matrices with thermoplastic or thermoset binders. Automotive interior panels for EU Green Deal emission compliance concentrate demand in Stuttgart and Wolfsburg manufacturing corridors. Material cost parity with glass fiber remains the critical adoption threshold.
- Films:Thin, flexible barriers with high oxygen resistance for food packaging applications.
- Coatings:Surface-functionalized layers for moisture management and antimicrobial protection on medical devices.
Hydrogels handle the majority of throughput; composites are expanding most quickly on share.
End Use Industry:
Customer sophistication varies sharply, with biomedical buyers demanding full ISO 10993 documentation while automotive purchasers prioritize volume pricing and lot-to-lot consistency.
- Biomedical:Implantable scaffolds, wound dressings, and drug delivery platforms requiring full biocompatibility validation. Rotterdam academic medical centers and Boston hospital networks are standardizing nanocellulose mesh products for craniomaxillofacial reconstruction, displacing titanium alternatives.
- Automotive:Lightweight interior structural components and trim panels. OEMs in Germany face binding EU fleet emission targets that bio-based materials help satisfy. Supply agreements now specify chain-of-custody documentation from Nordic pulp sources.
- Aerospace:Cabin interior panels and non-structural components where flammability certification drives material selection.
- Packaging:Barrier films and molded pulp replacements for single-use plastic reduction mandates.
Biomedical commands premium pricing per kilogram; automotive offers the steepest expansion trajectory through 2035.
Application:
Functional requirements determine whether extrusion-based or photopolymerizable processing delivers viable economics.
- Tissue Engineering:Load-bearing scaffolds with vascular channel architectures for organ regeneration. Stereolithography systems in Rotterdam and Boston medical centers are collapsing lead times for patient-specific constructs from months to weeks.
- Structural Supports:Load-bearing lattices and reinforcement elements. Automotive seating frames and interior panels in Germany specify nanocellulose composites for weight reduction without sacrificing crash performance.
- Drug Delivery:Controlled-release matrices with tunable degradation profiles for localized therapeutic delivery.
- Filtration:High-flux membranes with nanoscale pore structures for water purification and bioprocessing.
Tissue engineering generates the highest value per unit volume; structural supports are climbing the fastest as automotive qualification batches scale.
Technology:
Process selection locks in resolution limits, material compatibility, and regulatory validation pathways.
- Fused Deposition Modeling:Aqueous nanocellulose extrusion through heated nozzles. The technology leads adoption due to feedstock compatibility with standard hydrogel formulations. Fraunhofer institutes in Germany have standardized FDM protocols for medical device partners.
- Stereolithography:Photopolymerizable nanocellulose resin curing with UV projection. Microscale precision enables vascularized tissue constructs for preclinical pharmaceutical testing. Acrylate functionalization elevates material costs above aqueous alternatives.
- Selective Laser Sintering:Powder-bed fusion of nanocellulose composite materials for durable end-use parts.
- Others:Emerging modalities including inkjet bioprinting and extrusion-based multi-material systems.
Fused Deposition Modeling handles current production volumes; Stereolithography is gaining share fastest in biomedical precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes 3D printed nanocellulose primarily for implantable medical devices under strict MDR traceability rules, while the United States channels volumes through FDA-cleared orthopedic applications and Canada leverages forestry feedstocks for industrial composite supply.
Germany
Fraunhofer institutes in Stuttgart and Dresden drive qualification protocols for nanocellulose hydrogel scaffolds in craniomaxillofacial reconstruction. EU MDR Annex I mandates chain-of-custody documentation from Nordic pulp sources through fibrillation, compressing time-to-market for implantable device submissions. The Stuttgart manufacturing corridor anchors applied research partnerships between medical device OEMs and cellulose nanofibril producers.
United States
FDA 510(k) pathway clarity accelerates orthopedic and wound-care submissions from Boston-based bioprinting firms and academic medical centers. The agency's risk-based device classification provides predictable regulatory routes absent REACH-equivalent nanomaterial scrutiny. Hospital purchasing consortiums in Greater Boston standardize nanocellulose mesh products, displacing patient-specific titanium alternatives in reconstructive surgery.
Canada
Quebec's forestry base supplies high-purity dissolving-grade cellulose inputs for North American nanocellulose extrusion. CelluForce leverages provincial pulp infrastructure to anchor regional nanofibril production for biomedical and automotive composite applications. Montreal research clusters bridge pilot-scale fibrillation to industrial qualification under Health Canada biocompatibility guidance.
Finland
UPM Biomedicals sustains a pulp-to-biomaterials pipeline commercializing nanocellulose for tissue engineering and drug delivery platforms. The country's forest industry concentration enables integrated chain-of-custody certification demanded by EU MDR implantable device regulations. Helsinki-Tampere research corridors connect university spinouts to Nordic medical device distribution networks.
Japan
Oji Holdings and Nippon Paper Industries repurpose traditional pulp capacity toward nanocellulose feedstock for domestic bioprinting applications. PMDA biocompatibility documentation requirements for long-term implant materials shape preclinical testing protocols. Tokyo-Osaka industrial clusters concentrate precision stereolithography system development for vascularized tissue constructs.
3D Printed Nanocellulose Market Competitive Landscape
Capability concentration sits with specialized nanocellulose fibrillation and functionalization players; scale advantage sits with integrated forestry and diversified materials conglomerates. The market structures around three archetypes: pulp-integrated biomaterial suppliers, bioprinting hardware specialists, and contract nanocellulose manufacturers. Dominant competitive moves include backward integration into dissolving-grade cellulose supply and strategic partnerships bridging fibrillation expertise to medical device qualification.
Among Nordic pulp-integrated biomaterial suppliers, UPM Biomedicals and CelluForce exemplify the vertical control archetype, anchoring regional supply security through captive forestry operations. CELLINK occupies a position within the bioprinting hardware tier, representing the convergence point between extrusion system development and scaffold material standardization. These three entities collectively illustrate how geographic feedstock concentration and regulatory proximity shape competitive positioning across the European and North American markets.
| Leading Market Players |
|---|
| CELLINK (BICO Group AB) |
| UPM Biomedicals |
| CelluForce |
| Sappi |
| Oji Holdings Corporation |
| Nippon Paper Industries |
| American Process Inc. |
| Axcelon Biopolymers Corporation |
| Nanografi |
| Others |
Value Network & Pricing Analysis
Undercapacity in Nordic dissolving-grade cellulose mills is compressing supplier margins while elevating pricing power for integrated pulp-to-nanocellulose producers serving EU MDR-qualifying implantable device markets.
Pricing Analysis
Long-term offtake agreements dominate nanocellulose hydrogel procurement for craniomaxillofacial reconstruction, with three-tier pricing structure across premium, standard, and economy levels differentiating by ISO 10993-5 cytotoxicity certification tier and chain-of-custody documentation depth. Automotive composite buyers exhibit highest price sensitivity due to material cost parity thresholds with glass fiber alternatives, while biomedical purchasers absorb premium pricing for traceability-assured Nordic pulp sources. Pricing pressure stems from REACH registration cost recovery demands and acrylate functionalization premiums in stereolithography resin formulations.
Supply Chain Analysis
Extended payment terms from German medical device OEMs are straining working capital for non-integrated nanocellulose fibrillation specialists, accelerating consolidation toward pulp-integrated suppliers. Feedstock concentration in Finland, Sweden, and Quebec creates geographic vulnerability for extrusion-grade nanofibril production. Supply chains draw from high-purity dissolving-grade cellulose, photopolymerizable acrylate resins, and biocompatible crosslinking agents. Single-source vulnerability concentrates around Nordic pulp mill qualification for EU MDR chain-of-custody certification. Distribution runs through direct mill-to-device-manufacturer contracts for biomedical grades, with automotive composites channeling through Tier 1 interior panel suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as hospital procurement consortiums consolidate around pre-qualified nanocellulose scaffold platforms following pandemic-delayed orthopedic reconstruction backlogs.
For Market Incumbents: Pre-empt margin erosion by deepening upstream control over dissolving-grade cellulose supply through Nordic pulp mill partnerships or captive forestry operations, while accelerating FDA 510(k) submission pipelines to defend against emerging photopolymerizable resin specialists capturing microscale precision applications. For New Entrants and Emerging Players: Establish a beachhead in Indian medical device assembly under PLI scheme tariff advantages, targeting export-oriented nanocellulose implant production for EU markets where REACH registration timelines disadvantage European newcomers; pursue hospital purchasing consortium qualification as the primary go-to-market pathway. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pulp-integrated biomaterial suppliers with captive forestry operations and established EU MDR traceability documentation, positioning these archetypes for superior cash flow stability across the analysis window; monitor FDA 510(k) clearance velocity for nanocellulose orthopedic scaffolds as the critical inflection signal for biomedical segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving-Grade Cellulose | Secures Nordic pulp mill chain-of-custody certification required under EU MDR Annex I traceability mandates. |
| FDA 510(k) Submission Acceleration | Exploits risk-based device classification clarity to compress orthopedic scaffold approval timelines against slower EMA paths. |
| Photopolymerizable Resin Formulation Partnership | Enables vascularized tissue construct capabilities for Rotterdam and Boston academic medical center contracts. |
| Automotive Lightweighting Qualification | Captures EU Green Deal fleet emission compliance demand from Stuttgart and Wolfsburg OEM manufacturing corridors. |
| Hospital Purchasing Consortium Standardization | Displaces project-by-project custom contracts with recurring scaffold platform volumes in craniomaxillofacial reconstruction. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nanocellulose fibrillation plant managers, medical device regulatory affairs leads, hospital GPO contracts managers, automotive Tier 1 procurement directors, and bioprinting hardware platform engineers. Secondary validation drew from FDA 510(k) submission databases, EMA MDR technical documentation filings, EU customs trade data for dissolving-grade cellulose imports, and SEC 10-K disclosures from integrated forestry conglomerates. Bottom-up volume modeling across hydrogel, composite, and resin product tiers was triangulated against top-down macroeconomic drivers.
Calibration against historical qualification timelines for implantable nanocellulose devices anchored growth rate derivation across the projection horizon. Segmentation dimensions modeled include product form factor, end-use industry vertical, manufacturing technology platform, and regional regulatory cluster. Forecast inputs incorporated EU MDR Annex I implementation pace, FDA nanomaterial guidance evolution, and automotive OEM bio-based content target trajectories.
Sensitivities concentrate around REACH registration timeline extensions, Nordic pulp mill capacity utilization shocks, and hospital procurement consortium consolidation velocity. Forecasts embed assumptions regarding regulatory pathway stability and feedstock supply security. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market