
 Aerospace 3D Printing Materials Market | 2026-2036
Aerospace 3D Printing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace 3D Printing Materials Market Analysis
Aftermarket service revenue is fragmenting across OEMs, tier suppliers, and independent additive specialists. EOS GmbH dominates powder-bed fusion systems for nickel superalloy turbine hardware. Stratasys Ltd leverages fused deposition modeling for non-structural cabin components and prototyping workflows. GKN Powder Metallurgy anchors European supply of aerospace-qualified titanium and Inconel powders through captive atomization capacity.
Aerospace 3D printing materials comprise engineered feedstocks—metal alloys, thermoplastics, ceramics, and composites—processed through layer-wise consolidation to produce geometrically complex components with buy-to-fly ratios below 3:1. Metal alloys, particularly Ti-6Al-4V and Inconel 718, sustain the largest margin pools due to qualification barriers and powder recycling economics. Thermoplastics such as ULTEM 9085 represent the fastest-expanding category for cabin interior brackets and ducting where flame-smoke-toxicity compliance applies. Production parts as an application segment is displacing prototyping as the primary value driver as airframers qualify flight-critical hardware for serial manufacturing.
FAA airworthiness directives and EASA certification memoranda on additive manufacturing impose stringent powder lot traceability and mechanical testing protocols. ISO/ASTM 52900 standards framework governs terminology and process classifications, while NIST measurement science programs address in-situ process monitoring gaps. Stakeholders must decide whether to pursue vertical integration into powder production or lock in long-term supply agreements as qualified material sources consolidate.
Market Dynamics
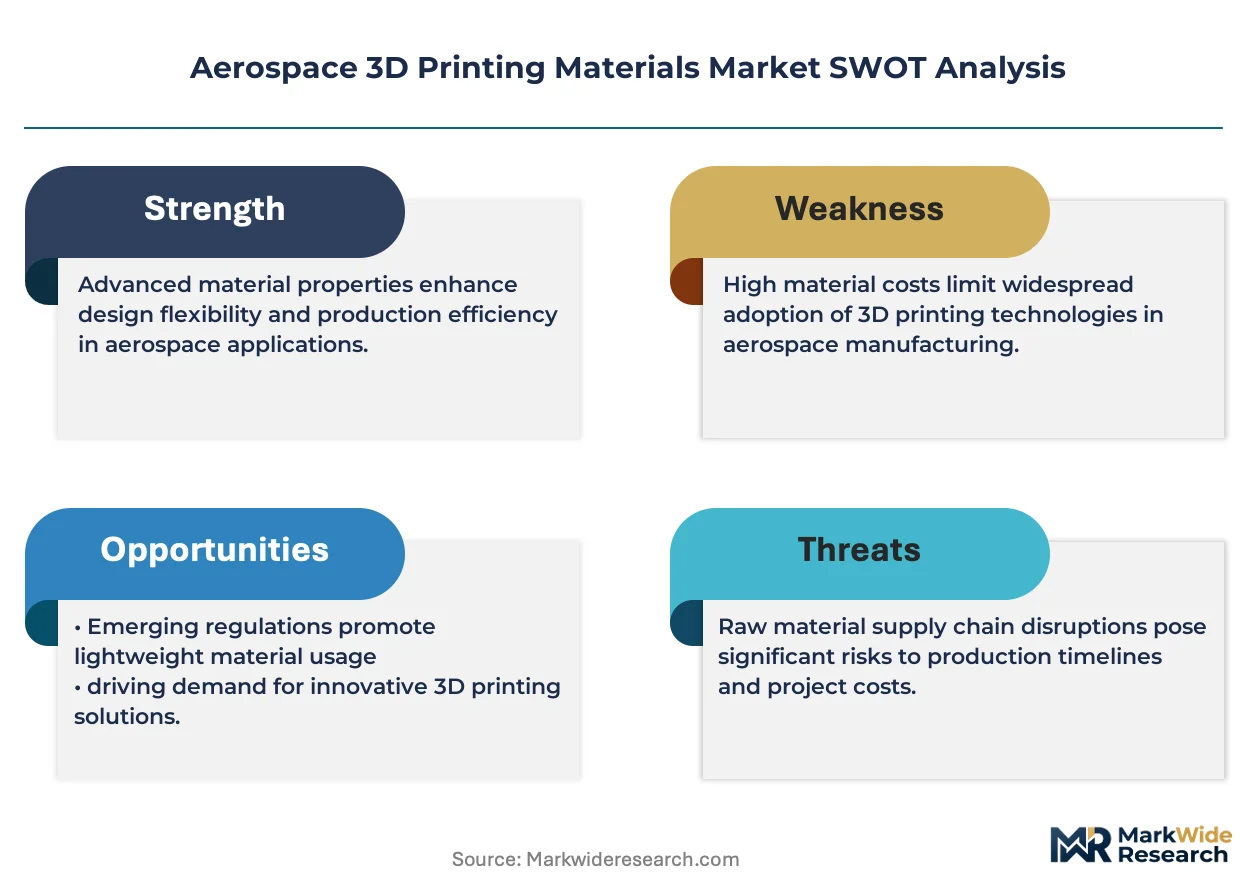
The Aerospace 3D Printing Materials Market pivots on FAA and EASA certification tightening for flight-critical components, forcing material suppliers to rebuild traceability infrastructure from atomization through final part qualification.
Growth Catalysts
- Ti-6Al-4V powder qualification:Defense contractors are accelerating adoption of titanium flight hardware under revised MIL-STD-31000B guidelines for additive manufacturing.
- ISO/ASTM 52900 harmonization:Standardized terminology across powder-bed fusion and directed energy deposition processes is reducing cross-border qualification friction for European suppliers.
- Engine bracket consolidation:GE Aviation and Pratt & Whitney are replacing multi-part assemblies with single-print Inconel 718 turbine components, compressing supply chains.
Market Restraints
- Plasma atomization cost concentration:Spherical titanium powder production remains captive to six qualified atomizers globally, with three located in Germany.
- FAA powder lot traceability:Airworthiness directives now mandate 15-year retention of atomization parameters and chemical assay records, raising working capital requirements.
- Conventional forging residual strength:Forged titanium still exceeds printed Ti-6Al-4V fatigue performance in high-cycle wing attachments, limiting substitution.
Strategic Opportunities
- India defense localization:The country's PLI scheme for aerospace components creates captive demand for indigenized nickel superalloy powder production.
- Cabin thermoplastic expansion:Flame-smoke-toxicity compliant ULTEM 9085 brackets for galley and seating systems represent unpenetrated volume in narrowbody retrofits.
- Digital twin integration:Converging in-situ process monitoring with predictive maintenance platforms enables outcome-based powder supply contracts.
Industry Challenges
- Non-destructive testing technician scarcity:Industrial CT scanning for internal defect detection requires operators certified to ASTM E1441, with fewer than 200 qualified globally.
- Multi-material deposition integration:Combining Ti-6Al-4V with copper alloys in single builds for thermal management hardware remains pre-production due to intermetallic formation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace 3D Printing Materials Market |
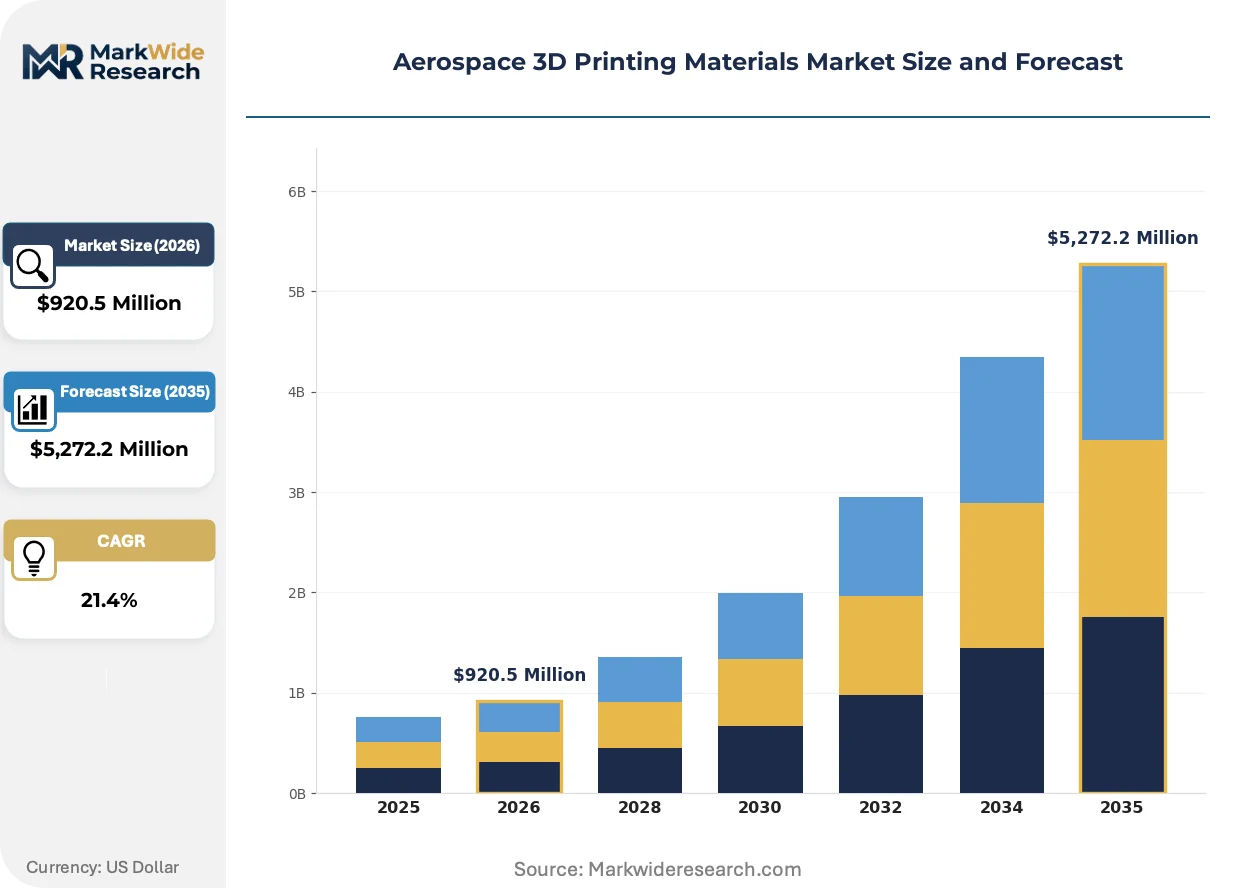
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $5,272.2 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal Alloys, Thermoplastics, Ceramics, Composites Application: Prototyping, Tooling, Production Parts, Spare Components Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Binder Jetting End User: Aircraft Manufacturers, Defense Contractors, Space Agencies, Maintenance Providers |
| Companies Covered | Stratasys Ltd, 3D Systems Corporation, EOS GmbH, Höganäs AB, ExOne, ATI, GKN Powder Metallurgy, CNPC Powder, Arkema Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace 3D Printing Materials Market Emerging Trajectories
Process-parameter digitalization is compressing qualification timelines while regulatory bodies race to codify in-situ monitoring as acceptable evidence of part conformity.
Electron beam powder-bed fusion is collapsing the buy-to-fly ratio for titanium structural brackets from conventional 15:1 machining to below 3:1. SpaceX and Blue Origin are qualifying EBM Ti-6Al-4V for rocket engine manifolds at production rates exceeding 500 parts annually. This compression is eliminating subtractive machining capacity planning from new facility designs.
EASA certification memoranda on additive manufacturing now require statistical validation of powder reuse ratios, forcing suppliers to install closed-loop sieving and contamination detection. The regulation is driving consolidation among European powder producers unable to fund validation campaigns. German aerospace clusters around Munich are absorbing smaller atomization facilities into captive supply chains.
Airframers are unbundling powder procurement from machine OEM service contracts, directly contracting qualified atomizers for long-term supply agreements. Boeing and Airbus procurement teams now specify chemistry, morphology, and flowability independently of printer manufacturer recommendations. This disintermediation is most visible in North American narrowbody programs, where material costs now represent 40% of printed part landed cost versus 25% under bundled arrangements.
Aerospace 3D Printing Materials Market Segmentation
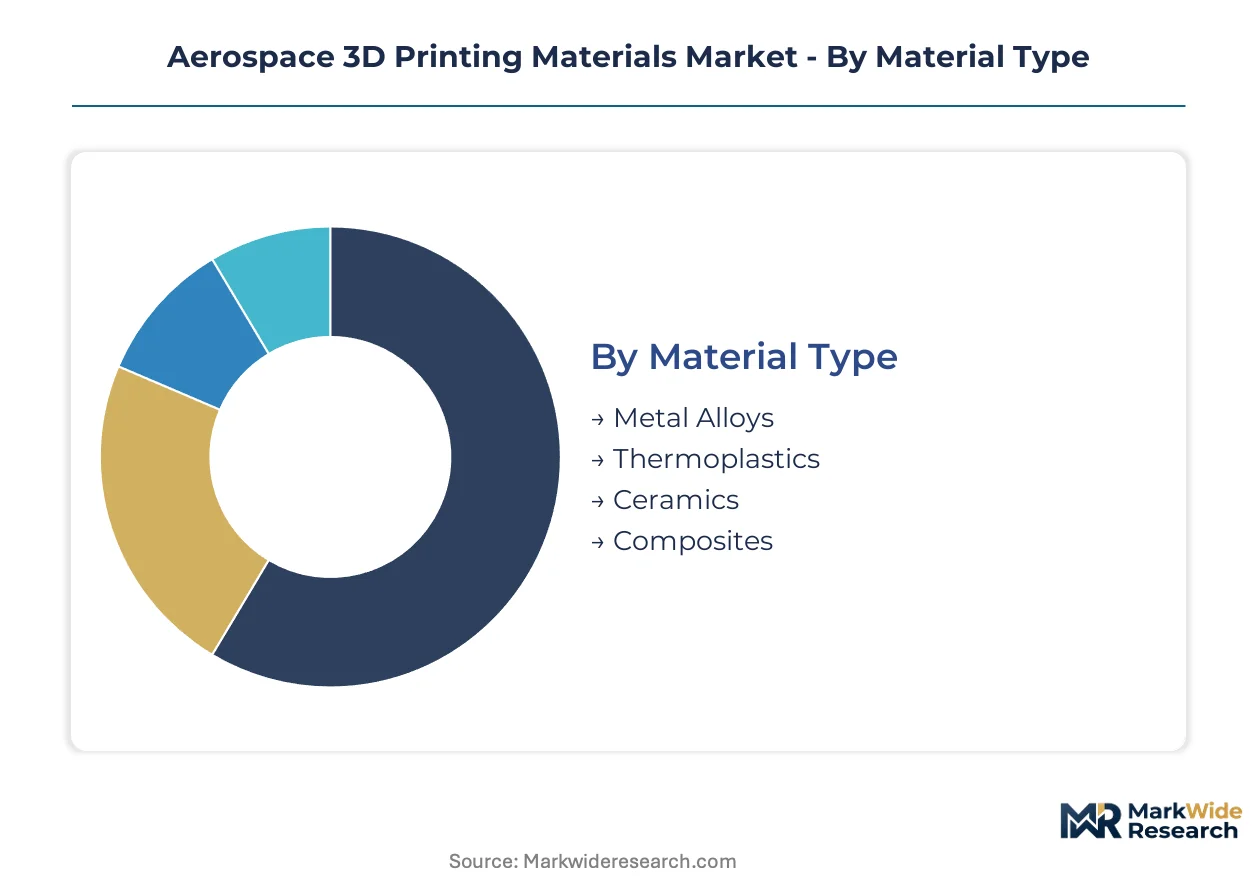
Material qualification barriers and certification pathways fragment the Aerospace 3D Printing Materials Market into discrete supply tiers. Each segment carries distinct atomization economics, traceability burdens, and end-user procurement protocols that reshape competitive positioning.
Material Type:
Cost tier stratification separates qualified aerospace feedstocks from industrial-grade alternatives, with powder recycling economics determining margin sustainability.
- Metal Alloys:Ti-6Al-4V and Inconel 718 dominate flight-critical hardware through plasma atomization spherical morphology requirements. Defense contractors in Germany and the United States are consolidating long-term supply agreements for nickel superalloy powders as FAA traceability mandates tighten.
- Thermoplastics:ULTEM 9085 and PEEK formulations serve cabin interior brackets where flame-smoke-toxicity compliance applies. Narrowbody retrofit programs across France and the United States are expanding filament consumption for galley and seating systems.
- Ceramics:Oxide and non-oxide ceramics enable thermal barrier coatings for turbine vanes.
- Composites:Continuous fiber-reinforced thermoplastics address structural brackets requiring anisotropic strength.
Metal Alloys holds installed capacity. Thermoplastics is rotating up the share rankings.
Application:
Volume concentration shifts from prototype workflows toward serial production as airframers qualify flight hardware for manufacturing.
- Prototyping:Non-structural mockups and fit-check components consume engineering-grade thermoplastics through fused deposition modeling. Boeing and Airbus design centers in Washington and Toulouse maintain captive prototyping cells for iterative development cycles.
- Production Parts:Flight-critical brackets, manifolds, and turbine hardware now qualify under FAA airworthiness directives. SpaceX and Blue Origin are qualifying EBM Ti-6Al-4V rocket engine components at annual rates exceeding 500 parts.
- Tooling:Drill guides and assembly fixtures leverage polymer composites for temporary use.
- Spare Components:On-demand manufacturing for legacy fleet support reduces inventory carrying costs.
Production Parts commands qualification investment. Spare Components is climbing the fastest as fleet age extends.
Technology:
Customer type differentiation separates powder-bed fusion systems for metals from extrusion platforms for polymers and resin systems for precision tooling.
- Selective Laser Sintering:Powder-bed fusion using CO2 or fiber lasers consolidates nylon and metal powders with layer thicknesses below 50 microns. EOS GmbH systems anchor European production capacity for aerospace-grade nickel superalloy turbine hardware.
- Fused Deposition Modeling:Thermoplastic filament extrusion builds non-structural cabin components through Stratasys Ltd platforms. Flame-retardant ULTEM grades dominate galley bracket applications where FAA burn certification applies.
- Stereolithography:UV-cured resins produce high-precision tooling masters and investment casting patterns.
- Binder Jetting:Liquid binding agents consolidate metal and sand powders for core and mold fabrication.
Selective Laser Sintering holds installed capacity. Binder Jetting is rotating up the share rankings as green part sintering advances.
End User:
Margin structure varies by procurement sophistication, with defense contractors absorbing qualification costs and maintenance providers demanding outcome-based powder supply.
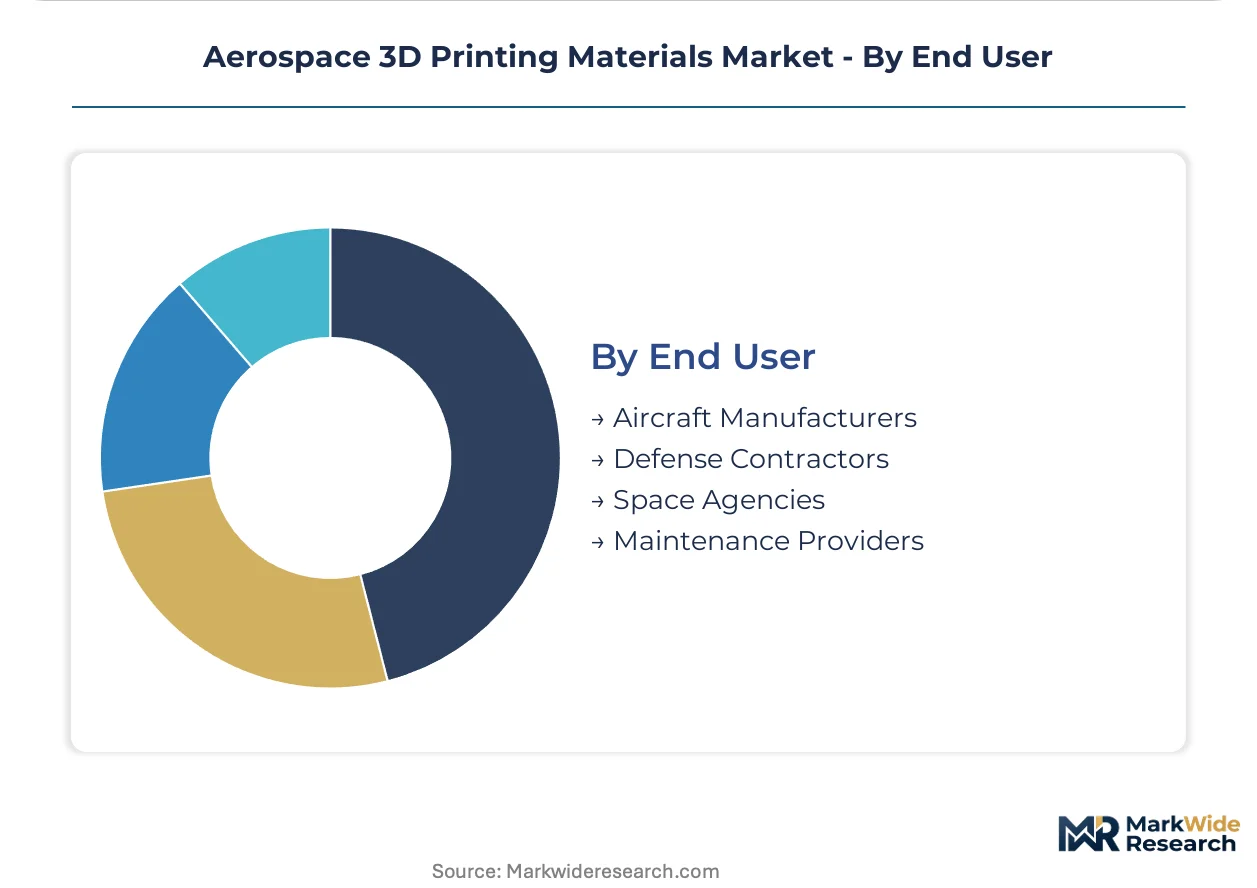
- Defense Contractors:Flight-critical titanium hardware under MIL-STD-31000B guidelines drives Ti-6Al-4V powder qualification. Lockheed Martin and Northrop Grumman are expanding adoption of additively manufactured structural brackets for fighter airframes.
- Aircraft Manufacturers:Boeing and Airbus procurement teams now specify chemistry and morphology independently of printer OEM recommendations. Narrowbody programs in the United States and France unbundle material costs from machine service contracts.
- Space Agencies:NASA and ESA qualify EBM and DED processes for rocket engine manifolds and thermal management hardware.
- Maintenance Providers:MRO operators leverage digital spare part catalogs for legacy fleet support.
Defense Contractors holds installed capacity. Maintenance Providers is rotating up the share rankings as digital inventory platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors in the United States absorb qualification premiums for flight-critical titanium hardware, while Indian procurement teams under PLI schemes prioritize cost-efficient nickel superalloy localization. German buyers accept elevated powder prices for EASA traceability compliance. Chinese state-owned airframers negotiate volume discounts on qualified atomization capacity.
United States
Lockheed Martin and Northrop Grumman drive Ti-6Al-4V powder demand for fighter airframe brackets under revised MIL-STD-31000B guidelines. FAA airworthiness directives mandate 15-year retention of atomization parameters and chemical assay records. Seattle-Tacoma aerospace clusters anchor Boeing procurement teams that now unbundle material costs from printer OEM service contracts.
Germany
EOS GmbH systems anchor European production capacity for nickel superalloy turbine hardware, with defense contractors consolidating long-term supply agreements. EASA certification memoranda require statistical validation of powder reuse ratios, forcing closed-loop sieving investments. Munich industrial clusters absorb smaller atomization facilities into captive supply chains as qualification barriers tighten.
China
State-owned airframers qualify EBM Ti-6Al-4V for narrowbody programs at production rates compressing buy-to-fly ratios below 3:1. GB standards and MIIT dual carbon goals shape powder recycling economics for domestic atomizers. Yangtze River Delta manufacturing bases concentrate plasma atomization capacity for aerospace-grade spherical morphology requirements.
India
PLI scheme incentives for aerospace components create captive demand for indigenized Inconel 718 powder production. BIS standards harmonization with ISO/ASTM 52900 reduces cross-border qualification friction for defense contractors. Bengaluru and Hyderabad defense manufacturing corridors attract backward integration investments from global atomization specialists.
France
Airbus procurement teams in Toulouse specify chemistry and morphology independently of printer manufacturer recommendations. ANSM traceability protocols align with EASA powder lot retention mandates for flight-critical hardware. Île-de-France aerospace engineering centers drive narrowbody retrofit demand for flame-smoke-toxicity compliant ULTEM 9085 cabin brackets.
Aerospace 3D Printing Materials Market Vendor Landscape
Capability concentration sits with specialized atomization houses that control plasma and electrode induction spheroidization IP; scale advantage sits with diversified materials conglomerates that cross-subsidize aerospace qualification costs from industrial powder volumes. The vendor base stratifies into three tiers: captive powder divisions of machine OEMs, independent qualified atomizers, and industrial-grade feedstock suppliers attempting aerospace certification. Consolidation pressure intensifies as EASA statistical validation requirements raise working capital barriers. Dominant competitive moves include long-term supply agreement lock-ins with airframer procurement teams and geographic expansion into PLI-subsidized defense manufacturing corridors.
Within the independent qualified atomizer tier, Höganäs AB and GKN Powder Metallurgy exemplify European positioning through captive electrode induction capacity. Stratasys Ltd occupies a position representing machine-integrated material bundling, though airframer disintermediation pressures this model. EOS GmbH anchors the powder-bed fusion system tier where material qualification barriers protect margin pools. These three entities illustrate divergent responses to FAA and EASA traceability mandates: backward integration into atomization, strategic partnership with qualified suppliers, or specification independence from printer recommendations.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Corporation |
| EOS GmbH |
| Höganäs AB |
| ExOne |
| ATI |
| GKN Powder Metallurgy |
| CNPC Powder |
| Arkema Inc |
| Others |
Supply Flow & Price Mechanics
Munich industrial clusters anchor European plasma atomization capacity, concentrating qualified Ti-6Al-4V powder supply among six global producers and granting incumbent atomizers substantial pricing leverage over airframer procurement teams. This geographic concentration interacts with FAA 15-year traceability mandates to inflate working capital requirements, compressing margins for smaller European producers while consolidating premium pricing power among EASA-compliant suppliers.
Pricing Analysis
Aftermarket service revenue from powder recycling and closed-loop sieving contracts drives lifetime value for qualified atomizers. Three-tier pricing structure across aerospace-certified, industrial-grade, and prototype feedstock tiers separates flight-critical Ti-6Al-4V from non-structural thermoplastics. Cost compression in nickel superalloy powders is intensifying because airframers unbundle material procurement from printer OEM service contracts. Tier suppliers and independent additive specialists exhibit highest price sensitivity; defense contractors absorbing MIL-STD-31000B qualification costs show lowest.
Supply Chain Analysis
Extended payment terms from Boeing and Airbus procurement teams strain working capital for independent atomizers, accelerating captive supply chain absorption. Plasma atomization capacity concentrates in Germany, the United States, and China, drawing from titanium sponge feedstock, argon gas supply, and electrode induction spheroidization IP. Single-source vulnerability pervades the six qualified spherical powder producers globally. Distribution runs through long-term supply agreements directly with airframer procurement teams rather than machine OEM bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates this market as airframer disintermediation from printer OEM service contracts creates niches for independent qualified atomizers and specialized thermoplastic compounders.
For Market Incumbents: Pre-empt consolidation pressure from EASA statistical validation requirements by locking in 10-15 year supply agreements with Boeing and Airbus procurement teams. Backward integration into electrode induction spheroidization capacity protects margin pools from emerging Indian PLI-subsidized competitors. Certification investment in closed-loop powder reuse validation represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in flame-smoke-toxicity compliant ULTEM 9085 cabin brackets for narrowbody retrofit programs across France and the United States. White-space targets include indigenized Inconel 718 powder production for Indian defense manufacturing corridors and digital twin-integrated outcome-based supply contracts for MRO operators. Go-to-market angle: direct contracting with maintenance providers bypassing established OEM procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized atomization houses with captive plasma and EBM process-parameter IP over diversified materials conglomerates. Long-term viability across the 5-10 year window rests on EASA traceability compliance infrastructure and powder recycling economics. Acquisition target archetype: European qualified atomizers with closed-loop sieving validation and existing airframer supply agreements. Signal to watch: FAA codification of in-situ process monitoring as acceptable conformity evidence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atomization | EOS GmbH and GKN Powder Metallurgy secure captive Ti-6Al-4V powder supply against EASA consolidation pressure. |
| Long-term Supply Agreement Lock-in | Boeing and Airbus procurement teams now specify chemistry independently, favoring direct atomizer relationships. |
| Digital Twin Platform Integration | Converging in-situ monitoring with predictive maintenance enables outcome-based powder supply contracts. |
| Geographic Expansion into PLI Corridors | Bengaluru and Hyderabad defense manufacturing clusters attract indigenized nickel superalloy powder investments. |
| Closed-loop Powder Reuse Validation | EASA statistical validation requirements force consolidation among European producers unable to fund campaigns. |
Methodological Framework
Operator-level perspectives from powder metallurgy plant managers, airframer procurement executives, FAA certification specialists, and MRO inventory planners anchored the qualitative base. Primary interviews combined with secondary validation from FAA airworthiness directives, EASA certification memoranda, ISO/ASTM 52900 standards documentation, and SEC filings from publicly traded additive manufacturing equipment vendors. Bottom-up atomization capacity modeling and top-down airframer demand triangulation cross-verified segment outputs.
Scenario-bracketing around regulatory acceleration, defense procurement cycles, and powder recycling economics framed the analytical approach across the projection horizon. Segmentation dimensions modeled include material type, application tier, technology platform, and end-user procurement sophistication. CAGRs derived from installed base expansion rates, qualification timeline compression, and buy-to-fly ratio improvements in EBM Ti-6Al-4V structural brackets. Forecast inputs incorporated MIL-STD-31000B guideline revisions and PLI scheme incentive trajectories.
Stress conditions across FAA traceability mandate enforcement intensity, plasma atomization capacity expansion, and airframer unbundling velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline standardization and powder reuse ratio validation. Macroeconomic contraction, regulatory deviation from ISO/ASTM 52900 harmonization, or breakthrough multi-material deposition integration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing Plastics Market