
 Polypropylene in 3D Printing Market | 2026-2036
Polypropylene in 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene in 3D Printing Market Analytics
Material scientist availability is bifurcating the competitive landscape between established polymer houses and specialized additive startups. Stratasys Ltd. leverages its fused deposition modeling installed base to drive filament adoption across service bureaus. SABIC anchors supply security through backward integration into polypropylene resin production, capturing margin pools upstream. Evonik Industries AG specializes in high-flow powder formulations optimized for selective laser sintering platforms.
Polypropylene in 3D printing denotes thermoplastic additive manufacturing using isotactic polypropylene feedstocks with melt flow indices between 20-50 g/10min, processed through fused deposition modeling, selective laser sintering, or multi-jet fusion to produce chemically resistant, fatigue-tolerant components. The material serves industrial applications requiring living hinge performance, sterilization compatibility, or hydrocarbon exposure resistance that elude ABS or PLA alternatives. Filament dominates current volume through accessibility to desktop and benchtop printer fleets, though powder formats command premium positioning in production-grade healthcare and aerospace workflows. Medical Devices represents the fastest-growing application segment as sterilizable, biocompatible polypropylene displaces polycarbonate in surgical instrument prototyping and custom orthopedic tooling.
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern healthcare applications, while REACH and RoHS frameworks in Europe restrict residual monomer content in consumer-facing parts. The EU MDR intensifies documentation burdens for patient-contact components, favoring suppliers with established regulatory dossiers over commodity entrants. Stakeholders must weigh capital allocation between filament scale economies and powder qualification investments as production applications outpace prototyping volumes.
Market Dynamics
Automotive lightweighting mandates and medical sterilization requirements are pulling polypropylene 3D printing from prototyping into certified end-use production, restructuring supplier qualification hierarchies around resin purity documentation and platform-specific material datasets.
Growth Catalysts
- Automotive Weight Reduction:Tier-1 suppliers in Germany's Stuttgart industrial cluster are qualifying polypropylene living hinges and ductwork for electric vehicle thermal management systems.
- FDA Material Pathways:ISO 10993 biocompatibility certification is opening surgical instrument prototyping workflows to sterilizable polypropylene formulations previously reserved for polycarbonate.
- Selective Laser Sintering Maturation:High-flow powder grades with melt flow indices above 35 g/10min are enabling batch production of fatigue-tolerant orthopedic tooling.
Market Restraints
- Propylene Feedstock Volatility:Naphtha-cracking economics in the US Gulf Coast and Rotterdam harbor complexes transmit directly to filament and powder pricing.
- Resin Purity Concentration:Medical-grade isotactic polypropylene with sub-50 ppm residual monomer content relies on a narrow supplier base in Belgium and the Netherlands.
- Platform Lock-In Effects:Fused deposition modeling slicer presets and build chamber thermal profiles create switching costs between printer OEM ecosystems.
Strategic Opportunities
- India Industrial Additive:PLI scheme incentives for domestic medical device manufacturing are creating first-mover advantages for localized filament compounding operations.
- Multi-Jet Fusion Convergence:Hewlett Packard's open materials strategy is inviting third-party polypropylene powder qualification for production aerospace ducting.
- EU MDR Documentation Services:Technical file preparation and clinical evidence packaging for patient-contact components represent high-margin service adjacencies.
Industry Challenges
- Material Scientist Scarcity:Formulation chemists with simultaneous expertise in rheology control, laser absorption tuning, and regulatory dossier construction command premium compensation.
- Qualification Timeline Compression:FDA 510(k) clearance cycles for patient-specific surgical guides extend 18-24 months, misaligning with product development sprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene in 3D Printing Market |
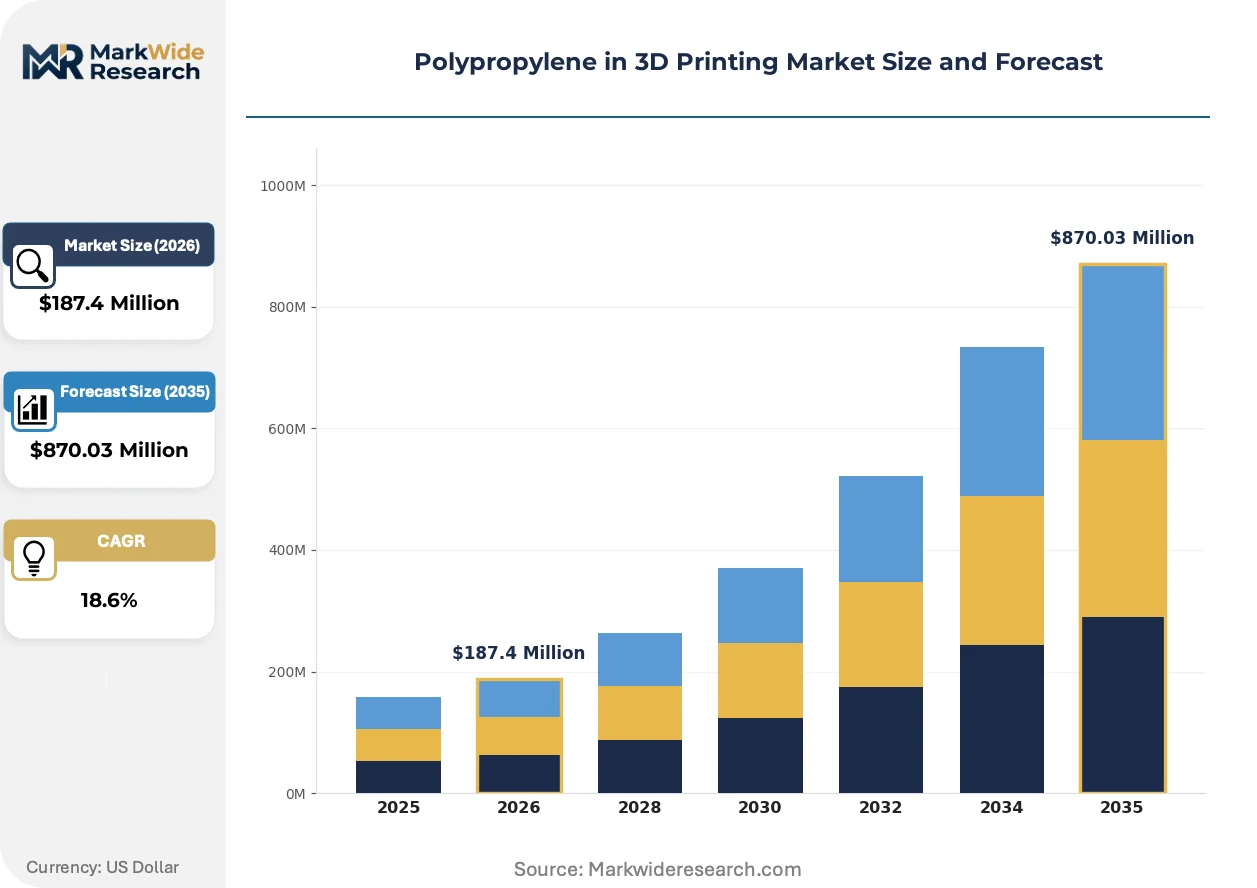
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Resin, Powder, Sheet Application: Prototyping, End-Use Parts, Tooling, Medical Devices Delivery Mode: Online, Retail, Direct Sales, Distributors Industry Vertical: Aerospace, Automotive, Consumer Goods, Healthcare |
| Companies Covered | HP Inc., Stratasys Ltd., 3D Systems Inc., LyondellBasell Industries, SABIC, Covestro AG, Evonik Industries AG, Arkema, Materialise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene in 3D Printing Market Evolving Landscape
Polypropylene 3D printing is bifurcating into commodity filament for service bureaus and premium powder for regulated production, with technology choices hardening into strategic commitments rather than tactical selections.
Reinforced polypropylene composites with glass fiber loadings between 15-30% by weight are fragmenting the historical neat resin market. Automotive underhood component manufacturers in Michigan and Lower Saxony are adopting these grades for charge air cooler housings and battery module brackets. The technology is fragmenting supplier relationships as compounders must now certify fiber dispersion uniformity alongside base resin metrics.
REACH Annex XVII restrictions on residual monomer content are tightening purity thresholds for consumer-facing applications. ECHA enforcement actions against imported filament spools are driving European converters toward certified supply agreements with established resin houses. Medical device contract manufacturers in Ireland and Switzerland are responding by dual-sourcing from EU-based compounding facilities with established regulatory dossiers.
Hospital procurement departments are consolidating vendor lists around suppliers offering both material qualification packages and sterilization validation support. Medical device OEMs in Minnesota and Massachusetts are displacing spot-buy filament relationships with multi-year supply agreements bundling technical support. This concentration is most visible in orthopedic and spinal implant tooling workflows where ISO 13485 certification has become a non-negotiable screening criterion.
Polypropylene in 3D Printing Market Segmentation
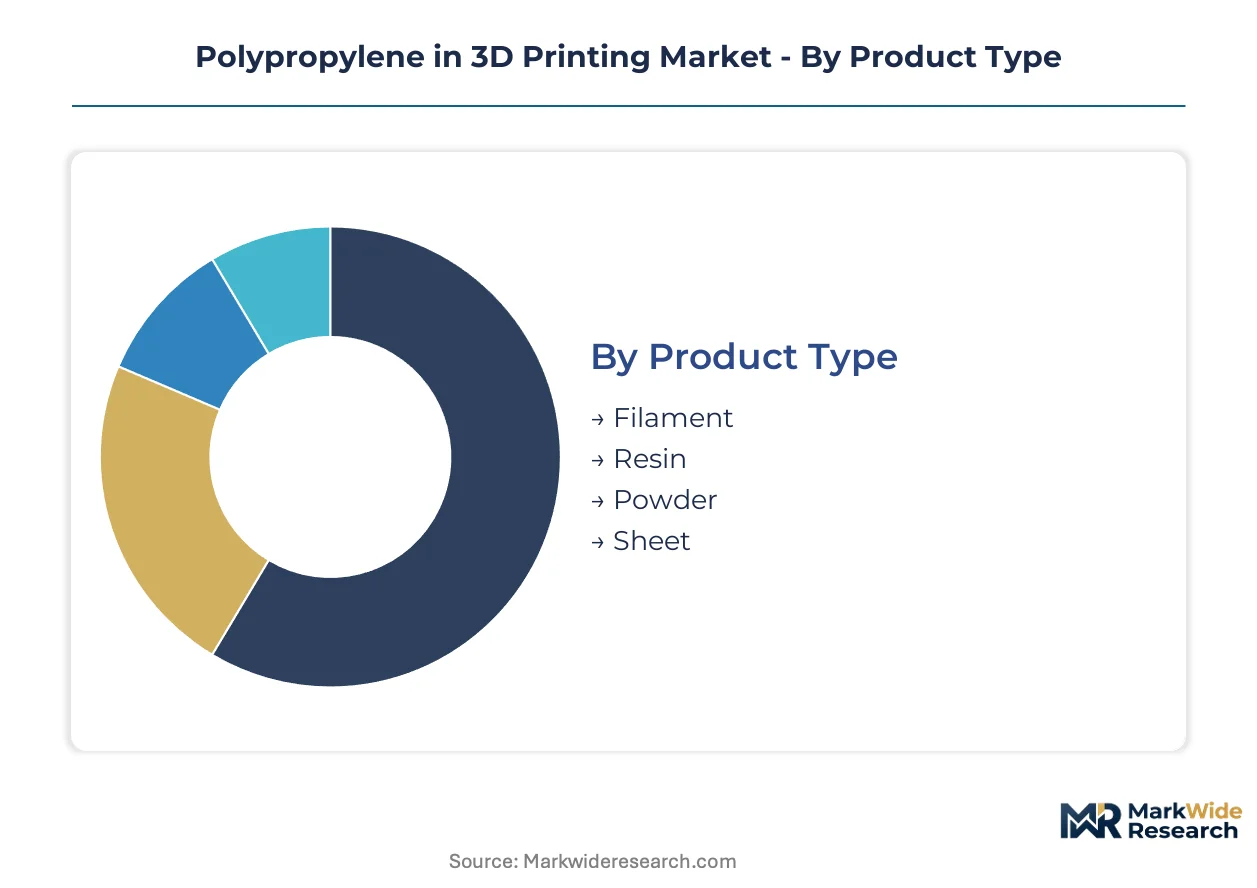
Segmentation in polypropylene 3D printing exposes divergent margin architectures across material formats and procurement channels. Product type selection dictates capital intensity, while application maturity separates prototyping commodity plays from certified production workflows.
Product Type:
Filament faces acute substitution pressure from PETG and ABS in desktop prototyping, while powder grades defend moats through selective laser sintering platform lock-in and medical qualification barriers.
- Filament:Continuous fiber-reinforced and neat formulations dominate service bureau consumption in Germany's Munich-Stuttgart corridor. Desktop printer fleet expansion in North American maker spaces sustains volume, though margin compression intensifies as Chinese suppliers flood commodity spool channels.
- Powder:High-flow isotactic grades with melt flow indices exceeding 35 g/10min enable batch production of fatigue-tolerant orthopedic tooling. Healthcare contract manufacturers in Ireland and Switzerland pay premiums for ISO 13485-certified supply with documented residual monomer below 50 ppm.
- Resin:Photopolymerizable polypropylene formulations remain niche, constrained by limited vat photopolymerization printer compatibility and higher raw material costs versus thermoplastic alternatives.
- Sheet:Laminated stock for CNC-assisted hybrid manufacturing serves jigs and fixtures in automotive stamping plants, though additive-native competition from large-format fused deposition modeling is eroding addressable volume.
Filament retains volume leadership; powder holds the steepest expansion curve.
Application:
Cost tier stratification separates low-margin prototyping from premium certified production, with tooling occupying an intermediate position where throughput economics dominate qualification burdens.
- Prototyping:Design validation and form-fit testing consume the majority of filament volume through service bureau networks. German automotive OEMs specify polypropylene for living hinge prototypes to validate fatigue performance before steel tooling commitment.
- Medical Devices:Sterilizable surgical instrument prototypes and patient-specific orthopedic tooling command premium positioning. FDA 510(k) clearance requirements and ISO 10993 biocompatibility testing create qualification moats that commodity suppliers cannot cross.
- End-Use Parts:Production adoption concentrates in electric vehicle thermal management ducting and aerospace cabin components where weight reduction mandates override legacy material specifications.
- Tooling:Jigs, fixtures, and manufacturing aids represent high-throughput, medium-margin business where print speed and material cost efficiency outweigh regulatory documentation requirements.
Prototyping captures the widest installed base; medical devices is expanding most quickly.
Delivery Mode:
Customer type fragmentation splits procurement between price-sensitive spot buyers and integrated supply agreements demanding technical support bundling.
- Direct Sales:Medical device OEMs in Minnesota and Massachusetts negotiate multi-year agreements combining material supply with sterilization validation support and regulatory dossier maintenance.
- Distributors:Regional industrial distributors in the US Midwest and German Ruhrgebiet hold inventory for just-in-time fulfillment to tier-1 automotive suppliers, capturing margin through technical service and application engineering.
- Online:E-commerce platforms serve hobbyist and education markets with commoditized filament spools, though REACH compliance documentation gaps expose European buyers to enforcement risk.
- Retail:Brick-and-mortar channels for professional 3D printing supplies have contracted as procurement shifts toward direct manufacturer relationships and specialized distributors.
Direct sales commands the highest value per transaction; distributors maintain the broadest geographic coverage.
Industry Vertical:
Supply concentration in healthcare and aerospace contrasts with automotive's distributed procurement, reshaping supplier qualification investments.
- Healthcare:Hospital procurement consolidation around ISO 13485-certified vendors is displacing spot-buy relationships. Swiss and Irish contract manufacturers dual-source from EU-based compounding facilities with established regulatory dossiers.
- Automotive:Electric vehicle thermal management systems and battery module brackets in Michigan and Lower Saxony drive glass-reinforced polypropylene adoption for underhood components.
- Aerospace:Production aerospace ducting qualification on multi-jet fusion platforms requires third-party powder certification, with open materials strategies inviting new supplier entry.
- Consumer Goods:REACH Annex XVII residual monomer restrictions and ECHA enforcement actions against imported filament are driving European converters toward certified supply agreements with established resin houses.
Automotive generates the highest unit volumes; healthcare delivers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powder-grade polypropylene commands 40% pricing premiums in Switzerland versus spot-market filament in China's Pearl River Delta. This asymmetry reflects regulatory documentation burdens and medical-grade purity requirements rather than raw material costs alone.
United States
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards drive medical device adoption in Minnesota and Massachusetts. Hospital procurement consolidation favors suppliers bundling sterilization validation with material supply. The Twin Cities corridor anchors surgical instrument prototyping workflows for orthopedic OEMs.
Germany
Automotive lightweighting mandates from KBA and EU Green Deal carbon targets accelerate electric vehicle thermal management applications. REACH compliance documentation creates moats against commodity filament imports. The Stuttgart-Munich industrial cluster hosts tier-1 supplier qualification programs for living hinge ductwork.
China
Domestic medical device manufacturing expansion under the 14th Five-Year Plan drives filament demand in Jiangsu and Zhejiang provinces. NMPA regulatory harmonization with ISO standards enables export-oriented production. The Yangtze River Delta concentrates desktop printer fleet deployment for service bureau networks.
Switzerland
Swissmedic certification requirements and EU MDR technical file preparation sustain premium powder pricing. Contract manufacturers in the Basel-Zurich corridor dual-source from EU-based compounding facilities. The country's precision manufacturing heritage supports patient-specific orthopedic tooling workflows.
India
PLI scheme incentives for domestic medical device manufacturing attract filament compounding investments in Maharashtra and Gujarat. CDSCO regulatory alignment with ISO 13485 enables export qualification. The Pune industrial corridor emerges as a hub for automotive prototyping service bureaus.
Polypropylene in 3D Printing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Specialized additive material houses command premium positioning through regulatory dossiers and platform-specific formulations, while integrated polymer majors leverage resin production scale for filament cost advantages. Three archetypes dominate: backward-integrated resin producers, platform-locked material specialists, and regulatory-certified healthcare suppliers. Competitive moves concentrate on powder qualification investments for production workflows and multi-year supply agreements bundling technical support.
Among the integrated polymer majors, SABIC and LyondellBasell Industries exemplify cost-leadership archetypes through captive resin supply. Evonik Industries AG occupies a specialist position in high-flow powder formulations. Stratasys Ltd. represents platform-ecosystem leverage, converting installed base scale into filament adoption across service bureau networks. These three anchors illustrate divergent strategic commitments rather than direct competition.
| Leading Market Players |
|---|
| HP Inc. |
| Stratasys Ltd. |
| 3D Systems Inc. |
| LyondellBasell Industries |
| SABIC |
| Covestro AG |
| Evonik Industries AG |
| Arkema |
| Materialise |
| Others |
Value Network & Pricing Analysis
Sixty-day powder inventory cycles at Swiss medical device contract manufacturers signal how supply-chain concentration in Belgium and the Netherlands translates directly into pricing premiums for ISO 13485-certified polypropylene. Filament buyers in China's Yangtze River Delta operate on fifteen-day just-in-time turns, compressing margins through spot-market procurement that bypasses regulatory documentation burdens entirely.
Pricing Analysis
The customization-premium spread between configured-to-order medical powder and standard filament spools runs three-to-one in European markets. Three-tier pricing structure across premium certified, standard industrial, and economy desktop grades anchors the market, with FDA 510(k) dossier maintenance and ISO 10993 testing as the primary price differentiation drivers. Cost compression in commodity filament channels is intensifying because Chinese suppliers are flooding e-commerce platforms with REACH-noncompliant spools. Desktop prototyping service bureaus exhibit the highest price sensitivity, while orthopedic contract manufacturers in Ireland and Switzerland accept premium positioning for documented residual monomer below fifty ppm.
Supply Chain Analysis
Strategic stockpile preferences dominate medical-grade procurement, with Swiss and Irish contract manufacturers maintaining ninety-day powder inventories against propylene feedstock volatility. Supply concentrates in Belgium, the Netherlands, and Germany for high-purity isotactic resin, while filament compounding spreads across China's Jiangsu and Zhejiang provinces. Raw material dependencies rest on naphtha-cracking economics from Rotterdam harbor and US Gulf Coast complexes, laser-grade additive packages, and medical-certification documentation services. Single-source vulnerability in medical-grade resin purification creates structural risk. Distribution runs through regional industrial distributors in Germany's Ruhrgebiet and the US Midwest holding inventory for tier-one automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EU MDR, and NMPA pathways is fragmenting supplier qualification requirements, creating specialist niches for dossier-capable compounders and opening entry points for regional certification experts.
For Market Incumbents: Consolidate regulatory dossier libraries and backward integration into propylene resin production to defend against emerging Chinese filament suppliers flooding commodity channels. Capacity addition in India's Maharashtra and Gujarat under PLI scheme incentives captures localized medical device manufacturing growth. Certification investment in ISO 13485 and sterilization validation support bundling locks in multi-year supply agreements with Minnesota and Massachusetts OEMs. For New Entrants and Emerging Players: Differentiate on EU MDR technical file preparation and clinical evidence packaging as high-margin service adjacencies to material supply. The most penetrable white space sits in India's Pune industrial corridor, where automotive prototyping service bureaus lack qualified polypropylene filament sources. Target aerospace multi-jet fusion powder qualification, where Hewlett Packard's open materials strategy invites third-party supplier entry without platform lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified polymer majors with underutilized medical-grade compounding assets and dormant regulatory dossiers. Long-term viability hinges on powder qualification investments for production workflows outpacing prototyping volumes. The signal to watch is hospital procurement consolidation velocity, as ISO 13485 certification becomes a non-negotiable screening criterion displacing spot-buy relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | SABIC and LyondellBasell capture upstream margin pools and supply security for filament scale economies. |
| Medical-Grade Powder Qualification | Evonik Industries AG defends premium positioning through high-flow formulations optimized for selective laser sintering platforms. |
| Platform Ecosystem Leverage | Stratasys Ltd. converts fused deposition modeling installed base into filament adoption across service bureau networks. |
| Regulatory Dossier Services | EU MDR technical file preparation creates high-margin service adjacencies bundling sterilization validation with material supply. |
| Geographic Manufacturing Footprint | PLI scheme incentives in Maharashtra and Gujarat attract localized filament compounding for domestic medical device production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across material formulation chemists, regulatory affairs leads at medical device OEMs, procurement managers at tier-one automotive suppliers, and distribution channel partners in Germany's Ruhrgebiet. Secondary validation drew from FDA 510(k) filings, ECHA REACH enforcement actions, SEC 10-K disclosures of integrated polymer majors, and customs data tracking polypropylene filament imports into European ports. Bottom-up and top-down triangulation reconciled service bureau consumption estimates with resin production volumes reported by major petrochemical complexes.
Across the analysis window, the analytical framework modeled volume and value outputs through product type segmentation, application maturity tiers, delivery mode fragmentation, and industry vertical concentration. CAGRs were derived from regression analysis against automotive lightweighting mandates, medical sterilization requirements, and selective laser sintering platform deployment curves. Forecast inputs incorporated propylene feedstock volatility indices from Rotterdam and US Gulf Coast naphtha-cracking spreads, alongside hospital procurement consolidation velocity metrics.
Material uncertainties — propylene feedstock volatility, ECHA enforcement intensity against imported filament, and FDA 510(k) clearance timeline compression — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained automotive electric vehicle thermal management adoption and medical device outsourcing trends. Revision becomes warranted when hospital procurement consolidation velocity crosses thresholds that displace spot-buy relationships faster than qualified supplier capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market