
 Advanced Materials for 3D Printing Market | 2026-2036
Advanced Materials for 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Materials for 3D Printing Market Outlook
High-performance aerospace-grade certification tiers is collapsing the gap between prototyping polymers and production-qualified materials. EOS GmbH leverages its laser-sintering material portfolio to dominate industrial metal powder supply. BASF sustains broad filament and resin chemistry capabilities across European manufacturing hubs. Evonik Industries AG specializes in high-temperature polyamide formulations for engine-adjacent applications.
Advanced materials for 3D printing encompass engineered polymers, metals, ceramics, and composites formulated with defined melt-flow indices, particle size distributions, and thermal stability thresholds to enable layer-by-layer construction of functional geometries. These materials must achieve precise viscosity profiles during extrusion or sintering to produce isotropic mechanical properties in finished components for load-bearing industrial use. Powder form factors lead structural demand in aerospace and medical implant segments where laser-based fusion requires tightly controlled spherical particle morphology. Resin formulations for vat photopolymerization occupy premium margin pools in dental and hearing-aid manufacturing, while filament extrusion competes on volume across educational and consumer prototyping channels.
The US FAA and EASA impose stringent qualification protocols on flight-critical additively manufactured parts, forcing material suppliers to invest in batch-traceability systems and statistical process documentation. REACH and RoHS frameworks in Europe restrict certain chemical additives in photopolymer resin systems, redirecting R&D toward bio-based initiator compounds. ISO and ASTM standards for additive manufacturing feedstock characterization are consolidating testing methodologies across North American and Asian supply bases. Stakeholders must monitor evolving medical-device material master files at the FDA and Japan's PMDA as patient-specific implant applications expand regulatory scrutiny beyond mechanical performance into biocompatibility certification pathways.
Market Dynamics
Flight-certification bottlenecks are compressing the timeline between material development and aerospace qualification, forcing suppliers to front-load statistical process documentation before prototype validation. EOS GmbH and BASF have restructured their R&D pipelines around batch-traceability systems that anticipate FAA and EASA audit requirements.
Growth Catalysts
- Engine-adjacent thermoplastic demand:Aerospace OEMs are qualifying high-temperature polyamide formulations for cabin pressure vessels and engine nacelles, bypassing traditional subtractive manufacturing lead times.
- REACH-compliant resin innovation:European photopolymer suppliers are redirecting formulation chemistry toward bio-based initiator compounds ahead of RoHS additive restrictions, opening dental and hearing-aid manufacturing channels.
- Laser-sintering material standardization:ISO and ASTM feedstock characterization protocols are consolidating testing methodologies across German and Japanese supply bases, reducing cross-border qualification redundancy.
Market Restraints
- Titanium powder supply concentration:Spherical plasma-atomized titanium feedstock for aerospace laser fusion remains captive to three primary refiners, exposing buyers to spot-price volatility and allocation risk.
- FAA qualification timeline friction:Statistical process documentation requirements for flight-critical parts extend material approval cycles to 18-24 months, freezing capital in pre-revenue development phases.
- Subtractive machining substitution:Five-axis CNC systems retain cost advantages for titanium structural brackets below 50-unit production runs, capping addressable volume for metal additive in legacy aerospace programs.
Strategic Opportunities
- India medical implant localization:CDSCO and BIS are harmonizing biocompatibility certification pathways for patient-specific cranial and orthopedic implants, reducing import dependency on European material master files.
- Multi-material extrusion convergence:Continuous fiber-reinforced thermoplastic printing is merging with automated fiber placement to produce load-bearing aerospace brackets without autoclave curing cycles.
- US IRA clean manufacturing incentives:Domestic powder atomization facilities qualify for advanced energy project credits, offsetting capital intensity for regional titanium and nickel superalloy supply.
Industry Challenges
- Process engineer scarcity:Laser-sintering parameter optimization for novel alloy systems requires hybrid metallurgy-software expertise that outpaces European and North American technical training pipeline output.
- Legacy MES integration friction:Additive work cell data architectures lack standardized APIs for SAP and Oracle shop-floor systems, forcing custom middleware development at each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Materials for 3D Printing Market |
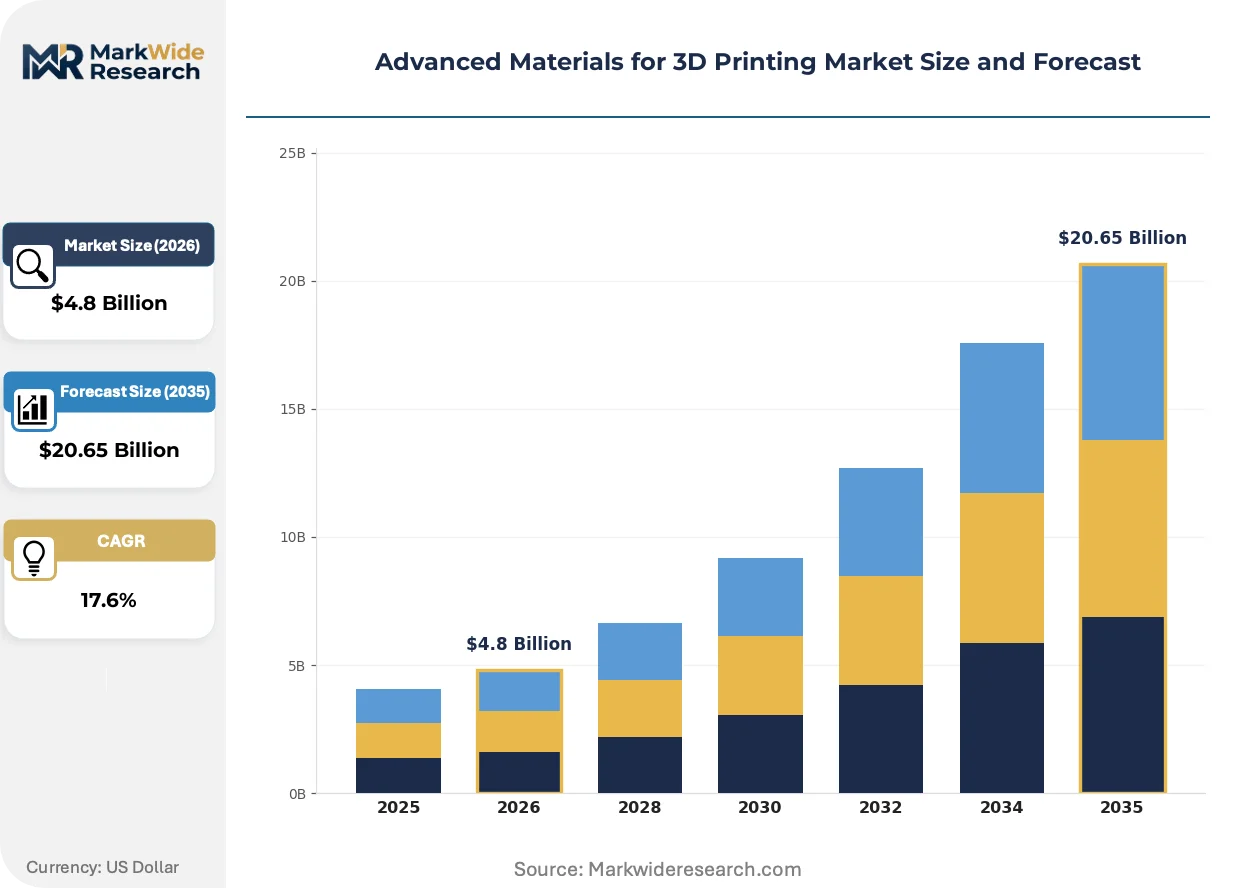
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, ABS, Nylon, TPU Form Factor: Filament, Powder, Resin, Paste End User: Aerospace, Automotive OEMs, Healthcare, Consumer Electronics Application: Prototyping, Tooling, Production Parts, Educational Use |
| Companies Covered | 3D Systems, Inc., Stratasys, EOS GmbH, HP Development Company, L.P., BASF, General Electric Company, Arkema, Evonik Industries AG, Materialise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Materials for 3D Printing Market Strategic Shifts
Material qualification protocols are bifurcating into two tracks: rapid prototyping tiers optimized for printability, and production-grade tiers engineered for statistical mechanical reliability. This divergence is reshaping supplier R&D allocation and buyer procurement segmentation simultaneously.
Continuous fiber-reinforced thermoplastic printing is decomposing the traditional autoclave-cured composite supply chain for aerospace secondary structures. Tier 1 suppliers are adopting in-situ consolidation systems for flight-certified brackets and ducting. This technology is decomposing capital requirements for mid-volume aerostructure programs by eliminating tooling lead times and cure oven bottlenecks.
EASA's updated AMC 20-42 guidance for additive manufacturing is compressing design organization approval timelines for metal laser powder bed fusion. The framework introduces standardized damage tolerance assumptions that reduce case-by-case negotiation with national authorities. German and Italian aerospace clusters are leveraging this regulatory clarity to consolidate multi-site qualification across distributed manufacturing networks.
Consolidated procurement of certified material lots is displacing spot-market powder purchasing among tier 1 aerospace suppliers. Long-term offtake agreements with atomization facilities now include embedded statistical process control data packages that satisfy FAA Order 8110.55 audit trails. This shift is most visible in US and German supply chains where flight-critical part liability concentrates buyer risk tolerance toward traceable batch provenance.
Advanced Materials for 3D Printing Market Segmentation
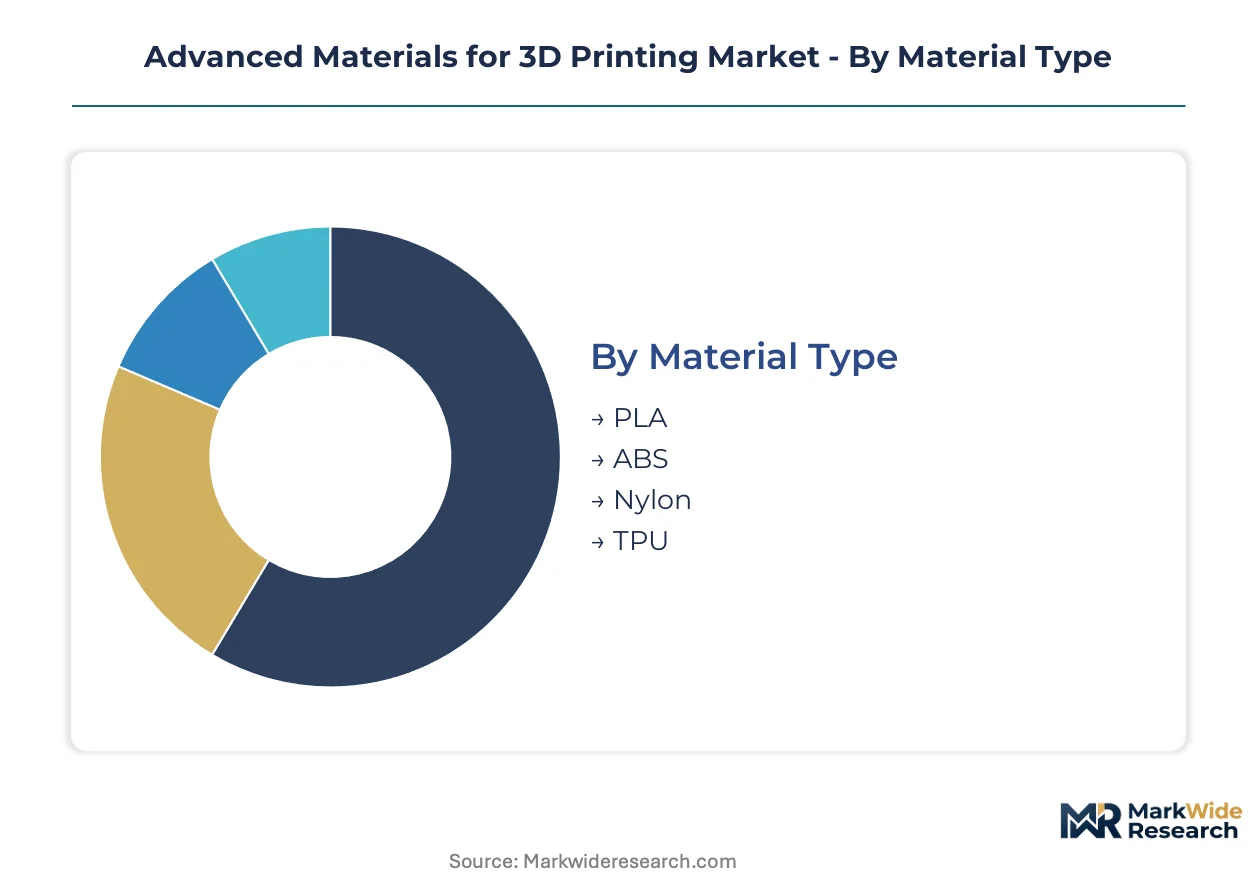
Material segmentation in additive manufacturing determines qualification pathways, supply chain configuration, and margin capture. Each category reflects distinct technical specifications that govern printer compatibility and end-use certification requirements.
Material Type:
Geographic demand spreads unevenly across these polymers, with PLA and ABS dominating domestic educational and consumer markets while Nylon and TPU concentrate in export-oriented industrial supply chains serving aerospace and medical device manufacturers.
- PLA:Polylactic acid delivers low-temperature printability with minimal warping, making it the default feedstock for desktop extrusion systems. Demand concentrates in North American and European educational institutions and consumer prototyping channels where biodegradability and odorless processing offset limited thermal resistance. Cost sensitivity in these segments constrains supplier margins despite volume scale.
- ABS:Acrylonitrile butadiene styrene provides higher impact strength and temperature tolerance than PLA, qualifying it for functional automotive interior components and consumer electronics housings. German automotive OEMs specify ABS formulations for dashboard prototyping and small-series tooling, driving batch-consistent supply requirements from European compounders.
- Nylon:Polyamide formulations serve laser-sintering platforms in aerospace ducting and medical instrument production.
- TPU:Thermoplastic polyurethane enables flexible lattice structures for footwear midsoles and protective equipment.
ABS holds the largest share; momentum sits with Nylon as flight-certification protocols mature.
Form Factor:
Cost tiers separate these categories sharply, with powder and resin commanding premium pricing tied to aerospace and medical qualification overhead while filament and paste compete on volume in price-sensitive prototyping segments.
- Filament:Extruded polymer wire dominates unit volume across educational, hobbyist, and entry-level professional installations. Spooled ABS and PLA feedstock moves through distributor networks in the US, Germany, and China with minimal technical support requirements, compressing margins toward commodity levels.
- Powder:Spherical metal and polymer particles engineered for laser powder bed fusion carry the highest qualification burden and corresponding price premiums. Titanium and nickel superalloy powders for aerospace engine components require plasma atomization, inert handling, and batch-traceability documentation that satisfies FAA Order 8110.55 audit trails.
- Resin:Photopolymer formulations for vat photopolymerization occupy dental and hearing-aid manufacturing with tight viscosity control.
- Paste:High-viscosity extrusion materials support construction-scale printing and ceramic prototyping at experimental deployment stages.
Powder captures the highest value per kilogram; filament expands most quickly as desktop printer installation accelerates.
End User:
Application maturity varies dramatically across these verticals, with aerospace and healthcare demanding production-grade certification while automotive and consumer electronics tolerate broader prototyping tolerances.
- Aerospace:Flight-critical component manufacturing imposes the most stringent material qualification protocols through FAA and EASA oversight. EOS GmbH and BASF supply laser-sintering powders and high-temperature thermoplastics for cabin pressure vessels and engine nacelles where statistical process documentation extends approval cycles.
- Healthcare:Patient-specific implants and surgical instruments require biocompatibility certification through FDA and Japan's PMDA master file pathways. Cranial and orthopedic applications concentrate demand for titanium and PEEK formulations with traceable batch provenance.
- Automotive OEMs:Functional prototyping and tooling fixtures drive ABS and nylon consumption for interior component validation.
- Consumer Electronics:Enclosure prototyping and custom accessory production absorb PLA and resin volumes with minimal regulatory overlay.
Aerospace commands the steepest pricing; healthcare shows the steepest expansion trajectory as implant personalization scales.
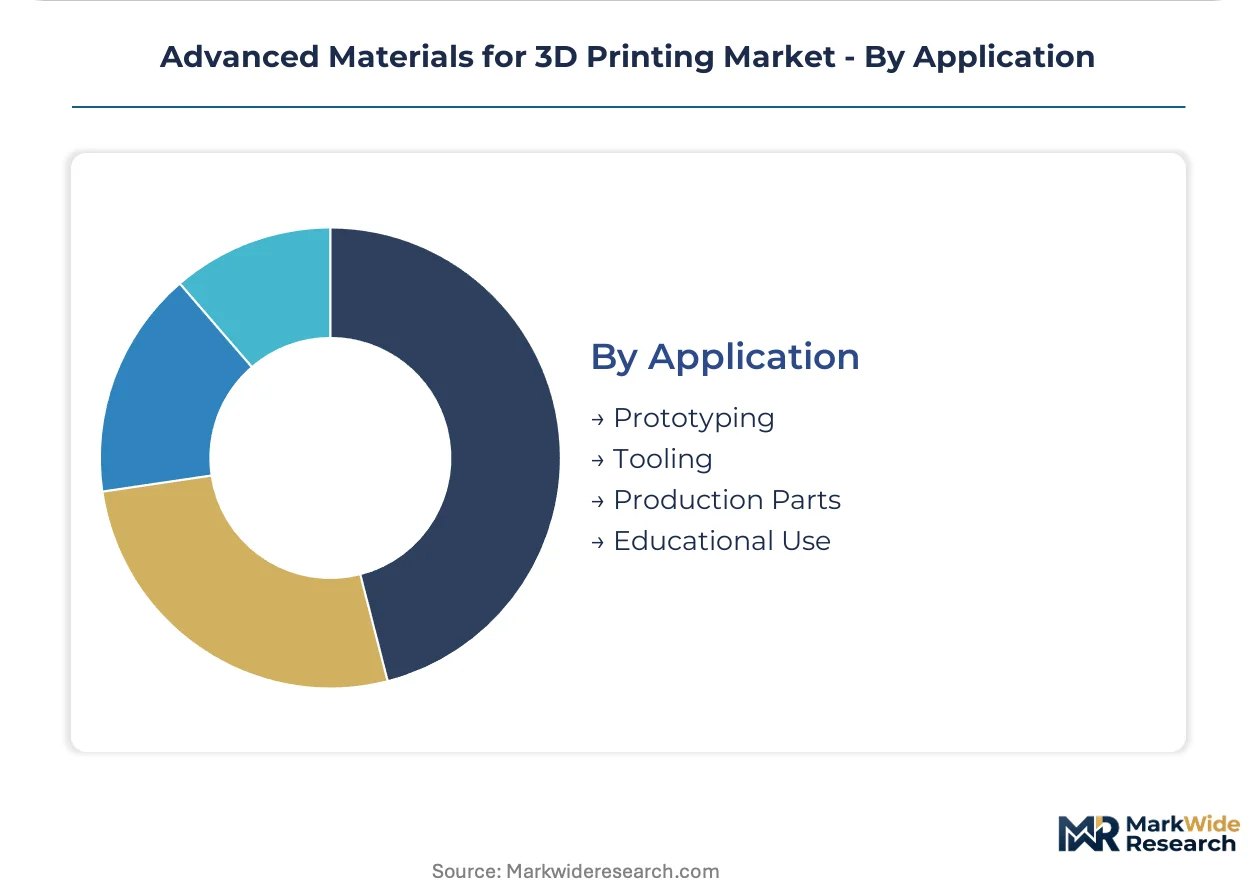
Application:
Customer procurement patterns diverge across these use cases, with production parts requiring long-term offtake agreements and statistical process control while prototyping and educational use sustain spot-market purchasing.
- Prototyping:Design validation and form-factor testing consume the majority of PLA, ABS, and standard resin volumes across corporate R&D departments and independent design firms. Rapid iteration requirements prioritize print speed and material cost over mechanical isotropy, concentrating demand in North American and European urban technology clusters.
- Production Parts:End-use component manufacturing shifts procurement toward certified material lots with embedded quality documentation. Aerospace bracket production and medical implant fabrication require locked specifications and batch traceability that disqualify spot-market sourcing.
- Tooling:Jigs, fixtures, and mold inserts absorb nylon and composite formulations for manufacturing floor applications.
- Educational Use:University and secondary school programs drive filament volume with curriculum-integrated printer installations.
Prototyping retains volume leadership; production parts gain share fastest as qualification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spherical metal powder atomization capacity clusters in Germany and the United States, with regulatory harmonization between the FAA and EASA accelerating cross-border material qualification. German suppliers anchor European aerospace supply chains while US facilities capture IRA clean manufacturing incentives. Asian demand concentrates in Japan and India where medical implant certification pathways are localizing.
United States
Aerospace OEMs in Washington and California states are locking in long-term titanium powder offtake agreements with domestic atomization facilities. The FAA's updated Order 8110.55 streamlines statistical process documentation for flight-critical laser-sintered components. The Greater Boston cluster houses medical device manufacturers qualifying PEEK formulations for patient-specific cranial implants through FDA master file pathways.
Germany
EOS GmbH and BASF anchor industrial polymer and metal powder supply chains serving Airbus and MTU Aero Engine programs. EASA's AMC 20-42 guidance reduces design organization approval timelines for laser powder bed fusion damage tolerance assumptions. The Bavarian aerospace cluster around Munich consolidates multi-site qualification across distributed manufacturing networks.
Japan
Medical device manufacturers in the Kanto region are expanding titanium implant production using PMDA-harmonized biocompatibility certification. METI funding supports high-temperature polyamide R&D for engine-adjacent applications. The Nagoya aerospace corridor qualifies laser-sintered brackets for regional jet programs through streamlined material master file submissions.
India
CDSCO and BIS harmonization is reducing import dependency on European material certifications for patient-specific orthopedic implants. Domestic powder metallurgy facilities in Maharashtra and Gujarat are scaling spherical titanium feedstock capacity. The Bangalore medical device cluster prototypes cranial implants using localized PEEK supply chains.
United Kingdom
Aerospace tier 1 suppliers in the Midlands are adopting continuous fiber-reinforced thermoplastic printing for flight-certified brackets. The UK Civil Aviation Authority aligns with EASA additive manufacturing guidance to maintain post-Brexit market access. Bristol's aerospace engineering base integrates in-situ consolidation systems for nacelle ducting production.
Advanced Materials for 3D Printing Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with laser-sintering material specialists commanding premium pricing while filament extrusion suppliers compete on volume scale. The market structures around three tiers: integrated powder atomization houses, formulation-focused chemical conglomerates, and printer-integrated material platforms. Dominant competitive moves include backward integration into spherical powder production and strategic partnerships between chemical suppliers and printer OEMs.
Within the integrated powder tier, EOS GmbH exemplifies technology leadership through its laser-sintering material portfolio dominance. BASF occupies a position bridging chemical formulation breadth with industrial polymer supply chain scale. Evonik Industries AG represents the high-temperature specialization archetype, anchoring engine-adjacent polyamide demand. These three German-origin entities collectively illustrate how European chemical industry heritage translates into additive manufacturing feedstock qualification depth.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| Stratasys |
| EOS GmbH |
| HP Development Company, L.P. |
| BASF |
| General Electric Company |
| Arkema |
| Evonik Industries AG |
| Materialise |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month qualification timelines for flight-critical materials compress inventory turns and concentrate pricing power among plasma-atomization houses in Germany and the United States. This lead-time rigidity forces tier 1 aerospace buyers into long-term offtake agreements that embed statistical process documentation premiums into unit economics.
Pricing Analysis
FAA Order 8110.55 dictates the pricing tier structure across certified and uncertified material streams. Three-tier pricing separates flight-grade titanium powders with batch-traceability documentation from industrial prototyping polymers and educational filament grades. Price differentiation hinges on certification tier and spherical particle morphology precision. Cost compression in prototyping filaments is intensifying because Chinese extrusion capacity is flooding distributor channels. Educational and hobbyist segments exhibit highest price sensitivity; aerospace engine programs show least.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes elevate inbound logistics costs for Asian filament distributors serving North American education markets. Spherical titanium and nickel superalloy powder production draws from Germany, the United States, and Japan. Raw material dependencies span titanium sponge, high-purity nickel, and engineered polyamide resin feedstocks. Single-source vulnerability concentrates in plasma-atomization equipment suppliers. Distribution runs through certified material lot procurement systems for aerospace and medical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated tier 1 aerospace OEMs as long-term offtake agreements displace spot-market purchasing. Procurement consolidation among flight-critical part manufacturers is compressing supplier margins and elevating qualification barriers.
For Market Incumbents: Shield certified material margins by embedding statistical process control data packages directly into batch documentation. Deepen backward integration into spherical powder atomization to capture IRA clean manufacturing credits in domestic US facilities. Counter emerging Chinese filament extruders through channel control over European distributor networks. For New Entrants and Emerging Players: Differentiate on localized biocompatibility certification for India's CDSCO-harmonized orthopedic implant market. Target Maharashtra and Gujarat for spherical titanium feedstock capacity to serve Bangalore medical device clusters. Pursue partnership-based go-to-market with printer OEMs for material-platform integration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize non-core additive manufacturing feedstock divisions. Five-to-ten-year viability favors specialized high-temperature polyamide formulators over commodity filament extruders. Watch FAA-EASA regulatory harmonization progress as inflection signal for cross-border qualification cost reductions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Atomization | Captures IRA credits while securing titanium supply for aerospace laser-sintering demand. |
| Long-term Supply Agreement | Locks in batch-traceability documentation streams satisfying FAA Order 8110.55 audit requirements. |
| Joint Venture | Combines EOS GmbH laser-sintering expertise with regional medical device certification capabilities. |
| Capacity Expansion | Adds spherical nickel superalloy output for engine-adjacent thermoplastic bracket programs. |
| Regulatory Certification Pathway | Accelerates EASA AMC 20-42 compliance for distributed manufacturing network qualification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with additive manufacturing engineers, aerospace procurement managers, medical device regulatory affairs leads, and powder metallurgy plant directors. Secondary validation drew from FAA Order 8110.55 documentation, EASA AMC 20-42 guidance, FDA medical device master file databases, and SEC filings of publicly traded material suppliers. Bottom-up and top-down triangulation reconciled printer installation data with certified material consumption patterns.
Across the analysis window, volume and value outputs reflect segmentation modeling across material type, form factor, end user vertical, and application maturity. CAGRs were derived from regression analysis of historical qualification timeline compression and projected adoption curves in flight-critical component manufacturing. Forecast inputs incorporated laser-sintering platform deployment rates and medical implant personalization scaling assumptions.
Material uncertainties — regulatory harmonization delays, titanium powder supply disruptions, and REACH additive restriction scope expansions — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification pathway standardization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Global 3D Printing Filament Market