
 Europe Container Drayage Market | 2026-2036
Europe Container Drayage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Container Drayage Market Insights
The shift from single-source to multi-source drayage contracting is recalibrating how European shippers manage port-to-inland risk. DB Schenker leverages its integrated rail-road network to capture intermodal volumes across the Rhine-Alpine corridor. Kuehne + Nagel anchors its drayage position through proprietary control tower visibility platforms. Maersk Line extends its terminal-operating footprint into captive hinterland services, reducing third-party dependency.
Europe container drayage denotes the short-haul movement of maritime shipping containers between ports and inland logistics nodes, typically covering distances under 100 kilometers using chassis-mounted tractor units with twist-lock securing mechanisms. The activity functions as the critical velocity constraint in multimodal supply chains, where dwell time at port gates directly determines vessel schedule reliability. Port Drayage dominates service type revenue due to concentrated throughput at Rotterdam, Hamburg, and Antwerp-Bruges, though Intermodal Drayage is gaining structural share as rail connectivity investments deepen. Refrigerated container movements command premium positioning within the container type matrix, driven by temperature-sensitive pharmaceutical and food sector requirements across Northern Europe.
EU Green Deal emissions mandates and the F-Gas Regulation are reshaping fleet procurement criteria, while Germany's KBA enforces axle-weight and safety standards that filter chassis specifications across member state operations. REACH compliance requirements for lubricants and hydraulic fluids add chemical management burdens to maintenance protocols. Stakeholders must monitor how the EU AI Act's deployment rules for autonomous yard tractors will restructure labor models at major European container terminals.
Market Dynamics
EU Green Deal emissions mandates are forcing fleet operators to accelerate electrification timelines while Rotterdam, Hamburg and Antwerp-Bruges port authorities impose congestion pricing that compresses drayage margins. The collision between decarbonization capital requirements and throughput velocity demands is restructuring operator economics across Northern European corridors.
Growth Catalysts
- EU Green Deal fleet mandates:Binding CO2 reduction targets for heavy-duty vehicles are pulling forward investment in battery-electric and hydrogen fuel cell tractor units across German and Dutch port hinterlands.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution from Belgian and Irish manufacturing clusters is expanding reefer container movements through Rotterdam and Antwerp-Bruges.
- Rhine corridor rail electrification:Completed infrastructure upgrades along the Rotterdam-Genoa corridor are shifting container volumes from road to intermodal drayage at German and Swiss inland terminals.
Market Restraints
- Driver labor scarcity:Germany's KBA enforcement of stricter rest-period regulations and aging workforce demographics are constraining available operating hours across the EU.
- Battery cost volatility:Lithium and cobalt price fluctuations are inflating electric tractor unit total cost of ownership calculations beyond diesel parity timelines.
- Port gate congestion:Concentrated throughput at Rotterdam and Hamburg is creating systematic dwell time penalties that erode per-move economics for independent operators.
Strategic Opportunities
- Polish intermodal penetration:Underdeveloped rail-road terminal infrastructure around Gdansk and Warsaw offers first-mover positioning as manufacturing relocates from Asia.
- EU AI Act autonomous yard deployment:Regulatory clarity on unmanned terminal tractor operations creates pathway to labor cost reduction at major container facilities.
- Reefer telematics convergence:Integration of IoT sensors with blockchain documentation is opening premium service tiers for pharmaceutical and food sector clients.
Industry Challenges
- Technician skill gaps:High-voltage electric drivetrain maintenance requires retraining programs that outpace current vocational pipeline output in Germany and the Netherlands.
- Charging infrastructure capex:Megawatt-capable depot charging installations demand capital allocations that strain mid-size operator balance sheets.
- REACH chemical compliance:Lubricant and hydraulic fluid documentation requirements are extending maintenance protocol complexity across multi-country fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Container Drayage Market |
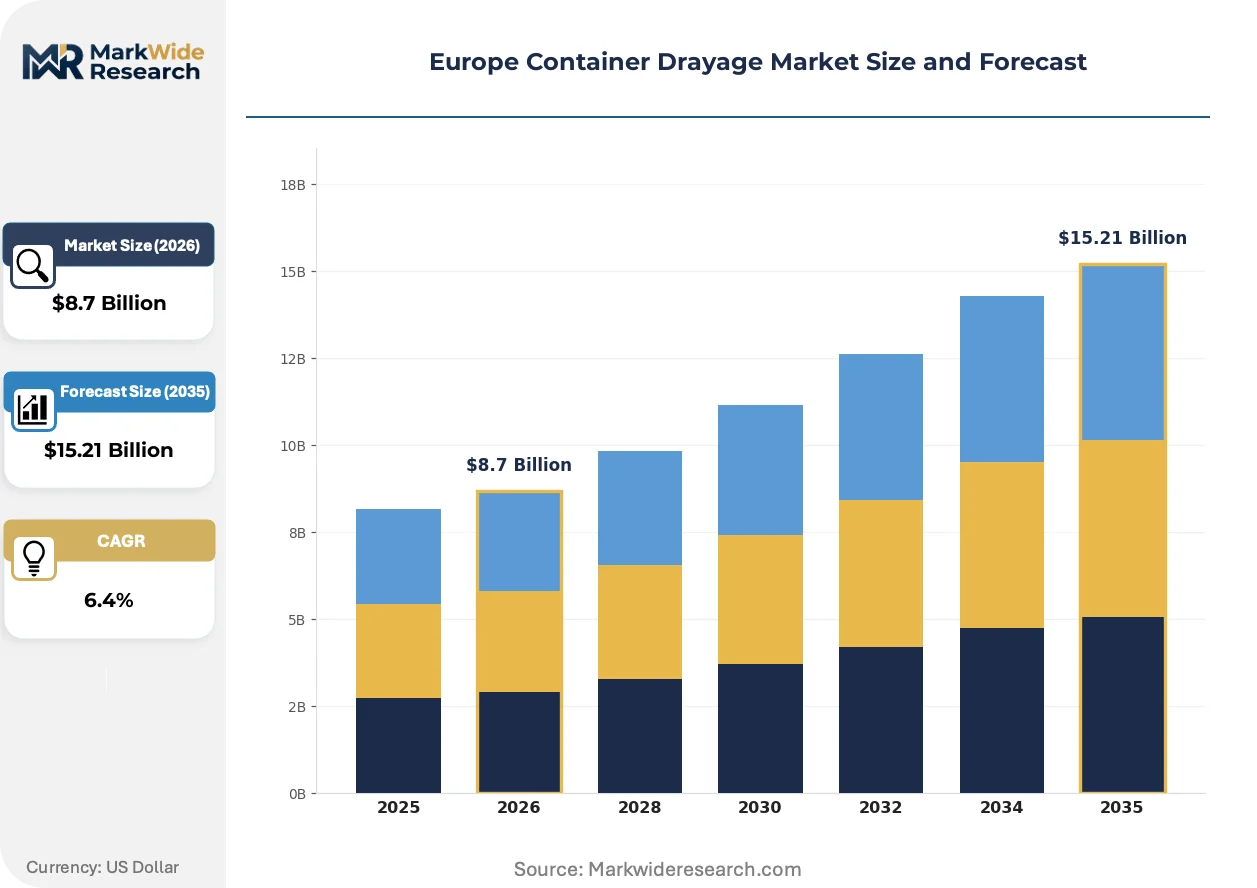
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Port Drayage, Rail Drayage, Long-Haul Drayage, Intermodal Drayage Container Type: Flat Rack, Open Top, Refrigerated, Standard Operation Mode: Transloading, Direct Delivery, Cross-Docking, Scheduled Routing Client Type: Shipping Lines, Freight Forwarders, OEMs, Retailers |
| Companies Covered | DHL, DB Schenker, Kuehne + Nagel, Maersk Line, CMA CGM, MSC (Mediterranean Shipping Company), Hapag-Lloyd, COSCO Shipping, Evergreen Marine, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Container Drayage Market Trends and Innovations
Battery-electric terminal tractors are overtaking diesel units in European port procurement specifications. Digital freight matching platforms are compressing contract structures. Regulatory pressure on scope emissions is reshaping asset ownership models.
Heavy-duty battery-electric tractors with 350kWh-plus packs are overtaking diesel equivalents in Rotterdam and Hamburg terminal procurement tenders. Food retailers and pharmaceutical distributors are specifying zero-emission last-mile drayage in vendor scorecards. This technology compression is enabling 24-hour continuous yard operations previously limited by diesel idling restrictions and noise ordinances.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in transport refrigeration units by 2030. Reefer container operators must retrofit or replace cooling systems with CO2 or ammonia-based alternatives. Pharmaceutical cold chain providers in Belgium and the Netherlands are accelerating equipment refresh cycles to maintain temperature compliance under stricter leakage monitoring rules.
Shippers are unbundling long-term exclusive drayage contracts in favor of spot-market platform access with pre-qualified carrier pools. Dutch and German retailers are driving this fragmentation to secure surge capacity during peak e-commerce windows. The shift is most visible in Antwerp-Bruges hinterland corridors where digital freight brokers now intermediate 30% of container moves.
Europe Container Drayage Market Segmentation
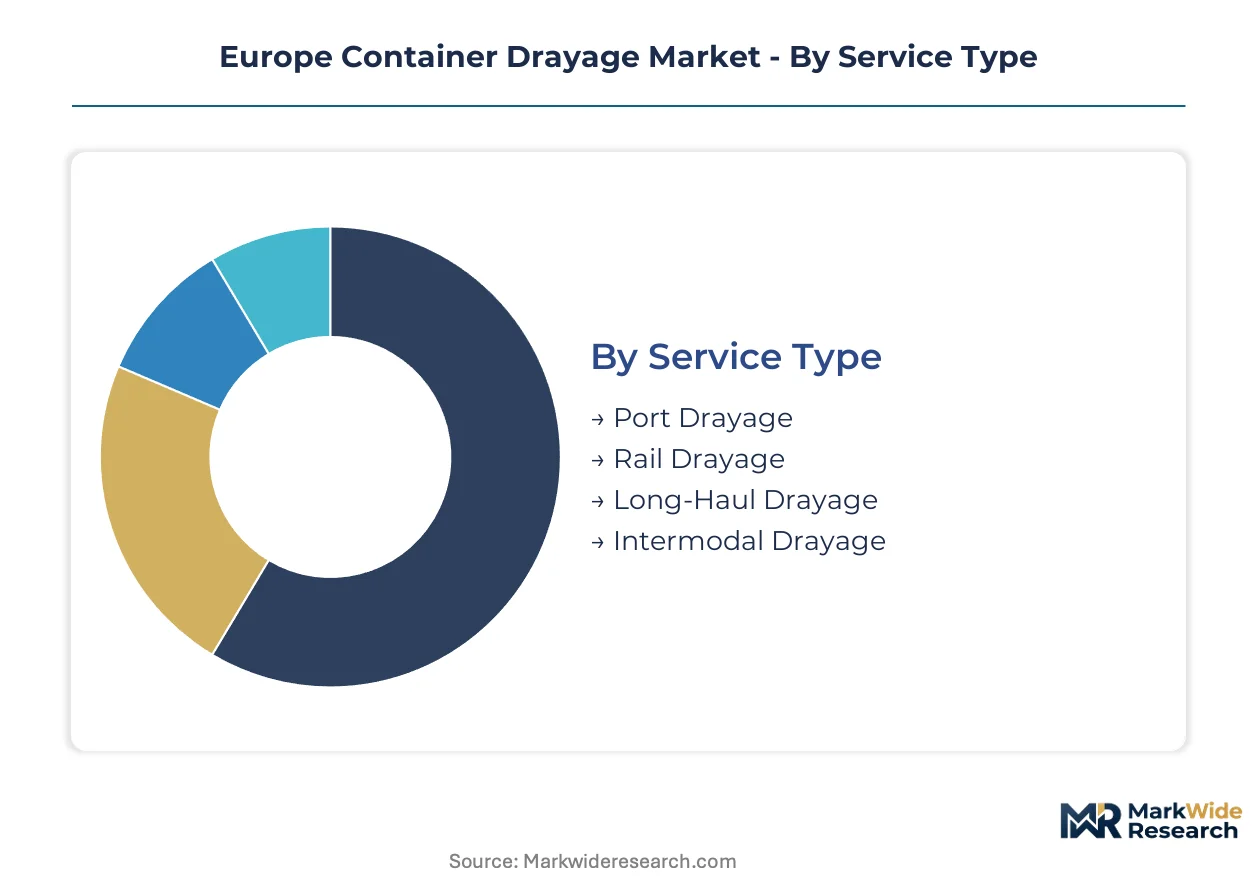
Container drayage segmentation reveals how service specialization maps to infrastructure constraints across European corridors. Distinct operational models command different margin profiles and capital requirements depending on port proximity and cargo characteristics.
Service Type:
Supply concentration at Rotterdam, Hamburg and Antwerp-Bruges determines which service types capture volume leverage versus margin premiums.
- Port Drayage:Short-haul movements under 50 kilometers connecting maritime terminals to inland distribution parks. Rotterdam and Hamburg throughput volumes anchor continental revenue concentration, though congestion pricing is compressing per-move economics for independent operators.
- Intermodal Drayage:Rail-road coordination at inland terminals along electrified corridors. Rhine-Alpine infrastructure investments are shifting container volumes from road to intermodal handoffs at German and Swiss railheads, expanding structural share fastest across Northern Europe.
- Rail Drayage:First-mile container positioning between vessel berths and marshalling yards. Antwerp-Bruges and Bremerhaven operators leverage this segment to bypass road congestion during peak vessel windows.
- Long-Haul Drayage:Extended road movements exceeding 100 kilometers when rail connectivity gaps persist. Polish and Baltic state corridors rely on this mode where intermodal terminal density remains underdeveloped.
Today's leader: Port Drayage. Tomorrow's challenger: Intermodal Drayage.
Container Type:
Cost tier differentiation separates commodity box handling from temperature-controlled premium services requiring specialized chassis and monitoring infrastructure.
- Refrigerated:Temperature-controlled units for pharmaceutical and food sector cargo. Belgian biologics manufacturing clusters and Dutch food distribution networks drive reefer demand through Antwerp-Bruges and Rotterdam, with EU F-Gas Regulation mandates accelerating equipment refresh cycles.
- Standard:Dry cargo containers representing baseline volume throughput. German retail fulfillment networks and e-commerce distribution centers across the Rhine corridor generate consistent demand for standard box movements.
- Flat Rack:Collapsible platforms for oversized industrial cargo. Heavy machinery exports from German manufacturing regions utilize this type for out-of-gauge loads.
- Open Top:Removable-roof containers for top-loading cargo. Scandinavian timber and bulk material flows through Baltic ports employ this configuration seasonally.
Refrigerated commands margin premiums. Standard handles volume scale.
Operation Mode:
Customer type preferences are fragmenting contract structures toward platform-mediated flexibility rather than long-term exclusivity.
- Direct Delivery:Point-to-point container movement without intermediate handling. Pharmaceutical distributors in Belgium and the Netherlands specify this mode for temperature integrity compliance.
- Scheduled Routing:Fixed-timetable services aligning with vessel arrival windows. German automotive supply chains rely on this predictability for just-in-sequence production feeds.
- Transloading:Cargo transfer between container and domestic equipment. Polish retail distribution centers use this mode to consolidate Asian imports into regional truckloads.
- Cross-Docking:Minimal-dwell sorting at intermediate facilities. Dutch e-commerce fulfillment networks leverage this for rapid inventory velocity during peak seasonal windows.
Scheduled Routing anchors reliability premiums. Cross-Docking enables surge elasticity.
Client Type:
Procurement authority is concentrating among integrated logistics providers seeking captive drayage capacity.
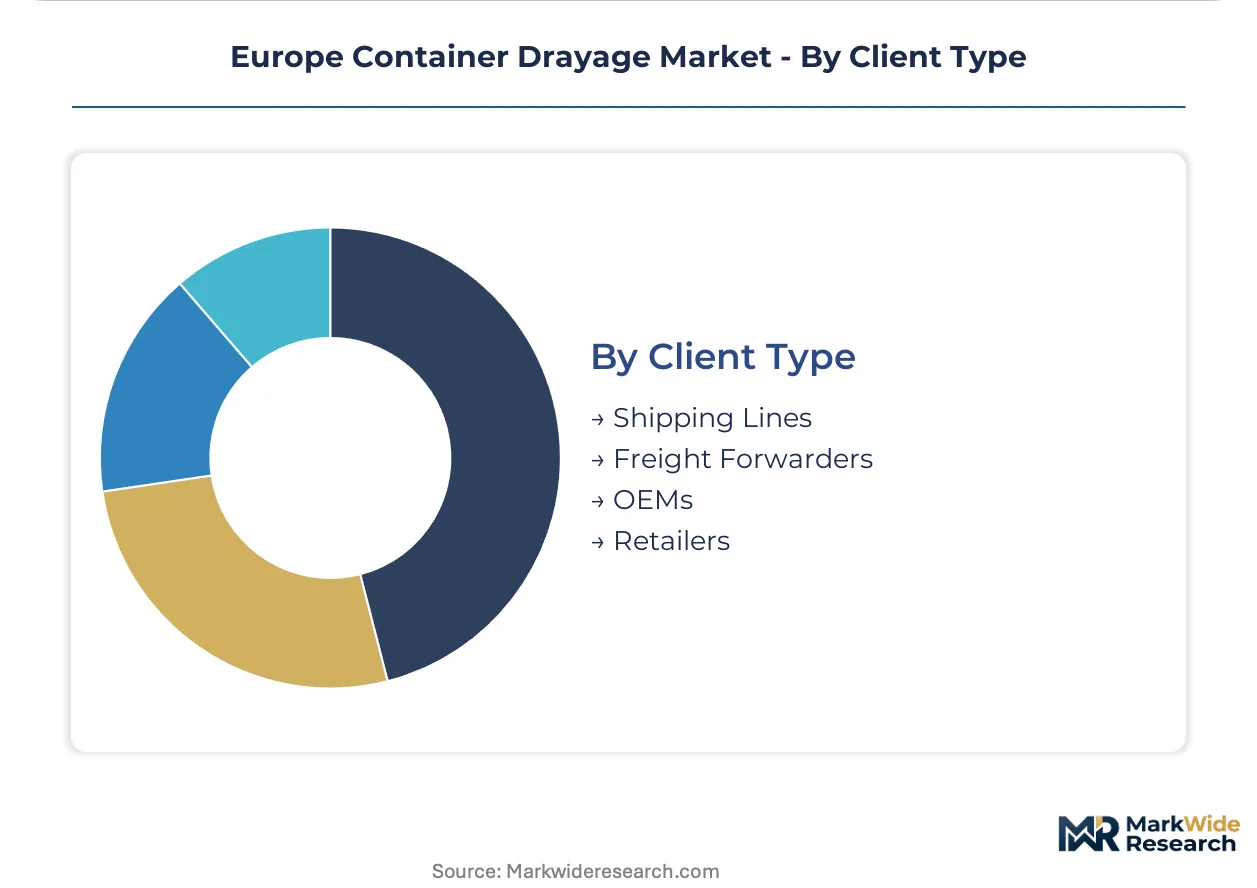
- Freight Forwarders:Intermediaries bundling drayage into multimodal service packages. German and Dutch forwarders are unbundling long-term contracts in favor of spot-market platform access with pre-qualified carrier pools.
- Shipping Lines:Ocean carriers extending terminal-operating footprints into hinterland services. Maersk and Mediterranean Shipping Company vertical integration strategies reduce third-party drayage dependency at Rotterdam and Hamburg.
- Retailers:Large-format merchants with private fleet requirements. French and German food retailers are specifying zero-emission last-mile drayage in vendor scorecards under scope emissions pressure.
- OEMs:Original equipment manufacturers with component container flows. German automotive producers coordinate inbound parts movements through dedicated drayage arrangements.
Freight Forwarders intermediate volume. Shipping Lines capture integration margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward Poland and the Baltic states, where EU Green Deal compliance costs remain below German and Dutch levels. Container drayage demand follows this production migration, with Polish intermodal terminals capturing volumes that previously flowed through Rhine corridor gateways.
Germany
Automotive component flows from Bavarian manufacturing clusters and pharmaceutical distribution from the Rhine-Main region sustain dense drayage networks around Hamburg and Bremerhaven. The KBA enforces axle-weight limits and driver rest-period regulations that constrain fleet utilization rates. DB Schenker coordinates intermodal handoffs at Duisburg and Mannheim inland terminals, shifting container volumes from road to rail along electrified corridors.
Netherlands
Rotterdam port throughput and Dutch food distribution networks generate consistent reefer container movements through the Randstad logistics belt. EU F-Gas Regulation mandates are accelerating cooling system retrofits for pharmaceutical cold chain operators based near Schiphol. Digital freight platforms now intermediate roughly one-third of Antwerp-Bruges hinterland moves as retailers unbundle long-term contracts.
Belgium
Biologics manufacturing clusters around Antwerp and Ghent drive temperature-controlled container demand through Antwerp-Bruges terminals. REACH compliance requirements for lubricants and hydraulic fluids extend maintenance protocol complexity across multi-country fleets serving Belgian pharma distributors. Reefer telematics integration with blockchain documentation is opening premium service tiers for cold chain clients.
Poland
Manufacturing relocation from Asia is concentrating container imports through Gdansk port, where underdeveloped rail-road terminal infrastructure creates first-mover opportunities. The Polish central government has allocated cohesion funds to inland terminal construction along the Warsaw-Lodz corridor. Independent operators are expanding long-haul drayage capacity where intermodal density remains insufficient for rail competition.
United Kingdom
Post-Brexit customs complexity has fragmented container flows between UK ports and EU inland terminals, extending dwell times at Felixstowe and Southampton. The UK's departure from EU regulatory alignment is creating parallel compliance regimes for cross-border drayage operators. London and Southeast distribution centers rely on scheduled routing services to maintain inventory velocity amid border processing delays.
Europe Container Drayage Market Competitive Landscape
Established logistics providers occupy the standard tier; emerging platform entrants pursue spot-market intermediation and digital freight matching. The market structure consolidates around integrated multimodal operators with captive terminal access, while independent drayage contractors face margin compression from congestion pricing and electrification capital requirements. Three archetypes dominate: ocean carrier vertical integration strategies, forwarder control tower platforms, and asset-heavy regional specialists. Competitive positioning depends on securing port terminal operating agreements and deploying battery-electric tractor units ahead of EU Green Deal enforcement timelines.
Among Germany-based integrated logistics groups, DB Schenker exemplifies the rail-road network archetype, leveraging Rhine-Alpine corridor infrastructure to capture intermodal volumes. Kuehne + Nagel, a Swiss forwarder, occupies a position within the control tower visibility tier, anchoring drayage coordination through proprietary digital platforms. Maersk Line represents ocean carrier backward integration, extending terminal-operating footprints into captive hinterland services to reduce third-party dependency at Rotterdam and Hamburg.
| Leading Market Players |
|---|
| DHL |
| DB Schenker |
| Kuehne + Nagel |
| Maersk Line |
| CMA CGM |
| MSC (Mediterranean Shipping Company) |
| Hapag-Lloyd |
| COSCO Shipping |
| Evergreen Marine |
| Others |
Pricing and Supply Chain Analysis
Certified electric-drivetrain technicians concentrated in Germany's Rhine-Ruhr industrial belt command wage premiums that widen pricing spreads between premium fleet operators and independent contractors. Labor-cost differentials between electrified incumbent fleets and diesel-dependent independents are compressing margins in Rotterdam and Hamburg corridors under EU Green Deal enforcement.
Pricing Analysis
Distributor margin layers for chassis-mounted tractor units separate OEM-direct procurement from dealer-mediated fleet sales. Three-tier pricing structure across premium electrified, standard diesel, and economy used-equipment levels reflects battery-pack capacity and telematics integration depth. Cost compression in the economy tier is intensifying because Polish and Baltic operators undercut German rates for long-haul drayage. Retailers with scope-emissions mandates show least price sensitivity; independent freight forwarders exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements for battery-electric tractor units mandate qualification of both German and Chinese cell suppliers across major fleet procurement tenders. Geographic supply concentration centers on Germany for chassis assembly, China for lithium-ion cells, and the Netherlands for charging infrastructure components. Raw material dependencies draw from cobalt, lithium carbonate, and high-grade steel. Single-source vulnerability sits with semiconductor-based motor controllers. Distribution runs through manufacturer-authorized service networks with captive parts warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal fleet mandates pull forward capital deployment timelines and reshape competitive viability thresholds.
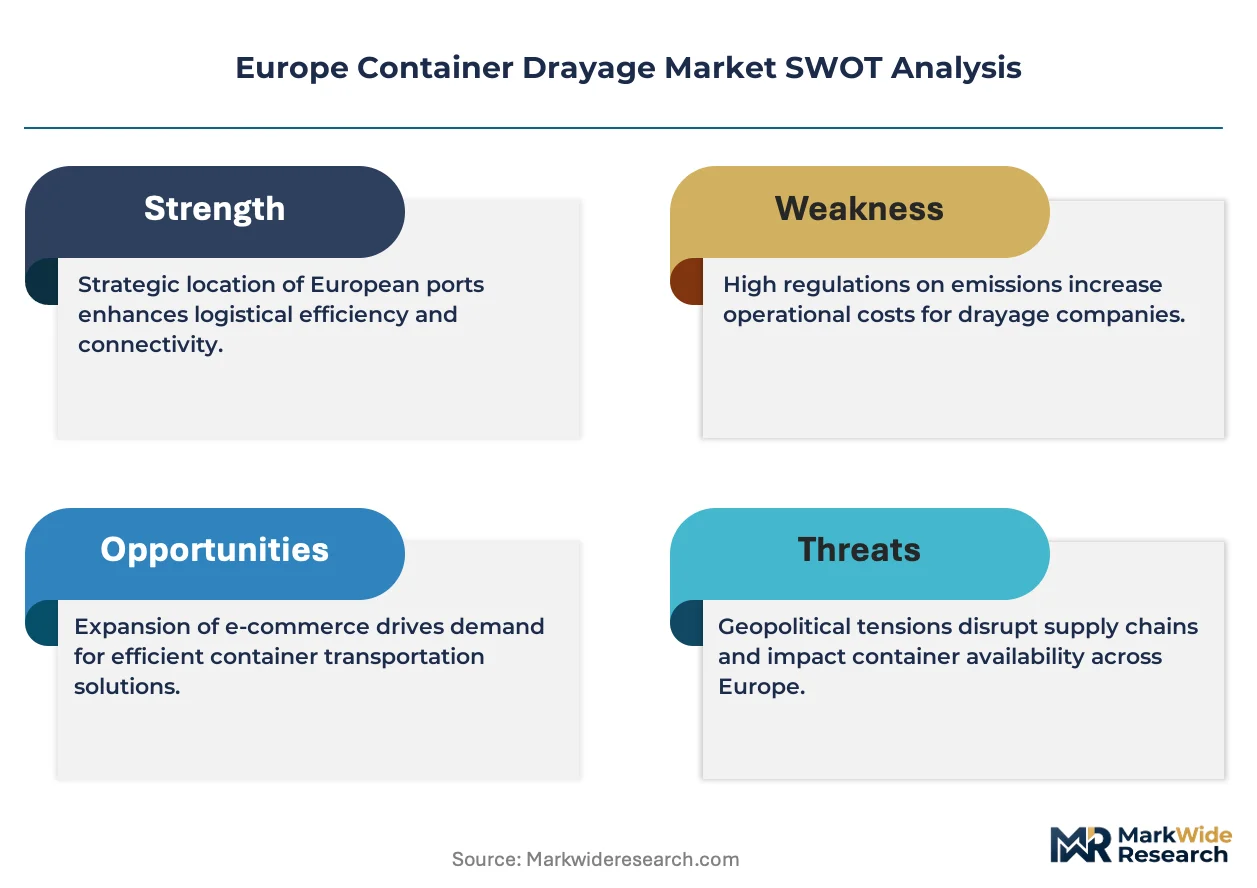
For Market Incumbents: Anchor market position through accelerated electrification of terminal tractor fleets ahead of binding CO2 enforcement windows. Secure exclusive operating agreements at Rotterdam and Hamburg port terminals to lock in throughput volumes. Defend against digital freight platform disintermediation by integrating proprietary visibility tools with customer ERP systems. For New Entrants and Emerging Players: Begin with underdeveloped Polish intermodal corridors where rail-road terminal density remains insufficient for incumbent saturation. Target pharmaceutical cold chain segments in Belgian biologics clusters where temperature-compliance specialization commands premium positioning. Pursue telematics-enabled reefer monitoring as a differentiated service tier for Dutch food distribution networks. For Investors and Strategic Acquirers: Ocean carriers extending terminal-operating footprints into captive hinterland services represent the most active acquirer category in this space. Long-term viability over the coming decade hinges on securing port terminal operating agreements and deploying battery-electric assets ahead of regulatory deadlines. Watch for inflection in EU AI Act autonomous yard tractor deployment rules as a signal for labor-cost restructuring opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Procurement | EU Green Deal CO2 mandates pull forward battery-electric tractor investment timelines across German and Dutch port hinterlands. |
| Terminal Operating Agreement | Exclusive access at Rotterdam and Hamburg locks in throughput volumes against digital platform intermediation. |
| Reefer Telematics Integration | IoT sensor convergence with blockchain documentation opens premium service tiers for Belgian pharmaceutical cold chain clients. |
| Polish Intermodal Expansion | Cohesion-funded inland terminal construction along Warsaw-Lodz corridor captures manufacturing relocation volumes from Asia. |
| Autonomous Yard Deployment | EU AI Act regulatory clarity on unmanned terminal tractors creates pathway to labor cost reduction at major European container facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations managers, port authority procurement leads, chassis OEM sales directors, and intermodal terminal planners with secondary validation. Primary sources drew from EU Green Deal implementation guidance, KBA enforcement bulletins, port authority throughput disclosures, and REACH compliance documentation. Secondary data sources included customs trade flows, ECHA chemical registration databases, EU transport infrastructure investment reports, and SEC filings from listed logistics groups. Bottom-up vessel call volumes and top-down corridor flow estimates underwent cross-triangulation.
Comparable historical periods anchored the projection horizon to pre-pandemic baseline throughput and post-2022 electrification investment cycles. Segmentation modeling spanned service type, container temperature requirements, operation mode, and client procurement authority across the analysis window. CAGRs derived from volume-flow projections calibrated to port capacity expansion timelines and rail electrification completion schedules. Forecast inputs incorporated battery cost learning curves and EU F-Gas Regulation equipment refresh assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to Baltic container flows, abrupt lithium supply chain fracture, and unilateral member state deviation from EU Green Deal enforcement timelines. Forecasts reflect documented assumptions regarding fleet electrification adoption curves and port congestion pricing permanence. Deviation in EU AI Act autonomous deployment authorization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market