
 Germany Luxury Jewelry Market | 2026-2036
Germany Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Luxury Jewelry Market Insights
The gap between artisanal haute joaillerie and mass-luxury collections is expanding as German consumers sharpen their preference for provenance and craftsmanship over logo recognition. Chopard Deutschland GmbH leverages its vertically integrated Geneva atelier to control gemstone sourcing and finishing standards for the German market. Wellendorff GmbH & Co KG anchors its position through proprietary cold enamel techniques developed at its Pforzheim manufacture. Hemmerle differentiates via museum-grade metalwork that reinterprets industrial materials into collectible art pieces.
Germany luxury jewelry denotes ornamentation crafted from precious metals and gemstones, typically achieving fineness levels of 18-karat gold or 950 platinum, employing hand-fabrication methods such as lost-wax casting, hand-engraving, and stone-setting under 10x magnification for wearable art and wealth preservation. Rings dominate transaction volume among German buyers seeking engagement and anniversary pieces, while necklaces command the highest per-unit margins due to complex metalwork and rare stone requirements. The collector segment within customer type categories is outpacing fashion enthusiasts as auction houses in Cologne and Berlin report stronger consignment flows for signed vintage pieces.
Germany's Federal Agency for Cartography (BKG) supports geographic indication frameworks, while the Hallmarking Act enforced by regional assay offices in Stuttgart and Hanau mandates purity stamps that shape consumer trust and cross-border resale value. The EU Conflict Minerals Regulation, transposed into German commercial law, requires supply chain due diligence that filters out uncertified gold sources and elevates transparently sourced platinum. Stakeholders must monitor how KBA documentation requirements for high-value goods transport intersect with evolving AML protocols from Germany's Financial Intelligence Unit.
Market Dynamics
German collectors now prioritize documented provenance over brand heritage, compressing margins for logo-dependent houses while rewarding ateliers with captive gemstone sourcing and in-house fabrication capabilities.
Growth Catalysts
- Edelmetallkontrollgesetz Purity Mandates:Strict certification requirements under Germany's Precious Metals Control Ordinance elevate consumer trust in domestically hallmarked pieces, driving demand toward Stuttgart and Hanau assay office jurisdictions.
- Bavarian Collector Density:Affluent households in Munich and surrounding Alpine regions concentrate acquisition of bespoke platinum commissions, sustaining atelier order books through direct patronage relationships.
- Cold Enamel Technique Proliferation:Proprietary vitreous enamel methods developed in Pforzheim manufacturing clusters differentiate regional output against standardized international collections.
Market Restraints
- Platinum Supply Concentration:Russian and South African mine concentration exposes German fabricators to geopolitical disruption in primary platinum group metal flows.
- EU Conflict Minerals Due Diligence:Supply chain documentation burdens under transposed commercial law filter out uncertified gold sources, constraining raw material procurement flexibility.
- Artisan Talent Scarcity:Master stone-setters and hand-engravers require decade-long apprenticeships, limiting atelier expansion velocity regardless of capital availability.
Strategic Opportunities
- Baden-Württemberg Manufacturing Corridors:Underutilized precision metalworking infrastructure from automotive supplier networks offers conversion potential for jewelry-scale production.
- KBA High-Value Transport Documentation:Streamlined customs protocols for authenticated luxury goods create competitive advantage in cross-border consignment to Swiss and Austrian collectors.
- Blockchain Provenance Integration:Distributed ledger verification of gemstone origin and ownership history converges with existing Hallmarking Act frameworks to create tamper-resistant certification.
Industry Challenges
- Master Craftsman Pipeline Collapse:Pforzheim and Hanau technical schools report declining enrollment in traditional jewelry fabrication programs, threatening generational knowledge transfer.
- AML Protocol Intersection:Germany's Financial Intelligence Unit documentation requirements for high-value transactions conflict with established client privacy expectations in private sales channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Luxury Jewelry Market |
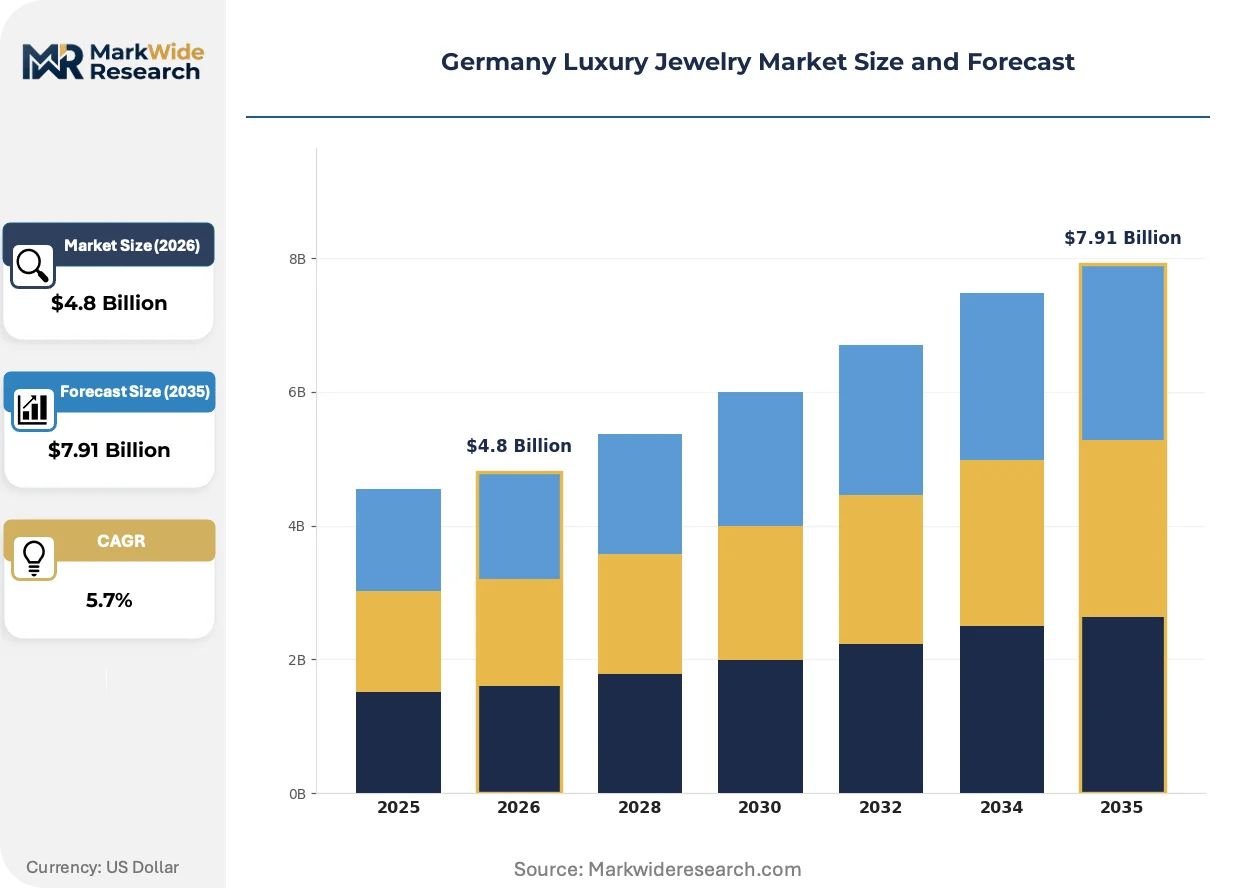
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Bracelets, Earrings, Rings Material: Gold, Platinum, Silver, Diamonds Customer Type: Affluent Consumers, Collectors, Gift Buyers, Fashion Enthusiasts Distribution Channel: Online Retail, Luxury Boutiques, Department Stores, Auctions |
| Companies Covered | Chopard Deutschland GmbH, Louis Vuitton Deutschland GmbH, Wellendorff GmbH & Co KG, Hemmerle, Thomas Sabo GmbH & Co Schmuckhandel KG, Gerhard D Wempe KG, Swarovski (Deutschland) GmbH, Stenzhorn, Cartier SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Luxury Jewelry Market Trends and Innovations
Digital provenance verification and parametric design tools are compressing the traditional gap between collector specification and atelier execution, reshaping how German luxury jewelry moves from commission to delivery.
Laser-assisted stone setting is overtaking traditional hand-pushed techniques in Pforzheim manufacturing clusters. Mid-tier ateliers serving anniversary and engagement segments adopt fiber-laser systems to achieve micron-precision placement previously reserved for haute joaillerie houses. This capability compression enables smaller fabricators to bid on museum-quality commissions without decade-long apprenticeship investments.
Germany's Federal Agency for Cartography supports geographic indication frameworks that protect regional manufacturing designations. The Hallmarking Act enforcement by Stuttgart and Hanau regional assay offices now incorporates digital registry cross-referencing, tightening documentation standards for pieces claiming Pforzheim or Idar-Oberstein origin. Collector segments in Munich and Frankfurt luxury corridors increasingly demand assay office verification as a prerequisite for acquisition.
Direct atelier relationships are displacing multi-brand retail intermediaries among serious German collectors. Auction houses in Cologne and Berlin report stronger consignment flows for pieces with documented single-origin fabrication, while Maximilianstrasse and Goethestrasse showrooms face pressure to demonstrate maker proximity. This channel compression concentrates margin capture with vertically integrated houses possessing captive manufacturing in Baden-Württemberg or Bavaria.
Germany Luxury Jewelry Market Segmentation
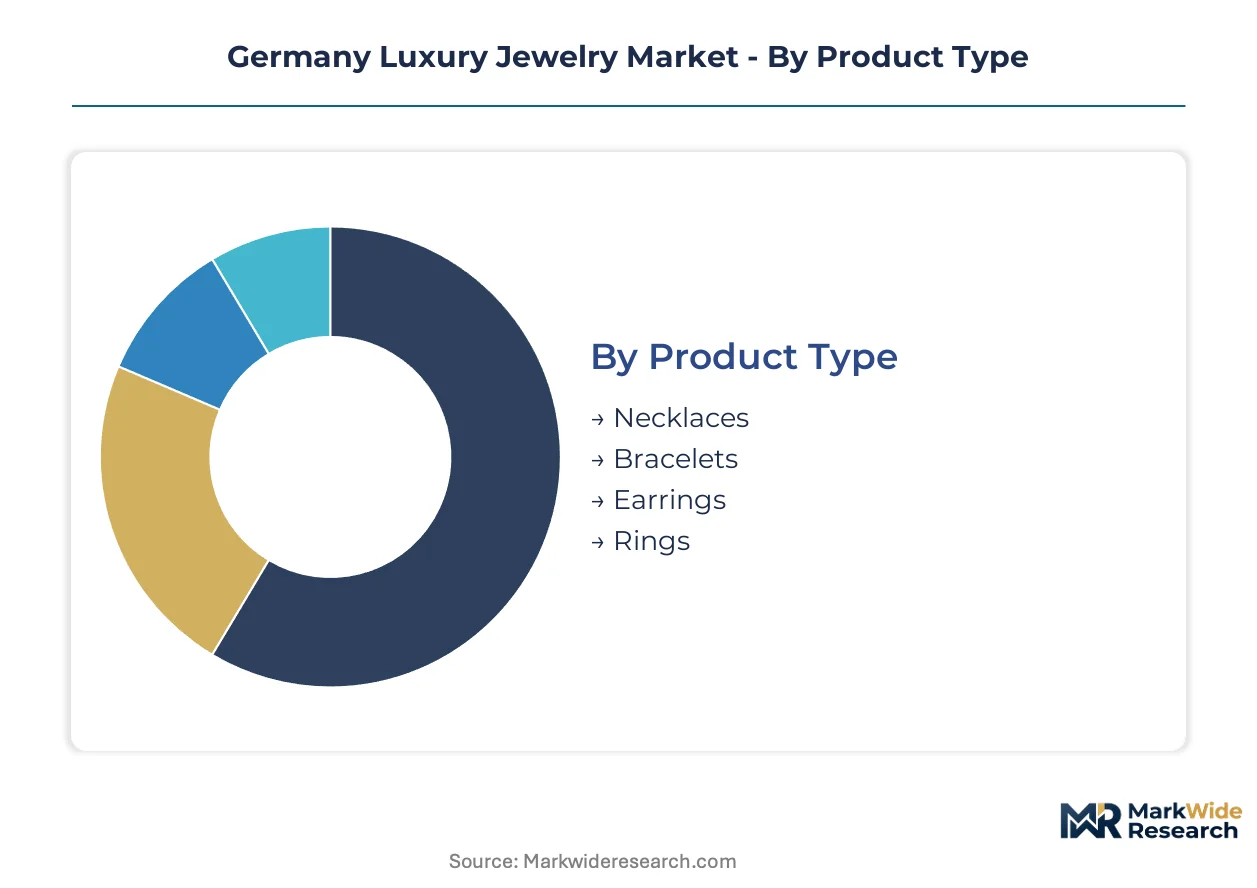
German luxury jewelry segmentation reveals how purity mandates and provenance documentation reshape purchase decisions across distinct buyer profiles. Material certification and fabrication origin now outweigh brand recognition in collector prioritization.
Product Type:
German buyers select formats based on occasion specificity and metalwork complexity requirements.
- Rings:Engagement and anniversary commissions dominate transaction volume, with platinum bands commanding premium positioning in Munich's Maximilianstrasse ateliers. Bavarian collectors drive demand for bespoke settings incorporating cold enamel accents from Pforzheim manufactures.
- Necklaces:Complex metalwork and rare stone requirements generate the highest per-unit margins. Frankfurt's Goethestrasse luxury corridors concentrate demand for museum-grade pieces requiring 10x magnification stone-setting verification.
- Bracelets:Anniversary gifting sustains steady demand for articulated link constructions with assay office hallmarks from Stuttgart or Hanau.
- Earrings:Fashion-forward German consumers favor platinum studs with documented conflict-free diamond sourcing under EU Regulation compliance.
Rings lead on scale; necklaces lead on momentum.
Material:
Fineness thresholds and regulatory compliance determine material selection hierarchies in German fabrication.
- Platinum:950 fineness mandates under Edelmetallkontrollgesetz elevate consumer trust, with Baden-Württemberg ateliers specializing in bespoke commissions for affluent collectors seeking wealth preservation instruments.
- Gold:18-karat minimum standards dominate engagement segments, though EU Conflict Minerals Regulation documentation burdens constrain procurement flexibility for smaller fabricators.
- Diamonds:Certified origin documentation requirements filter supply chains toward transparently sourced stones, particularly for auction house consignments in Cologne and Berlin.
- Silver:Entry-tier positioning serves gift buyer segments with lower purity thresholds, though Hallmarking Act enforcement maintains quality floors.
Platinum leads on scale; diamonds lead on momentum.
Customer Type:
Acquisition sophistication varies sharply across buyer knowledge levels and relationship depth with fabrication sources.
- Collectors:Documented provenance demands compress margins for logo-dependent houses while rewarding vertically integrated ateliers with captive gemstone sourcing. Auction house consignment flows strengthen for signed vintage pieces with single-origin fabrication records.
- Affluent Consumers:Direct atelier relationships displace multi-brand retail intermediaries, concentrating margin capture with Baden-Württemberg and Bavarian manufacturers.
- Gift Buyers:Occasion-driven purchases prioritize assay office verification as trust signal, particularly for pieces claiming Pforzheim or Idar-Oberstein geographic indications.
- Fashion Enthusiasts:Style-focused acquisition favors accessible price points, though digital provenance verification tools increasingly influence selection criteria.
Collectors lead on scale; affluent consumers lead on momentum.
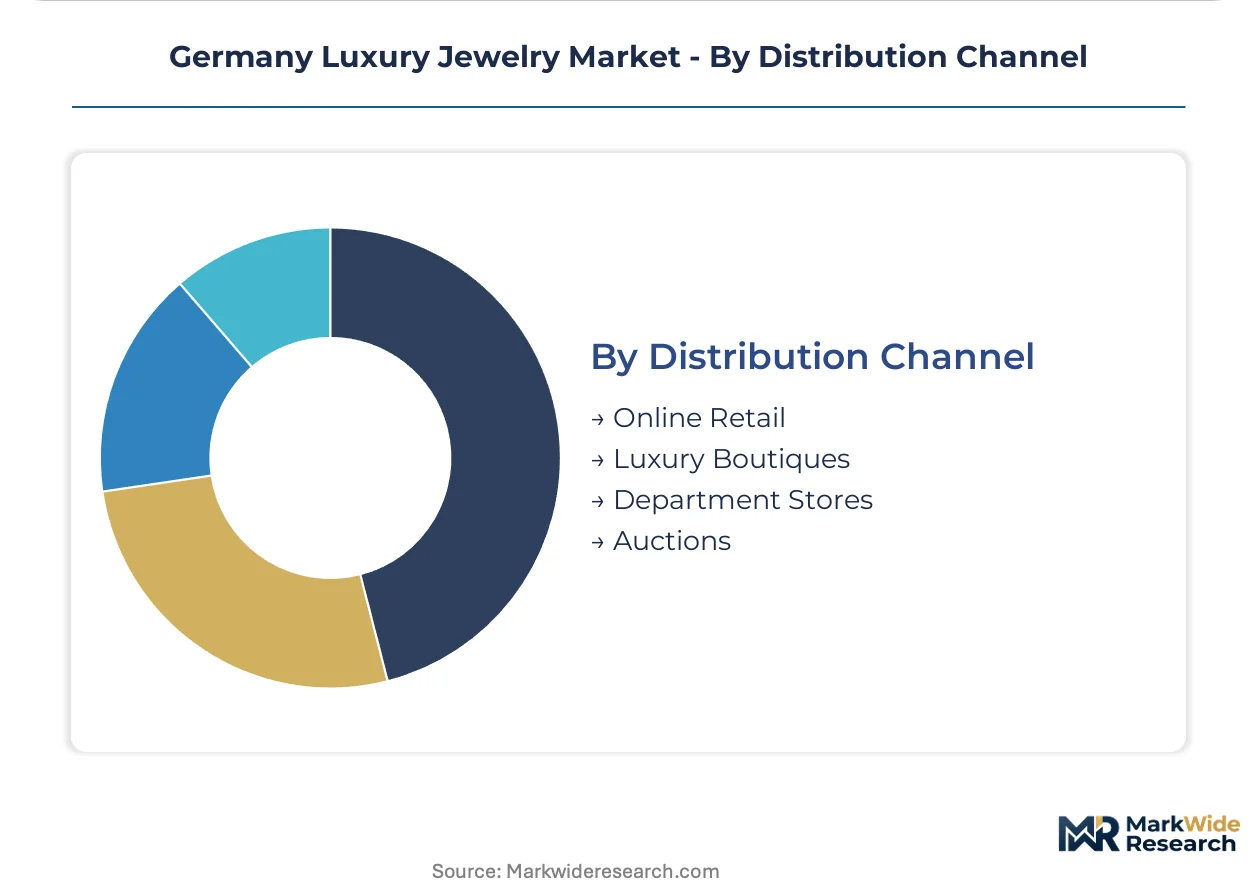
Distribution Channel:
Channel selection reflects buyer risk tolerance and documentation requirements for high-value transactions.
- Luxury Boutiques:Maximilianstrasse and Goethestrasse showrooms face pressure to demonstrate maker proximity, with direct atelier relationships displacing intermediaries among serious collectors.
- Auctions:Cologne and Berlin auction houses report stronger consignment flows for pieces with documented fabrication provenance, particularly from Pforzheim cold enamel specialists.
- Online Retail:Digital provenance verification and blockchain integration expand reach, though KBA documentation requirements for high-value goods transport create compliance complexity.
- Department Stores:Multi-brand aggregation serves gift buyer segments, though margin compression limits representation from top-tier ateliers with captive manufacturing.
Luxury boutiques lead on scale; auctions lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates haute joaillerie heritage while Germany commands precision fabrication, creating divergent competitive postures across European luxury jewelry. Swiss ateliers leverage cross-border logistics to serve collectors in both markets. Italian manufacturers anchor Mediterranean styling preferences with distinct alloy traditions.
France
Parisian Place Vendôme houses anchor global auction premiums for signed vintage pieces. ANSM oversees precious metals compliance through hallmarking protocols that predate EU harmonization. Lyon and Saint-Etienne manufacturing clusters supply chain infrastructure for Rhône-Alpes ateliers specializing in Art Deco revival commissions.
Switzerland
Geneva-based fabrication commands collector premiums through vertically integrated gemstone sourcing. Swissmedic-adjacent customs frameworks streamline high-value transport documentation for cross-border consignment to German collectors. Basel and Zurich showrooms concentrate private client relationships for Alpine-region wealth preservation buyers.
Italy
Milan's Via Monte Napoleone corridors sustain demand for statement gold pieces with documented Valenza Po provenance. CE marking requirements intersect with regional assay traditions from Alessandria province. Vicenza and Arezzo manufacturing districts export finished jewelry through established logistics corridors serving Central European retail networks.
United Kingdom
London's Bond Street auction houses report strengthened consignment flows for German-fabricated pieces with Pforzheim hallmarks. FCA oversight of high-value goods transactions shapes documentation standards that influence EU-wide AML protocol development. Birmingham's Jewellery Quarter maintains historical assay capacity supporting cross-border certification recognition.
Austria
Vienna's Kärntner Strasse luxury corridor channels Alpine collector demand toward Baden-Württemberg ateliers with streamlined KBA transport documentation. National precious metals control ordinances align with German Edelmetallkontrollgesetz standards, reducing cross-border compliance friction. Salzburg and Innsbruck private banking relationships facilitate direct atelier patronage for bespoke platinum commissions.
Germany Luxury Jewelry Market Competitive Landscape
Top-tier vendors anchor provenance-driven positioning, while mid-tier fabricators compete on manufacturing efficiency and regional hallmark recognition. The vendor base stratifies across Geneva-integrated houses, Pforzheim-specialist ateliers, and multi-brand retail aggregators with varying captive production depth. Strategic archetypes include vertically integrated heritage manufacturers, precision-engineering specialists leveraging automotive supplier networks, and auction-house-aligned provenance curators. Dominant competitive moves encompass backward integration into gemstone sourcing and direct-to-collector channel development displacing traditional retail intermediaries.
Among Germany-based fabricators, Wellendorff GmbH & Co KG and Hemmerle occupy positions within the precision-specialist archetype, while Chopard Deutschland GmbH represents the Geneva-integrated tier with captive manufacturing advantages. These entities exemplify how regional assay office proximity and cold enamel technique development create defensible positioning against logo-dependent international houses. Thomas Sabo GmbH & Co Schmuckhandel KG sits within the accessible-luxury segment, demonstrating how Pforzheim manufacturing heritage translates across price-tier diversification.
| Leading Market Players |
|---|
| Chopard Deutschland GmbH |
| Louis Vuitton Deutschland GmbH |
| Wellendorff GmbH & Co KG |
| Hemmerle |
| Thomas Sabo GmbH & Co Schmuckhandel KG |
| Gerhard D Wempe KG |
| Swarovski (Deutschland) GmbH |
| Stenzhorn |
| Cartier SA |
| Others |
Pricing and Supply Chain Analysis
EU Conflict Minerals Regulation compliance gates both qualified raw material supply and premium-tier pricing access for German fabricators, as documented provenance becomes the threshold for entry into collector-grade segments while uncertified sources face automatic disqualification from Stuttgart and Hanau assay office jurisdictions.
Pricing Analysis
Capacity additions in Baden-Württemberg precision metalworking corridors are reshaping price floors for mid-tier fabrication, compressing margins for standardized 18-karat gold pieces while three-tier pricing structure across premium, standard, and economy levels stratifies around certification depth and atelier proximity. Price differentiation hinges on Hallmarking Act verification tier and captive gemstone sourcing capability. Pricing pressure stems from Russian and South African platinum supply concentration exposing fabricators to input cost volatility. Gift buyers exhibit highest price sensitivity, while collectors prioritize provenance documentation over absolute cost.
Supply Chain Analysis
Platinum group metal supply rests on South African and Russian mine concentration, with German fabricators drawing from Swiss-refined secondary sources and Geneva-integrated atelier networks for gemstone procurement. Raw material dependencies center on 950-fineness platinum feedstock, certified conflict-free gold, and Idar-Oberstein cut stones. Single-source vulnerability in primary platinum flows creates structural exposure to geopolitical disruption. Distribution runs through direct atelier relationships displacing multi-brand retail intermediaries, with KBA documentation enabling cross-border consignment to Austrian and Swiss collectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany luxury jewelry functions as a stable compounder anchored by generational wealth preservation demand from Bavarian and Baden-Württemberg collector households, with regulatory certification requirements creating durable barriers that sustain incumbent positioning.
For Market Incumbents: Anchor market position through backward integration into Pforzheim cold enamel manufacturing clusters and captive gemstone sourcing corridors, defending against precision-engineering specialists leveraging automotive supplier network conversions. Invest in blockchain provenance verification to preempt digital-native entrants. Certification depth under Edelmetallkontrollgesetz serves as the priority defensive lever. For New Entrants and Emerging Players: Direct-to-collector digital platforms offer the lowest-friction entry vector, enabling white-space penetration among fashion enthusiasts seeking accessible platinum pieces with transparent sourcing documentation. Target underdeveloped anniversary gifting segments in Frankfurt's Goethestrasse corridor through parametric design tools that compress commission-to-delivery timelines. Lead with digital provenance verification as the differentiated go-to-market anchor. For Investors and Strategic Acquirers: Roll-up economics work for Pforzheim-specialist ateliers with proprietary cold enamel techniques because generational knowledge transfer constraints limit organic replication capacity. Long-term viability centers on Baden-Württemberg manufacturing corridor consolidation over a multi-decade wealth transfer window. Acquisition focus should target mid-cap fabricators with Stuttgart assay office proximity and direct collector relationships. Watch master craftsman enrollment trends at Pforzheim technical schools as the inflection signal for supply-side constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Enamel Technique Acquisition | Proprietary Pforzheim vitreous enamel methods create defensible differentiation against standardized international collections. |
| Blockchain Provenance Integration | Distributed ledger verification converges with Hallmarking Act frameworks to create tamper-resistant certification for collectors. |
| Direct Atelier Channel Development | Maker-proximity relationships displace Maximilianstrasse retail intermediaries and concentrate margin capture. |
| Master Craftsman Apprenticeship Programs | Pforzheim and Hanau technical school partnerships address generational knowledge transfer collapse threatening expansion velocity. |
| KBA Documentation Streamlining | Optimized high-value goods transport protocols enable competitive cross-border consignment to Swiss and Austrian private banking clients. |
Research Methodology
Direct dialogue with atelier owners, master stone-setters, Stuttgart and Hanau assay office officials, luxury boutique category managers, and private banking wealth advisors in Munich and Frankfurt grounded qualitative findings, cross-referenced with Edelmetallkontrollgesetz regulatory filings, EU Conflict Minerals Regulation implementation reports, KBA transport documentation standards, auction house consignment records from Cologne and Berlin, and Pforzheim manufacturing cluster trade association data. Bottom-up fabrication capacity estimates and top-down collector spending patterns were triangulated for convergence.
Bottom-up modeling tracked atelier order books, platinum feedstock consumption, and assay office hallmark issuance across product type, material fineness, customer sophistication tier, and distribution channel. Top-down validation referenced wealth concentration metrics in Bavaria and Baden-Württemberg, cross-border trade flows, and auction house transaction volumes. CAGRs were derived from segmented growth rate reconciliation across the projection horizon, incorporating master craftsman pipeline constraints and regulatory compliance cost trajectories as industry-specific forecast inputs.
The model assumes a particular technology adoption path for laser-assisted stone setting; alternative pathways for hand-fabrication technique preservation would alter the outlook for atelier expansion velocity. Forecasts reflect assumptions regarding sustained collector preference for documented provenance over brand heritage, with platinum supply disruption, AML protocol tightening, and generational knowledge transfer collapse representing specific risk factors that could revise projections. A small set of triggers—master craftsman enrollment rates, KBA documentation requirement evolution, and Idar-Oberstein cutting house consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Europe Luxury Jewelry Market
Jewelry
Bead Products Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Luxury Jewelry Market
Jewelry
Customized Jewelry Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Body Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Latin America Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Leather Jewellery Box Market
Jewelry
China Luxury Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
Italy Luxury Jewelry Market