
 Luxury Jewelry Market | 2026-2036
Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Jewelry Market Intelligence
Gen Z and millennial collectors is redrawing demand architecture across the luxury jewelry landscape. Cartier leverages its heritage ateliers and vertical integration to command premium positioning in haute joaillerie. Tiffany & Co. anchors its competitive stance through diamond provenance traceability and direct retail channel control. Van Cleef & Arpels specializes in artisanal métiers and limited-production high jewelry that sustains scarcity value.
Luxury jewelry comprises precious-metal and gemstone adornments crafted to exacting specifications, typically employing 18-karat gold, platinum, or ethically graded diamonds with clarity ratings of VS1 and above, serving as wearable stores of value and cultural signifiers. Rings and necklaces occupy the largest revenue pools, though bracelets show accelerated momentum among male end users. Gold and platinum dominate material value, while gemstones command the widest margin spreads; auction houses capture the highest per-unit prices despite representing a thin volume slice.
The EU's Conflict Minerals Regulation, the Kimberley Process Certification Scheme, and the UAE's DMCC responsible sourcing standards constrain supply chains and elevate compliance costs for unverified producers. The US Federal Trade Commission's Jewelry Guides further tighten disclosure requirements for gemstone treatments and origin claims. Stakeholders must monitor evolving traceability mandates and consumer willingness to pay for authenticated provenance as defining strategic variables.
Market Dynamics
Digital traceability infrastructure is forcing luxury jewelry houses to reconfigure sourcing architectures around blockchain-verified provenance and real-time chain-of-custody documentation.
Growth Catalysts
- EU Conflict Minerals Regulation:Mandatory due diligence on 3TG minerals entering the European Economic Area creates certified supply scarcity that rewards compliant producers with preferential offtake agreements.
- Gen Z collector preference:Younger high-net-worth buyers prioritize authenticated ethical sourcing over traditional heritage signaling, redirecting volume toward houses with transparent mine-to-finger documentation.
- Platinum group metal substitution:Palladium price volatility and automotive demand competition is accelerating jewelry sector migration toward platinum-ruthenium alloys for white-metal settings.
Market Restraints
- Input cost volatility:Rough diamond price instability at Antwerp and Dubai trading hubs compresses manufacturing margins for mid-tier polishers lacking long-term mining contracts.
- Supply concentration risk:Botswana and Russia collectively control over sixty percent of gem-quality rough production, creating geopolitical exposure for houses dependent on Alrosa or Debswana offtake.
- Kimberley Process loopholes:Weak enforcement on artisanal mining zones allows conflict-tainted stones to enter legitimate channels, eroding consumer trust in certification claims.
Strategic Opportunities
- UAE DMCC responsible sourcing standards:Dubai's regulatory push for blockchain-tracked gold creates a compliance-advantaged trading hub for houses serving Middle Eastern and South Asian bridal demand.
- Men's fine jewelry:Underdeveloped male accessory penetration in China and the United States offers expansion space for signet rings, cufflinks, and chain necklaces beyond traditional wedding bands.
- Secondhand authentication services:Pre-owned luxury platforms require gemological verification infrastructure, creating service revenue streams for houses with established appraisal expertise.
Industry Challenges
- Artisan skill attrition:Master stone setters and hand engravers in Paris, Geneva, and Milan are aging out faster than apprenticeship pipelines replenish, threatening métiers d'art production capacity.
- Blockchain integration complexity:Legacy inventory management systems require expensive middleware development to interface with distributed ledger traceability platforms demanded by EU and UAE regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Jewelry Market |
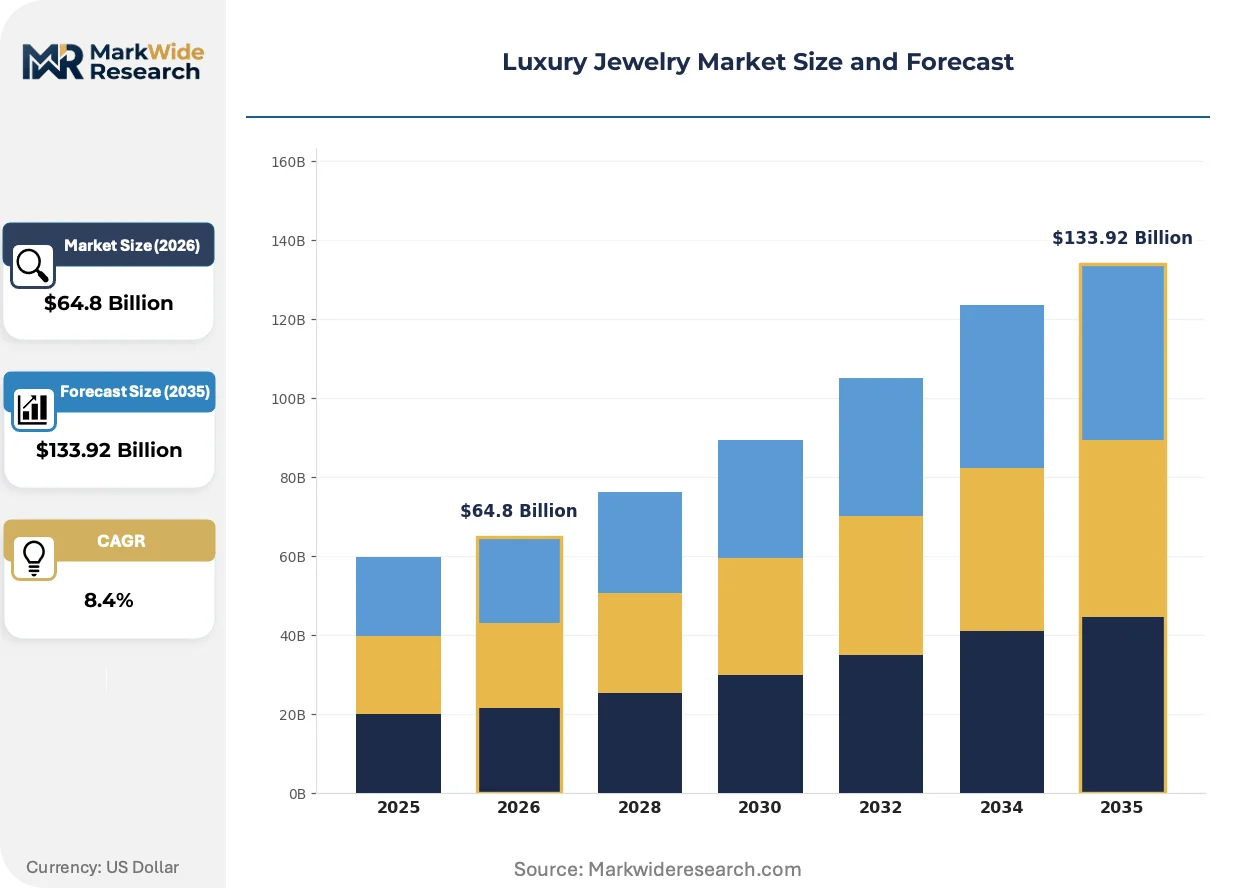
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $133.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Platinum, Silver, Gemstones End User: Men, Women, Couples, Collectors Distribution Channel: Online Retail, Luxury Boutiques, Department Stores, Auction Houses |
| Companies Covered | Bulgari, Boucheron, Cartier, Messika, Graff, Tiffany & Co., Chopard, Harry Winston, Van Cleef & Arpels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Jewelry Market Strategic Shifts & Innovations
Laboratory-grown diamond production is compressing natural stone price premiums and forcing heritage houses to articulate differentiation strategies around rarity narratives rather than material composition alone.
Blockchain-based provenance verification is fragmenting consumer trust architectures across the luxury jewelry sector. High-net-worth collectors in the United States and United Arab Emirates now expect immutable custody records from mine to retail. Houses without deployed distributed ledger infrastructure face exclusion from premium retail partnerships and auction consignment channels.
The EU's Corporate Sustainability Reporting Directive extends disclosure obligations to jewelry supply chains, mandating granular documentation of environmental and social impacts from extraction through finishing. Mid-sized manufacturers without dedicated compliance functions face audit costs that erode project profitability. Italian and French ateliers are consolidating shared-service sustainability teams to distribute regulatory burden.
Direct-to-consumer digital channels are displacing wholesale distribution for entry-luxury price points. Younger buyers in China research independently through social commerce platforms before requesting physical inspection appointments. Heritage houses are reallocating capital from department store concessions toward owned flagship experiences and appointment-only private salons in Shanghai, Shenzhen, and Chengdu.
Luxury Jewelry Market Segmentation
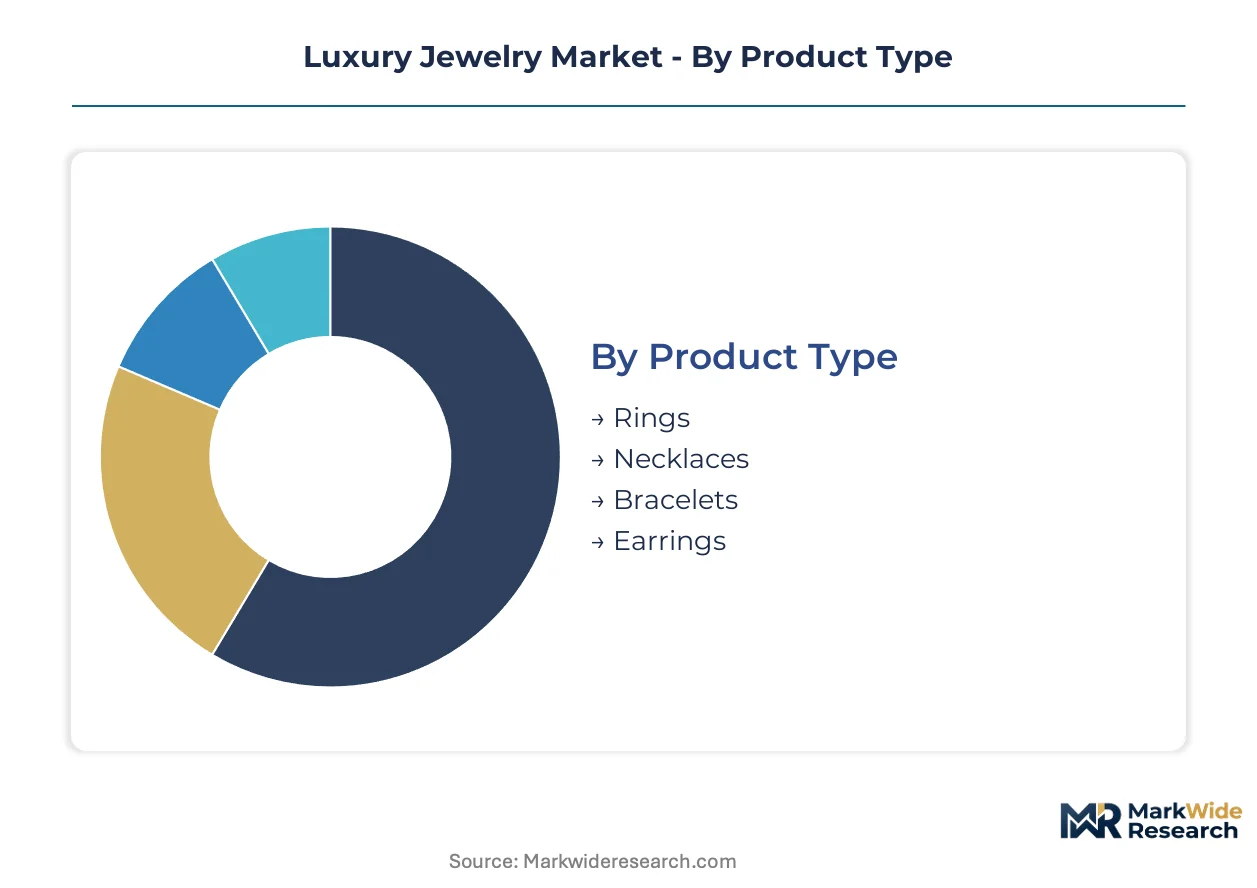
Segmentation in luxury jewelry reveals distinct margin architectures across product categories and buyer psychographics. Houses calibrate inventory depth and marketing spend against where value concentrates and where authentication premiums apply.
Product Type:
Margin pools concentrate in ceremonial categories where emotional weight supports price inelasticity and provenance documentation commands premiums.
- Rings:Engagement and wedding bands anchor revenue through repeat purchase cycles and upgrade traditions. China and the United States absorb the highest ceremonial volumes, with platinum-ruthenium alloys displacing palladium in white-metal settings due to automotive demand competition.
- Necklaces:Statement pieces in 18-karat gold and platinum carry the widest absolute margins, particularly in UAE bridal gifting and Chinese New Year consumption. Master stone setters in Paris and Geneva command scarcity rents for complex pavé work.
- Bracelets:Cufflinks and chain necklaces show accelerated adoption among male end users in China and the United States, expanding beyond traditional wedding band purchase.
- Earrings:Stud and drop configurations dominate daily-wear rotations, with laboratory-grown diamond options compressing natural stone premiums at entry price points.
The dominant share belongs to rings, while bracelets are closing the gap fastest.
Material:
Raw material sourcing constraints reshape competitive positioning across precious metals and gemstones.
- Gold:18-karat and 22-karat alloys serve as the primary store-of-value substrate, with Dubai's DMCC blockchain-tracked standards creating compliance-advantaged trading corridors for Middle Eastern and South Asian bridal demand.
- Platinum:Jewelry sector migration accelerates as automotive palladium consumption strains supply; platinum-ruthenium alloys offer superior durability for stone settings. Russian and South African mine concentration creates geopolitical exposure.
- Silver:Entry-luxury price points rely on sterling standards, though margin compression limits deployment in heritage house collections.
- Gemstones:Diamonds with VS1 clarity and above sustain auction premiums, while colored stones—emeralds from Colombia, rubies from Myanmar—trade on origin specificity and treatment disclosure under FTC Jewelry Guides.
Gold retains the deepest revenue pool, though platinum is expanding most quickly among white-metal alternatives.
End User:
Collector archetypes determine authentication requirements and channel preferences across the purchase journey.
- Women:Traditional core demand concentrates in self-purchase and gift reception, with Chinese buyers researching independently through social commerce before flagship appointments in Shanghai and Shenzhen.
- Collectors:High-net-worth individuals in the United States and United Arab Emirates require immutable custody records from mine to retail, excluding houses without deployed blockchain infrastructure from auction consignment.
- Men:Signet rings, cufflinks, and chain necklaces show underdeveloped penetration relative to wedding bands, offering expansion space in China and the United States.
- Couples:Co-purchase decisions increasingly prioritize ethical sourcing documentation over heritage signaling, redirecting volume toward transparent supply chains.
Women command the established volume base, while collectors are gaining share fastest on per-unit value.
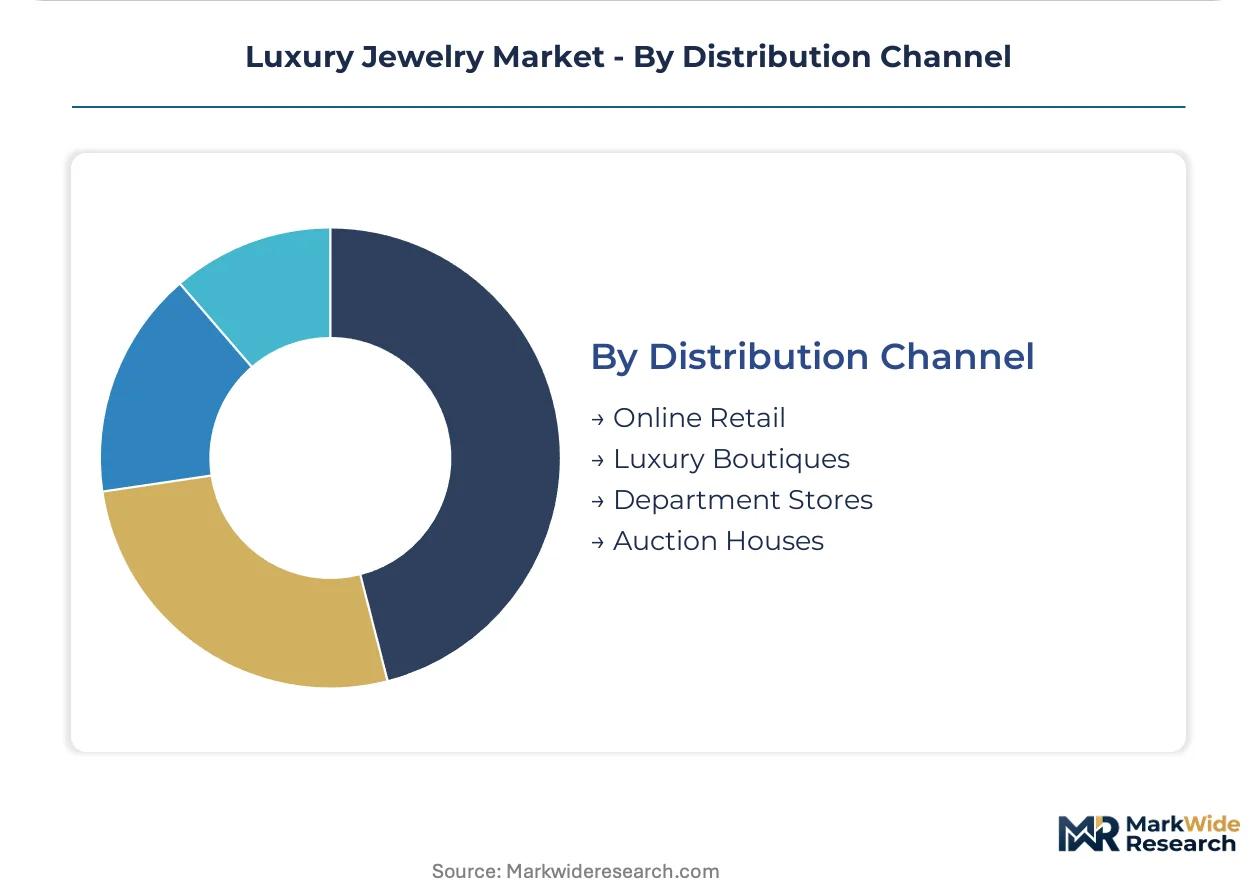
Distribution Channel:
Channel control determines margin capture and provenance narrative integrity.
- Luxury Boutiques:Owned flagship experiences and appointment-only private salons concentrate in Shanghai, Shenzhen, Chengdu, Dubai, and New York, displacing wholesale dependency.
- Online Retail:Direct-to-consumer digital channels serve entry-luxury price points, with social commerce platforms enabling independent research before physical inspection.
- Auction Houses:Christie's and Sotheby's capture the highest per-unit prices despite thin volume, with blockchain-verified provenance now mandatory for consignment.
- Department Stores:Concession models face capital reallocation as heritage houses prioritize owned retail and controlled experiential environments.
Luxury boutiques hold the premier position, while online retail is climbing the fastest among younger buyer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury jewelry supply chains concentrate in mining jurisdictions and heritage manufacturing centers. Demand clusters in high-net-worth consumer markets with established gifting traditions and bridal customs. Regulatory divergence across trade hubs is fragmenting compliance architectures.
China
Shanghai and Shenzhen anchor ceremonial demand through engagement ring upgrades and Lunar New Year gifting. The country's national market regulator enforces gemstone treatment disclosure standards under consumer protection frameworks. Master stone setters in Hong Kong and Guangzhou command scarcity rents for complex pavé work serving mainland buyers.
United States
New York and Los Angeles concentrate collector demand for auction-grade pieces with blockchain-verified provenance. The FTC Jewelry Guides mandate strict origin claims for diamond treatments and synthetic disclosures. Heritage houses maintain flagship salons on Fifth Avenue and Rodeo Drive while reallocating capital from department store concessions.
United Arab Emirates
Dubai's DMCC blockchain-tracked gold standards create a compliance-advantaged corridor for Middle Eastern and South Asian bridal demand. MOHAP oversees product safety standards while the free zone regulator mandates responsible sourcing documentation. Gold souks and ateliers in the Dubai Design District serve regional high-net-worth buyers.
France
Paris retains métiers d'art capacity for haute joaillerie despite aging master craftsmen. The national financial markets regulator enforces EU Conflict Minerals Regulation due diligence for 3TG minerals entering the European Economic Area. Place Vendôme ateliers sustain limited-production scarcity value through vertical integration into design and finishing.
Switzerland
Geneva hosts auction houses capturing the highest per-unit prices for colored stones and heritage pieces. Swissmedic oversees product safety while cantonal authorities enforce precious metals hallmarking standards. Master engravers and stone setters in the Rhône corridor face attrition faster than apprenticeship pipelines replenish.
Luxury Jewelry Market Key Industry Players
Concentration sits with heritage maisons controlling vertical integration from design through retail. The vendor base spans consolidated luxury conglomerates and independent ateliers with specialized métiers. Three archetypes dominate: conglomerate-owned houses with global retail networks, family-held maisons with artisanal production limits, and specialist auction houses with authentication infrastructure. Competitive moves center on blockchain traceability deployment and direct-to-consumer channel expansion.
Within the heritage maison tier, Cartier and Van Cleef & Arpels exemplify conglomerate-backed vertical integration into design, manufacturing, and owned retail. Tiffany & Co. occupies a position as a named entity in the raw data, representing American heritage positioning with diamond provenance specialization. These anchors demonstrate how authentication expertise and channel control separate premium pricing from mid-tier compression.
| Leading Market Players |
|---|
| Bulgari |
| Boucheron |
| Cartier |
| Messika |
| Graff |
| Tiffany & Co. |
| Chopard |
| Harry Winston |
| Van Cleef & Arpels |
| Others |
Cost & Logistics Intelligence
The Kimberley Process Certification Scheme gates both supply qualification and price differentiation simultaneously, with compliant rough commanding premiums at Antwerp and Dubai trading hubs while unverified material faces exclusion from EU and US retail channels. This bifurcation concentrates margin capture among houses with captive mining offtake or long-term polishing contracts.
Pricing Analysis
The EU Conflict Minerals Regulation dictates the pricing tier structure across the luxury jewelry landscape. Three-tier pricing structure across heritage maisons, mid-tier polishers, and unbranded manufacturers separates authenticated provenance from standard certification from untraceable supply. Cost compression in the mid-tier is intensifying because rough diamond price instability at trading hubs erodes manufacturing margins for houses lacking Debswana or Alrosa contracts. Bridal buyers in China and the United States show highest price sensitivity, while auction-grade collectors in the UAE demonstrate lowest elasticity for blockchain-verified pieces.
Supply Chain Analysis
Container availability constraints on the Antwerp-Dubai trade lane elevate inbound logistics costs for rough shipments. Botswana, Russia, and South Africa anchor gem-quality rough production, while India and Belgium concentrate cutting and polishing capacity. The supply chain draws from platinum group metals in South Africa and Russian mines, plus gold refined through Dubai's DMCC corridors. Single-source vulnerability sits with Alrosa offtake dependence. Distribution runs through owned flagship boutiques, auction house consignment, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates the luxury jewelry landscape as Gen Z collector preference for authenticated ethical sourcing creates niches between heritage maisons and unverified producers. Demand-side bifurcation rewards houses with deployed blockchain infrastructure.
For Market Incumbents: Compound authentication expertise through backward integration into mine-to-finger documentation and exclusive polishing partnerships. Laboratory-grown diamond compression threatens natural stone premiums, making captive supply of VS1+ rough from Debswana or Alrosa contracts essential. Channel control through owned flagship expansion in Shanghai, Shenzhen, and Dubai defends margin position against wholesale displacement. For New Entrants and Emerging Players: Lead with blockchain-verified provenance as the go-to-market anchor for underdeveloped men's fine jewelry penetration in China and the United States. Signet rings, cufflinks, and chain necklaces beyond wedding bands offer white-space expansion. Secondhand authentication services for pre-owned luxury platforms require gemological verification infrastructure that established appraisal expertise unlocks. For Investors and Strategic Acquirers: The EU Corporate Sustainability Reporting Directive reshapes the acquisition landscape toward houses with deployed compliance functions and shared-service sustainability teams. Long-term viability centers on vertical integration depth and traceability infrastructure rather than brand heritage alone. Watch for DMCC blockchain-tracked gold standard adoption rates as the inflection indicator for Middle Eastern and South Asian bridal demand capture.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Deployment | DMCC and EU mandates now require distributed ledger documentation for premium retail access. |
| Men's Fine Jewelry Line Launch | Underdeveloped male accessory penetration in China and the United States offers expansion space. |
| Secondhand Authentication Service | Pre-owned platforms require gemological verification that established appraisal expertise monetizes. |
| Platinum-Ruthenium Alloy Migration | Automotive palladium demand competition accelerates jewelry sector substitution for white-metal settings. |
| Direct-to-Consumer Channel Expansion | Social commerce research patterns in China favor owned flagship experiences over wholesale dependency. |
Research Approach
Cross-validation between primary interviews with heritage house executives, master stone setters, auction house specialists, and DMCC compliance officers and secondary validation anchors the qualitative findings. Customs data from Antwerp and Dubai trading hubs, Kimberley Process certification records, SEC filings from luxury conglomerates, and UAE free zone regulatory disclosures provide triangulation. Bottom-up segmentation modeling and top-down macroeconomic anchoring reconcile volume and value estimates.
Sensitivity analysis across the projection horizon tests forecast robustness against rough diamond price volatility and regulatory enforcement variance. Segmentation dimensions modeled include product category, material composition, end-user archetype, and distribution channel complexity. CAGRs derive from historical trajectory analysis adjusted for structural shifts in traceability mandates and collector preference evolution. Blockchain adoption curves and artisan skill attrition rates inform industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of EU Conflict Minerals Regulation and DMCC responsible sourcing standards would require recalibration. Forecasts reflect assumptions regarding geopolitical stability in Botswana and Russian rough supply, plus consumer willingness to pay premiums for authenticated provenance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Jewelry Cleaners Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Jewellery Market
Jewelry
Pearl Jewelry Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Brazil Jewelry Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Jewelry Repair Market