
 Saudi Arabia Luxury Jewelry Market | 2026-2036
Saudi Arabia Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Luxury Jewelry Market Insights
Asset-light franchising and concession-based retail leasing is tilting competitive dynamics toward operators with balance-sheet flexibility rather than heavy real estate ownership. Mouawad Jewelry leverages its vertically integrated atelier model to control craftsmanship quality across Riyadh and Jeddah flagships. Damas Jewelry anchors its position through extensive mall-based distribution, while L'azurde competes via localized design studios that respond faster to Gulf aesthetic preferences.
Saudi Arabia luxury jewelry denotes ornamental pieces crafted from precious metals and gemstones, typically exceeding purity thresholds of 18-karat gold or VS-clarity diamonds, designed for personal adornment and wealth signaling rather than investment alone. Gold necklaces and diamond rings occupy the dominant share of transaction value, reflecting cultural preference for bridal dowry traditions and Eid gifting cycles. Platinum earrings and high-end bracelets represent the fastest-growing material-product intersection, as younger consumers diversify beyond yellow gold. The women end-user segment sustains the largest margin pool, though men and couples categories expand with gender-neutral and wedding-band demand.
SFDA oversees precious metal hallmarking standards, while the Ministry of Commerce enforces anti-counterfeiting measures that protect branded retailers from gray-market infiltration. Zakat and VAT frameworks administered by the Zakat, Tax and Customs Authority shape consumer discretionary spending patterns and import cost structures. Stakeholders must monitor how excise adjustments and local content requirements under Vision 2030 alter sourcing economics for finished versus semi-finished goods.
Market Dynamics
Vision 2030's entertainment and tourism expansion is creating new gifting occasions beyond traditional bridal cycles, while mall-based retail concentration in Riyadh and Jeddah is reshaping how brands compete for foot traffic and concession terms.
Growth Catalysts
- SFDA hallmarking enforcement:Stricter precious metal certification standards are elevating consumer trust in branded retailers and compressing gray-market participation.
- Platinum fabrication advances:Improved white-metal casting techniques are enabling localized production of high-margin earrings and bracelets previously imported from European ateliers.
- Eid gifting normalization:Extended retail hours and entertainment district development around Riyadh Boulevard are stretching seasonal purchasing windows beyond traditional Ramadan peaks.
Market Restraints
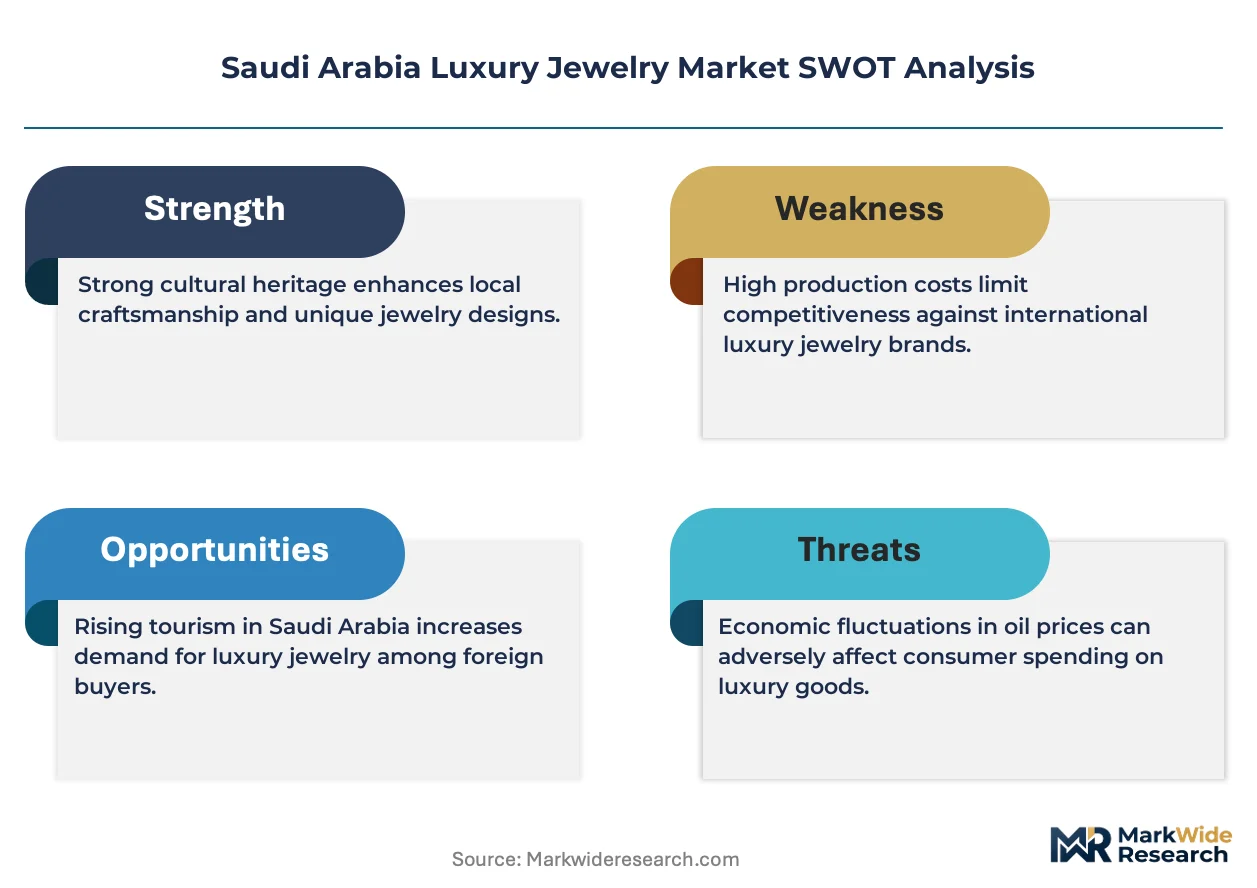
- Diamond rough supply concentration:Dependence on Antwerp and Dubai trading hubs exposes Saudi retailers to currency volatility and middlemarkup compression.
- 18-karat gold import duties:Zakat, Tax and Customs Authority tariff structures inflate landed costs for finished jewelry versus semi-finished blanks.
- Artisan bench jeweler scarcity:Limited vocational training infrastructure constrains expansion of high-end custom atelier capacity beyond established flagships.
Strategic Opportunities
- Neom and Red Sea Project zones:New tourism and residential developments offer first-mover positioning for experiential retail formats targeting affluent expatriate residents.
- Gender-neutral design white space:Unmet demand among younger male consumers for wedding bands and statement pieces outside traditional masculine codes.
- Local content incentives:Vision 2030 domestic manufacturing credits could subsidize captive casting and stone-setting operations versus offshore sourcing.
Industry Challenges
- Gemological certification bottlenecks:Limited accredited laboratories in Riyadh and Jeddah delay inventory turnover for high-value diamond and colored stone pieces.
- Legacy POS integration:Mall concession operators struggle to unify inventory visibility across fragmented franchisee networks and central e-commerce platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Luxury Jewelry Market |
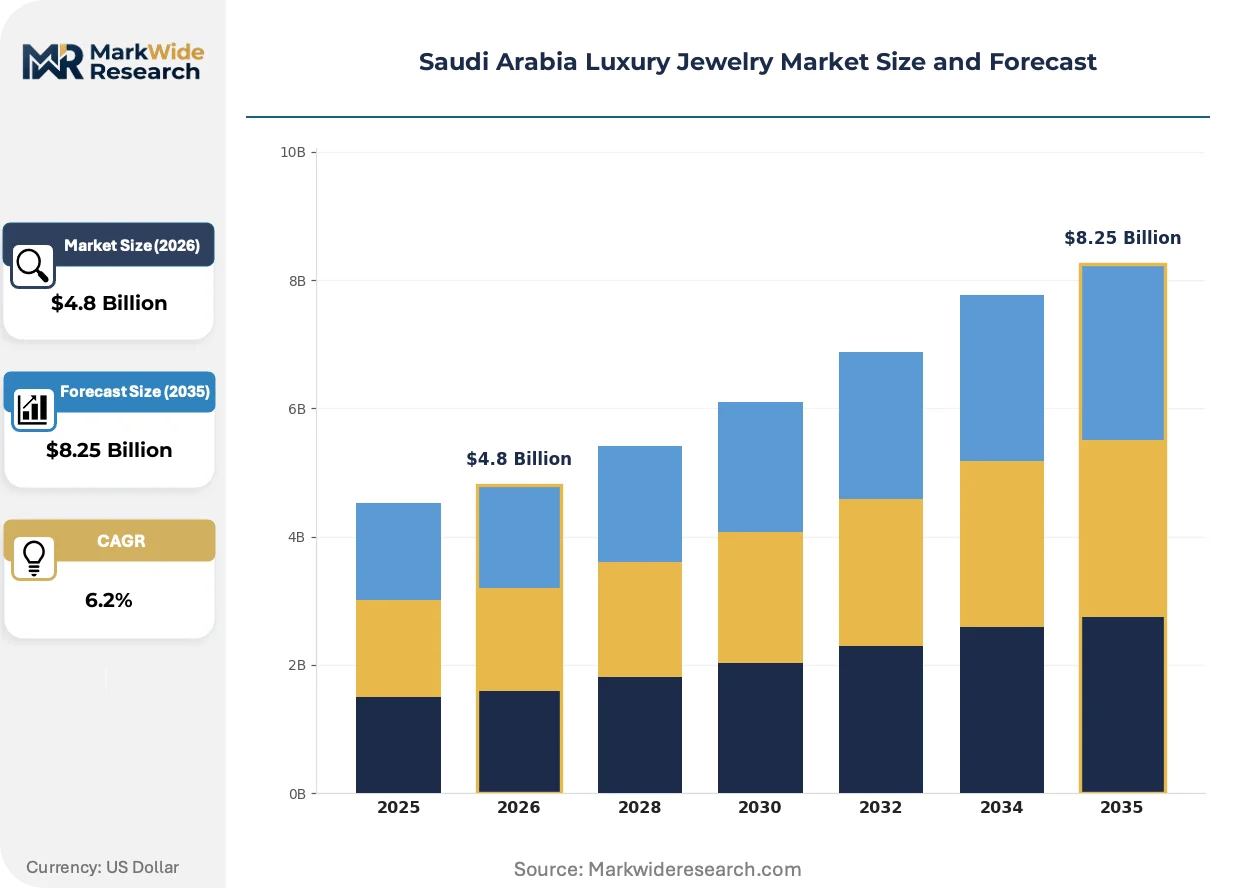
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Bracelets, Earrings, Rings Material: Gold, Silver, Platinum, Diamonds End User: Women, Men, Children, Couples Price Tier: Affordable, Mid-Range, Premium, High-End |
| Companies Covered | Mouawad Jewelry, Cartier, Al Haramain Jewelry, Harry Winston, Van Cleef & Arpels, L'azurde, Tiffany & Co., Bvlgari, Damas Jewelry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Luxury Jewelry Market Trends and Innovations
Digital traceability and generational taste divergence are compressing traditional supply chains while elevating transparency as a competitive differentiator in high-value transactions.
Blockchain-based provenance tracking is rendering obsolete paper-based chain-of-custody documentation for colored gemstones and high-carat diamonds. Bridal purchasers under age 35 now demand verifiable origin data as a standard condition of sale, forcing suppliers to retrofit legacy inventory with digital certificates or absorb resale discounts.
SFDA's phased implementation of digital hallmarking registries is tightening traceability requirements for 18-karat and above gold pieces sold through licensed retailers. The Ministry of Commerce is synchronizing enforcement actions with these technical standards, concentrating compliance costs on smaller unbranded souk operators lacking ERP integration.
Experiential retail formats are displacing conventional glass-case merchandising in Jeddah and Riyadh flagship locations. Private viewing suites and co-design consultations now capture margin premiums from HNW clients seeking exclusivity beyond mass-market mall positioning, with this shift most visible in bridal and anniversary purchase occasions.
Saudi Arabia Luxury Jewelry Market Segmentation
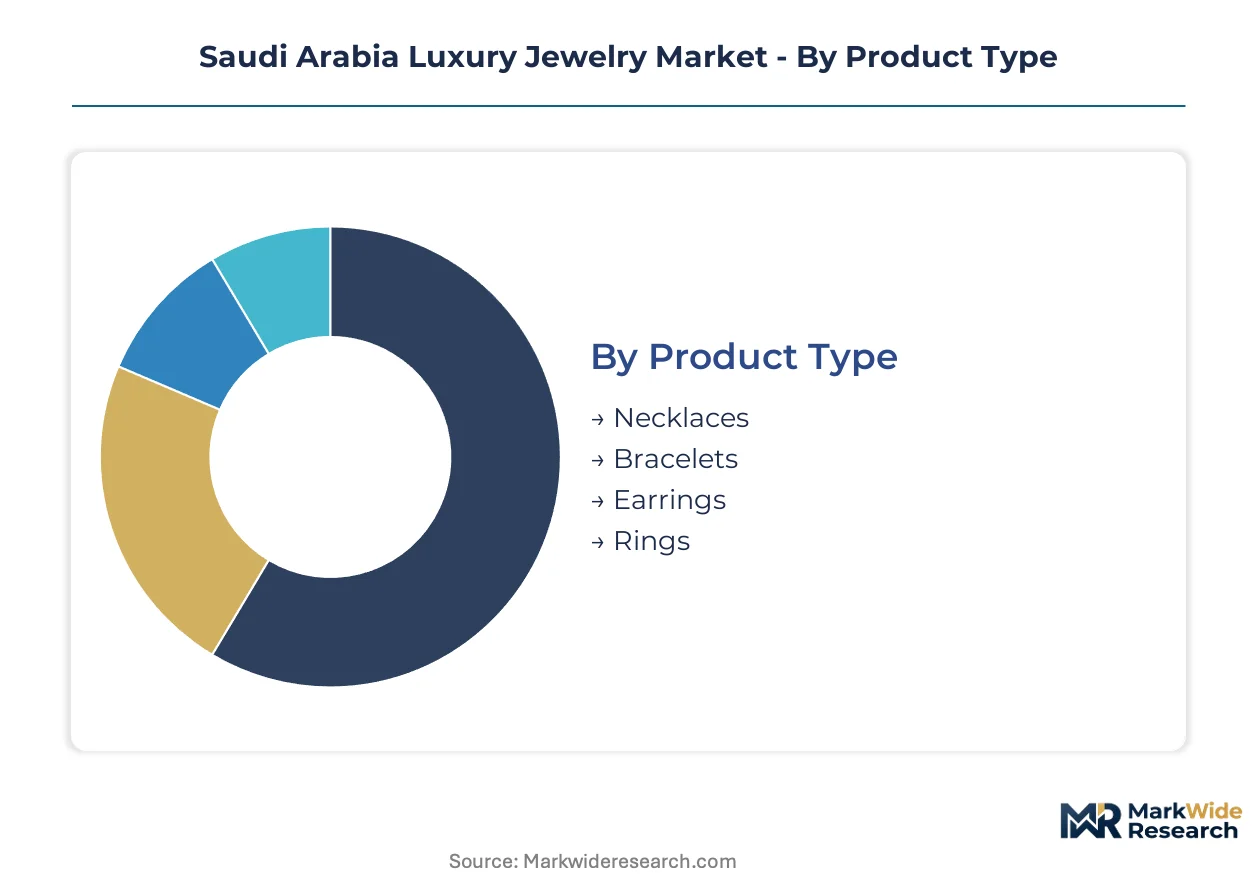
Segmentation in Saudi Arabia's luxury jewelry market reveals how purchasing occasions, material preferences, and price thresholds fragment demand across distinct consumer clusters. Understanding these divisions enables targeted inventory positioning and retail format selection.
Product Type:
After-sales service intensity varies sharply across product categories, with intricate pieces demanding specialized maintenance programs that anchor long-term customer relationships.
- Necklaces:Elaborate collar and pendant designs in 18-karat gold dominate bridal dowry transactions across Riyadh and Jeddah. SFDA hallmarking requirements for high-value pieces elevate trust in certified retailers serving this segment.
- Rings:Wedding bands and solitaire settings concentrate margin capture during engagement seasons, with platinum fabrication advances enabling localized production previously sourced from European ateliers.
- Bracelets:Cuff and chain designs respond to Eid gifting cycles with standardized sizing that reduces alteration service burdens.
- Earrings:Stud and drop configurations in white metals represent the fastest-growing product type as younger consumers diversify beyond traditional yellow gold preferences.
Necklaces hold the largest share; momentum sits with earrings.
Material:
Cost tier stratification in raw materials directly shapes finished goods pricing and import duty exposure under Zakat, Tax and Customs Authority frameworks.
- Gold:18-karat and 22-karat yellow gold remains the cultural default for bridal and ceremonial purchases, though import tariff structures inflate landed costs for finished versus semi-finished blanks.
- Platinum:White-metal casting improvements enable domestic production of high-margin earrings and bracelets, reducing dependence on Antwerp and Dubai trading hubs for finished pieces.
- Diamonds:VS-clarity stones anchor investment-grade positioning, with blockchain provenance tracking now demanded by purchasers under 35 as a standard condition of sale.
- Silver:Lower purity thresholds serve accessible gifting tiers and children's occasions with reduced hallmarking compliance costs.
Gold commands the dominant position; platinum shows the steepest expansion trajectory.
End User:
Customer type differentiation determines retail format requirements, from private viewing suites for high-net-worth individuals to efficient mall-floor transactions for seasonal gift purchasers.
- Women:The core margin pool spans bridal dowries, self-purchase upgrades, and anniversary occasions, with experiential retail formats in Riyadh and Jeddah flagships capturing premium positioning.
- Men:Wedding bands and statement pieces outside traditional masculine codes represent unmet white space, particularly among younger consumers seeking gender-neutral design language.
- Couples:Coordinated bridal sets and matching band purchases concentrate transaction value during compressed engagement-to-wedding windows.
- Children:Lower-value gifting occasions around Eid and births sustain volume throughput with standardized designs requiring minimal customization.
Women sustain the largest revenue base; men are gaining share fastest.
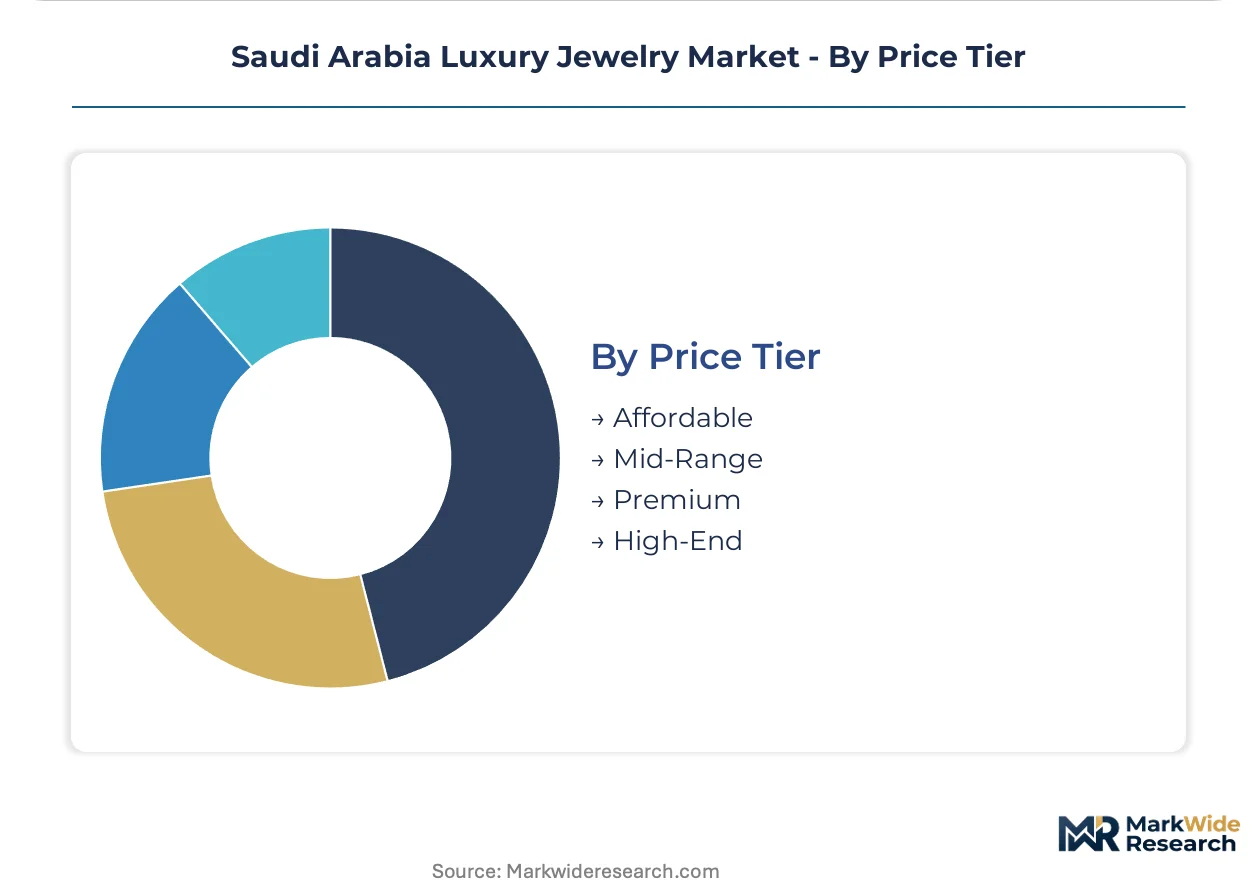
Price Tier:
Margin structure across price bands reflects certification requirements, with SFDA digital hallmarking registries concentrating compliance costs on smaller operators in the affordable tier.
- Premium:Branded atelier pieces with verifiable provenance and bespoke design services capture margin premiums through private consultation formats in flagship locations.
- High-End:Investment-grade diamonds and rare colored gemstones require extended sales cycles and gemological certification that bottlenecks inventory turnover in Riyadh and Jeddah.
- Mid-Range:Mall-based concession operators compete on accessibility, with fragmented POS integration challenges across franchisee networks constraining unified inventory visibility.
- Affordable:Volume-driven silver and lower-karat gold pieces serve seasonal gifting with reduced service intensity and faster inventory velocity.
Premium commands the deepest margins; high-end shows the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's luxury jewelry trade maintains a structural import surplus, with finished goods inflows from European ateliers and Dubai trading hubs outpacing outbound re-exports of locally fabricated pieces. Riyadh and Jeddah concentrate domestic retail infrastructure, while emerging zones in the Eastern Province and NEOM corridor reshape geographic demand distribution.
Riyadh
HNW bridal consumers and Vision 2030 entertainment district development anchor transaction value growth in the capital. SFDA digital hallmarking registries concentrate compliance-capable retailers in Riyadh Boulevard and King Abdullah Financial District clusters. Private viewing suites in flagship locations capture margin premiums from anniversary and dowry purchasers seeking exclusivity beyond mall concessions.
Jeddah
Coastal proximity to Red Sea shipping lanes reduces landed costs for platinum rough and colored gemstone imports entering through King Abdulaziz Port. The Ministry of Commerce synchronizes anti-counterfeiting enforcement with SFDA technical standards, compressing gray-market participation in traditional souk districts. Experiential retail formats in Jeddah Corniche and Tahlia Street displace conventional glass-case merchandising for younger consumer segments.
Eastern Province
Expatriate professional households in Dhahran and Al Khobar sustain mid-range gifting volume outside traditional bridal peaks. Zakat, Tax and Customs Authority tariff structures inflate costs for finished 18-karat gold pieces versus semi-finished blanks processed through Dammam industrial zones. Mall-based concession operators compete for foot traffic in Dhahran Mall and Al Rashid Mall with fragmented POS integration challenges.
Western Region
Religious tourism flows through Makkah and Madinah create concentrated seasonal demand spikes around Hajj and Umrah cycles. Localized design studios respond faster to Gulf aesthetic preferences for geometric motifs and calligraphic elements in ceremonial pieces. Artisan bench jeweler scarcity constrains expansion of high-end custom atelier capacity beyond established flagships in these cities.
NEOM Northwest
New tourism and residential developments in the giga-project zone offer first-mover positioning for experiential retail formats targeting affluent expatriate residents. Vision 2030 domestic manufacturing credits could subsidize captive casting and stone-setting operations versus offshore sourcing for operators establishing early presence. Regulatory sandboxes may relax import documentation requirements for high-value inventory positioned for duty-free resale to international visitors.
Saudi Arabia Luxury Jewelry Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated atelier operators and concession-dependent mall retailers with limited balance-sheet flexibility. Three archetypes dominate: heritage houses with Riyadh-Jeddah flagship networks, Gulf-based regional chains exploiting localized design velocity, and global maisons leveraging brand equity for premium positioning. Competitive moves concentrate on experiential retail format rollout and blockchain provenance integration rather than capacity expansion.
Within the heritage atelier tier, Mouawad Jewelry and Cartier exemplify operators controlling craftsmanship quality through captive production infrastructure. Among Gulf-based fabricators, L'azurde and Damas Jewelry occupy positions emphasizing mall accessibility and faster design turnaround respectively. Global maisons including Harry Winston and Van Cleef & Arpels represent the import-dependent premium segment where brand equity commands concession terms in Riyadh and Jeddah luxury retail clusters.
| Leading Market Players |
|---|
| Mouawad Jewelry |
| Cartier |
| Al Haramain Jewelry |
| Harry Winston |
| Van Cleef & Arpels |
| L'azurde |
| Tiffany & Co. |
| Bvlgari |
| Damas Jewelry |
| Others |
Pricing and Supply Chain Analysis
Antwerp and Dubai trading hubs concentrate rough diamond supply, anchoring margin capture for finished jewelry in Riyadh and Jeddah flagships while compressing pricing power for mid-range mall operators lacking direct sourcing relationships.
Pricing Analysis
Bridal consumers anchor three-tier pricing structure across premium, standard, and economy levels in Saudi Arabia's luxury jewelry market. Price differentiation rests on SFDA certification grade and brand heritage, with heritage ateliers commanding premiums for bespoke craftsmanship. Pricing pressure stems from Zakat, Tax and Customs Authority tariff structures inflating landed costs for finished 18-karat pieces. Mid-range mall concession operators exhibit highest price sensitivity due to fragmented POS integration and inventory visibility constraints.
Supply Chain Analysis
Extended payment terms from Antwerp rough traders and Dubai polishing houses shape working capital requirements for Saudi retailers. Geographic supply concentrates in Belgium, United Arab Emirates, and India for diamond cutting, with Italy and Switzerland for high-end platinum fabrication. Raw material dependencies center on rough diamond parcels, 18-karat gold blanks, and platinum sponge. Single-source vulnerability runs through Antwerp's oligopolistic rough allocation system. Distribution runs through Riyadh and Jeddah flagship networks for premium tiers, with mall concessions handling volume throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as generational taste divergence and Vision 2030 entertainment expansion create distinct purchasing occasions beyond traditional bridal cycles.
For Market Incumbents: Build experiential retail moats through private viewing suites and co-design consultations that capture margin premiums from HNW clients. Consolidate position by securing concession terms in Riyadh Boulevard and King Abdullah Financial District clusters before competitor flagships anchor. Invest in blockchain provenance tracking to defend against gray-market infiltration and satisfy under-35 purchaser demands for verifiable origin data. For New Entrants and Emerging Players: Gender-neutral design white space in men's wedding bands and statement pieces represents the most penetrable entry point for differentiated positioning. NEOM and Red Sea Project zones offer first-mover experiential retail opportunities targeting affluent expatriate residents ahead of established heritage houses. Localized design studios responding faster to Gulf aesthetic preferences provide a viable go-to-market angle against slower-moving global maisons. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Gulf-based regional chains possessing mall distribution networks but lacking captive production infrastructure. Five-to-ten year viability favors operators with balance-sheet flexibility for asset-light franchising rather than heavy real estate ownership. Monitor SFDA digital hallmarking registry enforcement as an inflection indicator concentrating compliance costs on smaller unbranded souk operators and accelerating branded retailer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | SFDA digital hallmarking synchronization elevates transparency as a competitive differentiator for high-value transactions. |
| Experiential Retail Format Rollout | Private viewing suites in Riyadh and Jeddah capture margin premiums from HNW bridal and anniversary purchasers. |
| Localized Design Studio Expansion | Faster response to Gulf aesthetic preferences compresses design-to-shelf cycles versus European atelier dependencies. |
| Platinum Fabrication Capability Buildout | Domestic white-metal casting reduces Antwerp and Dubai trading hub exposure for high-margin earrings and bracelets. |
| NEOM Zone First-Mover Positioning | Vision 2030 domestic manufacturing credits could subsidize captive operations versus offshore sourcing for early entrants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with jewelry atelier directors, mall concession operators, SFDA compliance officers, and Zakat, Tax and Customs Authority officials; and secondary validation through customs trade records, SFDA hallmarking registry disclosures, Ministry of Commerce enforcement actions, and Vision 2030 policy documentation. Bottom-up sizing of Riyadh and Jeddah retail clusters triangulated against top-down import value flows from European ateliers and Dubai trading hubs.
Forecast inputs considered product type segmentation across necklaces, rings, bracelets, and earrings; material tier stratification in gold, platinum, diamonds, and silver; end-user clustering by women, men, couples, and children; and price band differentiation across premium, high-end, mid-range, and affordable tiers. CAGRs derived from trajectory analysis of HNW population growth, bridal transaction velocity, and entertainment district development across the projection horizon. Industry-specific inputs incorporated SFDA phased implementation schedules and Vision 2030 local content incentive structures.
Practitioners should monitor excise adjustments, local content requirement evolution, and gemological certification laboratory capacity expansion for early signals of forecast deviation. Macroeconomic shifts in oil revenue, regulatory changes in hallmarking enforcement, or technological advances in synthetic diamond detection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Wedding Rings Market
Jewelry
Customized Jewelry Market
Jewelry
China Luxury Jewelry Market
Jewelry
Bead Products Market
Jewelry
Jewellery Box Market
Jewelry
Body Jewelry Market
Jewelry
Luxury Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Imitation Jewelry Market
Jewelry
Artificial Jewellery Market