
 Japan Jewellery Market | 2026-2036
Japan Jewellery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Jewellery Market Outlook
Digital design-to-manufacture workflows is rewriting how Japanese jewellers prototype and produce custom pieces. K Mikimoto & Co Ltd anchors its position through proprietary pearl cultivation technology integrated with CAD rendering. Tiffany & Co Japan Inc leverages its flagship Ginza presence to control high-consideration purchase journeys. NIWAKA specializes in bridal collections that dominate Kyoto and Osaka wedding markets.
Japan jewellery encompasses ornamental accessories crafted from precious metals and gemstones, typically requiring 18-karat gold purity or platinum grades above 850 for domestic retail certification, serving both ceremonial gift exchange and personal wealth preservation. Rings command the largest share of platinum and gold material consumption due to persistent bridal demand. Online shoppers represent the fastest-expanding customer type as virtual try-on tools reduce purchase friction for gemstone earrings and bracelets.
METI enforces hallmarking standards through Japan Assay Office verification, while the Consumer Affairs Agency monitors precious metal labeling accuracy to prevent alloy misrepresentation. PMDA oversight extends to nickel release testing in body-contact pieces, shaping import requirements for European and Asian suppliers. Stakeholders must track evolving ethical sourcing mandates and digital authentication protocols to secure market access.
Market Dynamics
Digital design-to-manufacture workflows are compressing prototyping cycles for custom platinum bridal sets, while METI's ethical sourcing mandates force supply chain reconfiguration across domestic refiners and import channels.
Growth Catalysts
- Online customization platforms:Virtual try-on tools reduce purchase friction for gemstone earrings and bracelets, expanding the addressable base beyond flagship retail footprints in Tokyo and Osaka.
- METI ethical sourcing guidelines:Mandatory disclosure requirements for precious metal origin are accelerating adoption of blockchain-traceable supply chains among domestic wholesalers.
- Platinum bridal demand:Ceremonial gift exchange traditions in Kyoto and Osaka metropolitan areas sustain material consumption for 850-grade platinum rings.
Market Restraints
- Precious metal price volatility:Fluctuations in platinum and 18-karat gold spot prices compress margin buffers for independent ateliers lacking hedging instruments.
- Import concentration risk:Rough gemstone sourcing dependence on specific overseas cutting centers creates vulnerability to customs processing delays and tariff adjustments.
- Nickel release compliance:PMDA body-contact testing requirements for alloy components add certification costs that disproportionately burden small-scale producers.
Strategic Opportunities
- Kyoto bridal market expansion:NIWAKA's regional dominance demonstrates whitespace for specialized ceremonial collections targeting traditional wedding venues.
- CAD-pearl cultivation convergence:Integration of parametric design software with biogenic material sourcing is hybridizing product development timelines for cultured pearl specialists.
- Direct-to-consumer channels:Social commerce platforms enable bypass of Ginza flagship rental costs, capturing younger demographics seeking customizable gemstone configurations.
Industry Challenges
- CAD technician scarcity:Digital rendering expertise for custom jewelry workflows remains concentrated among a limited pool of trained operators, constraining atelier scaling.
- Dual certification timelines:Simultaneous Japan Assay Office hallmarking and PMDA nickel compliance create bottlenecks for import-dependent product launches.
- Legacy inventory integration:Pre-ethical-sourcing stockpiles require segregation and documentation retrofitting to meet METI disclosure mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Jewellery Market |
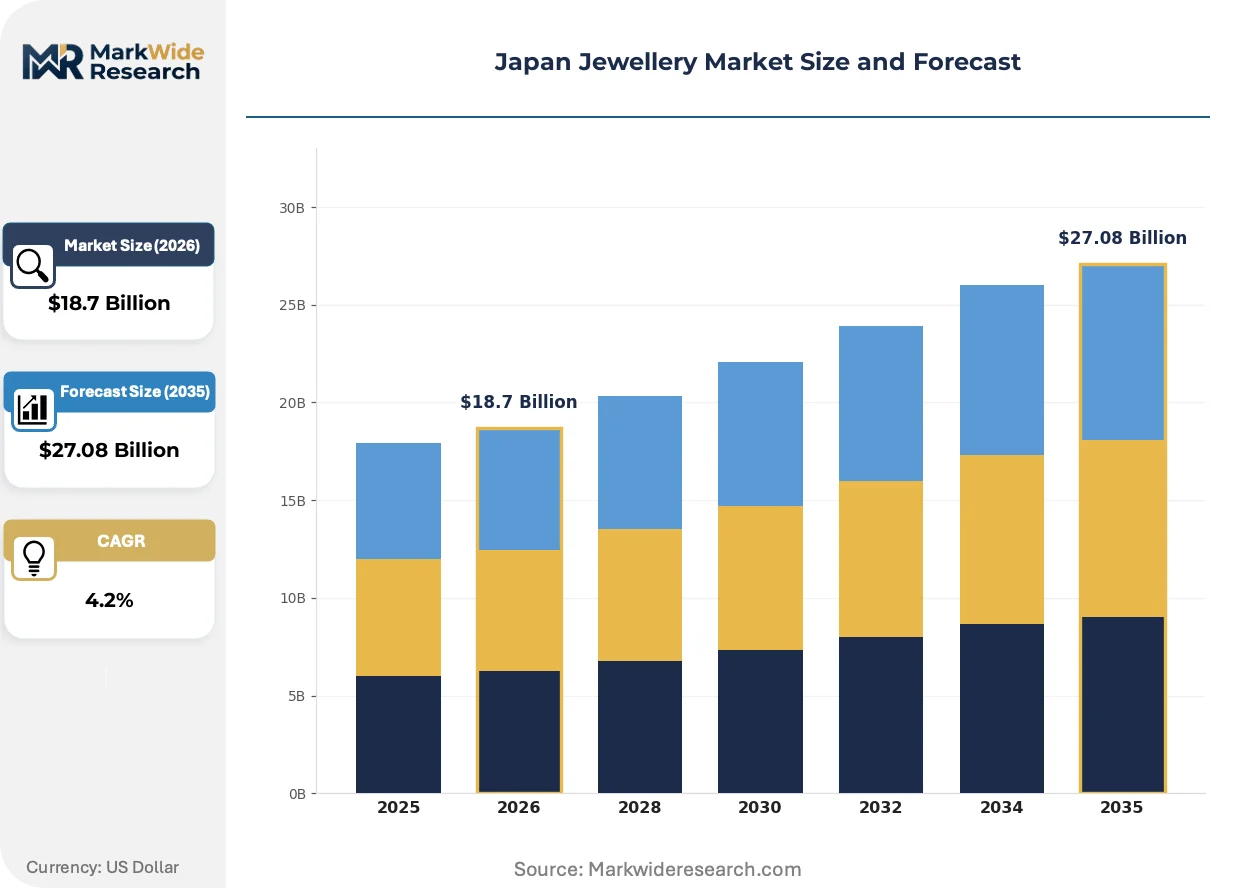
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Silver, Platinum, Gemstones Customer Type: Retail Consumers, Online Shoppers, Gift Buyers, Luxury Clients Distribution Channel: Jewellery Stores, Online Marketplaces, Department Stores, Boutiques |
| Companies Covered | Richemont Japan Ltd, Bulgari Japan Ltd, K Mikimoto & Co Ltd, As-me Estelle Co Ltd, Kuwayama Corp, Fdc Products Inc, Tiffany & Co Japan Inc, NIWAKA, Chanel KK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Jewellery Market Strategic Shifts
Parametric design tools and biogenic material science are converging to reshape how Japanese ateliers develop custom ceremonial pieces, compressing traditional craftsmanship timelines while elevating precision standards.
CAD rendering software is hybridizing with proprietary pearl cultivation protocols at heritage houses, enabling real-time visualization of nacre layering patterns before harvest commitment. Bridal buyers in Osaka and Kyoto metropolitan corridors now expect 48-hour digital prototype turnaround for platinum setting modifications. This capability compression is collapsing the traditional seasonal collection cycle into continuous micro-production runs.
METI's tightening disclosure requirements for precious metal provenance are forcing refiners to deploy blockchain-anchored documentation systems. Domestic assay offices now verify chain-of-custody records alongside traditional purity testing. Small wholesalers lacking technical infrastructure face exclusion from department store supply networks that demand audit-ready transparency.
Virtual try-on applications are displacing physical flagship visits for initial gemstone consideration among digital-native purchasers. Tokyo-based online shoppers now complete bracelet and earring transactions through augmented reality interfaces, reserving showroom appointments solely for final platinum ring fitting. This channel bifurcation is reallocating capital from Ginza real estate toward cloud rendering infrastructure and last-mile logistics.
Japan Jewellery Market Segmentation
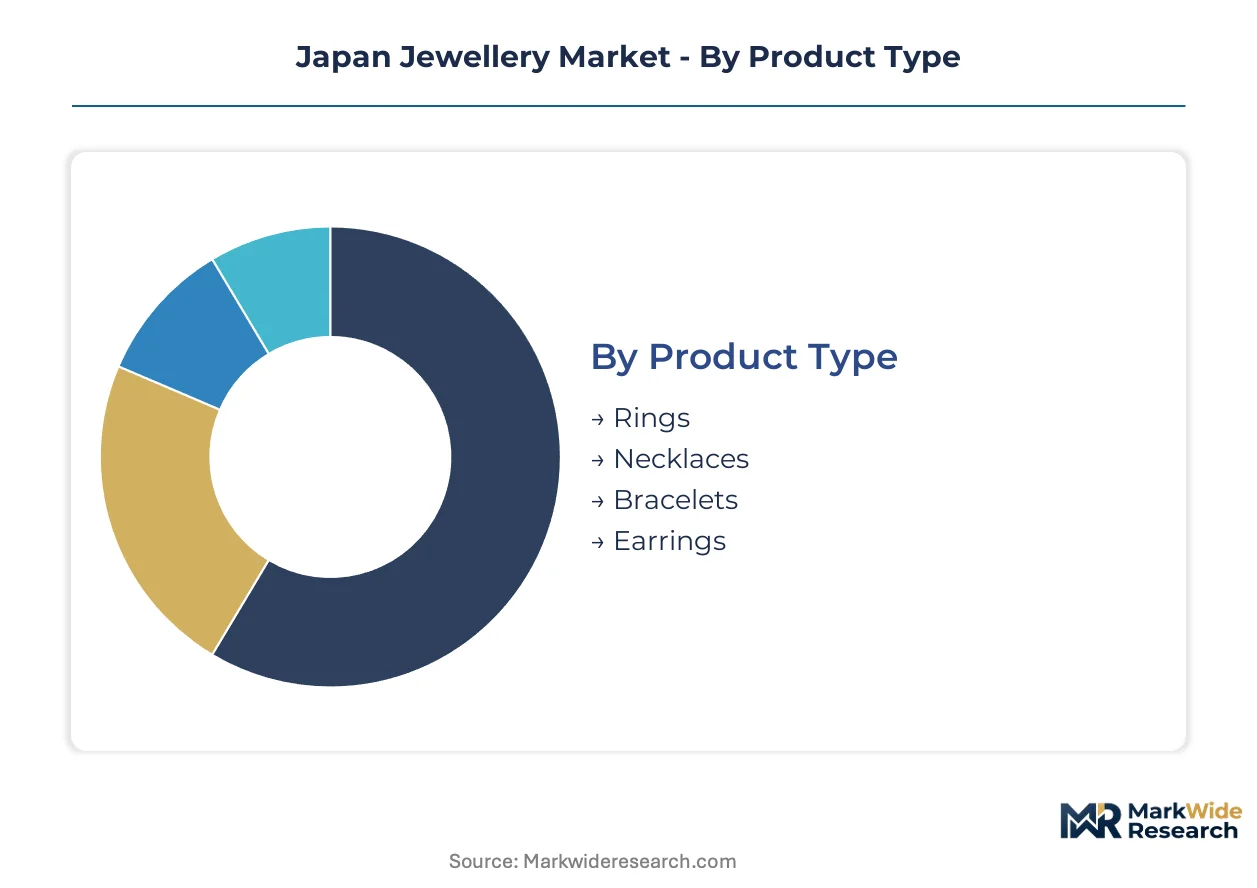
Segmentation reveals how METI regulations and digital channels reshape purchasing patterns across Japan's jewellery landscape. Understanding these divides exposes where platinum bridal demand concentrates versus where virtual try-on tools unlock new customer acquisition.
Product Type:
After-sales service intensity varies dramatically across product categories, with platinum bridal rings requiring resizing and maintenance commitments that necklaces and bracelets rarely demand.
- Rings:Platinum and 18-karat gold bands dominate material consumption through ceremonial gift exchange traditions in Kyoto and Osaka. Bridal buyers expect lifetime resizing services and annual polishing protocols that lock retailers into long-term customer relationships.
- Earrings:Virtual try-on tools have collapsed purchase friction for gemstone studs and drops among Tokyo's digital-native shoppers. Augmented reality interfaces now handle initial selection, reserving showroom visits solely for metal sensitivity testing.
- Necklaces:Chain length customization and clasp repair needs sustain mid-tier service revenue for independent ateliers.
- Bracelets:Link adjustment requirements create recurring touchpoints that department stores leverage for cross-selling opportunities.
By volume, rings lead. By growth pace, earrings are expanding most quickly through social commerce channels.
Material:
Cost tier stratification separates wealth preservation buyers from ceremonial purchasers, with purity grades determining both price positioning and regulatory scrutiny intensity.
- Platinum:850-grade purity minimums for domestic retail certification anchor bridal demand in Osaka and Kyoto metropolitan corridors. METI's Japan Assay Office verification creates compliance bottlenecks that favor established refiners with integrated hallmarking capacity.
- Gold:18-karat standards dominate wealth preservation segments, with alloy composition disclosure requirements tightening under ethical sourcing mandates.
- Gemstones:Rough sourcing dependence on overseas cutting centers exposes importers to customs processing delays and tariff volatility.
- Silver:Lower purity thresholds reduce certification overhead, attracting price-sensitive younger demographics through online marketplaces.
By revenue concentration, platinum leads. By channel shift velocity, gemstones are climbing the fastest through direct-to-consumer platforms.
Customer Type:
Application context separates one-time ceremonial purchasers from recurring personal buyers, with gift exchange traditions imposing stricter quality expectations than self-directed acquisition.
- Luxury Clients:Flagship Ginza presence controls high-consideration journeys for platinum bridal sets requiring bespoke CAD rendering and cultivation protocol integration. These buyers demand white-glove resizing services and archival documentation.
- Online Shoppers:Virtual try-on adoption has reallocated capital from physical retail toward cloud infrastructure and last-mile logistics. Tokyo-based digital natives complete transactions through augmented reality, bypassing traditional showroom overhead.
- Gift Buyers:Ceremonial exchange traditions in Kyoto wedding markets sustain demand for certified provenance and hallmarking documentation.
- Retail Consumers:Department store foot traffic concentrates among older demographics seeking in-person alloy verification and nickel release assurance.
By transaction frequency, luxury clients lead. By acquisition cost efficiency, online shoppers are gaining share fastest.
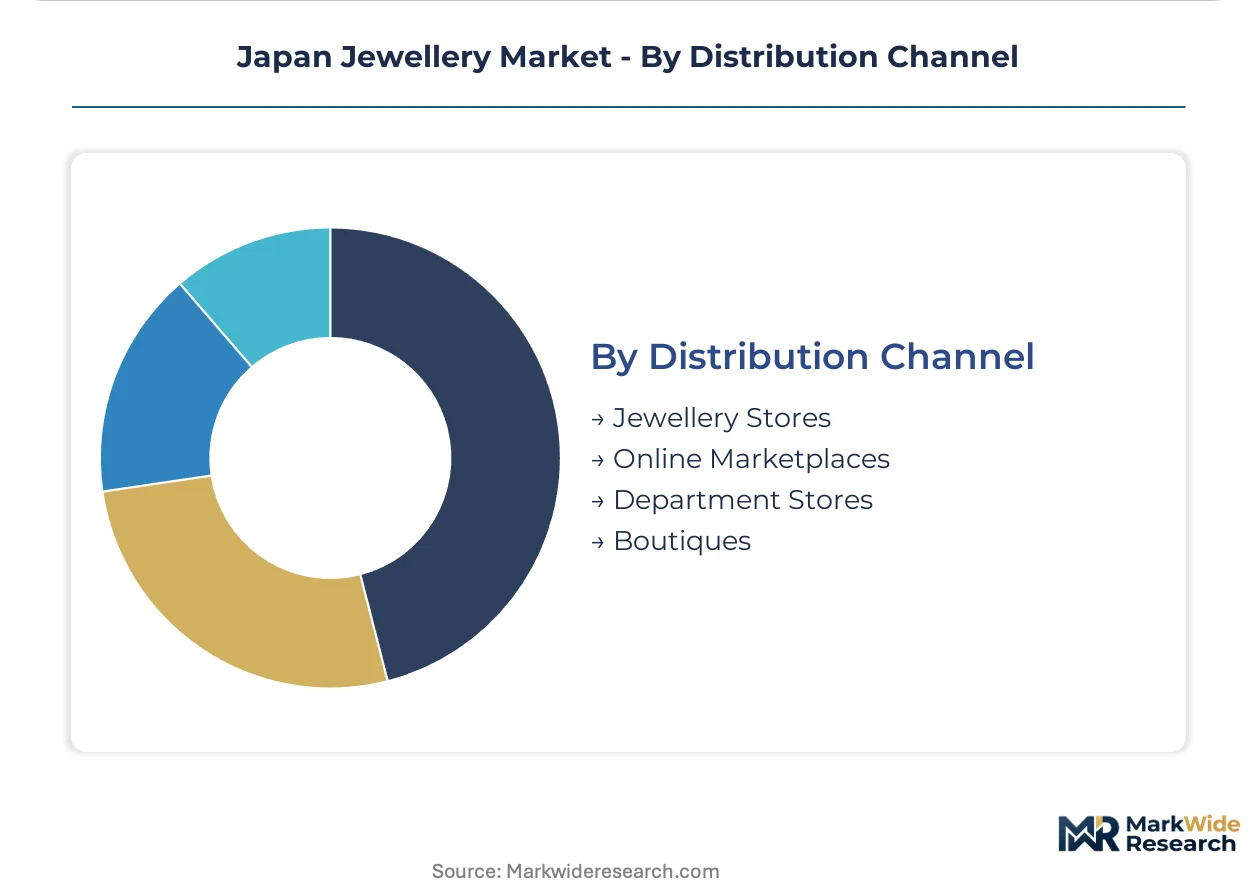
Distribution Channel:
Supply concentration in Tokyo and Osaka metropolitan corridors shapes channel profitability, with rental cost differentials between Ginza flagship positions and suburban boutiques determining margin structures.
- Online Marketplaces:Social commerce platforms enable bypass of Ginza rental costs, capturing customizable gemstone configurations among younger demographics. Cloud rendering infrastructure and logistics partnerships now rival physical presence for brand building.
- Jewellery Stores:Independent ateliers concentrate CAD technician expertise for custom platinum prototyping, though scaling constraints limit output volume.
- Department Stores:Audit-ready transparency requirements under METI disclosure mandates favor wholesalers with blockchain-anchored documentation systems.
- Boutiques:Kyoto and Osaka wedding venue proximity drives specialized ceremonial collection placement for regional bridal dominance.
By revenue stability, jewellery stores lead. By capital efficiency, online marketplaces show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury clients concentrate in Tokyo and Osaka metropolitan corridors, driving platinum bridal demand through ceremonial gift exchange traditions. Online shoppers represent the fastest-expanding archetype as virtual try-on tools reduce purchase friction. Regional performance varies across Japan's major economic zones based on manufacturing heritage and retail infrastructure density.
Kanto/Tokyo
Flagship Ginza presence controls high-consideration purchase journeys for platinum bridal sets requiring bespoke CAD rendering. METI's Japan Assay Office verification creates compliance bottlenecks that favor established refiners with integrated hallmarking capacity. Tokyo-based digital natives complete transactions through augmented reality interfaces, reallocating capital from physical retail toward cloud infrastructure.
Kansai/Osaka
Ceremonial gift exchange traditions in Osaka and Kyoto metropolitan corridors sustain material consumption for 850-grade platinum rings. NIWAKA's regional dominance demonstrates whitespace for specialized ceremonial collections targeting traditional wedding venues. The area's manufacturing heritage supports independent ateliers concentrating CAD technician expertise for custom prototyping.
Chubu/Nagoya
Industrial precision manufacturing capabilities feed component supply chains for domestic jewellery fabricators. METI ethical sourcing guidelines accelerate adoption of blockchain-traceable supply chains among regional wholesalers. Nagoya's automotive-adjacent metalworking clusters provide technical workforce pools for CAD rendering and parametric design operations.
Kyushu
Pearl cultivation operations anchor biogenic material sourcing for heritage houses integrating proprietary protocols with digital design workflows. Regional producers face segregation and documentation retrofitting requirements for pre-ethical-sourcing stockpiles under tightening disclosure mandates. Fukuoka's logistics infrastructure supports last-mile distribution to online shoppers across western Japan.
Hokkaido
Tourism-dependent retail channels concentrate seasonal demand fluctuations for silver and lower-purity gemstone pieces. PMDA nickel release testing requirements for alloy components add certification costs that disproportionately burden small-scale producers in remote locations. Sapporo's department store networks demand audit-ready transparency that excludes wholesalers lacking technical infrastructure.
Japan Jewellery Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base fragments between heritage houses with proprietary cultivation technology and digital-native entrants leveraging social commerce platforms. Three archetypes dominate: flagship-dependent luxury marques, CAD-integrated custom ateliers, and direct-to-consumer marketplace operators. Competitive moves concentrate on M&A for supply chain control and strategic partnerships for cloud rendering infrastructure.
Within the heritage house tier, K Mikimoto & Co Ltd and Tiffany & Co Japan Inc exemplify channel-controlling strategies through flagship presence and proprietary technology integration. NIWAKA occupies a specialized position representing regional bridal market dominance. These three Japanese and Japan-based entities anchor competitive dynamics through distinct archetype representation rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Richemont Japan Ltd |
| Bulgari Japan Ltd |
| K Mikimoto & Co Ltd |
| As-me Estelle Co Ltd |
| Kuwayama Corp |
| Fdc Products Inc |
| Tiffany & Co Japan Inc |
| NIWAKA |
| Chanel KK |
| Others |
Value Chain & Pricing Dynamics
Rough gemstone sourcing dependence on Sri Lankan and Thai cutting centers concentrates margin capture upstream, leaving Japanese ateliers exposed to spot price volatility and customs processing delays that compress downstream profitability.
Pricing Analysis
Cost-plus contracts with platinum suppliers index to London Bullion Market Association spot pricing, creating margin compression for independent ateliers lacking hedging instruments. Three-tier pricing structure across heritage houses, mid-tier retailers, and online marketplaces differentiates by certification grade and after-sales service bundling. Price erosion runs through silver and lower-purity segments as social commerce platforms displace physical retail overhead. Online shoppers exhibit highest price sensitivity, while luxury clients purchasing platinum bridal sets prioritize provenance documentation over absolute cost.
Supply Chain Analysis
Tariff exposure between Japan and major rough gemstone suppliers dominates supply chain risk planning for domestic importers. Geographic concentration in Sri Lanka, Thailand, and India for cutting and polishing operations creates single-source vulnerability during regional trade disputes. Raw material dependencies center on platinum sponge from South African refiners, Australian gold bullion, and biogenic pearl cultivation from Kyushu operations. Distribution runs through department store networks for high-consideration purchases, while direct-to-consumer channels bypass traditional wholesale markups for customizable gemstone configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's jewellery market sits at a platform-economics inflection where virtual try-on tools and blockchain traceability protocols are rewiring buyer-seller relationships and value capture mechanisms.
For Market Incumbents: Entrench proprietary cultivation technology through CAD integration investments that compress custom prototyping timelines below 48 hours. Secure Japan Assay Office partnerships to streamline dual certification bottlenecks that threaten import-dependent product launches. Defensive moves must counter direct-to-consumer entrants capturing younger demographics through social commerce channels.
For New Entrants and Emerging Players: Establish a beachhead in Kyoto and Osaka bridal markets where NIWAKA's regional dominance demonstrates whitespace for specialized ceremonial collections. Target gift buyer segments through customizable gemstone configurations that bypass Ginza flagship rental costs. Go-to-market execution should leverage augmented reality interfaces and last-mile logistics partnerships rather than physical retail buildout.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CAD-integrated custom ateliers possessing trained technician pools but lacking scaling capital. Long-term viability hinges on backward integration into blockchain-traceable supply chains that satisfy METI disclosure mandates. Watch for inflection signals in cloud rendering infrastructure investment rates among heritage houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | METI disclosure mandates force refiners to deploy chain-of-custody documentation systems for market access. |
| CAD Technician Training Programs | Digital rendering expertise scarcity constrains atelier scaling and custom production volume expansion. |
| Virtual Try-On Platform Launch | Augmented reality interfaces reduce purchase friction for Tokyo-based digital-native earring and bracelet buyers. |
| Pearl Cultivation Protocol Integration | Parametric design software convergence with biogenic sourcing hybridizes product development timelines. |
| Direct-to-Consumer Channel Expansion | Social commerce platforms capture customizable gemstone demand while bypassing Ginza real estate overhead. |
Study Parameters
The analysis maps platinum bridal sets, gemstone earrings, pearl necklaces, and silver bracelets, each validated through conversations with jewellery store operators, CAD technicians, department store buyers, and METI compliance officers. Primary fieldwork combined with secondary validation from Japan Assay Office certification records, METI ethical sourcing guideline documents, and PMDA nickel release testing protocols. Bottom-up demand modeling across customer archetypes triangulated against top-down precious metal consumption data from domestic refiners.
Assumption sets held platinum spot price volatility and METI disclosure mandate enforcement timelines fixed across the projection horizon, while varying digital adoption rates and social commerce penetration assumptions. Segmentation dimensions modeled include product type, material purity grade, customer application context, and distribution channel concentration. CAGRs derived from historical precious metal consumption patterns and forward-looking channel shift velocity. Industry-specific inputs incorporated bridal ceremony seasonality and online marketplace transaction growth trajectories.
Sensitivities concentrate around platinum price volatility spikes, customs processing delays at rough gemstone entry points, and PMDA regulatory timeline extensions. Forecasts reflect documented assumptions regarding digital adoption curves and ethical sourcing compliance costs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Global Gems and Jewelry Market
Jewelry
Brazil Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Latin America Jewelry Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
China Jewellery Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Jewellery Market
Jewelry
Smart Jewelry Market
Jewelry
Global Costume Jewelry Market