
 China Luxury Jewelry Market | 2026-2036
China Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
China Luxury Jewelry Market Insights
China's dual carbon goals is hardening compliance requirements across precious metal supply chains, compelling refiners and retailers to document carbon footprints from mine to counter. Chow Tai Fook leverages its vertically integrated sourcing network to sustain traceability certifications across gold and diamond lines. Cartier differentiates through controlled boutique expansion in tier-one locations, while Lao Feng Xiang anchors its competitive position in heritage craftsmanship and domestic cultural resonance.
China luxury jewelry comprises high-value ornamental pieces crafted from precious metals and gemstones, typically achieving purity standards of 24-karat gold or VS-clarity diamonds, serving primarily as wealth storage, social signaling instruments, and ceremonial gift objects. Rings and necklaces occupy the largest revenue pools given their centrality to wedding rituals and milestone celebrations, while pearl and platinum categories are gaining traction among younger buyers seeking differentiation from conventional gold-heavy portfolios. Online and high-end boutiques represent the fastest-expanding sales channels as digital-native consumers expect seamless omnichannel experiences.
SAMR enforces mandatory precious metal labeling and anti-counterfeiting protocols that raise barriers for unverified entrants, while GB standards govern alloy compositions and gemstone grading consistency across domestic production. MIIT's oversight of e-commerce platforms intensifies documentation requirements for live-streaming jewelry sales, a channel that now commands substantial transaction volume. Stakeholders must monitor regulatory tightening on cross-border gemstone sourcing and anticipate how digital yuan integration will reshape payment infrastructure and consumer traceability expectations.
Market Dynamics
China's dual carbon goals are hardening compliance requirements across precious metal supply chains, compelling refiners and retailers to document carbon footprints from mine to counter while simultaneously reshaping consumer expectations around provenance transparency.
Growth Catalysts
- Self-purchase normalization:Women consumers in tier-one cities are acquiring high-value pieces outside traditional gift-giving contexts, expanding addressable demand beyond wedding and festival cycles.
- MIIT live-streaming protocols:E-commerce platform oversight has legitimized digital jewelry transactions, enabling real-time authentication demonstrations that reduce purchase hesitation for remote buyers.
- 24-karat gold purity preference:Cultural attachment to investment-grade metal content sustains premium pricing power and discourages substitution toward lower-alloy alternatives.
Market Restraints
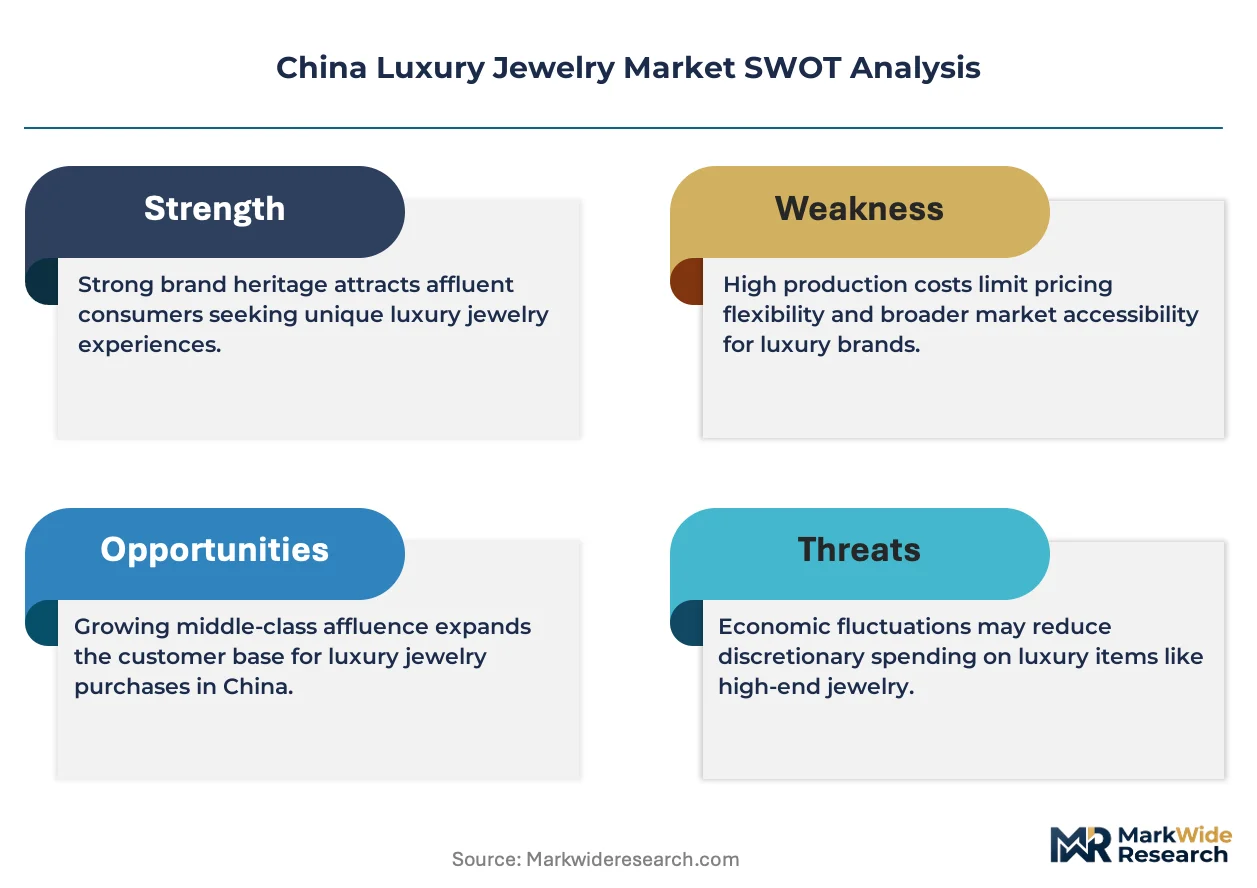
- Input cost volatility:Gold price fluctuations denominated in USD create margin compression for domestic retailers with RMB-denominated revenue streams.
- Supply concentration risk:Rough diamond sourcing dependence on limited cutting centers exposes brands to geopolitical disruption in key processing geographies.
- GB standards alloy restrictions:Mandatory composition thresholds limit material experimentation and elevate compliance costs for heritage craftsmanship techniques.
Strategic Opportunities
- Tier-two city penetration:Chengdu, Hangzhou, and Xi'an demonstrate rising per-capita luxury expenditure with underdeveloped flagship boutique presence.
- Platinum and pearl portfolio expansion:Younger buyers seeking differentiation from conventional gold-heavy portfolios are creating white space for alternative precious materials.
- Digital yuan integration:Central bank digital currency rollout enables programmable loyalty structures and enhanced transaction traceability for high-value purchases.
Industry Challenges
- Gemological certification capacity:VS-clarity diamond grading expertise scarcity creates bottlenecks for quality assurance at scale.
- Carbon documentation systems:Mine-to-counter traceability infrastructure requires capital deployment that mid-tier retailers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Luxury Jewelry Market |
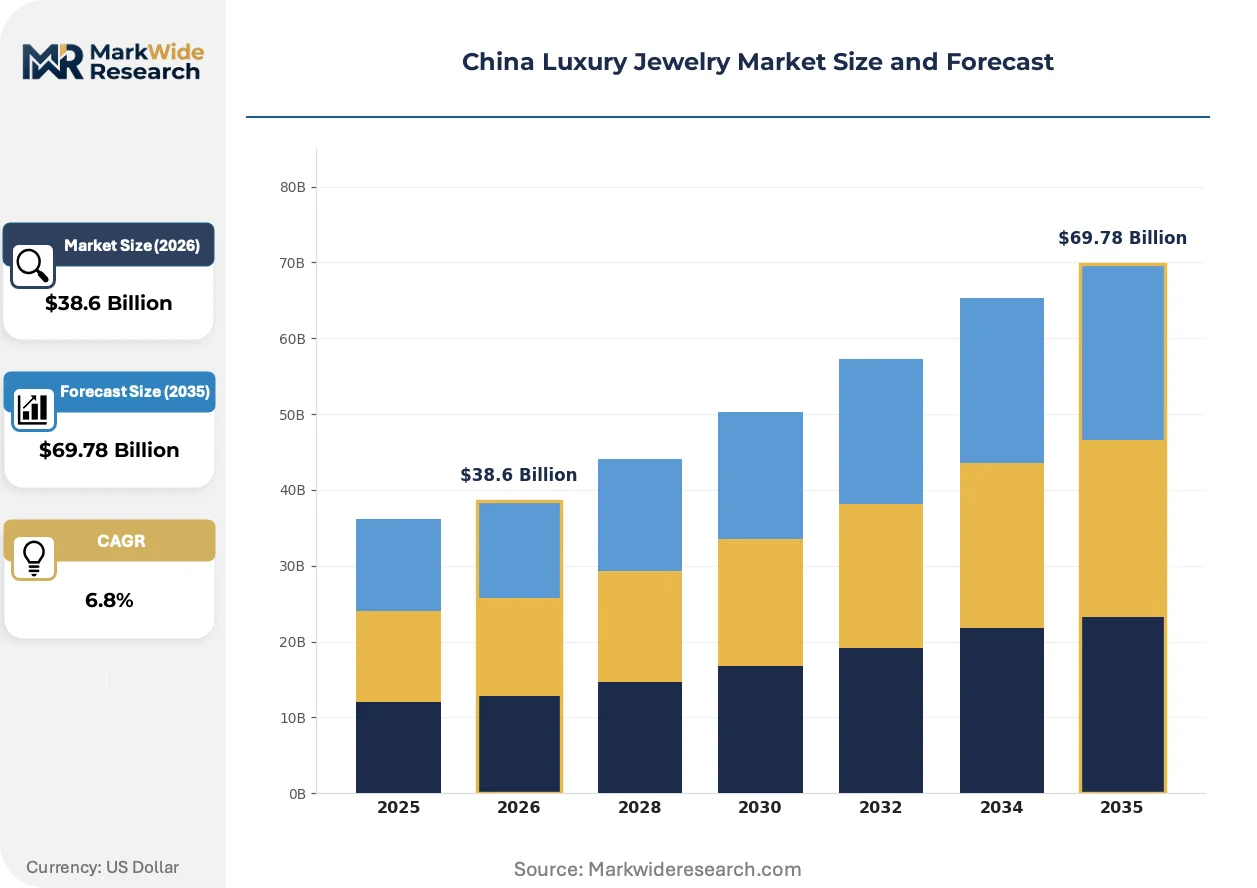
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Platinum, Diamond, Pearl End User: Women, Men, Couples, Gift Buyers Sales Channel: Online, Retail Stores, High-end Boutiques, Auctions |
| Companies Covered | Chow Tai Fook, Lao Feng Xiang, Chow Sang Sang, Cartier, Tiffany & Co., LVMH, Compagnie Financiere Richemont, Chow Tai Seng, Zhaoyi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Luxury Jewelry Market Trends and Innovations
Digital-native consumer expectations are compressing the traditional boundary between online discovery and physical purchase verification, forcing simultaneous investment in virtual try-on capabilities and boutique experiential design.
Blockchain-based provenance tracking is automating documentation of precious metal extraction and processing stages for compliance with dual carbon goals. Heritage houses and emerging designers alike are adopting distributed ledger systems to satisfy tier-one city buyer demands for supply chain transparency. This technology is automating audit processes that previously required manual third-party verification, reducing certification timeline friction.
SAMR anti-counterfeiting protocol expansion is tightening precious metal labeling enforcement across domestic production and import channels. The regulatory framework now mandates digital traceability tags for high-value pieces, elevating compliance infrastructure requirements. Retailers are responding by consolidating supplier relationships toward vertically integrated partners capable of end-to-end documentation.
Self-gifting behavior among professional women is displacing ceremonial purchase timing as the dominant transaction trigger. High-end boutiques in Shanghai and Beijing are redesigning floor space to accommodate solo browsing experiences rather than couple-centric consultation formats. This behavioral shift concentrates revenue in tier-one city flagships where experiential service differentiation remains achievable.
China Luxury Jewelry Market Segmentation
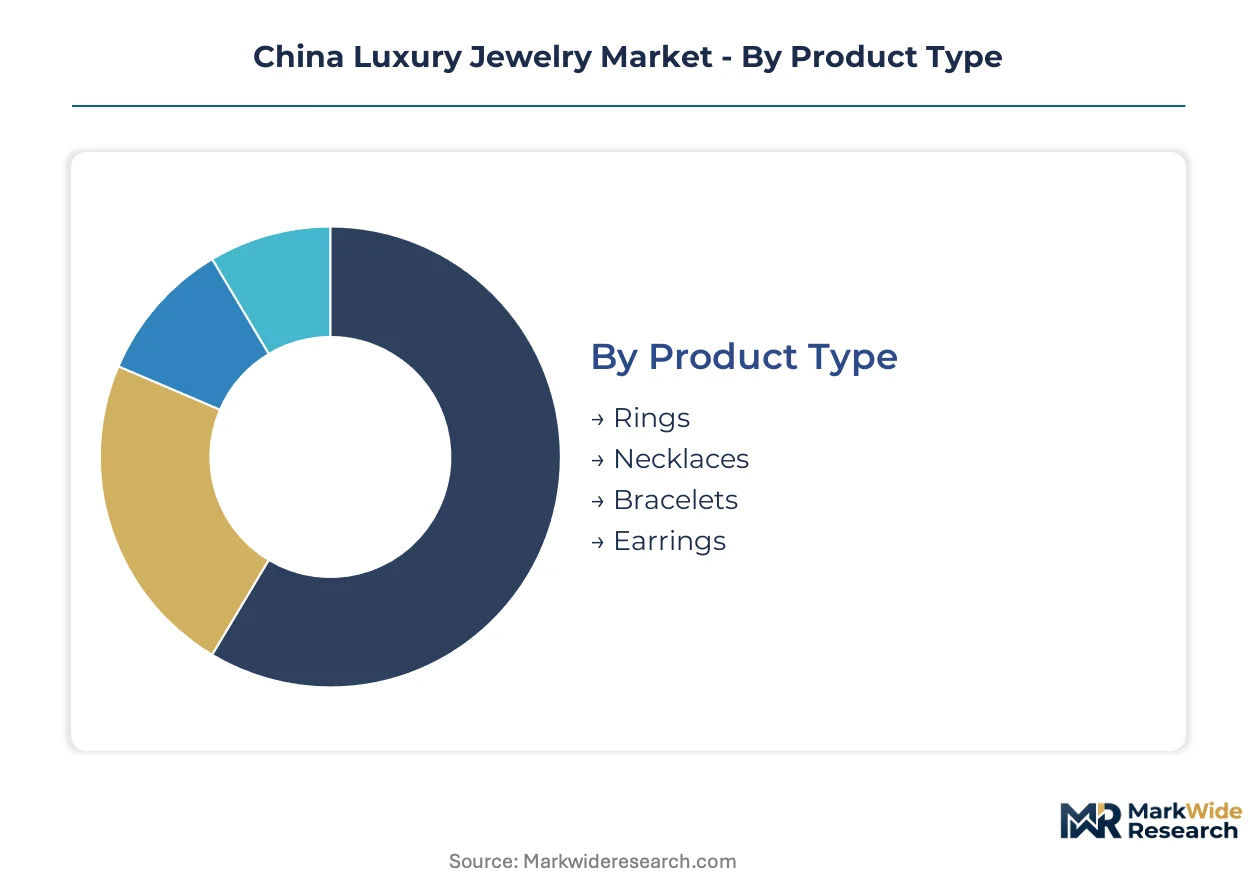
Segmentation in China's luxury jewelry market reveals how purity standards, ceremonial traditions, and channel evolution create distinct competitive arenas. Each dimension carries regulatory, cultural, and technological specificity that shapes investment priorities.
Product Type:
Technical sophistication and ritual centrality define competitive differentiation across forms.
- Rings:Wedding bands and engagement solitaires dominate transaction volume, with 24-karat gold bands and VS-clarity diamond settings commanding premium positioning in Shanghai and Beijing bridal markets. Chow Tai Fook and Lao Feng Xiang concentrate flagship inventory here due to margin density and repeat purchase potential.
- Necklaces:Statement pieces serve dual functions as wealth storage vehicles and social signaling instruments, with dragon and phoenix motifs sustaining cultural resonance among gift buyers during Lunar New Year cycles. Tier-one city consumers prioritize adjustable chain mechanisms and certified clasp durability.
- Bracelets:Bangle designs in solid gold construction appeal to self-purchasing professional women seeking daily wearable investment assets. Shenzhen manufacturers lead production scale for this segment.
- Earrings:Stud and drop configurations in platinum settings attract younger buyers seeking workplace-appropriate luxury with lower gold-content profiles.
Rings lead on scale; earrings lead on momentum among demographic expansion.
Material:
Cost tier stratification separates investment-grade metals from experiential luxury stones.
- Gold:24-karat purity preference sustains dominant revenue share, with SAMR-mandated labeling requirements forcing documentation of alloy composition and origin certification. Dual carbon goals are hardening carbon footprint disclosure expectations from mine to counter.
- Diamond:VS-clarity grading standards and GIA certification anchoring create quality assurance bottlenecks, with rough sourcing dependence on limited cutting centers exposing supply concentration risk.
- Platinum:White metal aesthetics attract differentiation-seeking younger buyers in Hangzhou and Chengdu, though GB standards alloy restrictions limit design experimentation.
- Pearl:Freshwater and South Sea varieties gain traction as alternatives to conventional gold-heavy portfolios, particularly among digital-native consumers exploring heritage craftsmanship revival.
Gold leads on scale; platinum leads on momentum with steepest expansion trajectory among alternative materials.
End User:
Procurement patterns distinguish ceremonial gift cycles from emerging self-directed acquisition.
- Women:Self-purchase normalization in tier-one cities expands addressable demand beyond traditional gift contexts, with solo browsing experiences redesigning boutique floor layouts in Beijing flagships.
- Gift Buyers:Festival and milestone-driven transactions concentrate revenue in Q1 and Q4, with digital yuan integration enabling programmable loyalty structures for high-value ceremonial purchases.
- Men:Cufflinks, signet rings, and understated bracelets represent narrower but premium-margin opportunities, particularly in Shenzhen's business professional corridors.
- Couples:Joint consultation formats persist in wedding band selection, though declining as a share of total transactions relative to individual purchasing.
Women lead on scale; gift buyers lead on momentum as digital channels capture ceremonial convenience.
Sales Channel:
Volume concentration and margin capture split between physical verification and digital discovery.
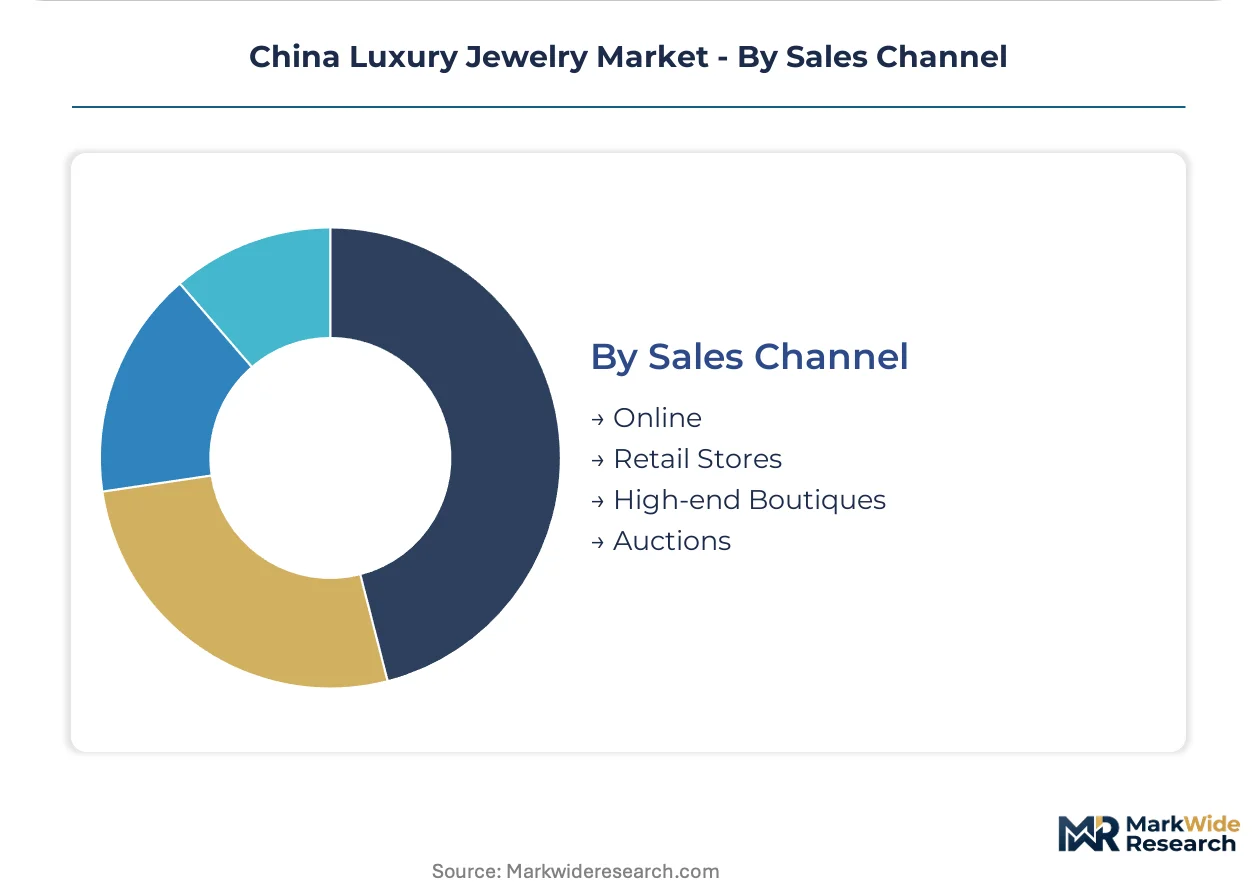
- Online:MIIT live-streaming protocols legitimize remote transactions through real-time authentication demonstrations, with e-commerce platforms now commanding substantial transaction volume among younger demographics.
- High-end Boutiques:Experiential service differentiation and immediate physical verification sustain premium positioning in Shanghai, Beijing, and Shenzhen flagship locations.
- Retail Stores:Mid-tier mall presence captures impulse and convenience purchasing, though facing margin compression from online price transparency.
- Auctions:Estate pieces and rare gemstones attract collector concentration, with blockchain-based provenance tracking automating documentation for dual carbon compliance.
High-end boutiques lead on scale; online leads on momentum as omnichannel expectations compress discovery-to-purchase boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled gemological talent and heritage metalworking expertise cluster in coastal provinces, anchoring production quality and retail innovation across China's luxury jewelry landscape.
Yangtze River Delta
Shanghai's bridal market concentrates 24-karat gold band and VS-clarity diamond solitaire demand, with self-purchasing professional women expanding transaction frequency beyond traditional festival cycles. SAMR labeling enforcement tightens documentation requirements for alloy composition and origin certification across Pudong and Huangpu flagship corridors. Suzhou and Hangzhou satellite cities host precision casting facilities supplying adjustable chain mechanisms to tier-one boutiques.
Pearl River Delta
Shenzhen's manufacturing ecosystem dominates solid gold bangle production for daily wearable investment assets, leveraging vertical integration from refining to retail. MIIT live-streaming protocols legitimize remote transactions through real-time authentication demonstrations on e-commerce platforms. Guangzhou's wholesale markets feed mid-tier mall presence while Dongguan facilities experiment with platinum settings for workplace-appropriate luxury.
Beijing-Tianjin-Hebei
State-affiliated procurement and diplomatic gift cycles sustain ceremonial revenue concentration in Q1 and Q4, with digital yuan integration enabling programmable loyalty structures for high-value purchases. Dual carbon goals harden carbon footprint disclosure expectations from mine to counter across Chaoyang and Dongcheng flagship locations. Tianjin's port infrastructure handles rough diamond import logistics exposed to geopolitical disruption in key cutting centers.
Sichuan-Chongqing
Chengdu demonstrates rising per-capita luxury expenditure with underdeveloped flagship boutique presence relative to coastal peers, creating whitespace for controlled expansion. GB standards alloy restrictions limit material experimentation for heritage craftsmanship techniques in local ateliers. Chongqing's inland port facilities reduce logistics friction for gemstone distribution to western provinces.
Shandong Peninsula
Qingdao and Yantai host freshwater pearl cultivation operations gaining traction among digital-native consumers exploring heritage craftsmanship revival. Regional refiners document carbon footprints to satisfy tier-one city buyer demands for supply chain transparency. Weihai facilities specialize in South Sea variety processing for alternative precious material portfolios.
China Luxury Jewelry Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's luxury jewelry market, with vertically integrated refiners and retailers maintaining distinct capability profiles from boutique-dependent heritage houses. The vendor base stratifies across three tiers: domestic heritage conglomerates with captive sourcing networks, international maisons relying on controlled distribution partnerships, and emerging designers leveraging direct-to-consumer digital channels. Strategic archetypes include purity-focused gold specialists, provenance-transparent diamond houses, and experiential service innovators. Dominant competitive moves encompass backward integration into mining and cutting operations, plus boutique experiential redesign to accommodate solo browsing formats.
Within the domestic heritage tier, Chow Tai Fook and Lao Feng Xiang exemplify divergent positioning strategies—one leveraging scale-driven vertical integration, the other anchoring in cultural resonance and craftsmanship lineage. Among international entrants, Cartier occupies a position as a controlled-expansion archetype, while Tiffany & Co. represents the American heritage house adapting to local purity preferences. These named entities serve as structural anchors for understanding how competitive positioning fragments across sourcing models, channel strategies, and generational targeting approaches.
| Leading Market Players |
|---|
| Chow Tai Fook |
| Lao Feng Xiang |
| Chow Sang Sang |
| Cartier |
| Tiffany & Co. |
| LVMH |
| Compagnie Financiere Richemont |
| Chow Tai Seng |
| Zhaoyi |
| Others |
Pricing and Supply Chain Analysis
Gold bullion costs denominated in USD flow through RMB-denominated retail pricing tiers, with exchange rate volatility compressing margins for domestic retailers unable to pass through input spikes to ceremonial gift buyers during fixed-price festival cycles.
Pricing Analysis
Unbundled certification and authentication services separate from core metal pricing, with SAMR-mandated traceability tags and carbon documentation adding compliance premiums at the high end. Three-tier pricing structure across 24-karat investment-grade, 18-karat fashion, and plated entry-level separates Chow Tai Fook's mass-market positioning from Cartier's experiential boutique premiums. Pricing pressure stems from live-streaming price transparency eroding regional margin variation. Self-purchasing professional women in Shanghai demonstrate lowest price sensitivity, while mid-tier mall shoppers in tier-two cities exhibit highest elasticity.
Supply Chain Analysis
Rough diamond supply rests on Antwerp, Dubai, and Mumbai cutting centers, with geopolitical disruption in any single node exposing inventory gaps for VS-clarity solitaire lines. Gold refining concentrates in Shenzhen and Hong Kong facilities, while platinum feedstock draws from South African and Russian mine output. Single-source vulnerability in gemological certification capacity creates bottlenecks for quality assurance at scale. Distribution runs through vertically integrated flagship networks in tier-one cities, supplemented by MIIT-regulated e-commerce platforms for remote authentication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's luxury jewelry market offers geographic-arbitrage value through dual carbon compliance costs that burden unintegrated competitors more severely in coastal tier-one cities than in inland manufacturing zones with legacy energy profiles.
For Market Incumbents: Anticipate margin compression from live-streaming price transparency by consolidating supplier relationships toward vertically integrated partners capable of end-to-end carbon documentation. Invest in blockchain-based provenance infrastructure ahead of SAMR's anticipated expansion of digital traceability mandates for high-value pieces. Channel control through flagship experiential redesign remains the priority lever for defending premium positioning against digital-native entrants. For New Entrants and Emerging Players: Capture whitespace in Chengdu and Xi'an where per-capita luxury expenditure rises faster than flagship boutique penetration. Target platinum and pearl portfolio gaps among differentiation-seeking younger buyers in Hangzhou seeking workplace-appropriate alternatives to gold-heavy conventions. A direct-to-consumer digital channel leveraging MIIT-compliant live-streaming authentication bypasses capital-intensive physical retail buildout. For Investors and Strategic Acquirers: Roll-up economics work for regional heritage ateliers with captive craftsmanship expertise because GB standards alloy restrictions prevent rapid capability replication by asset-light competitors. Long-term viability hinges on carbon documentation infrastructure deployable across the analysis window. Watch for SAMR enforcement intensity on cross-border gemstone sourcing as the inflection signal for regulatory compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Implementation | Automates carbon footprint documentation for dual carbon compliance across gold and diamond lines. |
| Tier-Two Flagship Expansion | Captures rising per-capita expenditure in Chengdu and Xi'an before controlled international entrant presence. |
| Platinum Portfolio Diversification | Addresses younger buyer demand for workplace-appropriate luxury outside conventional gold-heavy conventions. |
| Digital Yuan Loyalty Integration | Enables programmable incentive structures for high-value ceremonial purchases through central bank infrastructure. |
| Live-Streaming Authentication Scale-Up | Legitimizes remote transactions under MIIT protocols while reducing boutique capital intensity for customer acquisition. |
Research Methodology
Direct dialogue with jewelry brand procurement directors, SAMR regulatory affairs specialists, tier-one boutique operations managers, and Shenzhen refining facility engineers grounded qualitative assessment, cross-referenced against customs records for precious metal imports, MIIT e-commerce platform disclosure filings, GB standards documentation, and Chow Tai Fook and Lao Feng Xiang annual reports. Bottom-up transaction volume estimates from channel partners combined with top-down macroeconomic consumption models to triangulate market sizing.
Bottom-up modeling tracked product type, material purity tier, end-user procurement pattern, and sales channel format across the projection horizon. CAGRs derived from regression analysis of historical consumption elasticity against disposable income growth and regulatory compliance cost trajectories. Forecast inputs incorporated digital yuan adoption curves for high-value transaction infrastructure and SAMR enforcement intensity projections for traceability mandate expansion.
Gold price volatility denominated in USD, RMB exchange rate fluctuation, and geopolitical disruption in diamond cutting centers are the dominant revision risks to consumption forecasts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
China Jewellery Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Imitation Jewelry Market
Jewelry
Smart Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Qatar Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Body Jewelry Market