
 Customized Jewelry Market | 2026-2036
Customized Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Customized Jewelry Market Analysis
The distinction between bridal commissioning and self-purchase gifting is collapsing as younger consumers treat personalized jewelry as identity expression rather than occasion-bound expenditure. CustomMade.com leverages artisan network density to sustain made-to-order margins without inventory risk. Dongguan HonHo Jewelry anchors volume production through CNC milling and lost-wax casting integration. Kendra Scott competes via color-customization programs that let buyers configure stone palettes across bracelet and earring lines.
Customized jewelry denotes individually commissioned or configured adornment produced through CAD modeling, additive manufacturing, hand fabrication, or hybrid workflows to match buyer-specified dimensions, inscriptions, material selections, or design motifs. Gold and platinum configurations command premium positioning due to metal price transparency and heirloom durability expectations. Rings and necklaces occupy the largest share of consumer expenditure, while bracelets represent the fastest-growing product type as stackable personalization trends accelerate among repeat purchasers. Gift buyers and couples concentrate margin pools around seasonal peaks, though individual self-purchase frequency is rising through subscription and loyalty programs.
FDA oversight of nickel release and cadmium content in metal alloys shapes material sourcing decisions for US-bound production, while REACH compliance in Europe restricts certain plating chemistries and mandates substance disclosure. China's SAMR enforces GB standards for precious metal purity labeling that affect export-oriented manufacturers. Stakeholders must monitor how diverging chemical safety thresholds across these jurisdictions fragment supply chain standardization and force regional SKU differentiation.
Market Dynamics
Additive manufacturing is compressing production timelines from weeks to days while fragmenting value capture between artisan networks and automated fabricators. This technological inflection is restructuring how customization premiums are priced and defended across digital and physical channels.
Growth Catalysts
- Direct-to-consumer digital channels:Millennial and Gen-Z gift buyers are bypassing traditional retail intermediaries, collapsing margin stacks and accelerating order-to-delivery cycles through proprietary configuration interfaces.
- REACH compliance in Europe:Restrictions on certain plating chemistries and mandated substance disclosure are elevating certified producers above uncertified competitors, creating preference premiums for compliant supply chains.
- Three-dimensional printing:Desktop metal and resin systems are enabling micro-factories to produce complex geometries without tooling investment, democratizing access to previously capital-intensive customization capabilities.
Market Restraints
- Gold and platinum price volatility:Precious metal input costs transmit directly to consumer pricing, compressing margins during commodity spikes and forcing hedging overhead onto smaller fabricators.
- Dongguan cluster concentration:Volume production gravity in China's Pearl River Delta creates single-point-of-failure exposure for global supply chains during logistics disruptions or trade policy shifts.
- Lost-wax casting limitations:Traditional methods cannot achieve the geometric complexity of additive processes, constraining design freedom for heritage manufacturers without capital retooling.
Strategic Opportunities
- India's cultural gifting traditions:Underpenetrated digital customization channels in tier-two and tier-three cities present expansion white space as smartphone penetration deepens.
- Subscription and loyalty programs:Repeat purchase mechanics for stackable bracelet configurations are displacing one-time occasion buying, capturing lifetime value through programmed replenishment cycles.
- GB standards alignment:China's SAMR enforcement of precious metal purity labeling creates certification arbitrage for export-oriented manufacturers who preemptively adopt stricter domestic protocols.
Industry Challenges
- CAD-to-finish talent scarcity:Hybrid workflows demand operators fluent in both digital modeling and hand-finishing techniques, creating recruitment bottlenecks in established manufacturing clusters.
- FDA nickel release compliance:Metal alloy testing and documentation timelines extend product development cycles, delaying market entry for new material formulations bound for US consumers.
- Multi-jurisdiction SKU fragmentation:Diverging chemical safety thresholds across US, European, and Chinese regulatory regimes force regional product differentiation that complicates inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customized Jewelry Market |
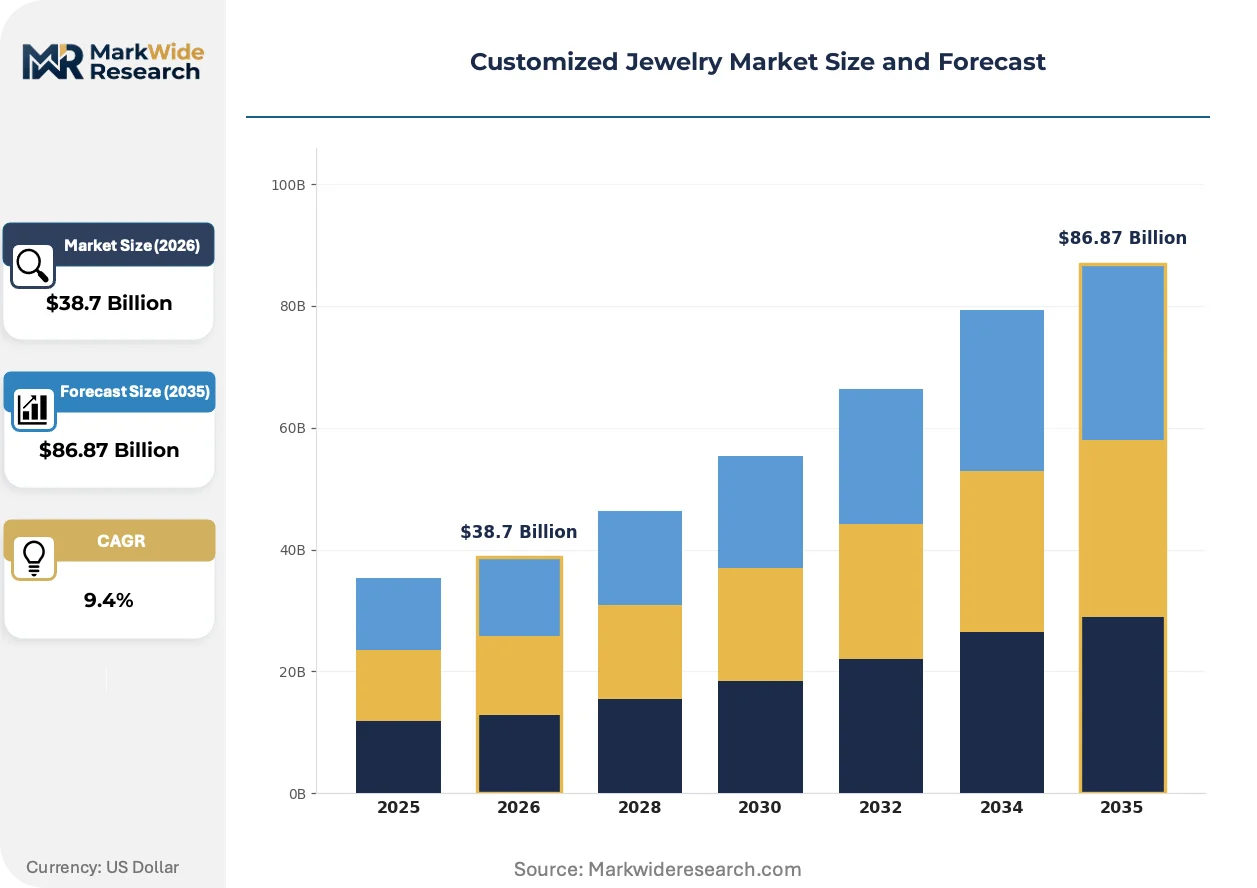
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Silver, Platinum, Gemstones Design Complexity: Simplistic, Intricate, Vintage, Modern Customer Type: Individuals, Couples, Gift Buyers, Retailers |
| Companies Covered | CadCamNYC, Casting House, CustomMade.com, Dongguan HonHo Jewelry, Bamina Jewelry, Oak & Luna, Hannoush Jewelers, Gildform Inc, Kendra Scott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customized Jewelry Market Emerging Trajectories
Production technology and consumer interface design are diverging along capability lines, separating premium artisan positioning from mass-customization efficiency plays. This divergence is rewriting competitive boundaries between heritage craftsmanship and algorithmic personalization.
Hybrid additive-subtractive workflows are bifurcating the fabrication base between desktop micro-factories serving local markets and industrial-scale systems producing standardized custom components. Independent designers are adopting compact resin and direct-metal printers for same-day prototyping, while centralized facilities deploy multi-axis CNC finishing for volume orders. This capability split is enabling tiered service models where speed and scale trade off against material prestige and hand-finish quality.
REACH substance disclosure mandates are forcing plating chemistry substitutions across European-bound production lines, accelerating transition to nickel-free and cadmium-free alloy formulations. Manufacturers are consolidating testing protocols under ECHA-registered certification bodies to preempt market access barriers. Bridal and children's jewelry segments face the steepest compliance ramps given skin-contact duration and sensitivity thresholds.
Self-purchase behavior is displacing occasion-bound gifting as the primary demand driver, particularly among repeat buyers configuring stackable bracelet and earring combinations through mobile-native interfaces. Digital-first brands are unbundling the traditional retail consultation into asynchronous configuration tools with virtual try-on overlays. This shift concentrates margin capture in the United States and China where subscription mechanics and loyalty point systems sustain engagement between purchase events.
Customized Jewelry Market Segmentation
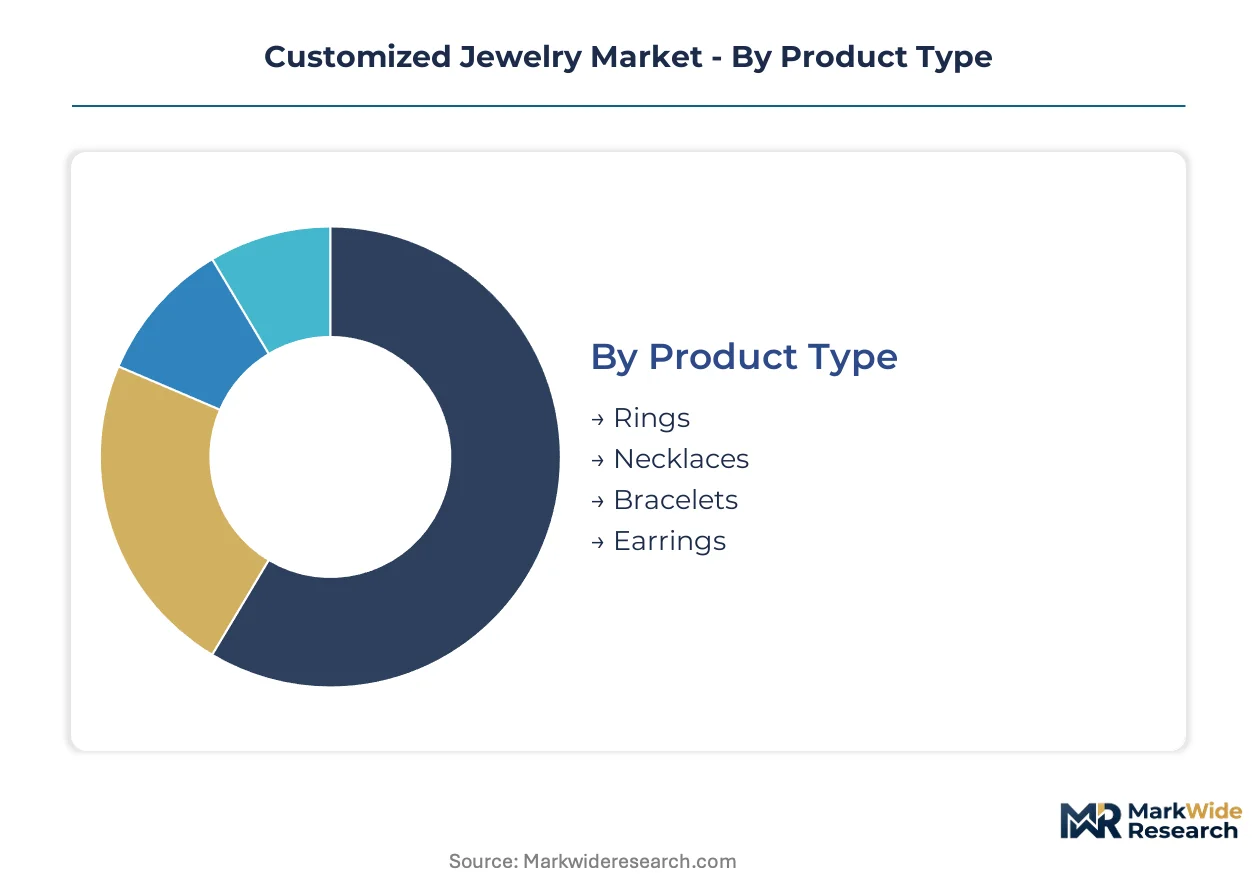
Segmentation in customized jewelry reveals how production technology and purchasing context reshape margin capture. Material selection and design complexity determine fabrication workflow choices, while customer type dictates channel strategy and pricing architecture.
Product Type:
Substitution pressure runs strongest against occasion-bound categories as self-purchase behaviors reconfigure demand patterns across wearable formats.
- Rings:Bridal and commitment bands dominate metal weight per unit, with CAD-to-cast workflows compressing sizing and engraving turnaround. United States couples concentrate expenditure around seasonal peaks, though stackable fashion rings are displacing single-occasion purchasing through subscription mechanics.
- Necklaces:Pendant and chain configurations command the highest average order values due to material surface area requirements. Chinese gift buyers drive volume through direct-to-consumer platforms during cultural festivals, while nameplate and coordinate engraving sustain repeat purchase frequency.
- Bracelets:Stackable chain and charm configurations are expanding most quickly among Millennial repeat purchasers configuring multi-unit combinations through mobile-native interfaces.
- Earrings:Stud and drop variants leverage additive manufacturing for complex geometric settings without traditional casting constraints.
Rings anchor the volume base while bracelets gain share at the steepest rate.
Material:
Cost tier stratification separates heirloom-positioned metals from fashion-accessibility alternatives, with purity certification becoming a competitive differentiator.
- Gold:14K and 18K alloys command premium positioning through price transparency and durability expectations, with SAMR GB standards enforcement in China creating certification arbitrage for export-oriented manufacturers. Indian cultural gifting traditions concentrate demand around 22K configurations for wedding commissions.
- Silver:Sterling and argentium formulations democratize entry-level customization through lower material risk per design iteration. European REACH compliance mandates are elevating nickel-free and cadmium-free certified producers above uncertified competitors.
- Platinum:Dense weight and hypoallergenic properties sustain bridal market positioning despite volatile input pricing.
- Gemstones:Lab-grown and ethically sourced alternatives are displacing mined stones in younger demographic segments.
Gold secures the revenue concentration while silver extends market penetration deepest.
Design Complexity:
Application context determines whether buyers prioritize speed and accessibility or material prestige and hand-finish quality.
- Simplistic:Clean-line geometries leverage three-dimensional printing for same-day prototyping without tooling investment, enabling micro-factories to serve local markets with compressed lead times.
- Intricate:Filigree and multi-component assemblies require hybrid additive-subtractive workflows, fragmenting value capture between artisan networks and automated fabricators.
- Vintage:Art Deco and Victorian revival motifs command heritage craftsmanship premiums through hand-engraving and milgrain finishing techniques.
- Modern:Algorithmic and parametric designs exploit generative CAD tools for mass-customization efficiency at scale.
Simplistic designs capture transaction volume while intricate configurations defend margin premiums.
Customer Type:
Volume concentration among gift buyers is fragmenting as self-purchase mechanics restructure lifetime value capture.
- Individuals:Self-purchase frequency is rising through loyalty point systems and programmed replenishment cycles, particularly for stackable bracelet configurations in United States and China digital channels.
- Couples:Bridal commissioning remains the highest-value transaction category, with CAD visualization tools collapsing the consultation-to-production timeline from weeks to days.
- Gift Buyers:Seasonal peaks around Valentine's Day and Mother's Day concentrate margin pools, though asynchronous configuration tools are displacing traditional retail intermediaries.
- Retailers:Boutique and department store private-label programs demand regional SKU differentiation to satisfy diverging chemical safety thresholds across US, European, and Chinese regulatory regimes.
Gift buyers anchor seasonal revenue while individuals drive the steepest expansion trajectory through repeat purchase mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites trans-Pacific precious metal flows, while Dubai's Jebel Ali Free Zone channels rough gemstone transit to cutting centers. India's Mundra Port anchors export throughput for polished diamond and gold jewelry bound for Western markets.
United States
Millennial self-purchase frequency drives digital channel expansion through mobile-native configuration tools. FDA nickel release testing extends product development timelines for new alloy formulations. Los Angeles hosts dense micro-factory clusters leveraging desktop metal printers for same-day prototyping.
China
Tier-two city smartphone penetration unlocks underpenetrated customization demand beyond coastal metros. SAMR GB standards enforcement for precious metal purity labeling creates certification arbitrage for export-oriented manufacturers. Dongguan's Pearl River Delta concentration anchors global volume production through CNC-lost-wax integration.
India
Cultural gifting traditions concentrate 22K gold demand around wedding commissioning cycles. BIS hallmarking mandates for gold jewelry purity reshape domestic supply chain documentation requirements. Surat's diamond cutting cluster feeds polished stone inputs to jewelry fabricators in Mumbai and Delhi-NCR.
Germany
REACH substance disclosure mandates accelerate nickel-free and cadmium-free alloy transitions across European-bound production. ECHA-registered certification bodies consolidate testing protocols for plating chemistry compliance. Pforzheim's traditional jewelry manufacturing base retools for hybrid additive-subtractive workflows.
United Kingdom
Self-purchase behavior displaces occasion-bound gifting among repeat bracelet configurators through subscription mechanics. HMRC precious metal taxation frameworks influence cross-border e-commerce fulfillment routing. Birmingham's Jewellery Quarter retains artisan density for heritage craftsmanship positioning.
Customized Jewelry Market Vendor Landscape
Listed leaders compete with private specialists across capitalization and production technology dimensions. The vendor base separates between venture-backed digital natives and multi-generational family operations. Three archetypes dominate: artisan-network platforms, vertically integrated manufacturers, and color-customization specialists. Competitive moves concentrate on M&A for digital configuration capabilities and strategic partnerships for additive manufacturing equipment access.
Within the artisan-network tier, CustomMade.com exemplifies platform-based aggregation without inventory risk. Dongguan HonHo Jewelry occupies a position among volume-driven fabricators leveraging automated production systems. Kendra Scott anchors the color-customization vector through configurable stone palette programs. These three represent divergent strategic postures on speed, scale, and design freedom trade-offs.
| Leading Market Players |
|---|
| CadCamNYC |
| Casting House |
| CustomMade.com |
| Dongguan HonHo Jewelry |
| Bamina Jewelry |
| Oak & Luna |
| Hannoush Jewelers |
| Gildform Inc |
| Kendra Scott |
| Others |
Supply Flow & Price Mechanics
REACH substance disclosure mandates in Europe simultaneously gate supply qualification for plating chemistry compliance and enable price differentiation between certified and uncertified alloy formulations. This dual function compresses margin stacks for non-compliant producers while elevating certified competitors into premium positioning across European-bound channels.
Pricing Analysis
Volume-discount tiering structures separate bridal commissioning from self-purchase segments, with couples absorbing higher per-unit premiums for heirloom-grade gold configurations while repeat bracelet buyers access subscription-scaled pricing. Certification grade under FDA nickel release protocols and volume scale through loyalty point systems drive price differentiation between tiers. Cost compression in silver fashion-accessibility tiers is intensifying because additive manufacturing democratizes entry-level customization capabilities. Gift buyers demonstrate highest price sensitivity around seasonal peaks, whereas bridal segments exhibit lowest sensitivity due to occasion-bound durability expectations.
Supply Chain Analysis
China, India, and the United States anchor global customized jewelry production through divergent capability specializations. Dongguan's Pearl River Delta cluster feeds volume fabrication through CNC-lost-wax integration, Surat's diamond cutting infrastructure supplies polished gemstone inputs, and Los Angeles micro-factories leverage desktop metal printers for same-day prototyping. Raw material dependencies rest on gold and platinum spot markets, resin feedstocks for additive systems, and rough diamond transit through Dubai's Jebel Ali Free Zone. Single-source vulnerability concentrates in Dongguan cluster concentration during logistics disruptions or trade policy shifts. Distribution runs through direct-to-consumer digital channels collapsing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Customized jewelry sits in early-cycle expansion as self-purchase behaviors displace occasion-bound gifting through mobile-native configuration tools. Millennial and Gen-Z adoption through subscription mechanics sustains repeat purchase frequency beyond traditional seasonal peaks.
For Market Incumbents: Fortify artisan network density against automated fabricator encroachment by investing in hybrid CAD-to-finish training pipelines. Preempt REACH compliance escalation through ECHA-registered certification body consolidation. Lock in backward integration into precious metal hedging mechanisms to buffer spot price volatility exposure.
For New Entrants and Emerging Players: Anchor in India's tier-two and tier-three cities where smartphone penetration unlocks underpenetrated digital customization demand beyond coastal metros. Target stackable bracelet configurations as the fastest-growing product type with lowest capital barriers to entry. Deploy virtual try-on overlays as the primary go-to-market angle to collapse consultation friction.
For Investors and Strategic Acquirers: SAMR GB standards enforcement reshapes the acquisition landscape by elevating export-oriented manufacturers with preemptive certification arbitrage. Long-term viability centers on hybrid workflow capability spanning digital modeling and hand-finishing techniques. Monitor FDA nickel release testing timeline extensions as the signal indicating margin pressure on new alloy formulation entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Artisan Network Platform Integration | CustomMade.com's density model sustains made-to-order margins without inventory risk exposure. |
| Hybrid Additive-Subtractive Workflow Investment | Pforzheim manufacturers retool to capture both speed-tier and prestige-tier demand simultaneously. |
| Direct-to-Consumer Channel Expansion | Kendra Scott's color-customization programs collapse retail intermediary margin stacks through proprietary interfaces. |
| REACH Compliance Certification Program | ECHA-registered bodies consolidate testing protocols elevating compliant producers above uncertified competitors. |
| Subscription Mechanics for Repeat Purchase | United States and China digital brands capture lifetime value through programmed bracelet replenishment cycles. |
Methodological Framework
A spread of perspectives from jewelry fabrication executives, CAD-to-finish operators, direct-to-consumer platform managers, and precious metal procurement specialists converged on the working assumptions underlying demand projections. Secondary validation drew from SAMR GB standards filings, ECHA substance disclosure registries, FDA nickel release guidance documents, and customs trade data tracking gold jewelry import flows. Bottom-up order volume analysis triangulated against top-down consumer expenditure surveys across the analysis window.
Segmentation dimensions modeled include product type, material grade tier, design complexity level, and customer purchase context across the projection horizon. CAGRs were derived from growth rate convergence between historical trajectory analysis and adoption curve penetration assumptions. Forecast inputs incorporated additive manufacturing equipment deployment rates and mobile-native configuration tool penetration by demographic cohort.
Underlying assumptions cover sustained precious metal price volatility within historical bands and regulatory compliance timeline stability, with deviation risk concentrated in trade policy shifts affecting Dongguan cluster throughput. Recalibration cycles align with material shifts in self-purchase behavior adoption rates and additive manufacturing cost curve trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Mexico Luxury Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Brazil Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Jewelry Cleaners Market
Jewelry
Luxury Jewelry Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Jewellery Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
Artificial Jewellery Market
Jewelry
Diamond Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Latin America Jewelry Market